
 Global Interspinous Spacers Market | 2026-2036
Global Interspinous Spacers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interspinous Spacers Market Foresight
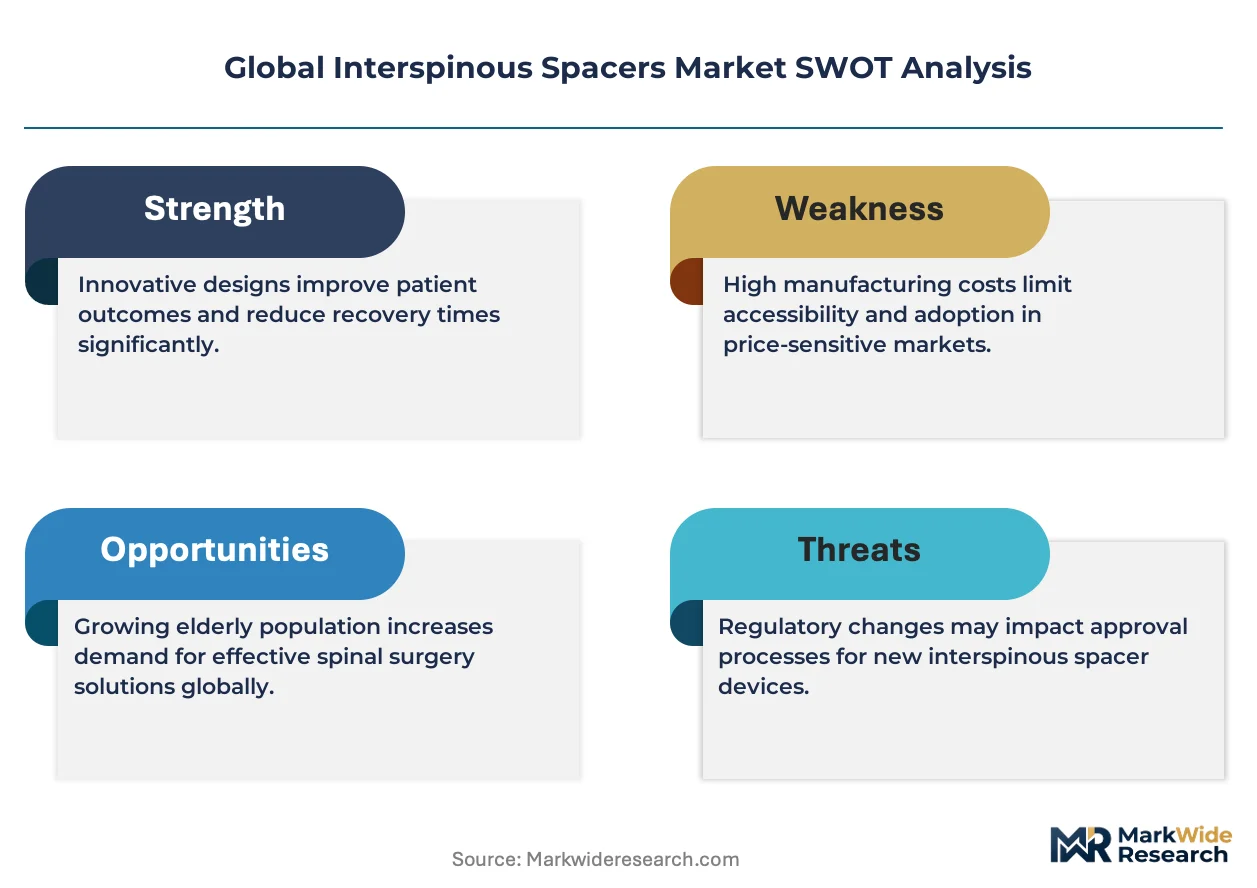
A shortage of fellowship-trained spine surgeons is bifurcating the market into high-volume academic centers and streamlined ambulatory settings. Medtronic leverages its integrated navigation and implant portfolio to sustain procedural pull-through across both channels. Zimmer Biomet anchors its position through scale manufacturing of titanium and PEEK constructs, while Globus Medical differentiates via robotics-enabled placement workflows that reduce operative variability.
Interspinous spacers are implantable devices positioned between adjacent spinous processes to maintain foraminal height and limit pathological extension in lumbar spinal segments, typically manufactured from titanium alloys, polyetheretherketone, or cobalt-chrome with surface modifications to promote osseointegration. Static spacers occupy the mature volume tier due to established reimbursement and simpler instrumentation, whereas expandable devices represent the fastest-growing product category as surgeons seek intraoperative adjustability without device exchange. Lumbar spinal stenosis applications generate the largest procedure base, though degenerative disc disease indications are gaining traction as diagnostic specificity improves through weight-bearing MRI protocols.
The FDA's Class II device pathway and the EU MDR's enhanced post-market surveillance requirements are reshaping clinical trial obligations and quality management systems for interspinous spacer manufacturers. Health Canada's Medical Devices Directorate and Japan's PMDA impose additional jurisdiction-specific biocompatibility and mechanical testing standards that fragment regulatory compliance costs across regions. Stakeholders must monitor evolving real-world evidence requirements and ambulatory surgery center accreditation standards to anticipate shifts in site-of-service economics and device selection criteria.
Market Dynamics
The EU Medical Device Regulation's enhanced post-market surveillance requirements are forcing manufacturers to rebuild quality management systems and expand clinical evidence portfolios for implantable spinal devices.
Growth Catalysts
- Ambulatory surgical center expansion:Same-day spinal procedure volumes are climbing as patients prioritize reduced hospital stays and faster recovery timelines.
- Weight-bearing MRI protocols:Improved diagnostic specificity for lumbar spinal stenosis is expanding addressable patient populations eligible for interspinous spacer intervention.
- Japan's PMDA pathway harmonization:Streamlined biocompatibility testing standards are reducing time-to-market for titanium and PEEK construct manufacturers.
Market Restraints
- Titanium alloy supply concentration:Raw material sourcing depends heavily on Chinese and Russian smelter output, exposing manufacturers to geopolitical volatility.
- EU MDR clinical evidence burdens:The regulation's expanded post-approval study requirements add twelve to eighteen months to device certification timelines.
- Conservative management substitution:Epidural steroid injections and physical therapy protocols retain strong payer preference for initial stenosis treatment.
Strategic Opportunities
- Expandable device category:Intraoperative adjustability without device exchange commands premium positioning in academic medical centers.
- India's CDSCO fast-track pathway:The regulator's priority review for orphan spinal indications offers first-mover advantages for specialized construct developers.
- Robotics-enabled placement workflows:Convergence of navigation systems with interspinous spacer instrumentation reduces operative variability and revision rates.
Industry Challenges
- Fellowship-trained spine surgeon scarcity:The talent gap limits procedural capacity at high-volume academic centers and forces reliance on general orthopedic surgeons.
- ISO 14155 clinical trial compliance:The standard's Good Clinical Practice requirements demand specialized CRO partnerships that fragment study management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interspinous Spacers Market |
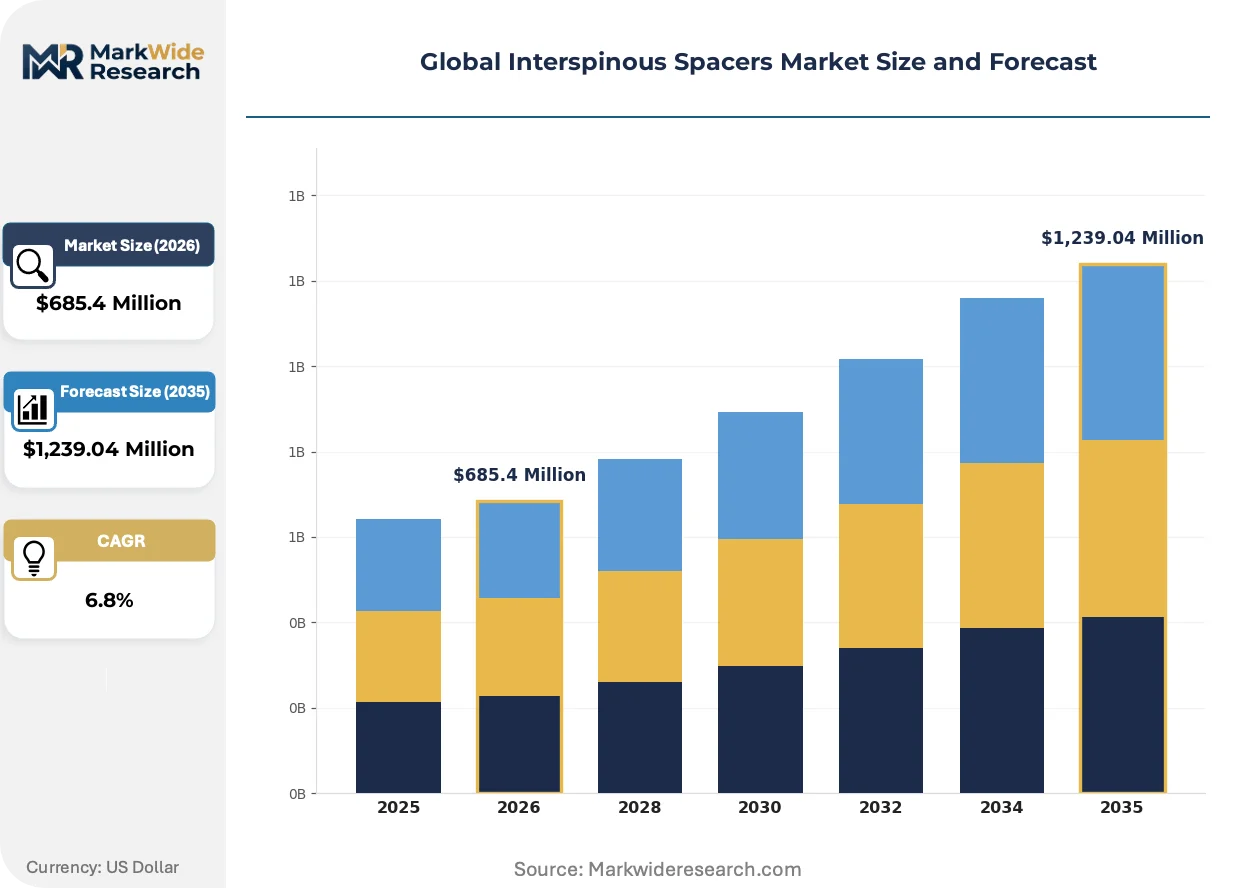
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Spacers, Dynamic Spacers, Minimally Invasive Devices, Expandable Devices Application: Lumbar Spinal Stenosis, Degenerative Disc Disease, Facet Joint Syndrome, Osteoarthritis End User: Orthopedic Clinics, Ambulatory Surgical Centers, Rehabilitation Centers, Specialty Hospitals Deployment Mode: Open Surgery, Percutaneous Surgery, Fluoroscopic Guided, Endoscopic Procedures |
| Companies Covered | Medtronic, NuVasive, Zimmer Biomet, Globus Medical, Stryker Corporation, Boston Scientific, Johnson & Johnson, Life Spine, Paradigm Spine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interspinous Spacers Market Shifts & Advancements
Device manufacturers are racing to integrate intraoperative imaging and navigation while regulators tighten evidence standards for osseointegration claims.
Expandable interspinous spacer designs are bifurcating the product landscape. These devices permit height adjustment after initial insertion, accommodating variable ligamentous tension. High-volume academic centers in Germany and the United States are adopting expandable platforms at three times the rate of static constructs. The technology is bifurcating surgeon training pathways and instrument tray requirements.
The EU MDR's Unique Device Identification mandate is reshaping supply chain traceability. Manufacturers must now maintain device-level lifecycle records from production through explant. Spinal implant distributors serving France and Italy are investing in serialized inventory management systems to comply with ANSM and AIFA inspection protocols.
Site-of-service economics are compressing hospital purchasing cycles. Ambulatory surgery centers in Texas and Florida are consolidating vendor relationships and demanding bundled pricing for spacer-plus-instrumentation sets. This consolidation is displacing traditional distributor markups and pushing manufacturers toward direct contracting models with multi-facility networks.
Global Interspinous Spacers Market Segmentation
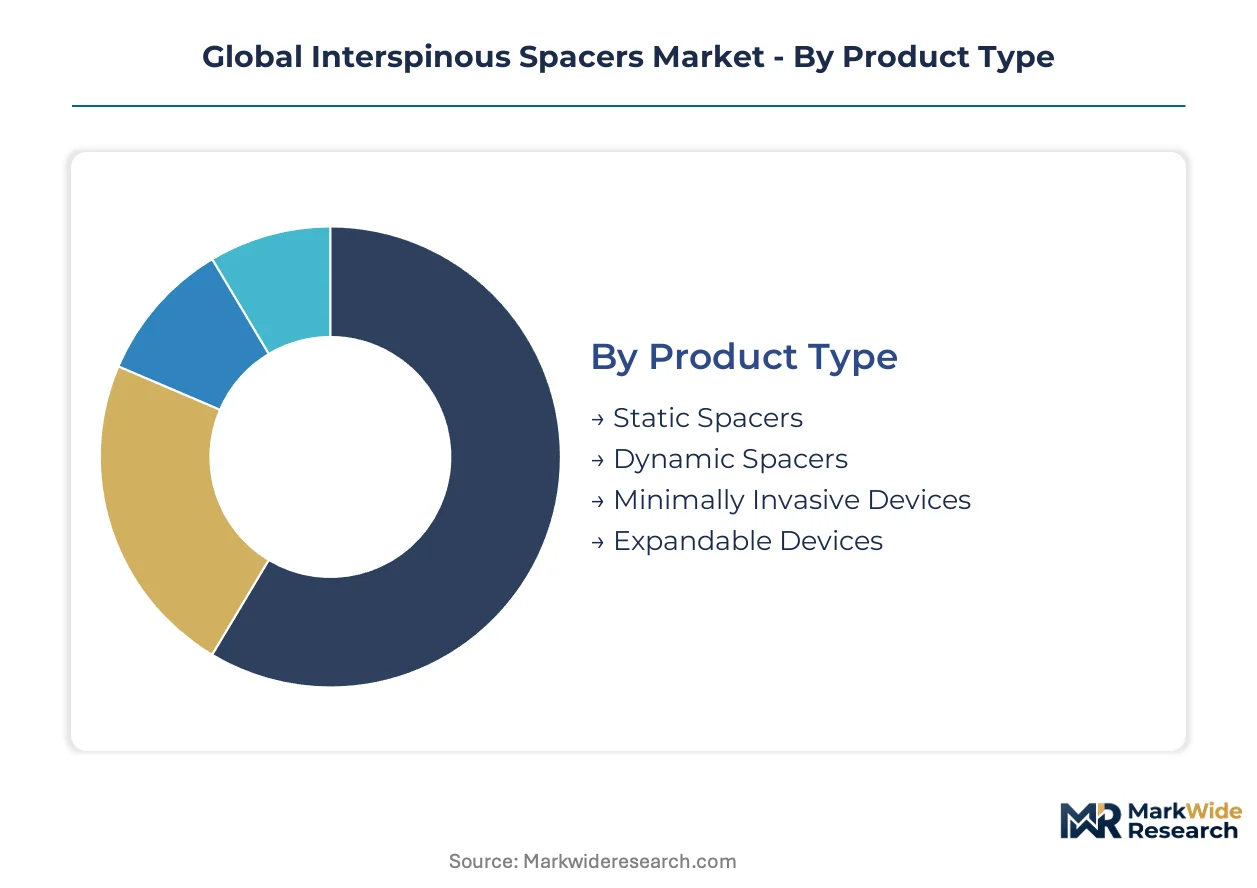
Interspinous spacer manufacturers face divergent margin structures across product architectures and procedural settings. Surgical approach selection and site-of-service economics create distinct competitive battlegrounds that reshape portfolio prioritization.
Product Type:
Margin pools concentrate in devices offering intraoperative flexibility without explantation, while static constructs defend volume through reimbursement familiarity.
- Static Spacers:Fixed-height titanium or PEEK constructs with established CPT coding dominate procedural volumes in United States ambulatory settings. Medicare reimbursement stability in Texas and Florida sustains manufacturer preference for these mature designs despite limited adjustability.
- Expandable Devices:Mechanisms permitting post-insertion height modification command premium pricing in German and United States academic centers. Surgeon demand for ligamentous tension optimization without device exchange is accelerating platform adoption.
- Dynamic Spacers:Motion-preserving designs with flexible cores target active patient demographics in Japanese and South Korean markets.
- Minimally Invasive Devices:Low-profile delivery systems reduce paraspinal muscle disruption in outpatient procedures across California and New York surgical networks.
Static spacers hold installed capacity. Expandable devices are rotating up the share rankings.
Application:
Procedure volumes bifurcate between stenosis interventions with definitive diagnostic pathways and degenerative conditions requiring improved imaging specificity.
- Lumbar Spinal Stenosis:Neurogenic claudication with confirmed central canal narrowing generates the largest addressable patient base across United States Medicare populations. Weight-bearing MRI protocol expansion in Germany and Japan is refining patient selection criteria.
- Degenerative Disc Disease:Discogenic pain without radiculopathy presents reimbursement complexity that limits penetration outside private payer networks in Switzerland and the Netherlands.
- Facet Joint Syndrome:Arthritic posterior element pathology drives hybrid construct demand in French and Italian academic hospitals.
- Osteoarthritis:Degenerative spinal changes in elderly populations concentrate procedural demand in Japanese geriatric centers.
Lumbar spinal stenosis commands current procedure tables. Degenerative disc disease is climbing the fastest as diagnostic precision improves.
End User:
Purchasing authority is fragmenting between consolidated hospital networks and independent ambulatory platforms with divergent vendor consolidation strategies.
- Ambulatory Surgical Centers:Same-day discharge protocols in Texas and Florida are compressing instrument tray requirements and demanding bundled spacer-plus-navigation pricing. Multi-facility networks are displacing traditional distributor markups through direct manufacturer contracting.
- Specialty Hospitals:High-volume spine centers in Germany and the United States maintain robotics-enabled placement workflows that reduce operative variability.
- Orthopedic Clinics:Office-based diagnostic and referral functions in India and Brazil influence device selection without direct purchasing authority.
- Rehabilitation Centers:Postoperative recovery protocols in Japanese and Australian markets affect long-term outcome tracking for implant performance.
Specialty hospitals hold installed capacity. Ambulatory surgical centers are rotating up the share rankings.
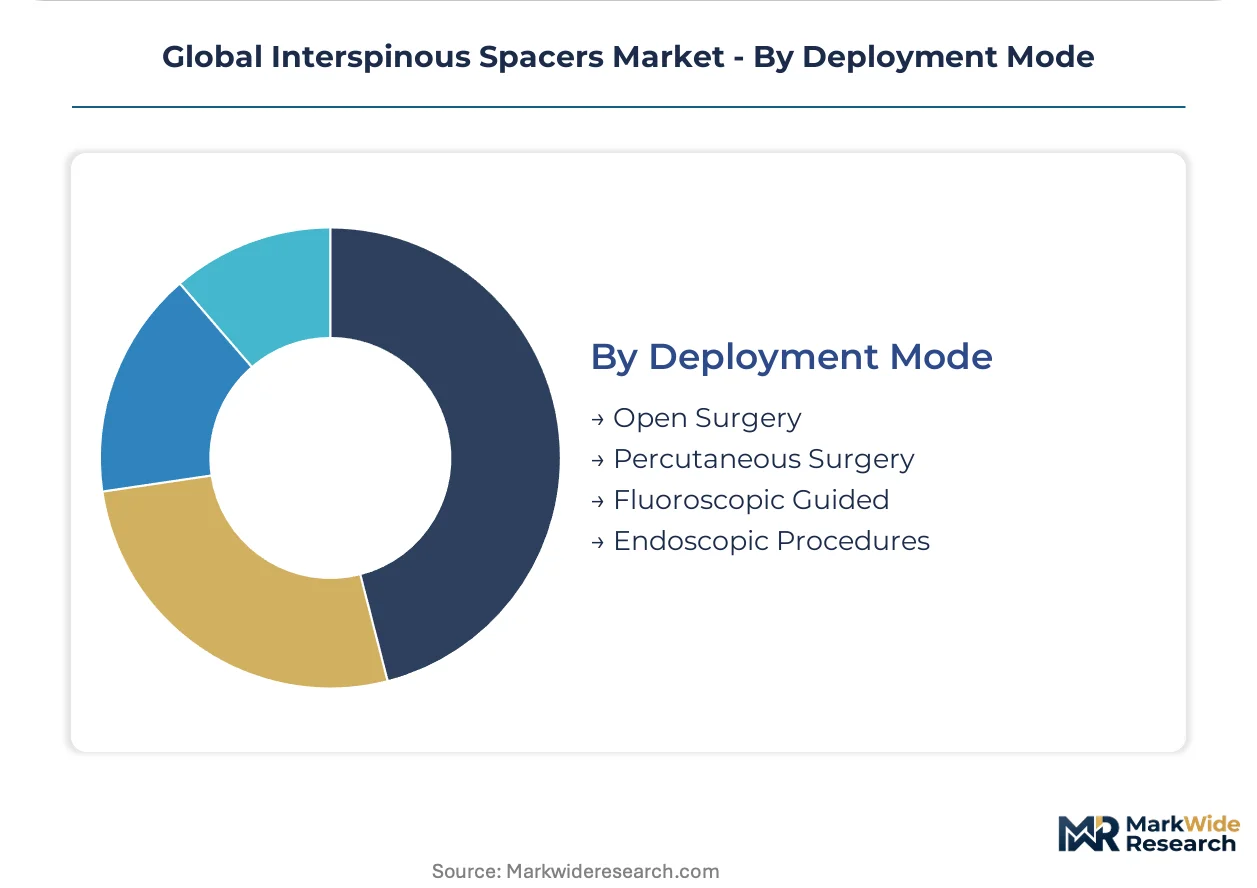
Deployment Mode:
Technique selection determines instrumentation complexity and surgeon training requirements that reshape competitive positioning.
- Percutaneous Surgery:Dilator-based placement through small incisions minimizes paraspinal disruption in outpatient settings across California and Arizona surgical networks. Reduced soft tissue trauma accelerates recovery timelines that align with ambulatory economics.
- Fluoroscopic Guided:Real-time imaging confirmation during insertion is standard of care in German and United States academic centers with hybrid operating room infrastructure.
- Open Surgery:Direct visualization approaches retain preference for revision procedures and complex deformity cases in French and Italian public hospitals.
- Endoscopic Procedures:Visualization through working channels remains limited to specialized training programs in South Korea and Japan.
Open surgery holds installed capacity. Percutaneous techniques are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Class II pathway for implantable spinal devices anchors procedural economics in the United States, while regulators in Germany and Japan impose parallel biocompatibility standards that fragment compliance costs across manufacturing footprints.
United States
Medicare reimbursement stability in Texas and Florida sustains ambulatory surgical center expansion for same-day spinal interventions. The FDA's 510(k) clearance framework maintains predictable regulatory timelines for titanium and PEEK construct manufacturers. High-volume spine networks in California and Arizona are consolidating vendor relationships and demanding bundled pricing for spacer-plus-instrumentation sets.
Germany
Weight-bearing MRI protocol adoption in Bavaria and Baden-Württemberg is refining patient selection criteria for lumbar spinal stenosis interventions. The EU MDR's enhanced post-market surveillance requirements are forcing manufacturers to rebuild quality management systems for implantable devices. Academic medical centers in Berlin and Hamburg are adopting expandable spacer platforms at three times the rate of static constructs.
Japan
PMDA pathway harmonization for biocompatibility testing is reducing time-to-market for titanium alloy construct manufacturers. METI's priority review mechanisms for orphan spinal indications are accelerating specialized device approvals. Geriatric spine centers in Tokyo and Osaka are driving procedural demand for motion-preserving dynamic spacer designs in active elderly populations.
Switzerland
Private payer networks in Zurich and Geneva are expanding coverage for degenerative disc disease indications outside traditional Medicare-equivalent pathways. Swissmedic's device certification standards align with EU MDR requirements while maintaining jurisdiction-specific mechanical testing protocols. Specialty orthopedic clinics in Basel are influencing device selection through office-based diagnostic and referral functions.
India
CDSCO's fast-track pathway for orphan spinal indications is offering first-mover advantages for specialized construct developers in Maharashtra and Gujarat. The country's national pharmaceutical regulator is streamlining import licensing for PEEK and titanium alloy raw materials. Urban surgical networks in Delhi-NCR and Bangalore are building robotics-enabled placement workflows that reduce operative variability.
Global Interspinous Spacers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the interspinous spacer market. The upper tier commands procedural pull-through through bundled navigation and implant portfolios, while mid-cap specialists defend position through scale manufacturing of titanium and PEEK constructs. Two strategic archetypes dominate: integrated platform providers spanning imaging-to-implant workflows, and component-focused fabricators supplying constructs to third-party distributors. Competitive moves concentrate on robotics-enabled placement technology licensing and direct contracting with multi-facility ambulatory networks.
Among integrated platform providers, Medtronic and Globus Medical exemplify the navigation-convergence archetype, anchoring positions through robotics-enabled workflows that reduce operative variability. Zimmer Biomet occupies a scale-manufacturing position within the construct-specialist tier, representing the titanium and PEEK volume production model that supplies standardized geometries to distributed surgical networks. These three companies collectively illustrate the bifurcation between technology-integrated and manufacturing-efficient competitive vectors.
| Leading Market Players |
|---|
| Medtronic |
| NuVasive |
| Zimmer Biomet |
| Globus Medical |
| Stryker Corporation |
| Boston Scientific |
| Johnson & Johnson |
| Life Spine |
| Paradigm Spine |
| Others |
Supply & Pricing Matrix
EU MDR certification gates both supplier qualification and price differentiation simultaneously, as manufacturers must absorb twelve to eighteen month compliance timelines before accessing premium pricing tiers in German and French academic centers. Titanium alloy sourcing from Chinese and Russian smelters introduces geopolitical volatility that compresses margins on static constructs while expandable devices command premium positioning through intraoperative adjustability.
Pricing Analysis
German academic centers pay three times the unit price of Texas ambulatory surgical centers for equivalent titanium constructs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with FDA 510(k) cleared devices capturing brand premiums. Cost compression in the standard tier intensifies as bundled spacer-plus-instrumentation pricing displaces traditional distributor markups. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with robotics-enabled workflows demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of titanium alloy feedstock dominates manufacturer inventory strategy given Chinese and Russian smelter concentration. Raw material sourcing draws from Chinese titanium sponge producers, German precision forging houses, and Japanese PEEK polymer manufacturers. Single-source vulnerability in Chinese titanium alloy supply creates exposure to export restriction scenarios. Distribution runs through specialized spinal implant distributors serving hospital networks and direct manufacturer contracts with multi-facility ambulatory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EU MDR compliance timelines and FDA 510(k) clearance pathways create twelve to eighteen month barriers that protect incumbent positions.
For Market Incumbents: Shield installed base through captive supply of titanium alloy feedstock and backward integration into precision forging capacity. Consolidate channel control by displacing distributor markups with direct contracting for multi-facility ambulatory networks. The emerging threat of robotics-enabled placement workflows from specialized navigation firms demands accelerated R&D investment in instrument tray standardization.
For New Entrants and Emerging Players: Differentiate on expandable device platforms with intraoperative height adjustment capabilities that command premium positioning in German academic centers. Target India's CDSCO fast-track pathway for orphan spinal indications as the most penetrable regulatory entry point. Pursue hospital system partnership go-to-market angles that bundle navigation training with device supply.
For Investors and Strategic Acquirers: EU MDR's enhanced post-market surveillance requirements reshape the acquisition landscape toward manufacturers with established quality management systems and clinical evidence portfolios. Long-term viability favors integrated platform providers spanning imaging-to-implant workflows over component-focused fabricators. The signal to watch is PMDA harmonization progress for biocompatibility testing standards.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Quality Management System Rebuild | Expanded post-market surveillance requirements force twelve to eighteen month compliance investments. |
| Robotics-Enabled Placement Workflow Development | Navigation convergence reduces operative variability in German and United States academic centers. |
| Direct Ambulatory Network Contracting | Multi-facility Texas and Florida networks displace traditional distributor markups. |
| Expandable Device Platform Launch | Intraoperative adjustability commands premium positioning without device exchange. |
| India CDSCO Fast-Track Pathway Entry | Priority review for orphan spinal indications offers first-mover advantages in Maharashtra. |
Research Methodology
A spread of perspectives from spine surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers converged on the working assumptions driving procedural volume forecasts. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up installation base modeling and top-down epidemiological triangulation anchored market sizing.
Segmentation dimensions modeled include product architecture, surgical approach, site-of-service economics, and regional regulatory cluster across the projection horizon. CAGRs derived from procedure volume trajectories, reimbursement stability indices, and technology adoption curves. Forecast inputs incorporated weight-bearing MRI protocol expansion rates and ambulatory surgical center accreditation standards.
Material uncertainties — titanium alloy supply disruption, EU MDR enforcement variability, and conservative management substitution — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and surgeon training pipeline capacity. Revision becomes warranted when titanium alloy export restrictions cross thresholds affecting manufacturer input costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Global Intragastric Balloon Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Infusion Management Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
Microscope Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Contraceptive Devices Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Microwave Ablation Devices Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Plethysmograph Market
Medical Devices
Air Oxygen Blender Market