
 Argentina Aesthetic Devices Market | 2026-2036
Argentina Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Aesthetic Devices Market Outlook
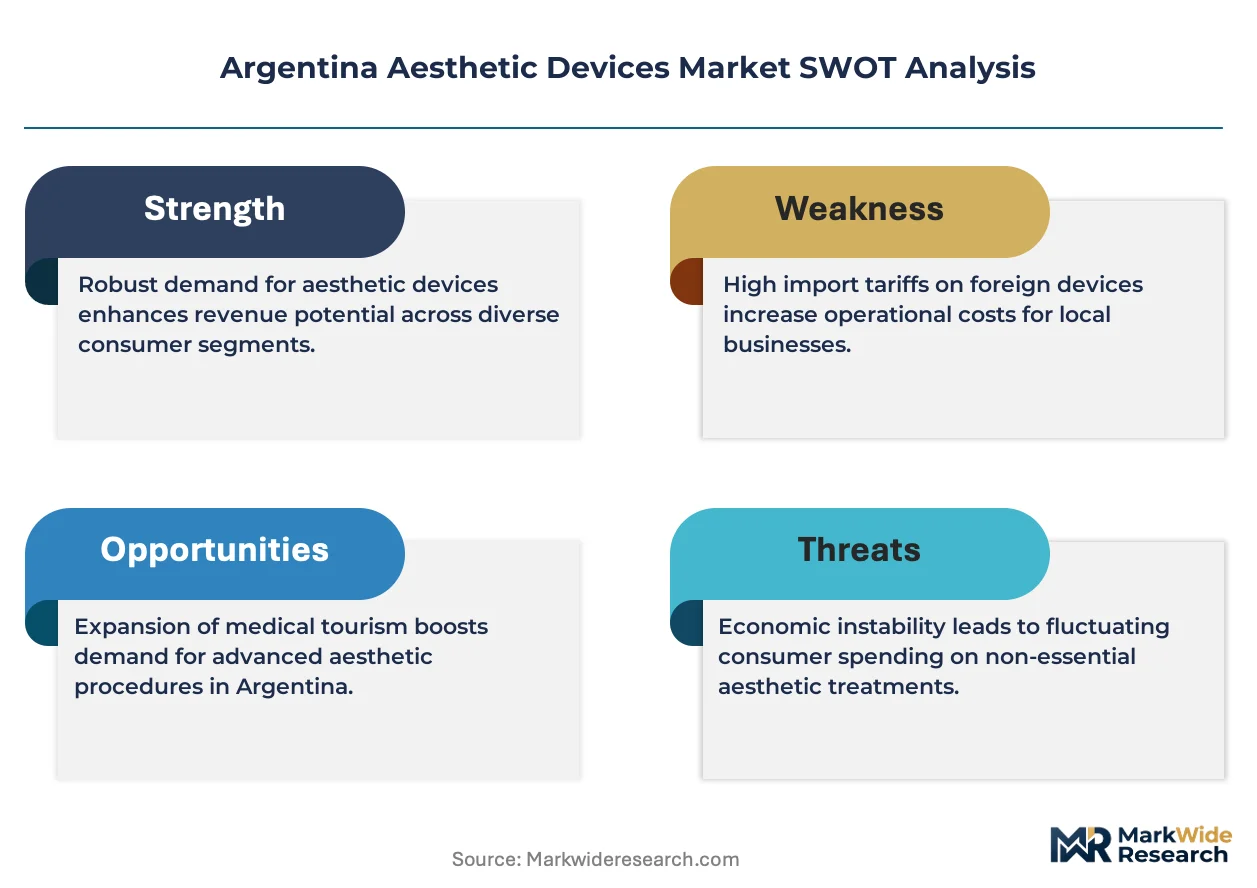
The price-performance boundary between premium laser platforms and commodity energy-based devices is hardening in Argentina. Alma Lasers Ltd (Sisram Medical) leverages its fractional and vascular laser portfolio to dominate high-end dermatology practices in Buenos Aires. AbbVie Inc. (Allergan) anchors the injectables tier through its established neurotoxin and hyaluronic acid filler lines. Candela competes on reliability and service density across mid-market clinics in Córdoba and Rosario.
Aesthetic devices encompass electromechanical and biologic systems engineered to alter skin, adipose, or muscular tissue through controlled thermal, optical, or mechanical energy delivery, typically operating at wavelengths between 532 nm and 10,600 nm or radiofrequencies in the 0.5–40 MHz range for non-invasive or minimally invasive cosmetic outcomes. Their primary commercial purpose is to enable licensed practitioners to perform revenue-generating procedures—skin rejuvenation, hair removal, body contouring, and acne treatment—without surgical intervention. Injectables command the deepest margin pools due to recurring consumable purchases and patient retention cycles, while energy-based devices represent the fastest-growing product type as clinics diversify beyond traditional laser hair removal. Non-invasive technology leads volume adoption among beauty centers, though minimally invasive modalities capture premium pricing in hospital-affiliated dermatology practices.
ANMAT, Argentina's national medical device regulator, enforces registration and post-market surveillance requirements that extend import timelines for novel aesthetic technologies, while the Argentine Ministry of Health coordinates provincial licensing standards for clinic-operated equipment. These frameworks elevate compliance costs for new entrants but protect incumbent suppliers with established regulatory dossiers. Stakeholders must monitor ANMAT's alignment with MERCOSUR technical regulations and the potential harmonization of energy-based device classifications across member states, as this will determine whether manufacturers can leverage centralized approvals or remain subject to country-specific pathways.
Market Dynamics
ANMAT's evolving registration pathways for energy-based systems are compressing import timelines for established suppliers while extending barriers for new entrants, concentrating market power among incumbents with dossier depth in Buenos Aires and Córdoba.
Growth Catalysts
- Private clinic network expansion:Dermatology practices across Argentina's metropolitan corridor are diversifying device portfolios for skin rejuvenation and body contouring, pulling capital into energy-based platforms.
- MERCOSUR technical harmonization:Alignment of energy-based device classifications across member states is enabling centralized approval pathways that reduce country-specific regulatory duplication for manufacturers.
- Radiofrequency platform adoption:Non-invasive modalities operating at 0.5–40 MHz are capturing volume in beauty centers as practitioners seek alternatives to traditional laser hair removal revenue streams.
Market Restraints
- ANMAT registration friction:Post-market surveillance requirements and extended dossier reviews for novel aesthetic technologies create compliance cost asymmetry favoring established suppliers.
- Consumable import dependency:Injectables and single-use components for energy-based devices rely on concentrated international supply chains, exposing margin compression from currency volatility.
- Technical wavelength limitations:Devices operating at 532 nm face restricted tissue penetration depth compared to 1,064 nm alternatives, limiting application scope in adipose tissue procedures.
Strategic Opportunities
- Rosario clinic density gap:Mid-market aesthetic centers in Argentina's third-largest metropolitan area remain underpenetrated by premium laser platforms compared to Buenos Aires saturation.
- Hybrid optical-RF convergence:Combination devices integrating fractional laser with bipolar radiofrequency are creating procedure efficiency advantages for skin tightening applications.
- Provincial licensing standardization:Argentine Ministry of Health coordination of clinic-operated equipment rules is reducing inter-provincial regulatory fragmentation for multi-location operators.
Industry Challenges
- Biomedical engineer scarcity:Servicing density requirements for energy-based platforms exceed trained technician supply in Córdoba and secondary cities, extending equipment downtime.
- Capital equipment cycles:Laser platform refresh timelines of 5–7 years compress ROI realization for clinic operators amid rapid wavelength and cooling technology advances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Aesthetic Devices Market |
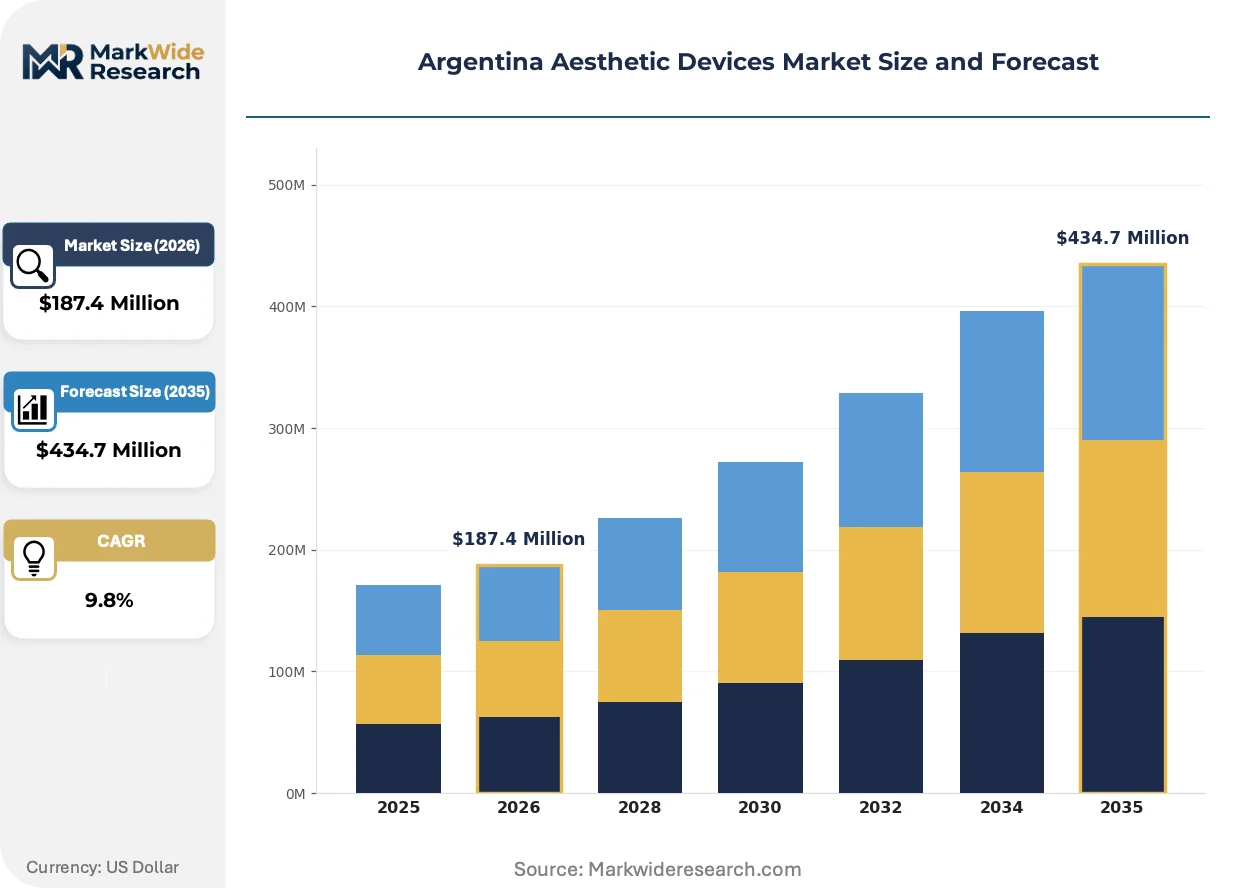
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Injectables, Energy-Based Devices, Dermal Fillers End User: Clinics, Hospitals, Beauty Centers, Dermatology Practices Technology: Non-Invasive, Minimally Invasive, Surgical Techniques, Radiofrequency Application: Skin Rejuvenation, Hair Removal, Body Contouring, Acne Treatment |
| Companies Covered | Johnson & Johnson, AbbVie Inc. (Allergan), Alma Lasers Ltd (Sisram Medical), Bausch Health Companies Inc. (Solta Medical), Candela, Sciton Inc., Venus Concept, Cutera Inc., Merz Pharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Aesthetic Devices Market Strategic Shifts
Technology convergence and regulatory pathway compression are restructuring competitive advantage in Argentina's aesthetic device sector, with platform unification and procurement model evolution as dominant forces.
Fractional laser technology is unifying vascular and rejuvenation applications through tunable wavelength platforms that reduce single-purpose device counts. High-end dermatology practices in Buenos Aires are consolidating capital budgets around multi-modality systems. This unification is compressing addressable market scope for standalone hair removal or vascular-specific platforms.
ANMAT's alignment with MERCOSUR technical regulations is reshaping import authorization timelines for energy-based systems. Manufacturers with centralized approval dossiers gain accelerated market access relative to country-specific filers. Hospital-affiliated dermatology practices are prioritizing suppliers with established MERCOSUR regulatory footprints to reduce procurement uncertainty.
Beauty centers are fragmenting procurement across capital purchase and consumable bundling models, unbundling after-sales service contracts from equipment acquisition. Mid-market clinics in Rosario and Córdoba are negotiating direct consumable supply agreements that bypass traditional distributor markups. This shift is most visible in injectables purchasing, where patient retention cycles drive recurring revenue concentration.
Argentina Aesthetic Devices Market Segmentation
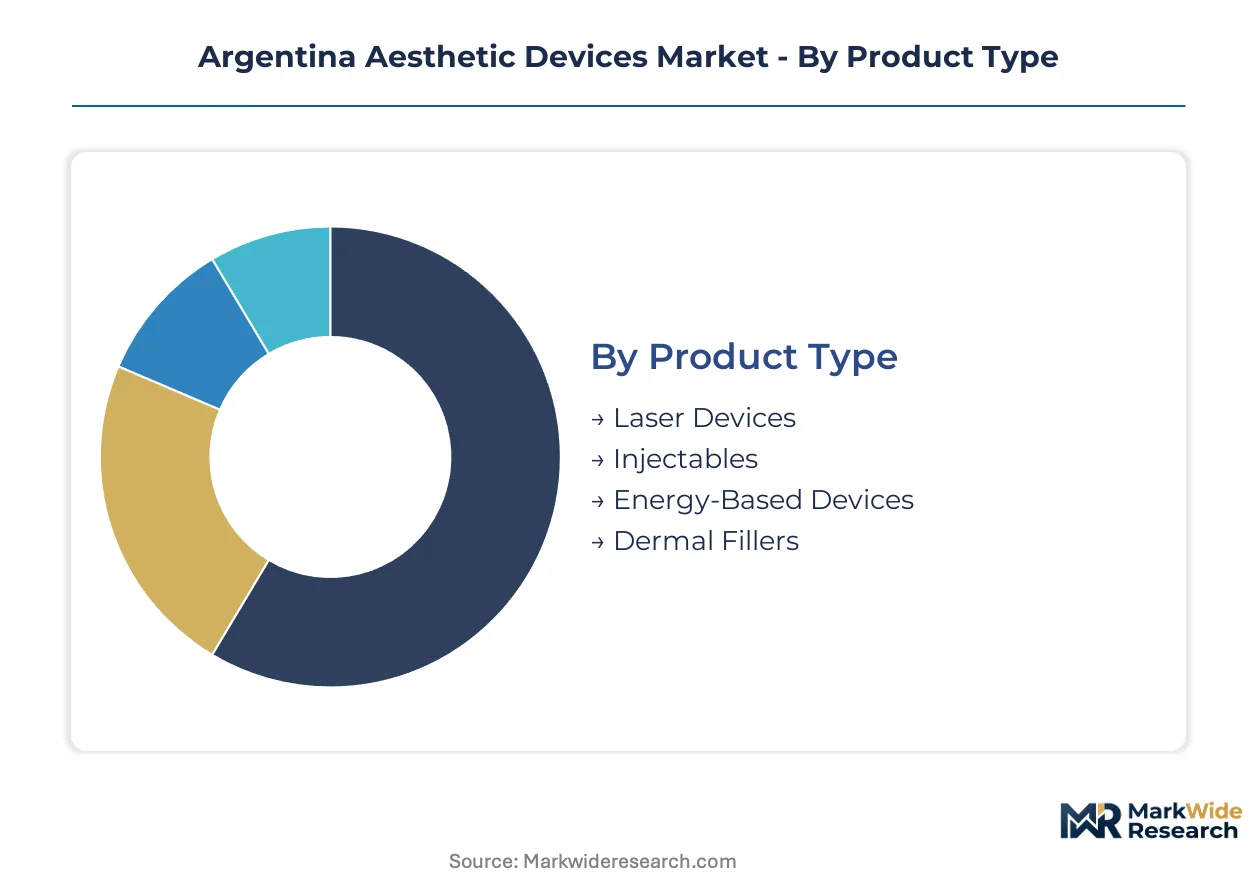
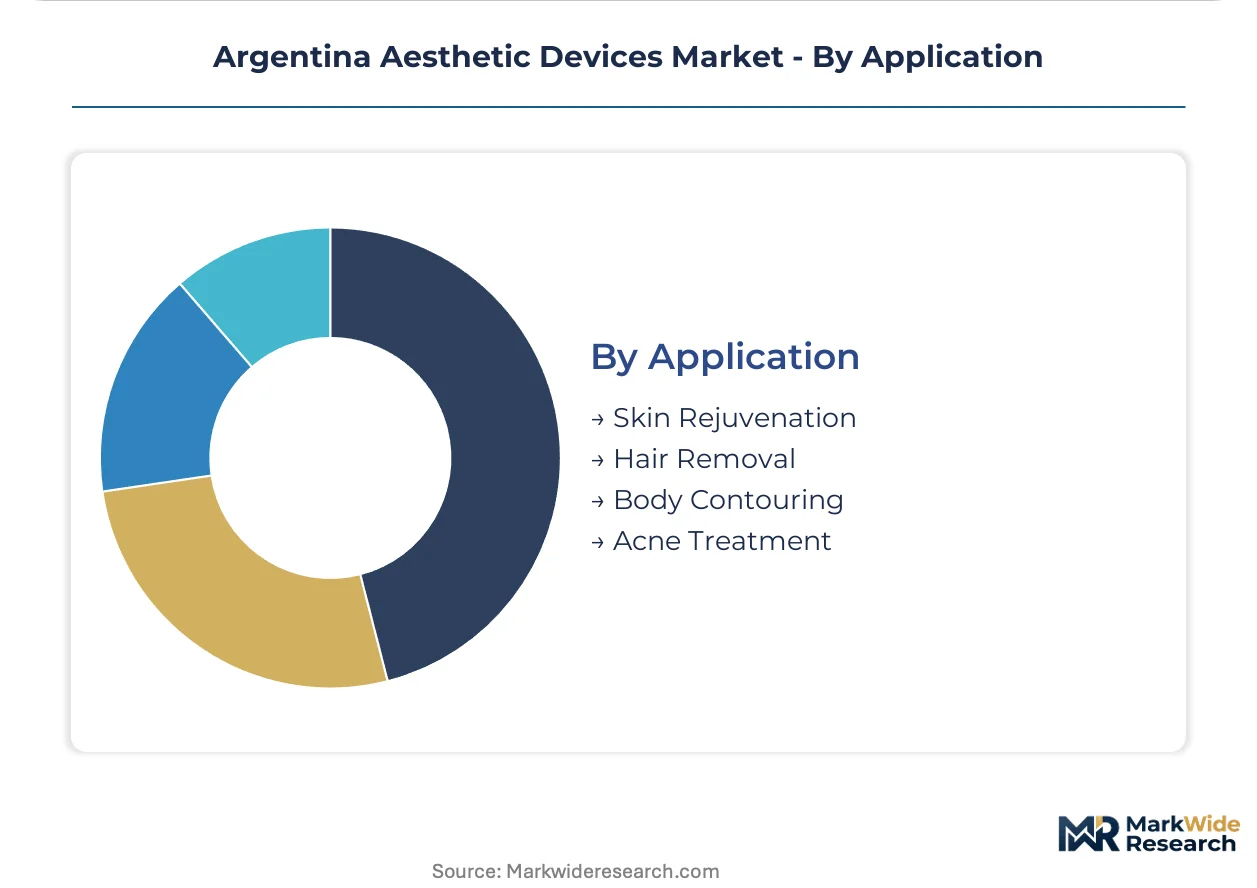
Argentina's aesthetic device landscape fragments across technology intensity and care setting tiers. Each segmentation axis reveals distinct procurement patterns and margin architectures that shape supplier positioning in Buenos Aires, Córdoba, and Rosario.
Product Type:
Customization intensity varies sharply across this category, from bespoke wavelength configurations in premium laser platforms to standardized consumable formats in injectables.
- Injectables:Neurotoxin and hyaluronic acid formulations generate recurring revenue through patient retention cycles. Buenos Aires dermatology practices concentrate demand here due to consumable bundling models and direct procurement agreements that bypass distributor markups.
- Energy-Based Devices:Radiofrequency and ultrasound platforms operating at 0.5–40 MHz enable non-invasive adipose tissue modification. Beauty centers across Argentina's metropolitan corridor are diversifying into these systems to offset declining laser hair removal margins.
- Laser Devices:Fractional and vascular platforms at 532–10,600 nm wavelengths dominate capital budgets in high-end practices. ANMAT registration dossiers for these systems favor established suppliers with MERCOSUR technical documentation.
- Dermal Fillers:Cross-linked hyaluronic acid formulations address volume loss and contouring applications. Córdoba clinic networks show rising uptake as practitioners expand beyond traditional neurotoxin protocols.
Most installed capacity flows through Injectables. Expansion is steepest in Energy-Based Devices.
End User:
Capital deployment thresholds and regulatory exposure separate these customer tiers, with hospital-affiliated practices demanding MERCOSUR-harmonized device classifications.
- Dermatology Practices:Hospital-affiliated and independent specialist clinics command premium pricing for minimally invasive modalities. ANMAT's evolving registration pathways compress procurement timelines for these operators in Buenos Aires.
- Beauty Centers:Non-invasive technology volume concentrates here, driven by lower capital barriers and faster patient throughput. Rosario and secondary cities show underpenetration relative to Buenos Aires saturation.
- Clinics:Mid-market aesthetic centers balance device portfolio breadth against 5–7 year capital refresh cycles. Córdoba's expanding clinic density pulls investment into multi-modality platforms.
- Hospitals:Academic medical centers prioritize suppliers with established post-market surveillance frameworks and biomedical engineer servicing density.
Revenue concentration sits with Dermatology Practices. Patient volume leadership belongs to Beauty Centers.
Technology:
Procedure invasiveness correlates directly with pricing power and technician training requirements across Argentine care settings.
- Non-Invasive:Surface-level energy delivery without epidermal breach dominates beauty center procurement. Radiofrequency platforms at 0.5–40 MHz capture volume as practitioners seek alternatives to traditional laser protocols.
- Minimally Invasive:Fractional laser and micro-needle RF systems command premium positioning in hospital-affiliated dermatology practices. Buenos Aires specialists favor these modalities for skin tightening applications with reduced downtime.
- Radiofrequency:Bipolar and monopolar configurations enable targeted thermal collagen remodeling. Argentine Ministry of Health provincial licensing standardization is reducing equipment approval fragmentation for multi-location operators deploying these systems.
- Surgical Techniques:Traditional excisional and liposuction methods retain niche positioning for severe adipose cases. Demand concentrates in tertiary hospital settings with anesthesia and overnight capability.
Technology deployment favors Non-Invasive systems. Capability investment is shifting toward Minimally Invasive platforms.
Application:
Procedure frequency and consumable attachment rates determine margin sustainability across these clinical use cases.
- Skin Rejuvenation:Fractional laser and RF-based collagen induction address photodamage and textural irregularities. Buenos Aires practices report strongest demand concentration as patient demographics skew toward preventive aging protocols.
- Hair Removal:Traditional revenue mainstay for aesthetic clinics now facing margin compression from commoditized IPL platforms. Córdoba and Rosario beauty centers still deploy these systems for volume patient acquisition.
- Body Contouring:Non-invasive fat reduction and skin tightening applications drive energy-based device diversification. ANMAT registration timelines for novel adipose-targeting technologies favor incumbent suppliers with dossier depth.
- Acne Treatment:Blue light and vascular laser protocols address inflammatory and post-inflammatory indications. Secondary city clinics underindex on these applications relative to metropolitan corridor penetration.
Procedure volume concentrates in Skin Rejuvenation. Platform investment is accelerating fastest in Body Contouring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the largest installed base of energy-based aesthetic platforms in Latin America, while Argentina concentrates higher procedure density per capita in private dermatology settings. Mexico's border corridor pulls cross-border patient flows from the southwestern United States. Chile and Colombia anchor premium-tier demand in the Andean region.
Brazil
Hospital-affiliated dermatology networks in São Paulo and Rio de Janeiro drive demand for multi-modality laser systems. ANVISA's medical device registration framework creates compliance cost asymmetry favoring established suppliers with dossier depth. The southeastern corridor concentrates premium platform installations, with mid-market clinics in Minas Gerais expanding device portfolios for body contouring applications.
Mexico
Beauty centers across Mexico City and Guadalajara deploy radiofrequency platforms at volume price points for non-invasive adipose procedures. COFEPRIS regulatory pathways for energy-based devices compress import timelines for manufacturers with established technical documentation. The Tijuana-Monterrey corridor captures cross-border patient flows seeking cost-advantaged aesthetic treatments.
Chile
Santiago's private clinic networks prioritize minimally invasive fractional laser systems for skin rejuvenation protocols. The national pharmaceutical regulator enforces post-market surveillance requirements that elevate servicing density standards for equipment suppliers. Metropolitan concentration of dermatology practices exceeds per-capita penetration in secondary cities such as Valparaíso and Concepción.
Colombia
Bogotá and Medellín anchor demand for injectable consumables through direct procurement agreements that bypass traditional distributor channels. INVIMA's evolving medical device classifications reshape import authorization timelines for novel aesthetic technologies. The Andean corridor shows rising adoption of hybrid optical-RF platforms among mid-market aesthetic centers.
Argentina Aesthetic Devices Market Competitive Environment
Top-tier vendors anchor premium laser platform supply, while mid-market specialists compete on service density and consumable bundling. The vendor base stratifies across three tiers: multinational manufacturers with MERCOSUR regulatory footprints, regional distributors with established clinic relationships, and emerging suppliers targeting price-sensitive beauty centers. Strategic archetypes include platform unifiers consolidating multiple wavelengths, consumable-anchored injectable suppliers, and service-intensive RF specialists. Dominant competitive moves encompass direct procurement agreement negotiations and provincial licensing standardization alignment.
Within the multinational manufacturer tier, AbbVie Inc. (Allergan) and Alma Lasers Ltd (Sisram Medical) occupy positions reflecting divergent strategic anchors. AbbVie exemplifies the consumable-recurring revenue archetype through neurotoxin and hyaluronic acid filler portfolios. Alma Lasers represents the platform-unification vector with fractional and vascular laser systems. Candela sits within the mid-market reliability tier, competing on service density across Córdoba and Rosario clinic networks.
| Leading Market Players |
|---|
| Johnson & Johnson |
| AbbVie Inc. (Allergan) |
| Alma Lasers Ltd (Sisram Medical) |
| Bausch Health Companies Inc. (Solta Medical) |
| Candela |
| Sciton Inc. |
| Venus Concept |
| Cutera Inc. |
| Merz Pharma |
| Others |
Value Chain & Pricing Dynamics
ANMAT's post-market surveillance mandates gate qualified supply access and premium-tier pricing power for energy-based platforms in Argentina. Compliance cost asymmetry favors established suppliers with dossier depth, compressing margin realization for new entrants while protecting incumbent pricing authority in Buenos Aires dermatology networks.
Pricing Analysis
Capacity additions in radiofrequency platforms across Brazil and Mexico are reshaping price floors for non-invasive modalities entering Argentina. Pricing stratifies across premium laser systems with MERCOSUR technical documentation, mid-market RF platforms with regional service coverage, and economy-tier IPL devices targeting beauty center volume procurement. Cost compression in the IPL tier is intensifying because Brazilian manufacturers are exporting refurbished platforms at distressed price points. Beauty centers in Rosario and secondary cities exhibit highest price sensitivity, while hospital-affiliated dermatology practices in Buenos Aires prioritize certification tier over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Israeli and German laser component suppliers for fractional wavelength systems. Manufacturing concentration centers on Israel for vascular laser platforms, Germany for precision optical assemblies, and the United States for RF generator modules. Argentine distributors draw from concentrated international supply chains for consumables including hyaluronic acid formulations and single-use laser handpieces. Tariff exposure runs through MERCOSUR external tariff schedules for energy-based device classifications. Distribution runs through authorized distributor networks with ANMAT registration custody, though mid-market clinics increasingly negotiate direct consumable procurement agreements that bypass traditional markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's aesthetic device market offers margin expansion through provincial licensing standardization reducing compliance duplication costs and premium-tier shift toward multi-modality platforms commanding service bundling premiums.
For Market Incumbents: Acquire biomedical engineering service capacity in Córdoba and Rosario to close servicing density gaps that extend equipment downtime for competitors. Consolidate ANMAT registration dossiers across MERCOSUR member states to accelerate import timelines relative to country-specific filers. Defend against emerging Chinese RF platform entrants by anchoring hospital-affiliated practices through post-market surveillance frameworks that new suppliers cannot replicate. For New Entrants and Emerging Players: The mid-market price-point gap between Alma Lasers premium platforms and commoditized IPL systems creates entry space for hybrid optical-RF devices with simplified service requirements. Target underpenetrated clinic networks in Rosario where established suppliers maintain thinner service presence. Pursue direct consumable supply agreements with Córdoba clinic operators seeking to bypass distributor markups on injectables and single-use components. For Investors and Strategic Acquirers: Roll-up economics work for regional distributor networks with established ANMAT regulatory custody and provincial clinic relationships because licensing standardization is reducing multi-location operational friction. Five-to-ten year viability hinges on MERCOSUR technical harmonization enabling centralized approval leverage. Monitor ANMAT alignment with regional device classifications as the inflection signal determining whether manufacturers achieve pathway compression or remain trapped in country-specific dossier requirements.| Strategic Initiative | Industry Significance |
|---|---|
| MERCOSUR Technical Harmonization Alignment | Centralized approval pathways reduce regulatory duplication for manufacturers with established dossiers. |
| Biomedical Engineer Training Program Expansion | Servicing density investments in Córdoba and Rosario compress equipment downtime for platform operators. |
| Direct Consumable Procurement Agreements | Bypassing distributor markups captures margin from patient retention cycles in injectables purchasing. |
| Hybrid Optical-RF Platform Development | Combination devices create procedure efficiency advantages for skin tightening applications in mid-market clinics. |
| Provincial Licensing Standardization Coordination | Argentine Ministry of Health alignment reduces inter-provincial fragmentation for multi-location operators. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dermatology practice owners, biomedical engineers, ANMAT regulatory consultants, and GPO contracts managers with secondary validation through ANMAT registration databases, MERCOSUR technical regulation filings, hospital procurement records, and customs import data for energy-based device classifications. Bottom-up clinic-level demand estimates and top-down manufacturer shipment analysis were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic baseline through post-recovery normalization informed the forecast window anchoring. Segmentation dimensions modeled include product type, technology intensity, end-user tier, and application area across the projection horizon. CAGRs were derived from procedure volume growth rates, capital equipment refresh cycles, and consumable attachment rate assumptions. Industry-specific inputs incorporated ANMAT registration timeline compression scenarios and provincial clinic network expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for radiofrequency platform convergence with fractional laser systems would alter the outlook. Forecasts reflect assumptions regarding MERCOSUR harmonization progress, currency stability for import-dependent consumables, and biomedical engineer supply expansion in secondary cities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Root Canal Irrigators Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Pectus Bar Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Microdebrider Market