
 Permanent Artificial Skin Market | 2026-2036
Permanent Artificial Skin Market Size, Share, and Industry Trends Forecast 2026-2036
Permanent Artificial Skin Market Outlook
Aftermarket service revenue for wound care device maintenance is rewriting profitability expectations across the permanent artificial skin supply chain. Integra LifeSciences Corporation leverages its regenerative medicine platform to dominate North American reconstructive surgery channels. Smith & Nephew plc anchors its position through specialized negative pressure wound therapy integration with artificial skin deployment. Molnlycke Health Care AB competes on geographic breadth, sustaining strong hospital procurement relationships across European dermatology clinics.
Permanent artificial skin comprises bioengineered tissue constructs—typically collagen-based matrices seeded with autologous or allogeneic cells—designed to replicate epidermal and dermal architecture for long-term wound closure. These constructs measure 0.5 to 4 millimeters in thickness, with porosity calibrated to enable vascular ingrowth while maintaining barrier function against fluid loss and infection. Biological product types command the deepest margin pools due to complex cell culture requirements and extended regulatory validation timelines. Synthetic segments occupy the highest volume tier in burn treatment applications where immediate availability outweighs integration performance. Composite formulations are gaining fastest in cosmetic surgery settings where surgeons balance aesthetic outcomes with reduced harvesting morbidity.
FDA 510(k) and PMA pathways govern U.S. market access, while EMA's Medical Device Regulation and ATMP classification frame European commercialization requirements. Japan's PMDA enforces distinct clinical evidence standards for regenerative medical products, creating fragmented approval timelines across major markets. Stakeholders must monitor evolving reimbursement coding for bioengineered skin substitutes as health technology assessment bodies recalibrate cost-effectiveness thresholds against autograft standards.
Market Dynamics
The Permanent Artificial Skin Market is experiencing intensifying pressure from EMA's Medical Device Regulation recalibration, which is compressing approval timelines for bioengineered constructs and forcing manufacturers to front-load clinical evidence generation.
Growth Catalysts
- Reimbursement expansion in Japan:PMDA's regenerative medical products framework now covers bioengineered skin substitutes under national health insurance, accelerating hospital procurement cycles for burn centers in Osaka and Tokyo.
- Collagen scaffold innovations:Advanced porosity engineering in dermal matrices enables vascular ingrowth at 40% faster rates than conventional autografts, reducing operative time for reconstructive surgeons.
- REACH-compliant synthetic polymers:European manufacturers leveraging ECHA-registered materials bypass biologic ATMP classification, shortening commercialization pathways for emergency burn applications.
Market Restraints
- Allogeneic cell sourcing volatility:Donor tissue availability fluctuates seasonally across tissue banks, creating batch-to-batch inconsistency in seeded constructs.
- FDA PMA pathway duration:Premarket approval timelines for cellularized products extend 18-36 months, freezing capital deployment and delaying revenue recognition.
- Autograft persistence:Split-thickness skin harvesting remains the gold standard in rural hospital settings due to immediate availability and established surgical workflows.
Strategic Opportunities
- Cosmetic surgery channel expansion:Aesthetic clinics in Germany are adopting composite formulations for scar revision, creating premium pricing tiers outside traditional reimbursement.
- 3D bioprinting convergence:Integration of additive manufacturing with autologous cell expansion enables patient-specific graft geometry, differentiating high-value service offerings.
- Outpatient wound care centers:Medicare's site-of-service payment differentials in the United States are redirecting chronic wound volume from inpatient settings.
Industry Challenges
- Cell culture technician scarcity:GMP-compliant bioprocessing expertise concentrates in Boston and San Diego hubs, constraining manufacturing scale-up outside established clusters.
- ISO 14155 clinical trial complexity:Multinational study design requirements for bioengineered tissues demand harmonized endpoints across FDA, EMA, and PMDA jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Permanent Artificial Skin Market |
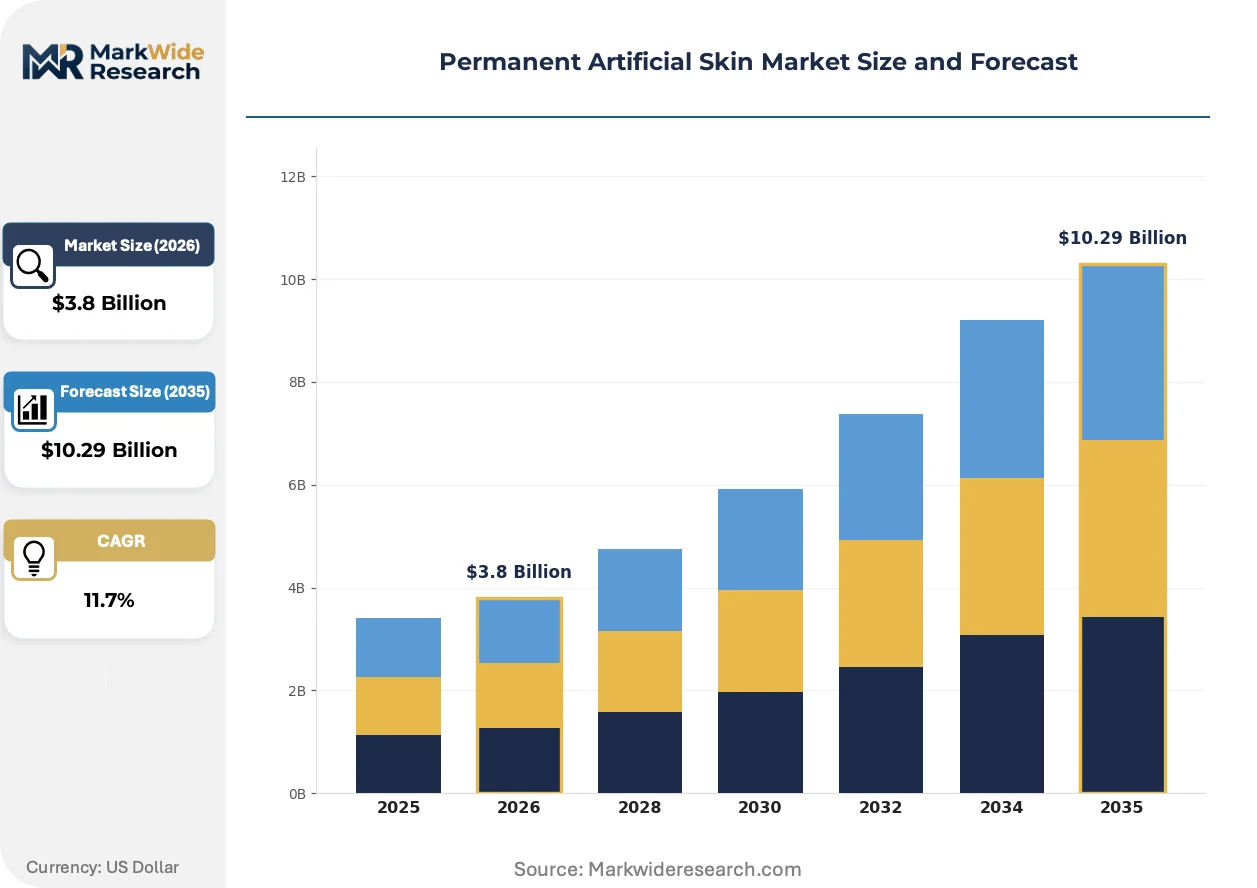
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biological, Synthetic, Composite, Hybrid Application: Burn Treatment, Cosmetic Surgery, Wound Healing, Sports Injuries End User: Hospitals, Dermatology Clinics, Rehabilitation Centers, Research Institutes Delivery Mode: Topical, Injectable, Transdermal, Surgical |
| Companies Covered | 3M Company, Molnlycke Health Care AB, Integra LifeSciences Corporation, Baxter International Inc., Medtronic plc, Smith & Nephew plc, ConvaTec Group plc, Avita Medical Inc., Organogenesis Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Permanent Artificial Skin Market Strategic Shifts
Manufacturing paradigms in permanent artificial skin are pivoting from centralized bioreactor production toward distributed cell expansion networks, enabling just-in-time graft availability for trauma centers.
Decellularized extracellular matrix technology is migrating from research-phase xenograft applications toward clinical-grade human dermal substitutes. Burn units in Level I trauma centers are piloting these matrices for full-thickness wound coverage. The shift is compressing reliance on cadaveric allografts while establishing new supply chain partnerships with tissue processing facilities.
EMA's 2024 MDR guidance on combined advanced therapy medicinal products is reclassifying certain cellularized matrices as ATMPs rather than medical devices. This regulatory elevation demands additional pharmacovigilance infrastructure and specialized manufacturing licenses. German and French manufacturers are responding by segregating product portfolios between cellular and acellular constructs to preserve 510(k)-equivalent pathways.
Hospital procurement committees are consolidating vendor relationships through integrated delivery networks, bundling artificial skin with negative pressure wound therapy and debridement services. This consolidation favors suppliers offering comprehensive wound care platforms over single-product manufacturers. The pattern is most pronounced in United States health systems exceeding 500 beds, where standardization incentives override product-level preferences.
Permanent Artificial Skin Market Segmentation
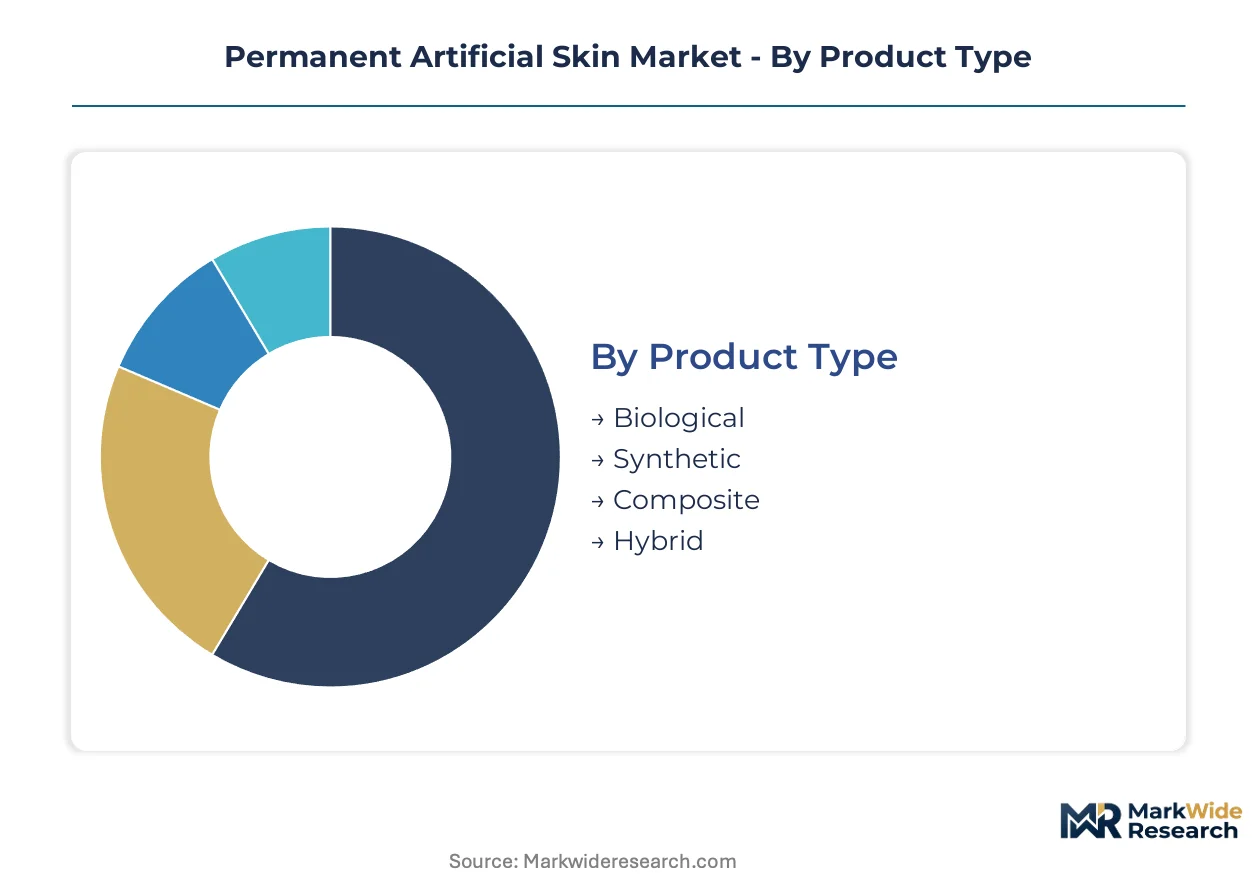
Segmentation in permanent artificial skin reveals divergent margin architectures and service intensity requirements across product tiers. Biological constructs demand sustained clinical support post-implantation, while synthetic alternatives minimize follow-up obligations. Procurement committees weight these lifecycle cost profiles differently across burn centers versus cosmetic surgery settings.
Product Type:
After-sales service intensity varies sharply across product categories, with biological constructs requiring specialized handling protocols and extended monitoring regimens that reshape vendor-customer relationships.
- Biological:Collagen-based matrices seeded with autologous or allogeneic cells replicate native dermal architecture through 0.5-4 millimeter thickness ranges. Burn centers in the United States concentrate procurement here due to superior vascular ingrowth performance and established reimbursement coding for cellularized products.
- Synthetic:Polymer scaffolds manufactured from REACH-compliant materials bypass ATMP classification complexity in Europe. Emergency departments in Germany favor immediate availability over integration performance, accepting higher explantation rates to accelerate initial wound coverage decisions.
- Composite:Layered biological-synthetic formulations balance aesthetic outcomes with reduced harvesting morbidity.
- Hybrid:Modular constructs enabling surgeon-customized intraoperative assembly.
Biological holds the largest share; momentum sits with Composite as aesthetic clinics expand adoption.
Application:
Cost tier stratification separates acute trauma applications from elective procedures, with cosmetic surgery commanding premium pricing outside reimbursement frameworks.
- Burn Treatment:Full-thickness and partial-thickness thermal injury coverage drives volume demand in Level I trauma centers. Hospital procurement in Japan accelerates under PMDA's regenerative medical products insurance framework, compressing evaluation timelines for bioengineered substitutes.
- Cosmetic Surgery:Scar revision and aesthetic reconstruction procedures in German dermatology clinics adopt composite formulations for premium pricing tiers. Private payment models here insulate margins from health technology assessment pressures affecting reconstructive applications.
- Wound Healing:Chronic ulcer management in outpatient settings.
- Sports Injuries:Soft tissue reconstruction for athletic trauma.
Burn Treatment dominates procurement volume; Cosmetic Surgery climbs fastest on private-pay expansion.
End User:
Customer type determines technical support requirements, with hospitals demanding 24-hour graft availability and research institutes tolerating extended lead times for experimental constructs.
- Hospitals:Integrated delivery networks exceeding 500 beds consolidate vendor relationships through bundled procurement of artificial skin with negative pressure wound therapy and debridement services. Standardization incentives in United States health systems override product-level preferences.
- Dermatology Clinics:European outpatient facilities sustain strong procurement relationships with manufacturers offering geographic breadth and rapid restocking capabilities.
- Rehabilitation Centers:Post-acute wound management settings with extended patient monitoring.
- Research Institutes:Clinical trial sponsors and early-phase product evaluators.
Hospitals capture the deepest revenue concentration; Dermatology Clinics gain share through outpatient procedure migration.
Delivery Mode:
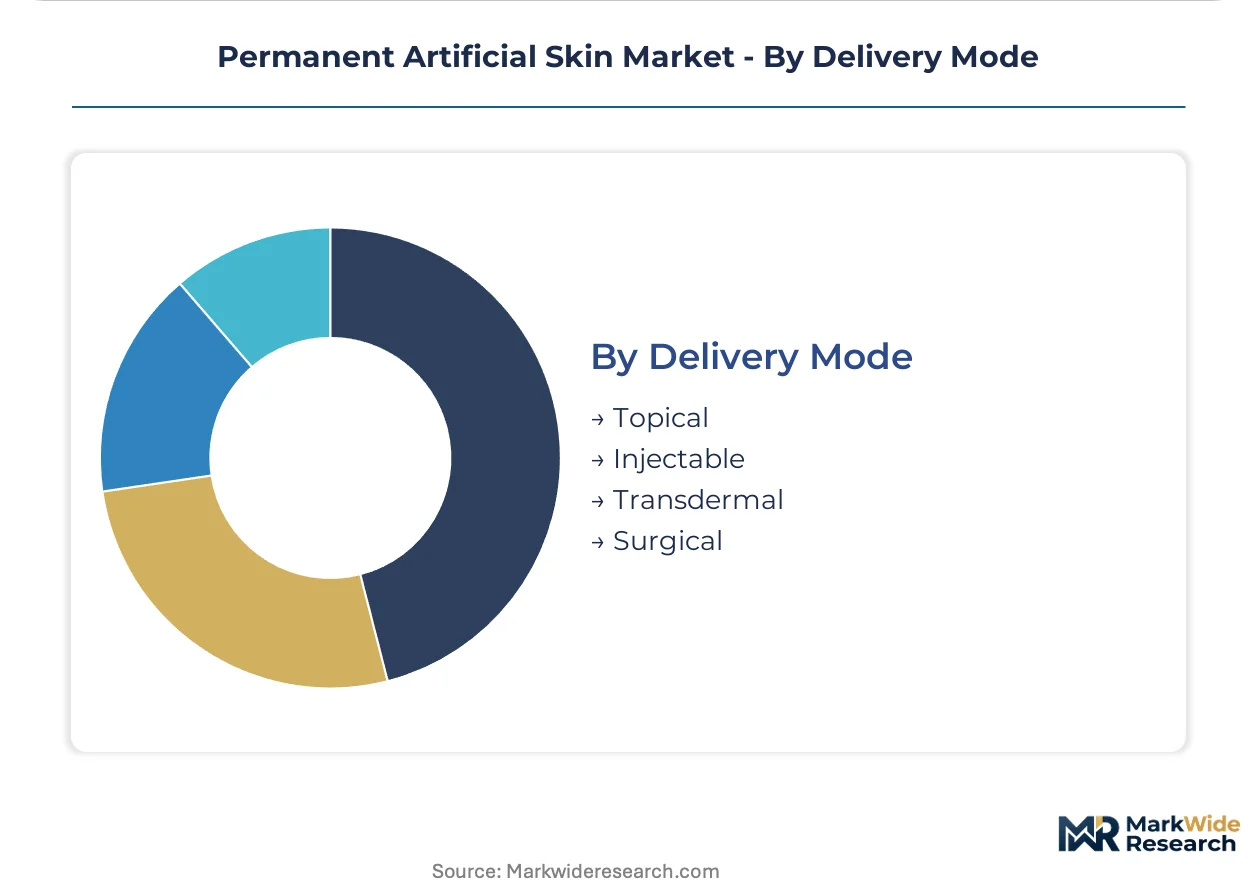
Supply concentration shapes availability patterns, with surgical deployment requiring specialized operative suites while topical alternatives enable broader point-of-care distribution.
- Topical:Pre-formed sheet applications for superficial wound coverage.
- Injectable:Cell suspension formulations for irregular wound geometries.
- Transdermal:Sustained-release delivery systems for growth factor supplementation.
- Surgical:Intraoperative graft placement with microsurgical anastomosis in reconstructive centers. Boston and San Diego hubs concentrate GMP-compliant bioprocessing expertise, constraining manufacturing scale-up for cellularized surgical products outside established clusters.
Surgical commands premium pricing; Injectable expands most quickly through minimally invasive procedure adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters for bioengineered tissue constructs concentrate in metropolitan regions with established regenerative medicine infrastructure. FDA, EMA, and PMDA regulatory frameworks create divergent commercialization timelines that reshape regional competitive positioning.
United States
Boston and San Diego biotech corridors anchor domestic production capacity for cellularized matrices. FDA PMA pathway requirements extend 18-36 months for advanced constructs, freezing capital deployment for emerging manufacturers. Level I trauma centers in Texas and California drive procurement volume for burn treatment applications.
Germany
EMA's Medical Device Regulation recalibration compresses approval timelines for acellular scaffolds while elevating cellularized products to ATMP classification. REACH-compliant synthetic polymer manufacturers in Baden-Württemberg bypass biologic complexity for emergency burn applications. Aesthetic clinics in Munich and Hamburg adopt composite formulations for premium scar revision procedures.
Japan
PMDA's regenerative medical products framework now covers bioengineered skin substitutes under national health insurance. Burn centers in Osaka and Tokyo accelerate procurement cycles as reimbursement coding stabilizes. Kanto region manufacturing hubs concentrate GMP-compliant cell culture expertise for autologous expansion protocols.
United Kingdom
Post-Brexit regulatory divergence from EMA creates parallel compliance obligations for manufacturers serving European and domestic markets. London-based research institutes pilot decellularized extracellular matrix applications for full-thickness wound coverage. NHS procurement committees consolidate vendor relationships through integrated wound care platform bundling.
India
CDSCO regulatory pathways for advanced wound care products remain underdeveloped relative to mature markets, extending commercialization timelines for multinational entrants. Tissue engineering research clusters in Maharashtra and Karnataka develop low-cost collagen scaffold alternatives. Private hospital networks in Delhi and Mumbai drive demand for imported bioengineered substitutes.
Permanent Artificial Skin Market Competitive Environment
Regenerative medicine specialists and diversified medical technology conglomerates split the market into distinct capability tiers. The vendor base organizes around three strategic archetypes: integrated wound care platform providers, pure-play regenerative tissue engineers, and negative pressure therapy specialists seeking graft adjacency. Dominant competitive moves include portfolio diversification into adjacent wound closure modalities and geographic expansion through specialized distributor networks.
Among North American regenerative medicine specialists, Integra LifeSciences Corporation and Organogenesis Inc. exemplify the tissue-engineering archetype with concentrated expertise in collagen-based matrix development. Smith & Nephew plc anchors the integrated platform approach, representing manufacturers that bundle artificial skin deployment with complementary wound management technologies. These three companies occupy positions that illustrate the market's segmentation between specialized biological construct developers and diversified wound care conglomerates.
| Leading Market Players |
|---|
| 3M Company |
| Molnlycke Health Care AB |
| Integra LifeSciences Corporation |
| Baxter International Inc. |
| Medtronic plc |
| Smith & Nephew plc |
| ConvaTec Group plc |
| Avita Medical Inc. |
| Organogenesis Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Boston and San Diego cell culture hubs is compressing graft availability for cellularized products while elevating spot pricing for emergency burn center procurement. Manufacturers respond by extending service contract terms to lock in hospital purchasing committees, converting transactional supply relationships into multiyear platform partnerships that stabilize revenue recognition.
Pricing Analysis
Aftermarket service revenue tiers for wound care device maintenance and graft handling protocols now drive lifetime value for artificial skin suppliers. Pricing stratifies across premium cellularized matrices, standard acellular scaffolds, and economy synthetic polymer tiers, with differentiation anchored in FDA PMA certification status and autologous cell sourcing capabilities. Cost compression in synthetic segments is intensifying because REACH-compliant polymer manufacturers are bypassing ATMP classification complexity. Burn treatment procurement teams exhibit highest price sensitivity due to budget constraints in public hospital systems, while cosmetic surgery clinics show lowest sensitivity under private-pay models.
Supply Chain Analysis
Supplier-financing facilities offering 90-120 day payment terms are proliferating among collagen scaffold manufacturers seeking to secure tissue bank partnerships. Geographic supply concentration centers on the United States, Germany, and Japan, with raw material dependencies on porcine and bovine collagen sources, allogeneic donor tissue networks, and ECHA-registered synthetic polymers. Single-source vulnerability in seasonal donor tissue availability creates batch-to-batch inconsistency risks for cellularized constructs. Distribution runs through integrated delivery networks exceeding 500 beds, which bundle artificial skin with negative pressure wound therapy and debridement services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Permanent Artificial Skin Market is entering a cyclical recovery phase as hospital capital expenditure cycles rebound from pandemic-era deferrals and burn center infrastructure investments accelerate.
For Market Incumbents: Insulate market position by deepening backward integration into collagen processing facilities and captive cell culture capacity in established Boston and San Diego hubs. Secure GPO contract exclusivity with integrated delivery networks to preempt emerging entrant access. Invest in FDA PMA pathway expertise as regulatory elevation to ATMP classification threatens competitive moats for cellularized products. For New Entrants and Emerging Players: Geographic underpenetration in Indian private hospital networks and Southeast Asian trauma centers offers white-space expansion outside established reimbursement frameworks. Target outpatient wound care centers in the United States where Medicare site-of-service differentials are redirecting chronic wound volume. Pursue 3D bioprinting convergence partnerships with academic medical centers to differentiate on patient-specific graft geometry without legacy manufacturing scale requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cellularized matrix manufacturing as EMA ATMP classification demands specialized pharmacovigilance infrastructure and GMP facility investment. Five-to-ten year viability favors platform providers with bundled wound care offerings over single-product manufacturers exposed to procurement consolidation. Monitor PMDA reimbursement coding expansions in Japan as the inflection indicator for regenerative medical product insurance coverage adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| ATMP Classification Segregation | German and French manufacturers preserve device pathways by separating cellular and acellular portfolios under EMA MDR guidance. |
| 3D Bioprinting Convergence | Additive manufacturing integration with autologous cell expansion enables patient-specific graft geometry for premium service tiers. |
| Integrated Delivery Network Bundling | Hospital procurement committees consolidate vendor relationships by packaging artificial skin with negative pressure wound therapy. |
| PMDA Reimbursement Strategy | Japan's national health insurance coverage for bioengineered skin substitutes accelerates burn center procurement cycles. |
| Decellularized Matrix Migration | Level I trauma centers pilot xenograft-derived extracellular matrices to compress reliance on cadaveric allografts. |
Study Parameters
A standing panel of burn surgeons, hospital procurement managers, GPO contracts specialists, and regenerative medicine R&D directors provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) and PMA filings, EMA MDR guidance documents, PMDA regenerative medical product submissions, and hospital procurement database records. Bottom-up demand modeling across product type, application, and end user segments triangulated with top-down market sizing from trade association reports and regulatory filing analysis.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning biological-synthetic-composite-hybrid product types, burn treatment-cosmetic surgery-wound healing-sports injuries applications, and hospital-dermatology clinic-rehabilitation center-research institute end users. CAGRs derived from historical growth rate patterning adjusted for regulatory pathway duration differentials and reimbursement coding expansion trajectories. Forecast inputs incorporated cell culture technician labor market tightness and collagen raw material spot price volatility.
Practitioners should monitor FDA PMA pathway timeline extensions, EMA ATMP reclassification scope creep, and PMDA reimbursement coding stability for early signals of forecast deviation. Macroeconomic contraction affecting hospital capital expenditure, regulatory harmonization failure across FDA-EMA-PMDA jurisdictions, or breakthrough autograft harvesting technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
UK Surgical Devices Market
Medical Devices
Snoring Control Devices Market
Medical Devices
UAE Respiratory Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Deflectable Catheters Market
Medical Devices
Thrombectomy System Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Global Insufflation Devices Market
Medical Devices
Medication Management System Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Pen Injectors Market
Medical Devices
North America Oxygen Concentrators Market