
 MRI Guided Drug Delivery Market | 2026-2036
MRI Guided Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Guided Drug Delivery Market Analytics
The EU Medical Device Regulation is hardening compliance requirements for MRI-compatible drug delivery systems, forcing manufacturers to expand clinical evidence packages. Medtronic leverages its neurosurgical navigation portfolio to anchor positions in intracranial drug delivery. ClearPoint Neuro specializes in MRI-guided convection-enhanced delivery platforms for central nervous system therapeutics. GE HealthCare extends its imaging hardware dominance into integrated therapy guidance ecosystems.
MRI guided drug delivery deploys magnetic resonance imaging to visualize and steer therapeutic agents to target tissues in real time, typically achieving spatial resolution below one millimeter for precise anatomical localization. The technology serves primarily to enable localized treatment of brain tumors and other deep-seated lesions while sparing surrounding healthy tissue. Nanoformulations command expanding R&D investment due to their magnetic susceptibility tuning and prolonged circulation profiles. Cancer Treatment applications generate the dominant revenue share, while Neurological Disorders represents the fastest-growing application segment as blood-brain barrier penetration techniques mature.
The FDA breakthrough device program and EU MDR conformity assessment frameworks shape product development timelines and market access trajectories for combination product developers. Japan's PMDA offers prioritized review pathways for innovative drug-device combinations targeting intractable cancers. ISO 13485 quality management requirements and IEC 60601 electrical safety standards govern manufacturing scale-up for MRI-conditional delivery hardware. Stakeholders must monitor evolving reimbursement codes for image-guided infusion procedures across major healthcare systems.
Market Dynamics
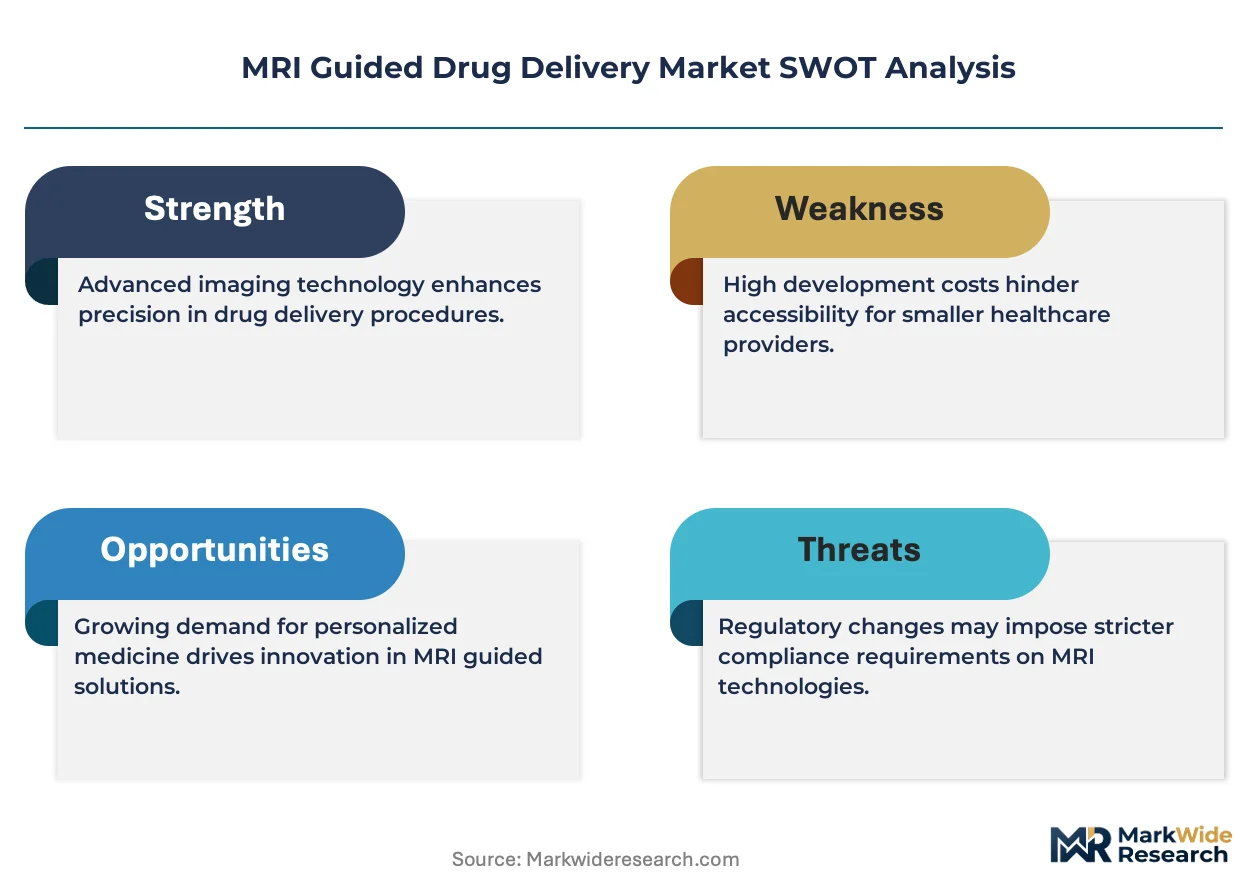
The EU Medical Device Regulation's tightened clinical evidence requirements for MRI-conditional hardware is compressing product development timelines while simultaneously elevating barriers for new entrants without established regulatory infrastructure.
Growth Catalysts
- FDA Breakthrough Device Pathway:The program accelerates commercialization timelines for combination products addressing intractable cancers, reducing premarket review duration for eligible intracranial delivery systems.
- Blood-brain barrier penetration techniques:Advances in convection-enhanced delivery and focused ultrasound are expanding addressable patient populations for CNS therapeutics previously deemed unreachable.
- Interventional MRI suite proliferation:Major hospital systems in the United States, Germany, and Japan are installing dedicated intraoperative MRI facilities, creating installed base for integrated drug delivery platforms.
Market Restraints
- Superconducting magnet supply concentration:Liquid helium dependency and cryogenic component manufacturing concentrates among a limited supplier base in Japan and the United States, exposing OEMs to input volatility.
- EU MDR conformity assessment bottlenecks:Notified body capacity constraints extend certification timelines for MRI-compatible infusion hardware, delaying market access by 12-24 months.
- Interventional radiologist training gaps:The specialized skill set required for real-time MRI-guided navigation limits deployment velocity even where capital equipment exists.
Strategic Opportunities
- Pediatric oncology applications:Minimally invasive delivery protocols for brainstem and posterior fossa tumors in children represent an underserved segment with limited competing modalities.
- Japan PMDA prioritized review:The Sakigake designation offers expedited pathways for innovative drug-device combinations, attracting developers targeting intractable CNS malignancies.
- Theranostic convergence:Integration of MRI-guided delivery with real-time therapeutic monitoring enables closed-loop treatment adaptation, commanding premium positioning.
Industry Challenges
- IEC 60601-2-33 electromagnetic compatibility:Demonstrating safe operation of active infusion devices within fringe magnetic fields demands extensive testing protocols that strain engineering resources.
- ISO 13485 quality management scale-up:Transitioning from R&D-stage documentation to production-grade QMS for MRI-conditional hardware requires substantial organizational restructuring.
- Reimbursement code fragmentation:Image-guided infusion procedures lack standardized CPT and DRG classifications across United States payers, creating revenue recognition uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Guided Drug Delivery Market |
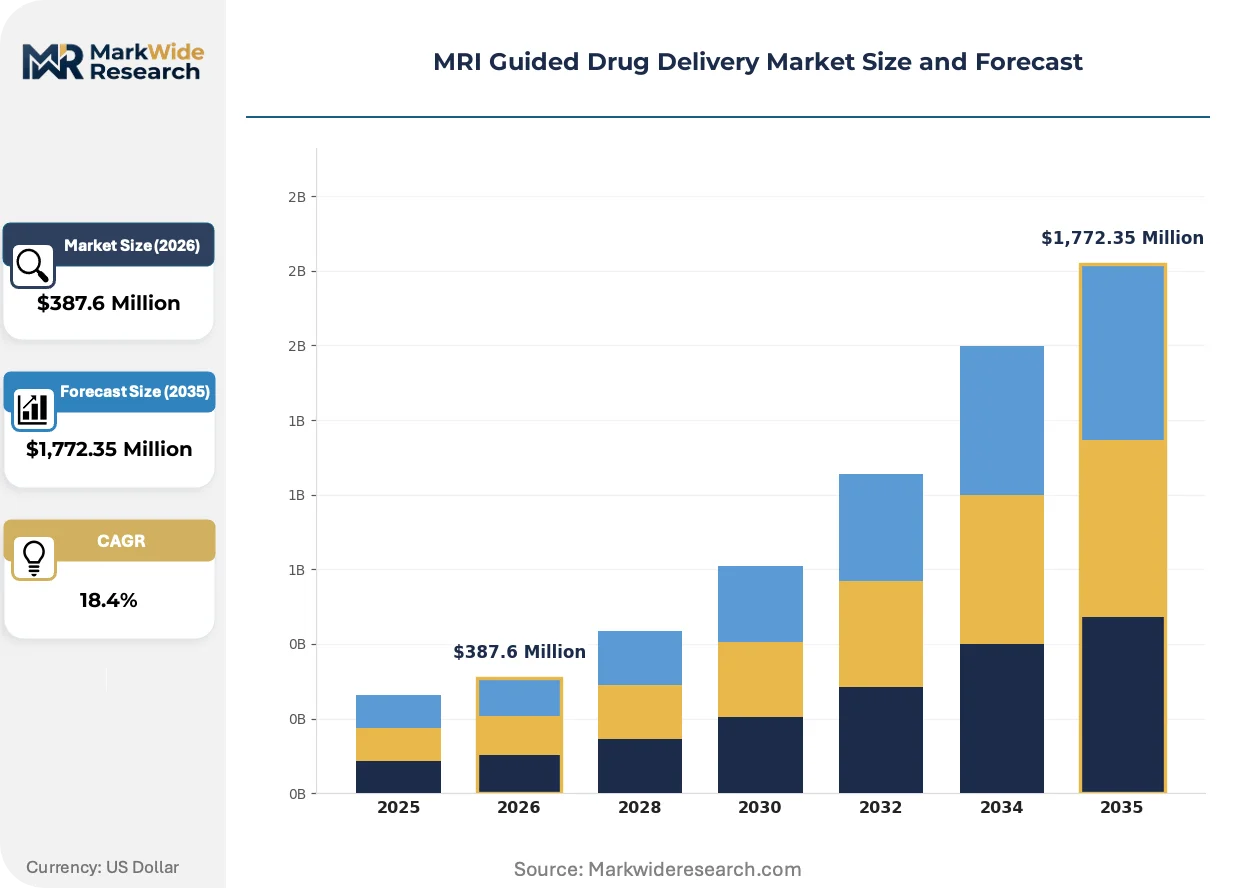
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Implantable, Nanoformulations, Microparticles Technology: Magnetic Resonance Imaging, Ultrasound, Electromagnetic, Thermal End User: Hospitals, Research Institutes, Specialty Clinics, Diagnostic Centers Application: Cancer Treatment, Pain Management, Neurological Disorders, Autoimmune Diseases |
| Companies Covered | Chongqing Haifu Medical Technology, Monteris, Medtronic, ClearPoint Neuro, GE HealthCare, Koninklijke Philips, Renishaw plc, TriSalus Life Sciences, RenovoRx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Guided Drug Delivery Market Evolving Landscape
Magnetic susceptibility-tuned nanoformulations are absorbing substantial R&D investment as developers engineer prolonged circulation profiles and enhanced target tissue accumulation for MRI-trackable therapeutics.
Iron oxide and gadolinium-based nanoparticle carriers are absorbing development priority from conventional liposomal formulations due to their intrinsic visibility on T1 and T2-weighted sequences. Academic medical centers and specialized neuro-oncology units are piloting these platforms in early-phase trials for glioblastoma multiforme. The technology is absorbing capital that previously flowed to external beam radiation sensitization, redirecting therapeutic focus toward locoregional chemotherapy delivery.
REACH restrictions on gadolinium-based contrast agents are compelling reformulation strategies across European development pipelines, with manufacturers exploring manganese and iron alternatives to reduce environmental persistence. The regulation forces substitution of established clinical materials with lower-ecotoxicity equivalents, elevating synthetic complexity. MRI-compatible drug delivery systems incorporating contrast-bearing nanoparticles face heightened scrutiny in EU environmental impact assessments, driving joint development agreements with specialty chemical suppliers.
Hospital procurement committees are consolidating vendor relationships for interventional MRI ecosystems, favoring integrated hardware-software-service contracts over point-solution acquisitions. This concentration disadvantages standalone infusion device manufacturers lacking imaging partnerships, compressing their addressable channel. The United States academic medical center segment exhibits the most pronounced consolidation, with three-source requirements giving way to single-vendor MRI suite standardization.
MRI Guided Drug Delivery Market Segmentation
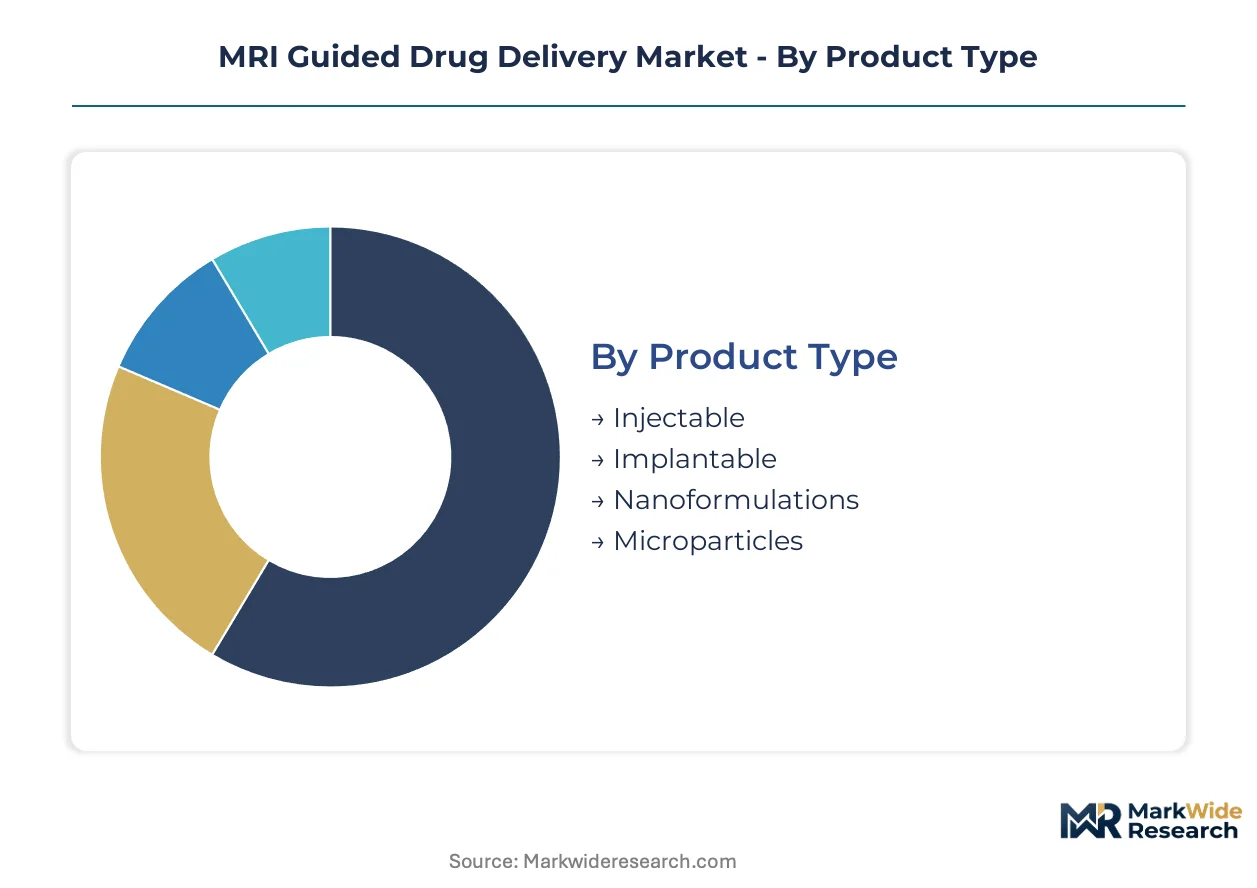
MRI guided drug delivery segments diverge sharply in regulatory pathway complexity and reimbursement velocity. Product type selection dictates clinical trial design, while technology choice determines compatibility with existing hospital infrastructure.
Product Type:
Replacement cycles vary from single-session injectables to multi-year implantable reservoirs, creating divergent revenue recognition patterns for manufacturers.
- Nanoformulations:Engineered carriers with magnetic susceptibility tuning enable real-time tracking on T1 and T2-weighted sequences. Demand concentrates in United States academic medical centers pursuing convection-enhanced delivery protocols, constrained by REACH environmental assessments for gadolinium-bearing particles in European markets.
- Implantable:MRI-conditional infusion pumps and reservoirs integrate with stereotactic navigation platforms for chronic CNS therapeutic administration. German neurosurgical departments anchor procurement volumes, driven by statutory health insurance coverage for intractable glioma interventions.
- Injectable:Bolus formulations designed for intraoperative MRI suite administration.
- Microparticles:Degradable polymer matrices for sustained local release.
Nanoformulations sit at the top of the volume ranking, with implantable systems climbing the fastest.
Technology:
Capital intensity and training requirements create distinct customer tiers across the four technical modalities.
- Magnetic Resonance Imaging:Direct visualization of therapeutic distribution with sub-millimeter spatial resolution enables closed-loop navigation. United States hospital systems with dedicated interventional MRI suites drive installed base expansion, though superconducting magnet supply bottlenecks constrain OEM delivery timelines.
- Thermal:MRI-compatible heating elements for triggered release applications. Japanese medical device manufacturers prioritize this modality under PMDA Sakigake designation pathways.
- Ultrasound:Focused acoustic energy for blood-brain barrier disruption.
- Electromagnetic:Field-responsive carrier activation for targeted payload release.
Magnetic Resonance Imaging dominates installed base, with thermal methods gaining share fastest.
End User:
Procurement authority and reimbursement sophistication separate the four customer categories.
- Hospitals:Integrated delivery ecosystems combining imaging hardware, navigation software, and infusion platforms. United States academic medical centers consolidate vendor relationships under single-source MRI suite contracts, compressing channel access for standalone device manufacturers.
- Specialty Clinics:Focused neuro-oncology and interventional radiology centers in Germany and Japan. These facilities prioritize portable MRI-compatible infusion systems with lower capital thresholds.
- Research Institutes:Early-phase clinical trial execution and device validation.
- Diagnostic Centers:Imaging-only facilities exploring therapeutic service line expansion.
Hospitals command the largest procurement volumes, with specialty clinics expanding most quickly.
Application:
Clinical evidence requirements and addressable patient populations vary substantially across therapeutic areas.
- Cancer Treatment:Locoregional chemotherapy for glioblastoma multiforme and metastatic CNS lesions generates dominant revenue share. FDA breakthrough device designation accelerates review timelines for intracranial delivery systems targeting intractable malignancies.
- Neurological Disorders:Blood-brain barrier penetration for enzyme replacement and gene therapy. Japanese PMDA prioritized review pathways attract developers addressing Parkinson's disease and rare lysosomal storage disorders.
- Pain Management:Intrathecal analgesic delivery with MRI verification.
- Autoimmune Diseases:Localized immunosuppression for CNS-limited manifestations.
Cancer Treatment leads absolute segment size, with Neurological Disorders showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional MRI suites first achieved clinical scale in the United States during the 1990s, with subsequent diffusion to German neurosurgical centers and Japanese university hospitals establishing the tripartite foundation of today's installed base.
United States
FDA breakthrough device designations accelerate premarket review for intracranial delivery systems targeting glioblastoma. Academic medical centers in Boston, Houston, and San Francisco consolidate vendor relationships under single-source MRI suite contracts. The National Cancer Institute's funding priorities favor locoregional chemotherapy protocols with real-time imaging verification.
Germany
Statutory health insurance coverage for intractable glioma interventions drives procurement volumes for implantable infusion reservoirs. EU MDR conformity assessment bottlenecks extend certification timelines for MRI-compatible hardware by 12-24 months. Heidelberg and Munich anchor the highest concentration of interventional neurosurgical facilities in Europe.
Japan
PMDA Sakigake designation offers expedited pathways for innovative drug-device combinations addressing CNS malignancies. Superconducting magnet manufacturing concentrates in Yokohama and Tokyo, exposing OEMs to input volatility from concentrated cryogenic component supply. University hospitals in Osaka and Nagoya pilot thermal-triggered release modalities under prioritized regulatory review.
Switzerland
Swissmedic maintains alignment with EU MDR requirements while offering streamlined procedures for innovative combination products. Basel and Zurich host specialized neuro-oncology units with dedicated intraoperative MRI capacity. Federal procurement frameworks favor integrated hardware-software-service contracts over standalone device acquisitions.
United Kingdom
NICE technology appraisals determine reimbursement eligibility for MRI-guided infusion procedures within the National Health Service. London and Cambridge concentrate early-phase clinical trial execution for nanoformulation platforms. MHRA post-Brexit regulatory autonomy permits divergence from EU MDR timelines, creating parallel assessment pathways.
MRI Guided Drug Delivery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and clinical evidence depth, with FDA breakthrough designations and EU MDR certifications separating pricing tiers. The vendor base clusters around three strategic archetypes: imaging hardware OEMs extending into therapy guidance, neurosurgical navigation specialists, and focused drug-device combination developers. M&A activity concentrates on navigation software assets and MRI-compatible infusion pump technologies. Strategic partnerships between contrast agent suppliers and device manufacturers accelerate nanoformulation scale-up.
Among imaging-dominant conglomerates, GE HealthCare and Koninklijke Philips occupy positions anchoring integrated therapy guidance ecosystems through hardware-software bundling. Medtronic exemplifies the neurosurgical navigation archetype, leveraging stereotactic positioning portfolios to anchor intracranial delivery positions. ClearPoint Neuro represents the focused combination-product developer, specializing in MRI-guided convection-enhanced platforms without competing imaging hardware exposure. These three patterns—imaging extension, navigation leverage, and therapeutic specialization—structure competitive positioning across procurement committees.
| Leading Market Players |
|---|
| Chongqing Haifu Medical Technology |
| Monteris |
| Medtronic |
| ClearPoint Neuro |
| GE HealthCare |
| Koninklijke Philips |
| Renishaw plc |
| TriSalus Life Sciences |
| RenovoRx |
| Others |
Value Network & Pricing Analysis
Liquid helium costs cascade through MRI-guided drug delivery hardware pricing tiers, with cryogenic input volatility from Japanese and United States superconducting magnet manufacturers compressing margins at the implantable pump tier while elevating premium positioning for integrated navigation suites.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated combination products from CE-marked hardware and non-certified research devices. Price differentiation hinges on ISO 13485 certification tier and bundled after-sales service coverage. Cost compression in the economy tier is intensifying because REACH environmental assessments are forcing gadolinium nanoformulation reformulation. Academic medical centers exhibit lowest price sensitivity; specialty clinics in Germany face highest budget constraints.
Supply Chain Analysis
Refurbishment flows for MRI-compatible infusion pumps concentrate in United States and German service depots, with remanufactured navigation platforms re-entering hospital procurement channels at 40-60% discount tiers. Superconducting magnet winding draws from Japan and United States cryogenic component suppliers, with iron oxide nanoparticle synthesis anchored in Switzerland and Netherlands specialty chemical facilities. Single-source vulnerability in liquid helium refining from Qatar and Algeria exposes OEM delivery timelines. Distribution runs through integrated hardware-software-service contracts rather than standalone device channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory milestones, with FDA breakthrough device designations and EU MDR certifications functioning as demand accelerators that lock in premium pricing tiers for compliant manufacturers.
For Market Incumbents: Anchor defensive positioning through backward integration into MRI-conditional pump manufacturing and captive navigation software development. GE HealthCare and Philips imaging ecosystems threaten standalone device manufacturers with bundled pricing pressure. Certification investment in ISO 13485 and IEC 60601-2-33 electromagnetic compliance secures procurement committee access against emerging entrants lacking established quality infrastructure. For New Entrants and Emerging Players: Capture white-space opportunity in pediatric oncology convection-enhanced delivery protocols and Japan PMDA Sakigake-designated thermal-triggered release modalities. Neurological disorder applications for blood-brain barrier penetration remain underpenetrated relative to cancer treatment saturation. Go-to-market execution should prioritize hospital system pilot partnerships over direct GPO channel competition. For Investors and Strategic Acquirers: Consolidation pressure builds where navigation software assets command valuation premiums exceeding hardware multiples. Long-term viability favors developers with FDA breakthrough designations in hand and EU MDR technical documentation files progressing through notified body review. Acquisition target archetype: MRI-compatible infusion pump specialists with stereotactic navigation integration capabilities. Monitor FDA breakthrough device announcement velocity and notified body capacity expansion as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses commercialization timelines for glioblastoma-targeting platforms. |
| EU MDR Technical Documentation | Notified body certification unlocks German statutory health insurance reimbursement pathways. |
| Hospital System Partnership | Single-source MRI suite contracts at United States academic medical centers displace standalone vendors. |
| Navigation Software Companion | Real-time therapeutic monitoring integration commands premium positioning in procurement evaluations. |
| Reimbursement Strategy | CPT and DRG code establishment determines revenue recognition certainty across United States payers. |
Research Methodology
Coverage spans United States, Germany, Japan, and Switzerland, with primary inputs from each market's hospital procurement ecosystem. The analysis combines structured interviews with neurosurgical department heads, biomedical engineers, GPO contracts managers, and regulatory affairs leads with secondary validation against FDA 510(k) and breakthrough device filings, EMA and PMDA submission databases, hospital procurement records, and ISO certification registries. Bottom-up demand modeling and top-down market sizing triangulate volume estimates.
Granularity-level modeling disaggregates the analysis window by product type, technology modality, end-user category, and application area, with regional regulatory cluster and reimbursement pathway status as cross-cutting dimensions. CAGRs derive from installed base expansion trajectories for interventional MRI suites and adoption curves for convection-enhanced delivery protocols. Forecast inputs incorporate superconducting magnet delivery timelines from Japanese and United States OEMs and notified body capacity constraints under EU MDR.
Underlying measurement precision varies by segment; nanoformulation and implantable pump categories carry tighter precision than emerging thermal and electromagnetic modalities due to more mature clinical trial visibility. Forecasts reflect assumptions about regulatory pathway velocity and reimbursement code finalization that could revise projections if FDA breakthrough designations stall or EU MDR notified body bottlenecks extend. Practitioners should monitor PMDA Sakigake designation announcements and United States academic medical center vendor consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Cochlear Implant Systems Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Global Smart Implants Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Body Contouring Devices and Procedures Market