
 Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market | 2026-2036
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market Foresight
CE marking under the EU Medical Device Regulation is reorganizing which manufacturers can serve Middle-East and Africa distribution channels, as Gulf Cooperation Authority countries reference European conformity for their own import approvals. Medtronic PLC leverages its integrated diagnostic-to-intervention portfolio to sustain presence across tertiary hospitals in Saudi Arabia and the UAE. Abbott Laboratories anchors its regional position through extensive training networks for electrophysiologists in Johannesburg and Cairo.
Cardiac arrhythmia monitoring devices are diagnostic and therapeutic instruments that detect, record, and transmit electrical activity abnormalities of the heart, typically operating through multi-lead electrode configurations sampling at 250–1000 Hz with real-time algorithmic analysis for beat classification. These systems serve primarily to reduce stroke risk through early detection of atrial fibrillation and to guide catheter ablation procedures by mapping arrhythmogenic substrates. Implantable monitors capture extended-term data streams that reveal episodic rhythm disturbances invisible to short-duration hospital testing, while wearable devices are gaining traction among home care programs seeking to lower readmission rates for post-ablation patients. Remote monitoring technology concentrates margin pools through recurring subscription revenues and technical service contracts tied to cloud-based diagnostic platforms.
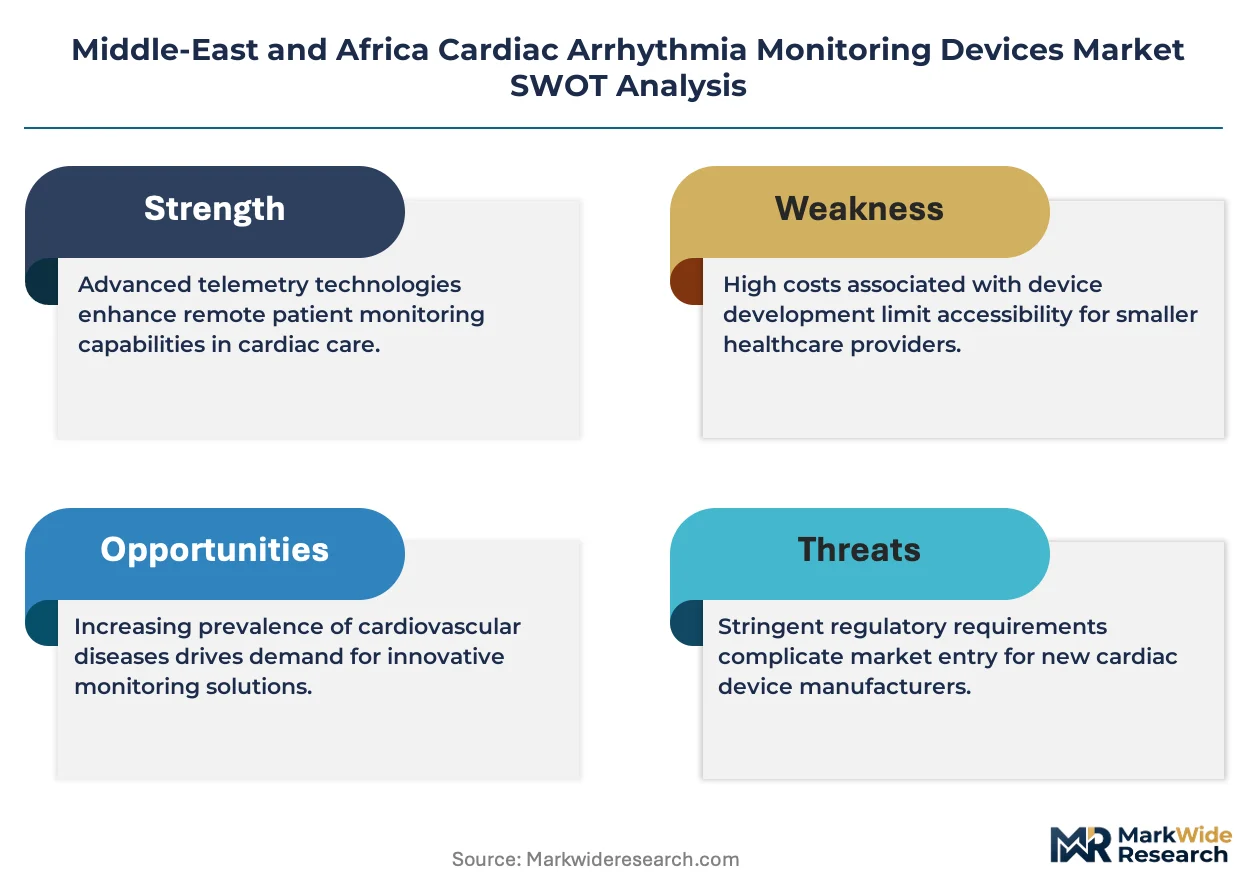
South Africa's Health Products Regulatory Authority and Saudi Arabia's SFDA enforce divergent registration pathways that fragment product launch timelines and inflate compliance costs for device manufacturers entering both markets. Egypt's drug authority and the UAE's Ministry of Health and Prevention have each introduced expedited review tracks for AI-enabled arrhythmia detection algorithms, reshaping competitive entry strategies. Stakeholders must weigh regulatory harmonization initiatives against the persistence of national labeling and clinical evidence requirements that continue to dictate commercial sequencing across the region.
Market Dynamics
CE marking reorganization under the EU Medical Device Regulation is restructuring which manufacturers can access Middle-East and Africa distribution channels, as Gulf Cooperation Authority countries reference European conformity for import approvals.
Growth Catalysts
- SFDA post-market surveillance mandates:Saudi Arabia's tightened oversight requirements for implantable cardiac devices are accelerating hospital investment in next-generation monitoring infrastructure.
- Ambulatory program expansion:Hospital cardiac units across South Africa are scaling remote monitoring programs to reduce readmission rates for post-ablation patients.
- AI-enabled detection algorithms:Egypt's drug authority and the UAE's Ministry of Health and Prevention have introduced expedited review tracks, compressing time-to-market for algorithmic diagnostics.
Market Restraints
- Input cost volatility:Semiconductor shortages and precious metal price swings in electrode manufacturing are squeezing margins on multi-lead configurations.
- Regulatory pathway fragmentation:South Africa's Health Products Regulatory Authority and Saudi Arabia's SFDA enforce divergent registration requirements, inflating compliance costs for dual-market entry.
- Technical limitation in signal fidelity:Wearable patch electrodes struggle with motion artifact rejection during patient activity, limiting diagnostic confidence outside controlled settings.
Strategic Opportunities
- Underpenetrated home care channels:Post-ablation patient monitoring in Egyptian and Nigerian urban centers remains underserved by formal remote monitoring programs.
- Regulatory tailwind from Dubai Health Authority:Mandatory arrhythmia screening in high-risk patient cohorts is creating guaranteed demand pools for diagnostic service providers.
- Technology convergence:Integration of cloud-based diagnostic platforms with implantable loop recorders is opening recurring subscription revenue streams independent of device sales cycles.
Industry Challenges
- Electrophysiologist training pipeline gaps:Cairo and Johannesburg training networks face capacity constraints as procedure volumes outpace specialist certification rates.
- Certification timeline compression:National labeling and clinical evidence requirements continue dictating commercial sequencing, delaying product launches despite harmonization initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market |
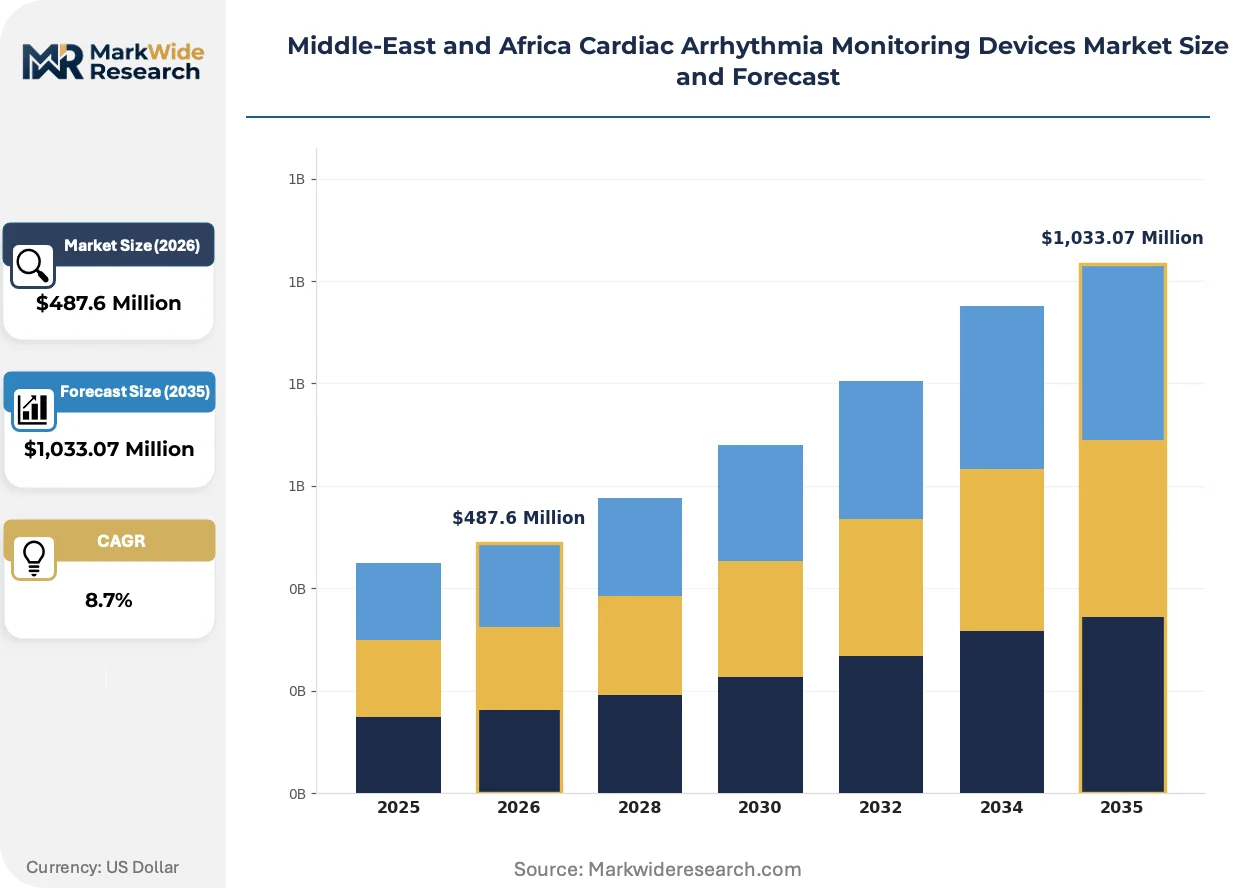
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Holter Monitors, Event Monitors, Implantable Monitors, Wearable Devices End User: Hospitals, Clinics, Home Care, Emergency Medical Services Technology: Electrocardiogram, Mobile Health, Remote Monitoring, Wireless Telemetry Application: Arrhythmia Diagnosis, Post-operative Monitoring, Patient Management, Clinical Research |
| Companies Covered | Nihon Kohden Corporation, BioTelemetry Inc., Cardiac Science Corporation, GE Healthcare, Abbott Laboratories, Medtronic PLC, Koninklijke Philips NV, Boston Scientific Corporation, Spacelabs Healthcare, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market Shifts & Advancements
Algorithmic diagnostic platforms are reconfiguring competitive advantage in cardiac arrhythmia monitoring, shifting value capture from hardware margins toward recurring data service revenues.
Machine learning-based beat classification is fragmenting the traditional division between hospital-grade and consumer-grade devices. Tertiary cardiac centers in Riyadh and Dubai are deploying FDA-cleared algorithms on wearable patches previously restricted to research use. This convergence is compressing price premiums on conventional Holter systems while expanding addressable patient populations.
Saudi Arabia's SFDA has aligned post-market surveillance timelines with EU MDR vigilance requirements, forcing manufacturers to maintain dual reporting systems. The regulation most affects implantable loop recorder suppliers, who must now submit periodic safety update reports across both jurisdictions. Device sponsors are responding by consolidating regulatory affairs functions in regional hubs serving both European and Gulf markets.
Service unbundling is separating technical support contracts from hardware procurement in UAE hospital tenders. Procurement teams at Dubai Health Authority-affiliated facilities now evaluate cloud platform uptime guarantees independently from electrode performance specifications. This bifurcation is most visible among tertiary hospitals managing large post-ablation cohorts, where diagnostic data continuity outweighs upfront capital cost considerations.
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market Segmentation
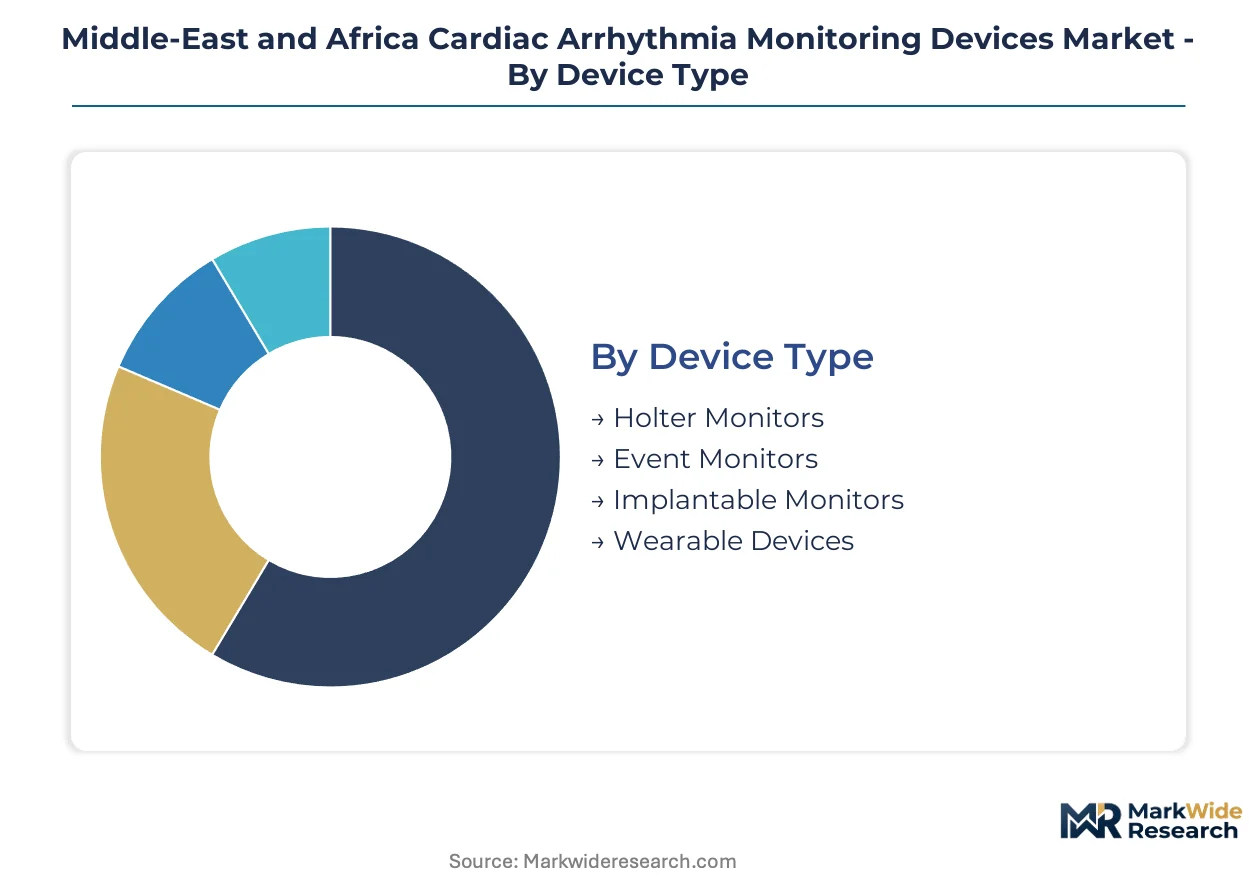
Cardiac arrhythmia monitoring devices fragment across four intersecting dimensions that determine procurement patterns across Middle-East and Africa healthcare systems. Device type and end-user channels dominate commercial strategy, while technology and application segments dictate regulatory pathways and reimbursement structures.
Device Type:
Implantable monitors and wearable devices concentrate demand in Gulf Cooperation Authority import channels, while Holter and event monitors retain stronger domestic distribution networks across South Africa and Egypt.
- Holter Monitors:Multi-lead electrode systems sampling at 250–1000 Hz for 24–48 hour continuous recording. Demand clusters in South African hospital cardiac units expanding ambulatory programs, constrained by semiconductor shortages in signal processing components.
- Implantable Monitors:Subcutaneous loop recorders capturing extended-term episodic rhythm data invisible to short-duration testing. Saudi Arabia's SFDA tightened post-market surveillance mandates are accelerating hospital investment in next-generation implantable infrastructure.
- Event Monitors:Patient-activated or auto-triggered devices for symptomatic episodes.
- Wearable Devices:Patch electrodes and consumer-grade monitors with algorithmic beat classification.
Implantable monitors command the established base. The steepest expansion runs through wearable devices.
End User:
Cost tier stratification separates capital-intensive hospital installations from subscription-based home care models, with emergency medical services occupying a distinct procurement band.
- Hospitals:Tertiary cardiac centers in Riyadh and Dubai deploying FDA-cleared algorithms on wearable patches. Dubai Health Authority mandates arrhythmia screening in high-risk patient cohorts, creating guaranteed demand pools for diagnostic service providers.
- Home Care:Remote monitoring programs for post-ablation patients seeking readmission reduction. Egyptian and Nigerian urban centers remain underserved by formal programs, presenting channel development opportunities.
- Clinics:Outpatient facilities with limited electrophysiology support.
- Emergency Medical Services:Pre-hospital diagnostic applications with ruggedized hardware requirements.
Hospitals absorb the majority of capital expenditure. Home care channels are climbing the fastest.
Technology:
Volume concentration favors electrocardiogram hardware, while margin pools shift toward cloud-based remote monitoring platforms with recurring subscription structures.
- Remote Monitoring:Cloud-based diagnostic platforms transmitting data from implantable or wearable devices to centralized analysis centers. UAE hospital tenders now evaluate platform uptime guarantees independently from electrode specifications.
- Mobile Health:Smartphone-integrated applications with AI-enabled arrhythmia detection. Egypt's drug authority and UAE's Ministry of Health and Prevention introduced expedited review tracks, compressing algorithmic diagnostic time-to-market.
- Electrocardiogram:Conventional 12-lead and reduced-lead configurations for standardized clinical assessment.
- Wireless Telemetry:Real-time transmission systems for inpatient continuous monitoring.
Electrocardiogram systems retain the installed base. Mobile health platforms are gaining share fastest.
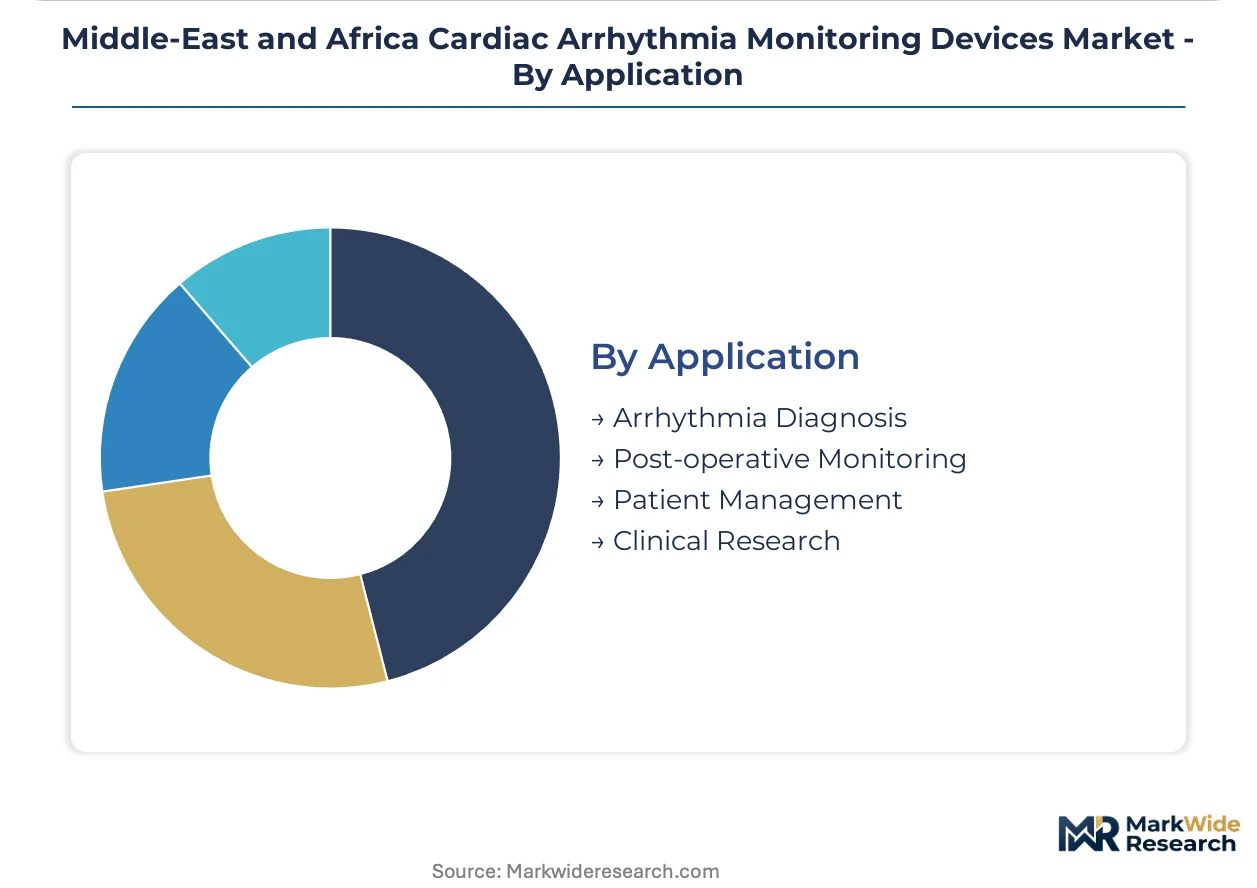
Application:
Maturity gradients separate established arrhythmia diagnosis from emerging patient management applications, with post-operative monitoring occupying a transitional technology position.
- Arrhythmia Diagnosis:Primary detection of atrial fibrillation and other rhythm disturbances for stroke risk reduction. SFDA post-market surveillance alignment with EU MDR vigilance requirements forces dual reporting systems on device sponsors.
- Post-operative Monitoring:Surveillance following catheter ablation procedures to detect recurrence. South African hospital cardiac units scale remote monitoring programs specifically for this cohort.
- Patient Management:Long-term rhythm surveillance with integrated care coordination.
- Clinical Research:Investigational device applications and algorithm validation studies.
Arrhythmia diagnosis anchors current revenue. Patient management applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mandatory arrhythmia screening protocols and tightened post-market surveillance requirements are redirecting procurement budgets toward next-generation monitoring infrastructure across Middle-East and Africa healthcare systems.
Saudi Arabia
Tertiary cardiac centers in Riyadh are scaling remote monitoring programs for post-ablation patients. The Saudi Food and Drug Authority has aligned implantable device surveillance timelines with EU MDR vigilance requirements, forcing dual reporting systems on manufacturers. King Faisal Specialist Hospital anchors demand concentration in the capital region.
United Arab Emirates
Dubai Health Authority mandates arrhythmia screening in high-risk patient cohorts, creating guaranteed demand pools for diagnostic service providers. The Ministry of Health and Prevention introduced expedited review tracks for AI-enabled detection algorithms, compressing algorithmic diagnostic time-to-market. Procurement teams at DHA-affiliated facilities now evaluate cloud platform uptime independently from hardware specifications.
South Africa
Hospital cardiac units across Johannesburg and Cape Town are expanding ambulatory monitoring programs to reduce readmission rates. The Health Products Regulatory Authority enforces registration pathways divergent from Gulf Cooperation Authority standards, inflating compliance costs for dual-market entry. Training networks for electrophysiologists face capacity constraints as procedure volumes outpace specialist certification rates.
Egypt
Urban centers in Cairo and Alexandria remain underserved by formal remote monitoring programs for post-ablation patients. The national drug authority introduced expedited review tracks for AI-enabled arrhythmia detection algorithms, reshaping competitive entry strategies. Egyptian tertiary hospitals concentrate procurement of wearable patch devices with algorithmic beat classification.
Israel
Cardiac centers in Tel Aviv and Haifa deploy FDA-cleared algorithms on wearable patches previously restricted to research use. The national medical device regulator maintains alignment with CE marking standards referenced by Gulf import channels. Algorithmic diagnostic platforms from Israeli developers are penetrating UAE and Saudi distribution networks.
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and cloud platform development in the Middle-East and Africa cardiac arrhythmia monitoring devices market. The vendor base fragments across integrated diagnostic-to-intervention portfolios, algorithmic software specialists, and hardware-focused electrode manufacturers. Three archetypes dominate: multinational conglomerates with full-stack capabilities, mid-cap regional distributors with regulatory expertise, and AI-native software vendors with algorithmic differentiation. Competitive moves concentrate on M&A for algorithmic capabilities and strategic partnerships for cloud infrastructure.
Within the multinational tier, Medtronic PLC and Abbott Laboratories exemplify integrated portfolio positioning across tertiary hospitals in Saudi Arabia and the UAE. Nihon Kohden Corporation anchors the hardware-specialist archetype with concentration in South African and Egyptian distribution channels. These three listed entities represent divergent strategic vectors: algorithmic platform development, electrophysiologist training network expansion, and signal processing hardware refinement.
| Leading Market Players |
|---|
| Nihon Kohden Corporation |
| BioTelemetry Inc. |
| Cardiac Science Corporation |
| GE Healthcare |
| Abbott Laboratories |
| Medtronic PLC |
| Koninklijke Philips NV |
| Boston Scientific Corporation |
| Spacelabs Healthcare |
| Others |
Supply & Pricing Matrix
Manufacturing scale economies in semiconductor fabrication and electrode production concentrate cost advantages among suppliers with dedicated cleanroom capacity and precious-metal forward contracts, compressing price floors for mid-tier Holter systems while elevating margins on implantable loop recorders with extended data service bundling.
Pricing Analysis
Certification level (CE marking under EU MDR, FDA 510(k) clearance, or SFDA registration) creates the primary spread between premium implantable monitors and economy-grade wearable patches. Subscription-based SaaS pricing for cloud diagnostic platforms now dominates tertiary hospital procurement in the UAE and Saudi Arabia, displacing per-unit transactional models. Pricing pressure stems from semiconductor input cost volatility and precious metal price swings in electrode manufacturing, squeezing margins on multi-lead configurations. Public hospital procurement committees in South Africa exhibit the highest price sensitivity, while private cardiac centers in Dubai demonstrate willingness to pay premiums for platform uptime guarantees.
Supply Chain Analysis
Container availability constraints on Asia-Middle East trade lanes and port congestion at Jebel Ali and Durban are extending inbound logistics timelines for semiconductor components and disposable electrode materials. Component sourcing concentrates in Taiwan and South Korea for signal processing chips, with precious metal electrodes drawing from South African platinum group metal refineries and Chinese manufacturing. Single-source vulnerability in advanced ASIC fabrication for algorithmic beat classification creates supply chain risk. Distribution runs through Gulf Cooperation Authority import channels referencing CE marking standards, with South Africa maintaining divergent domestic distribution networks for Holter and event monitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa cardiac arrhythmia monitoring devices market is recovering from cyclical compression in capital equipment procurement, with hospital infrastructure investment cycles now turning upward following post-pandemic budget restorations and SFDA surveillance mandate compliance deadlines.
For Market Incumbents: Shield installed base positions in Saudi tertiary hospitals by deepening algorithmic platform integration and securing multi-year technical service contracts independent of hardware refresh cycles. Accelerate backward integration into cloud infrastructure to reduce dependency on third-party platform providers facing data sovereignty restrictions. Counter emerging AI-native software vendors by embedding FDA-cleared algorithms directly into implantable loop recorder firmware. For New Entrants and Emerging Players: Post-ablation remote monitoring service gaps in Egyptian and Nigerian urban centers offer white-space entry points with lower competitive density than Gulf Cooperation Authority markets. Target home care channel development through smartphone-integrated wearable patches with expedited regulatory pathways under UAE Ministry of Health and Prevention AI-enabled algorithm tracks. Pursue strategic partnerships with regional distributors possessing established SFDA registration expertise to compress time-to-revenue. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among algorithmic diagnostic platform developers with hospital system integration contracts and cloud-based subscription structures. Long-term viability favors acquisition targets combining hardware manufacturing scale with software service capabilities, particularly those positioned for Dubai Health Authority mandatory screening program procurement. Monitor SFDA-EU MDR vigilance alignment implementation as an inflection indicator for regulatory compliance cost consolidation among mid-tier device sponsors.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment unlocks Gulf Cooperation Authority import channels for implantable monitors. |
| Hospital System Partnership | Dubai Health Authority-affiliated facilities prioritize integrated platform uptime over capital cost in tender evaluations. |
| Software Companion Development | AI-enabled arrhythmia detection algorithms qualify for expedited review tracks in Egypt and UAE regulatory frameworks. |
| Reimbursement Strategy | Mandatory screening mandates in high-risk patient cohorts create guaranteed demand pools for diagnostic service providers. |
| SFDA Registration Investment | Post-market surveillance alignment with EU MDR forces dual reporting systems, favoring sponsors with regional regulatory hubs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrophysiologists at King Faisal Specialist Hospital and Dubai Health Authority facilities, biomedical engineers managing implantable device programs, hospital procurement committee members, and regulatory affairs specialists navigating SFDA and Health Products Regulatory Authority pathways. Secondary validation drew from SFDA vigilance guidance documents, EU MDR technical documentation requirements, hospital procurement databases, and GPO contract disclosures. Bottom-up device shipment estimates and top-down healthcare expenditure allocations were triangulated to anchor volume and value outputs.
Across the analysis window, the forecast framework models expansion trajectories through device type segmentation (implantable monitors, wearable patches, Holter systems, event monitors), end-user channel stratification (hospitals, home care, clinics, emergency medical services), technology tier differentiation (remote monitoring platforms, mobile health applications, conventional electrocardiogram hardware), and application purpose (arrhythmia diagnosis, post-operative monitoring, patient management, clinical research). CAGRs were derived from fitted growth curves incorporating SFDA surveillance mandate implementation timelines, Dubai Health Authority screening protocol rollouts, and algorithmic diagnostic platform adoption rates.
Forecasts assume regulatory continuity in Saudi SFDA and UAE Ministry of Health and Prevention frameworks; material policy shifts in AI-enabled device classification or post-market surveillance timelines would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Tester Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Rapid Infuser Market
Medical Devices
United Kingdom Respiratory Devices Market
Medical Devices
Trocars Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Global Ventilators Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Bone Growth Stimulators Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Transcutaneous Oximetry Systems Market