
 Acute External Ventricular Drain Market | 2026-2036
Acute External Ventricular Drain Market Size, Share, and Industry Trends Forecast 2026-2036
Acute External Ventricular Drain Market Intelligence
Hospital procurement of acute external ventricular drain systems is consolidating as neurosurgical departments centralize purchasing authority under integrated delivery networks. Medtronic leverages its broad neurosurgery portfolio to sustain contract visibility across major academic medical centers. Integra LifeSciences anchors its position through specialized cranial access and cerebrospinal fluid management portfolios. Sophysa competes in programmable drain technology with differentiated pressure-regulation capabilities.
An acute external ventricular drain is a sterile, catheter-based system inserted through the skull into the lateral ventricle to monitor intracranial pressure and divert cerebrospinal fluid, typically constructed from radiopaque silicone or polyurethane tubing with graduated pressure manometers or electronic transducers. The device serves primarily as a temporary bridge in traumatic brain injury, hydrocephalus, and intracranial hemorrhage management until definitive treatment or spontaneous resolution occurs. Standard drains occupy the highest procedure volume due to lower unit cost and established clinical familiarity, while programmable drains capture expanding preference in tertiary centers seeking titratable pressure control. Application demand clusters around traumatic brain injury and intracranial hemorrhage where emergency intervention protocols drive rapid deployment.
FDA Class II 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access barriers for manufacturers. Japan's PMDA and METI enforce stringent biocompatibility and sterilization validation standards that filter out lower-capability suppliers. Stakeholders must monitor evolving neurocritical care bundling arrangements and reimbursement shifts that increasingly tie device selection to total episode cost outcomes.
Market Dynamics
Hospital procurement consolidation under integrated delivery networks is compressing vendor access and forcing manufacturers to restructure their commercial operations around multi-year enterprise contracts rather than individual department sales.
Growth Catalysts
- EU MDR technical documentation requirements:Stricter quality benchmarks are filtering out marginal suppliers and expanding market share for established manufacturers with robust regulatory affairs capabilities.
- Traumatic brain injury emergency protocols:Standardized neurocritical care pathways in tertiary centers are mandating rapid EVD deployment, embedding device demand into clinical workflow.
- Radiopaque silicone tubing:Enhanced material visibility under fluoroscopy is reducing placement complications and driving replacement cycles in high-volume centers.
Market Restraints
- Biocompatibility validation costs:PMDA and METI sterilization standards in Japan impose multi-year testing timelines that deter market entry.
- Single-source polymer supply:Medical-grade silicone concentrate production in Germany creates geographic concentration risk for tubing manufacturers.
- Catheter occlusion rates:Fibrin deposition and cellular debris accumulation limit functional device lifespan and drive unplanned replacement costs.
Strategic Opportunities
- Programmable pressure-regulation convergence:Integration of electronic transducers with wireless telemetry is enabling remote ICP monitoring and reducing bedside intervention frequency.
- India neurocritical care expansion:CDSCO regulatory harmonization and private hospital infrastructure investment are opening access corridors for premium drain systems.
- Outcome-based bundling:Medicare's total episode payment models are aligning device selection with length-of-stay reduction incentives.
Industry Challenges
- Neurosurgical specialist scarcity:Fellowship-trained ventriculostomy practitioners concentrate at academic medical centers, limiting procedural volume expansion.
- FDA 510(k) predicate device drift:Evolving substantial equivalence standards are extending clearance timelines for next-generation pressure-sensing catheters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute External Ventricular Drain Market |
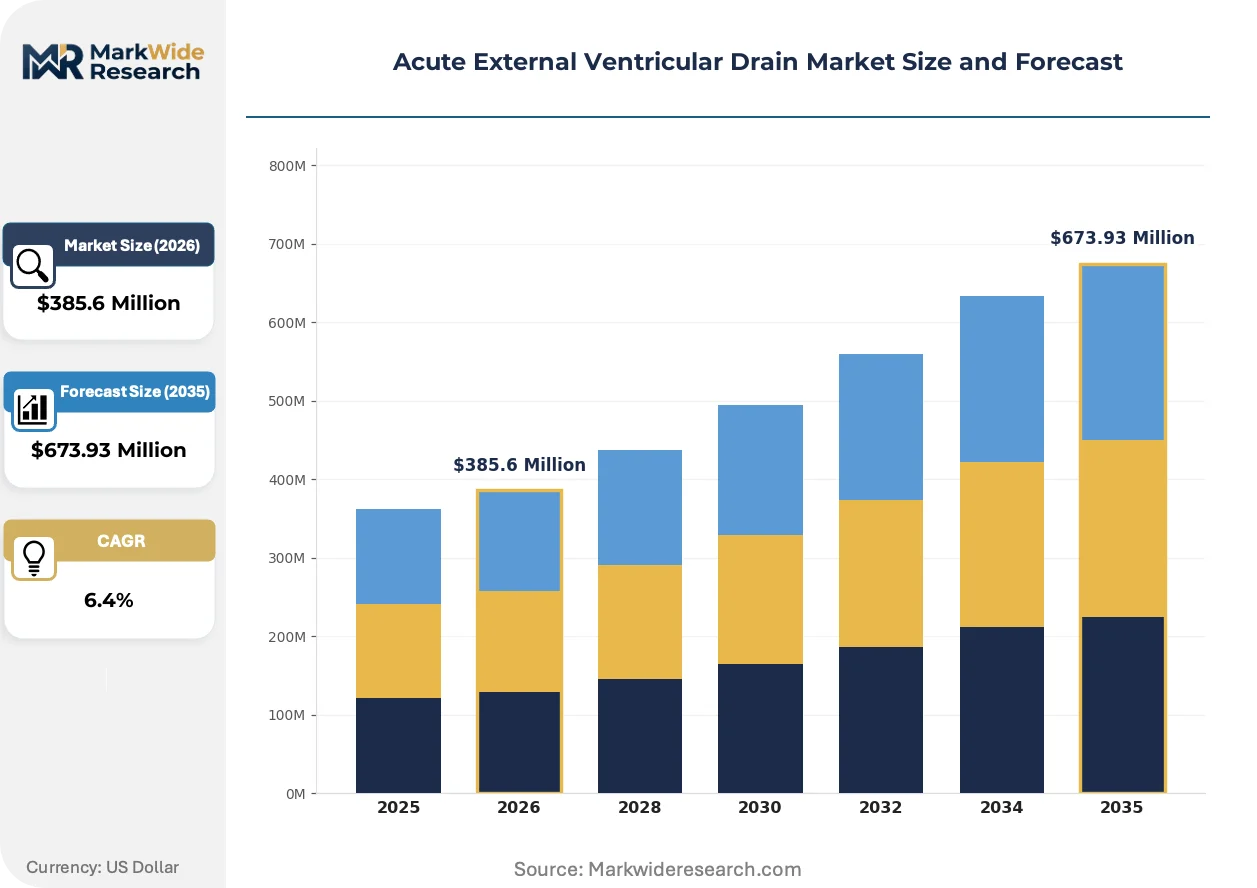
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Drains, Programmable Drains, Pressure Sensors, Flow Monitors End User: Hospitals, Clinics, Emergency Departments, Specialty Centers Application: Traumatic Brain Injury, Hydrocephalus, Intracranial Hemorrhage, Neurological Disorders Delivery Mode: Invasive Procedure, Outpatient Procedure, Emergency Intervention, Elective Surgery |
| Companies Covered | Medtronic, Integra LifeSciences, Sophysa, Spiegelberg GmbH & Co. KG, Natus Medical Incorporated, Neuromedex GmbH, Fuji Systems, Möller Medical, B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute External Ventricular Drain Market Strategic Shifts & Innovations
Electronic pressure monitoring is displacing mechanical manometry across tertiary neurocritical care units, while wireless connectivity architectures are enabling remote surveillance models that alter staffing and capital deployment patterns.
Closed-loop intracranial pressure management systems incorporating automated cerebrospinal fluid diversion are consolidating clinical workflow around integrated monitoring-treatment platforms. Academic medical centers in the United States and Germany are piloting these systems to reduce nursing burden and improve pressure control precision. The technology is consolidating vendor relationships by bundling transducer hardware with algorithmic control software under single-source contracts.
Japan's PMDA has tightened biocompatibility and sterilization validation requirements for intracranial devices, extending technical documentation obligations and filtering out lower-capability suppliers. Manufacturers must now demonstrate endotoxin limits and particulate contamination controls beyond prior standards. Programmable drain categories face the steepest compliance burden, advantaging incumbents with established quality management systems.
Integrated delivery networks are consolidating neurosurgical procurement authority and mandating standardized device formularies across member hospitals. Traditional distributor relationships are compressing as IDNs negotiate direct manufacturer agreements with price transparency and volume commitment provisions. This restructuring is most visible in United States metropolitan markets where health system consolidation has advanced furthest.
Acute External Ventricular Drain Market Segmentation
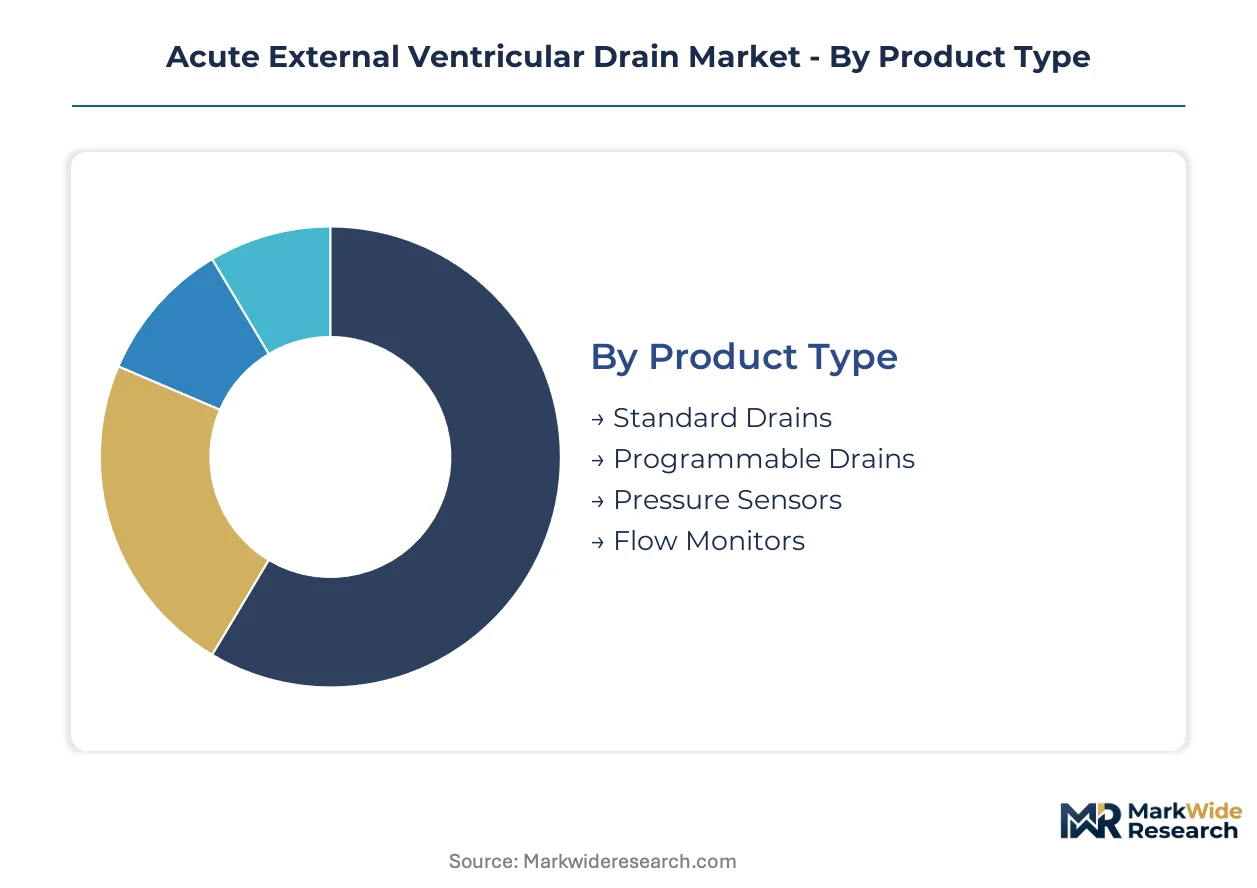
Device configuration determines whether acute external ventricular drains operate as standalone catheter systems or integrate with broader neurocritical care platforms. Procurement patterns diverge sharply across these boundaries, with embedded systems commanding enterprise contracts and standalone units facing commoditization pressure.
Product Type:
Integration depth separates catheter-only systems from sensor-embedded platforms, with programmable variants anchoring the convergence trajectory toward closed-loop neurocritical care architectures.
- Standard Drains:Radiopaque silicone or polyurethane tubing with passive gravity-dependent drainage and graduated pressure manometers. Demand clusters in United States community hospitals and German regional medical centers where cost containment dominates procurement criteria and established clinical familiarity reduces training overhead.
- Programmable Drains:Catheter systems incorporating electronic pressure transducers with titratable valve mechanisms for precise intracranial pressure regulation. Tertiary neurocritical care units in Japan and academic medical centers in Germany are consolidating purchasing around these systems to enable protocol-driven cerebrospinal fluid diversion and reduce nursing intervention frequency.
- Pressure Sensors:Miniaturized strain-gauge or fiber-optic transducers designed for intraventricular placement alongside drainage catheters.
- Flow Monitors:Inline volumetric measurement devices tracking cerebrospinal fluid output rates and cumulative drainage volumes.
Volume placements concentrate in Standard Drains; the faster expansion belongs to Programmable Drains.
End User:
Care setting intensity shapes device specification requirements, with high-acuity environments demanding programmable capabilities and lower-acuity sites prioritizing cost-efficient standard configurations.
- Hospitals:Inpatient facilities with dedicated neurosurgical departments and neurocritical care units. United States academic medical centers and Japanese tertiary hospitals are centralizing ventriculostomy volume and driving enterprise contract consolidation for integrated drain-monitoring platforms.
- Emergency Departments:Frontline trauma receiving centers where rapid EVD deployment protocols mandate immediate device availability. United States Level I trauma centers in metropolitan markets are embedding drain placement into standardized traumatic brain injury pathways, creating demand for pre-positioned standard drain inventory.
- Clinics:Outpatient neurological practices managing chronic hydrocephalus shunt surveillance and elective cerebrospinal fluid sampling.
- Specialty Centers:Dedicated neurosurgical or neurocritical care facilities with concentrated procedure volume and specialized nursing staff.
Procedure volume aggregates at Hospitals; Specialty Centers are climbing the fastest as neurocritical care service lines unbundle from general acute care.
Application:
Clinical indication severity dictates device selection urgency and monitoring sophistication, with emergent pathologies requiring immediate invasive intervention and chronic conditions permitting elective system placement.
- Traumatic Brain Injury:Acute intracranial hypertension management following blunt or penetrating head trauma. United States trauma centers and German emergency medical networks are embedding EVD protocols into standardized neurocritical care bundles, embedding device demand into reimbursement-aligned clinical workflows.
- Intracranial Hemorrhage:Cerebrospinal fluid diversion for intraventricular or subarachnoid blood evacuation. Japanese stroke centers are expanding EVD deployment for spontaneous hemorrhage management, with PMDA quality benchmarks filtering device selection toward established manufacturers.
- Hydrocephalus:Temporary cerebrospinal fluid diversion pending definitive shunt placement or spontaneous resolution.
- Neurological Disorders:Diagnostic intracranial pressure monitoring and therapeutic drainage for idiopathic intracranial hypertension and infectious meningitis complications.
Device utilization peaks in Traumatic Brain Injury; Intracranial Hemorrhage applications are gaining share fastest as hemorrhagic stroke protocols expand across developed neurocritical care networks.
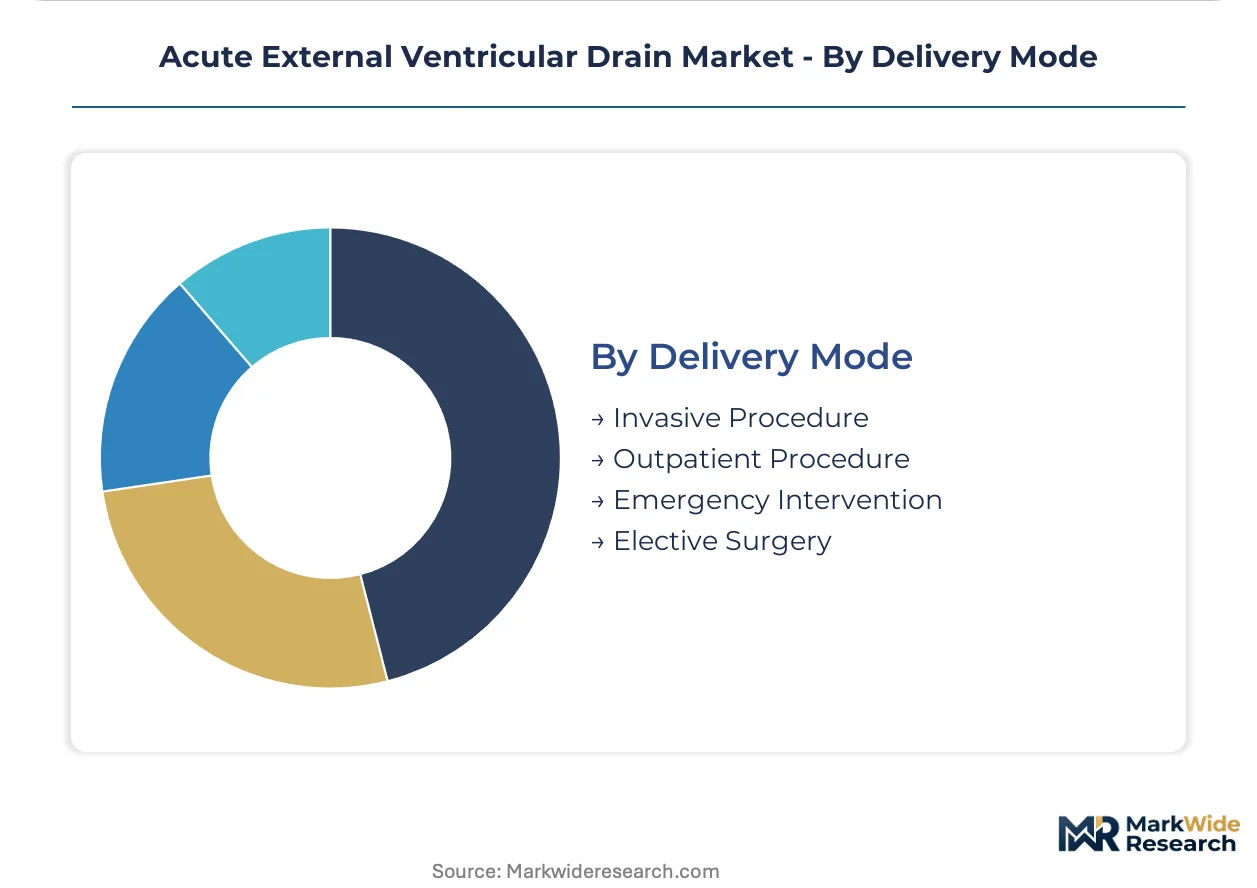
Delivery Mode:
Procedure acuity determines setting-of-care allocation and device configuration requirements, with emergent interventions demanding immediate availability and elective procedures permitting customized system selection.
- Invasive Procedure:Surgical ventriculostomy with catheter placement in operating room or intensive care unit settings. Academic medical centers in the United States and Germany are concentrating this volume within neurosurgical specialist teams, limiting expansion to fellowship-trained practitioner availability.
- Emergency Intervention:Bedside or trauma bay EVD placement under urgent indications without operating room transfer. United States Level I trauma centers are piloting rapid-deployment standard drain kits to compress time-to-treatment metrics for severe traumatic brain injury.
- Outpatient Procedure:Elective ventricular access for diagnostic pressure monitoring or therapeutic tap in ambulatory surgical settings.
- Elective Surgery:Scheduled ventriculostomy with preoperative planning and device specification optimization.
Procedure volume concentrates in Invasive Procedure; Emergency Intervention is expanding most quickly as pre-hospital triage protocols accelerate neurocritical care access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurocritical care infrastructure concentrates device demand in tertiary hospital clusters across the United States, Germany, and Japan, with procurement authority consolidating under integrated delivery networks and academic medical center systems.
United States
Level I trauma centers and academic medical centers drive standard and programmable drain procurement through enterprise contracting with integrated delivery networks. FDA Class II 510(k) clearance requirements filter market access toward established manufacturers with robust regulatory affairs capabilities. The Boston-Cambridge corridor and Baltimore-Washington corridor host concentrated neurosurgical research activity that pilots closed-loop pressure management systems.
Germany
Regional medical centers and university hospitals anchor demand for radiopaque silicone tubing systems amid EU MDR technical documentation obligations. The country's national pharmaceutical and medical device regulator enforces stringent biocompatibility validation standards that extend product development timelines. The Rhine-Ruhr metropolitan region and Munich cluster concentrate neurosurgical procedure volume and specialized nursing expertise.
Japan
Tertiary stroke centers and emergency medical networks expand EVD deployment for intracranial hemorrhage management under PMDA and METI sterilization standards. Multi-year endotoxin and particulate contamination testing filters lower-capability suppliers from market participation. The Kanto region surrounding Tokyo and the Kansai region centered on Osaka concentrate neurocritical care infrastructure and fellowship-trained practitioner availability.
United Kingdom
NHS neurosurgical units and major trauma centers standardize drain procurement through national framework agreements that emphasize cost containment alongside clinical outcomes. The Medicines and Healthcare products Regulatory Agency aligns device approval pathways with EU MDR convergence timelines. The Greater London area and Greater Manchester corridor concentrate specialized neurocritical care beds and ventriculostomy procedure volume.
India
Private hospital chains and emerging neurocritical care service lines create demand corridors for premium drain systems as CDSCO regulatory harmonization accelerates. Central government production-linked incentive schemes and medical device park investments reduce import dependency for catheter components. The Mumbai-Pune corridor and Bengaluru metropolitan area concentrate corporate hospital infrastructure and specialized neurosurgical training programs.
Acute External Ventricular Drain Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue sensor-embedded and wireless telemetry architectures. The vendor base stratifies across three tiers: diversified medical technology conglomerates with neurosurgery portfolios, specialized cranial access and cerebrospinal fluid management firms, and regional fabricators serving price-sensitive procurement channels. Dominant competitive moves include enterprise contract consolidation with integrated delivery networks and algorithmic control software licensing to anchor closed-loop system relationships.
Among diversified medical technology conglomerates, Medtronic leverages broad neurosurgery portfolio visibility across major academic medical centers. Integra LifeSciences anchors market position through specialized cranial access expertise. Sophysa occupies the programmable drain segment with differentiated pressure-regulation capabilities. These three exemplify contrasting archetypes: portfolio breadth, segment specialization, and technology-led differentiation respectively.
| Leading Market Players |
|---|
| Medtronic |
| Integra LifeSciences |
| Sophysa |
| Spiegelberg GmbH & Co. KG |
| Natus Medical Incorporated |
| Neuromedex GmbH |
| Fuji Systems |
| Möller Medical |
| B. Braun SE |
| Others |
Cost & Logistics Intelligence
Hospital procurement consolidation under integrated delivery networks is forcing manufacturers to absorb certification and validation costs while maintaining price competitiveness across standard and programmable drain tiers. This demand-side pressure compresses margins for catheter-only suppliers while rewarding sensor-embedded platform vendors with multi-year enterprise contract security.
Pricing Analysis
Volume placements cluster in standard drains where per-unit transactional pricing dominates community hospital procurement, while programmable systems command premium positioning through value-based contracts tied to length-of-stay outcomes. Price differentiation hinges on FDA 510(k) clearance tier and radiopaque material grade, with tertiary centers showing lowest price sensitivity due to bundled reimbursement alignment. Cost compression in the standard tier intensifies as German and Japanese regulators extend biocompatibility testing timelines, forcing smaller fabricators toward private-label supply arrangements.
Supply Chain Analysis
Dual-sourcing requirements from United States academic medical centers and Japanese tertiary stroke centers mandate multi-supplier qualification for medical-grade silicone tubing, preventing single-source dependency despite production concentration in Germany and the United States. Raw material supply draws from specialized polymer concentrate manufacturers, electronic transducer foundries in Japan, and sterilization validation facilities certified to PMDA endotoxin standards. Single-source vulnerability persists around fiber-optic pressure sensing components. Distribution runs through integrated delivery network direct contracts and specialized neurosurgical distributors serving regional medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic pressure transducers with wireless telemetry architectures are displacing mechanical manometry across tertiary neurocritical care units, creating a technology-transition window where algorithmic control software determines vendor stickiness.
For Market Incumbents: Deploy algorithmic control software licensing to anchor closed-loop system relationships before programmable drain commoditization accelerates. Backward integration into medical-grade silicone compounding secures supply continuity against German polymer concentrate bottlenecks. Counter emerging sensor-embedded entrants by accelerating EU MDR technical documentation completion to filter competitor market access. For New Entrants and Emerging Players: Enter via CDSCO regulatory harmonization corridors into Indian private hospital chains where neurocritical care infrastructure investment outpaces established vendor relationships. Target emergency intervention protocols at United States Level I trauma centers with rapid-deployment standard drain kits optimized for pre-positioned inventory models. Pursue white-label manufacturing partnerships with regional fabricators to bypass multi-year PMDA sterilization validation timelines. For Investors and Strategic Acquirers: The window for entry favors sensor-embedded platform specialists with wireless telemetry capabilities and existing FDA 510(k) predicates. Long-term viability rests on consolidation of hardware-software bundles under single-source hospital contracts. Monitor PMDA biocompatency guideline revisions as inflection indicator for Japanese market access barriers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance under Class II substantial equivalence standards unlocks United States academic medical center procurement. |
| CE Marking Pathway | EU MDR technical documentation completion filters competitor access across German and United Kingdom hospital systems. |
| Hospital System Partnership | Enterprise contracts with integrated delivery networks compress distributor margins and secure multi-year volume commitments. |
| Software Companion Development | Algorithmic control platforms for closed-loop pressure management consolidate vendor relationships beyond hardware substitution. |
| Reimbursement Strategy | Medicare total episode payment alignment positions programmable drains for length-of-stay reduction incentives. |
Research Approach
Independent corroboration across neurosurgical department heads, hospital procurement committee members, biomedical engineering directors, and GPO contracts managers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, PMDA approval databases, hospital procurement records, and EU MDR technical documentation filings. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Comparable-period anchoring to historical neurocritical care admission trends and ventriculostomy procedure registries shaped the forecast framework across product type, end user acuity tier, application severity, and regional regulatory cluster dimensions. CAGRs derived from segmented volume projections incorporating trauma protocol adoption curves, hemorrhagic stroke pathway expansion, and programmable drain replacement cycles. Industry-specific inputs included fellowship-trained practitioner supply constraints and integrated delivery network consolidation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA guideline acceleration or sudden polymer supply disruption scenarios. Projections reflect documented assumptions regarding neurocritical care infrastructure investment continuity and reimbursement bundling stability. A model refresh is warranted upon material change in EU MDR enforcement intensity or Medicare episode payment model expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Baby Thermometer Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Eye Massage Device Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Transilluminators Market