
 Membrane Oxygenators Market | 2026-2036
Membrane Oxygenators Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Oxygenators Market Intelligence
The EU Medical Device Regulation is decoupling low-compliance manufacturers from procurement pipelines across European cardiac centers. Getinge AB leverages its integrated perfusion portfolio to sustain long-term supply contracts with major hospital networks. Medtronic anchors North American demand through extensive ECMO training infrastructure and clinical support programs. LivaNova PLC competes on specialized oxygenator designs optimized for prolonged extracorporeal circulation.
Membrane oxygenators are medical devices that facilitate gas exchange between blood and a sweep gas across a semipermeable membrane, typically constructed from polypropylene hollow fibers with surface areas ranging from 1.8 to 4.5 square meters and rated for blood flow rates up to 7 liters per minute. Their primary purpose is to replace or supplement pulmonary function during cardiopulmonary bypass, ECMO, or acute respiratory failure when native lung oxygenation proves inadequate. Intracorporeal configurations dominate implantable long-term support applications, while portable systems represent the fastest-growing segment as point-of-care ECMO expands beyond traditional ICU settings. Hollow fiber technology leads production volumes due to manufacturing scalability, though membrane coating innovations are capturing margin pools by reducing platelet activation and extending safe perfusion duration.
The FDA maintains Class II/III device controls over oxygenator safety and efficacy, while the EU MDR imposes strengthened clinical evidence requirements and unique device identification tracking. Japan's PMDA enforces stringent biocompatibility testing protocols that shape product development cycles for Asian market entry. ISO 10993 standards govern material cytotoxicity and hemocompatibility evaluations globally, creating baseline compliance costs that favor scaled manufacturers. Stakeholders must monitor evolving reimbursement frameworks for ECMO procedures and anticipate how regional clinical data requirements will reshape competitive access across major markets.
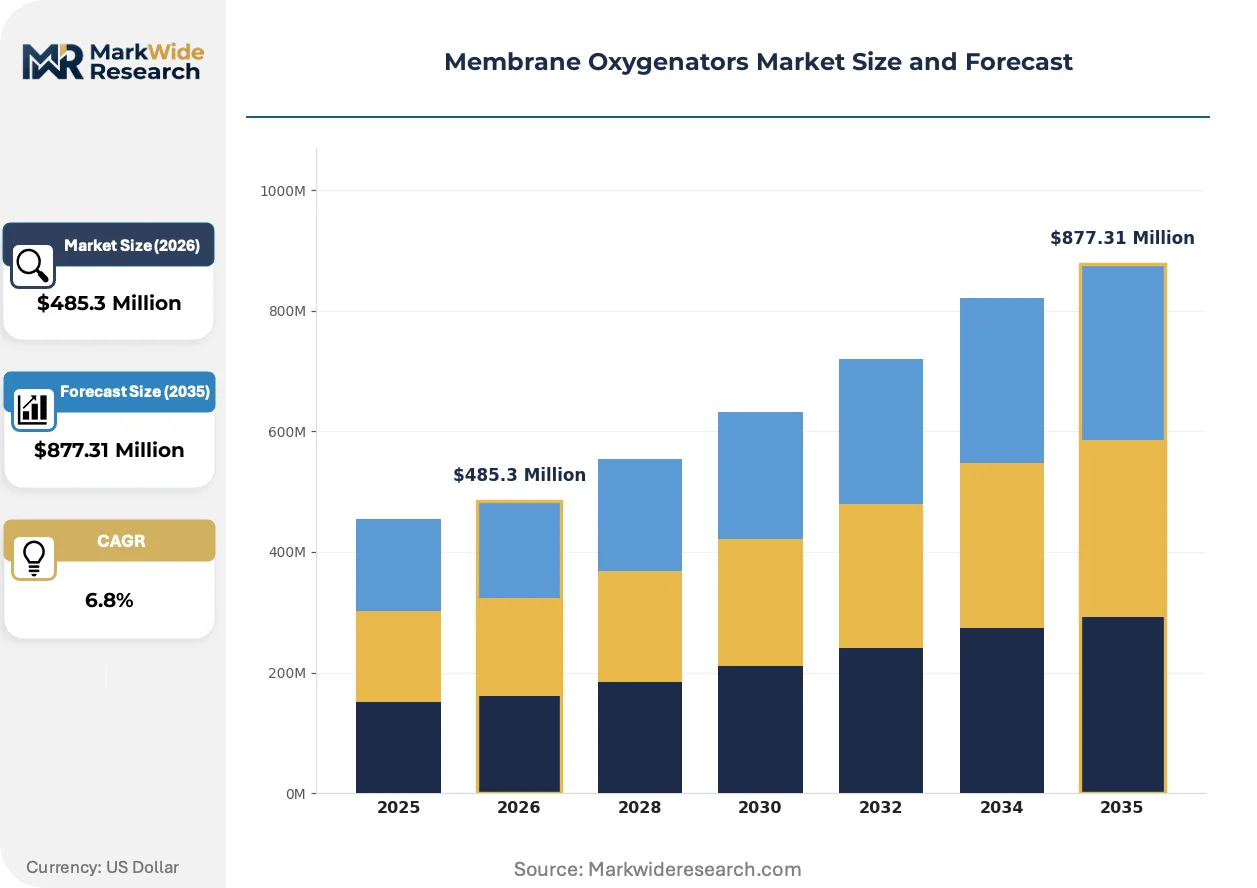
Market Dynamics
ECMO adoption in cardiac and respiratory failure management is reshaping procurement patterns across tertiary hospitals, while the EU Medical Device Regulation tightens biocompatibility and post-market surveillance requirements for extracorporeal devices.
Growth Catalysts
- Point-of-care ECMO expansion:Portable oxygenator systems are penetrating emergency departments and transport medicine, extending extracorporeal support beyond traditional ICU settings.
- Aging cardiac surgery volumes:Established procedural infrastructure in the United States, Germany, and Japan sustains replacement demand for advanced oxygenator systems.
- MDR compliance differentiation:The EU Medical Device Regulation is decoupling low-compliance manufacturers from procurement pipelines across European cardiac centers.
Market Restraints
- Polypropylene supply concentration:Hollow fiber membrane production depends on specialized polymer supply chains concentrated among limited chemical manufacturers.
- PMDA biocompatibility testing burden:Japan's pharmaceutical and medical device agency enforces extended evaluation protocols that elongate product development cycles for Asian market entry.
- Capital intensity of ECMO infrastructure:Tertiary hospital adoption requires substantial investment in perfusionist training, circuit priming systems, and 24/7 clinical support.
Strategic Opportunities
- Intracorporeal long-term support:Implantable oxygenator configurations for bridge-to-transplant applications represent underpenetrated therapeutic territory.
- Membrane coating innovation:Surface modification technologies reducing platelet activation are capturing margin pools by extending safe perfusion duration.
- ISO 10993 harmonization:Convergence around international hemocompatibility standards creates pathways for streamlined multi-regulatory submissions.
Industry Challenges
- Perfusionist workforce scarcity:Specialized ECMO operation requires certified clinical specialists whose training pipelines lag behind device deployment rates.
- Post-market surveillance integration:Unique device identification tracking mandates under EU MDR impose data infrastructure requirements that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Oxygenators Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paracorporeal, Intracorporeal, Portable, Disposable Application: Cardiac Surgery, ECMO, Respiratory Support, Emergency Medicine End User: Hospitals, Ambulatory Surgery Centers, Cardiac Care Units, Specialty Clinics Technology: Hollow Fiber, Flat Sheet, Membrane Coating, Gas Exchange |
| Companies Covered | Getinge AB, LivaNova PLC, Medtronic, Terumo Corporation, EUROSETS, Fresenius Medical Care AG & Co. KGaA, Abbott Laboratories, Nipro Corporation, Chalice Medical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Oxygenators Market Strategic Shifts & Innovations
Membrane oxygenator technology is converging around surface engineering advances and regulatory harmonization pressures, while distribution models adapt to point-of-care expansion and consolidated hospital procurement.
Hollow fiber technology dominates production volumes due to manufacturing scalability, yet membrane coating innovations are consolidating competitive advantage around hemocompatibility performance. Tertiary cardiac centers in the United States and Germany are prioritizing surface-modified oxygenators that reduce platelet activation during prolonged extracorporeal circulation. This consolidation is compressing margins for uncoated commodity oxygenators while rewarding specialized coating capabilities.
The EU Medical Device Regulation imposes strengthened clinical evidence requirements and unique device identification tracking that reshape competitive access. European cardiac centers now demand documented biocompatibility performance that exceeds legacy CE marking thresholds. Manufacturers serving this geography are responding with expanded post-market surveillance infrastructure and proactive clinical data generation.
Hospital procurement is consolidating around integrated perfusion portfolios rather than standalone oxygenator transactions. Major hospital networks in the United States and Japan are negotiating long-term supply contracts that bundle oxygenators with pumps, cannulae, and clinical support services. This bundling is most visible in tertiary centers where ECMO program maturity enables outcome-based vendor relationships.
Membrane Oxygenators Market Segmentation
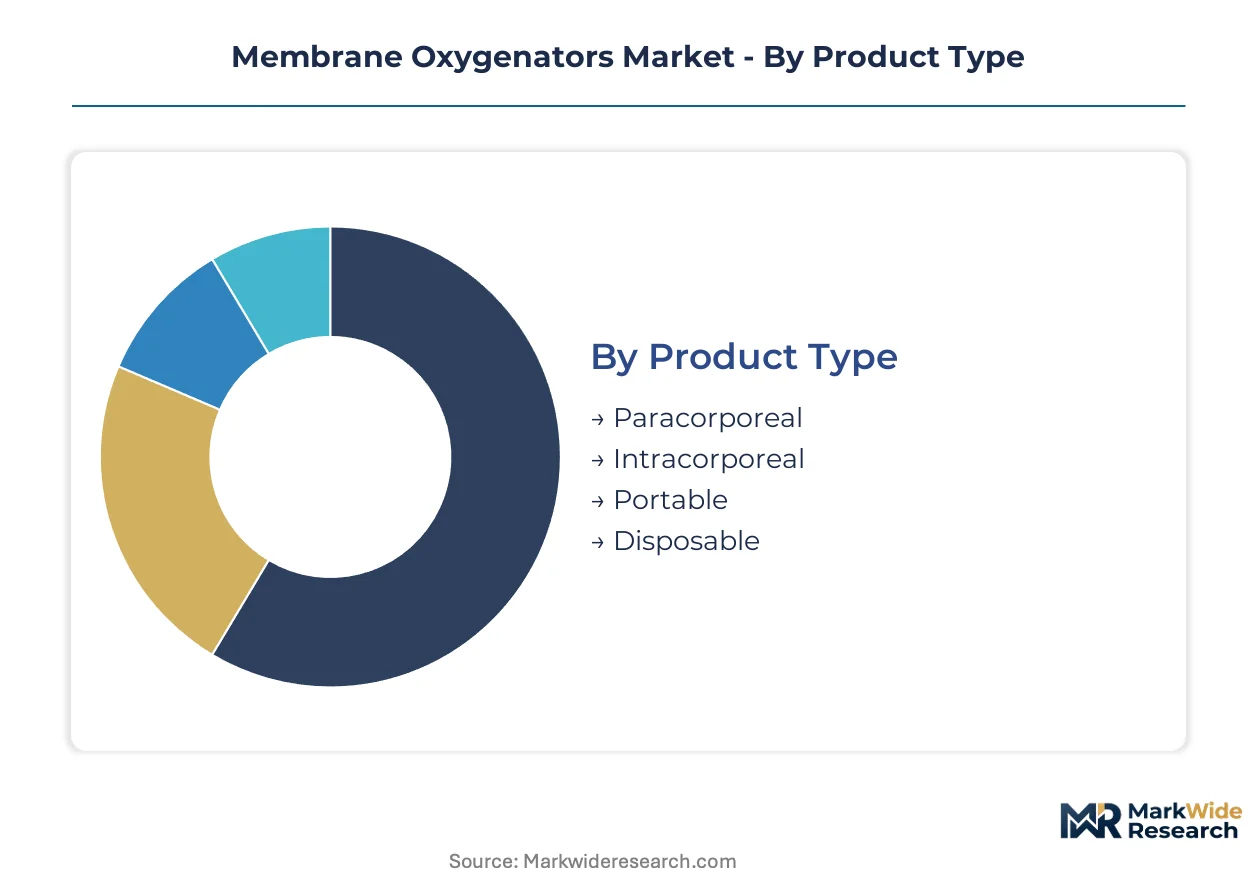
Segmentation in membrane oxygenators reveals how clinical setting, technical architecture, and regulatory exposure shape procurement decisions. Buyers prioritize hemocompatibility performance in prolonged procedures, while hospital scale determines whether integrated systems or standalone devices enter capital budgets.
Product Type:
Procurement teams evaluate implant duration and mobility requirements against total cost of ownership when selecting configurations.
- Paracorporeal:External circuits with pump and oxygenator positioned outside the body, typically employed for short-to-intermediate ECMO support in ICU settings. Demand concentrates in United States tertiary hospitals where 24/7 perfusionist staffing supports complex circuit management.
- Intracorporeal:Implantable configurations designed for bridge-to-transplant or long-term circulatory support, featuring biocompatible housings and reduced thrombogenic surfaces. German cardiac centers lead adoption as reimbursement frameworks recognize extended implantation protocols.
- Portable:Compact, battery-operated systems enabling inter-hospital transport and emergency department initiation. Ambulance services in Japan are piloting deployment for pre-hospital cardiac arrest management.
- Disposable:Single-use oxygenator assemblies eliminating reprocessing validation costs. ASCs in Florida and Texas favor these for scheduled cardiac procedures with predictable bypass durations.
Paracorporeal systems lead on scale; portable configurations lead on momentum.
Application:
Clinical indication determines membrane surface area requirements, anticoagulation protocols, and vendor support intensity.
- Cardiac Surgery:Standard cardiopulmonary bypass supporting coronary artery bypass grafting and valve replacement, requiring 2.5-4.0 square meter surface areas and 4-6 hour rated duration. Cleveland Clinic and Mayo Clinic procurement specifications influence manufacturer design priorities.
- ECMO:Prolonged extracorporeal support for refractory cardiogenic shock or respiratory failure, demanding coated membranes and integrated pressure monitoring. German and Japanese reimbursement expansion is accelerating device placement in mid-tier hospitals.
- Respiratory Support:Acute lung injury management with lower flow requirements than full ECMO, often deployed in step-down units without dedicated perfusion teams. United Kingdom NHS trusts are standardizing protocols for influenza-related ARDS.
- Emergency Medicine:ED-based ECMO initiation for refractory cardiac arrest, requiring rapid priming systems and simplified cannulation interfaces. Paris and London trauma networks are building mobile response capabilities.
Cardiac surgery anchors current volume; emergency medicine applications are expanding most quickly.
End User:
Capital availability and case complexity stratify purchasing authority across care settings.
- Hospitals:Comprehensive ECMO programs with dedicated perfusion departments, negotiating multi-year supply agreements bundling oxygenators with pumps and cannulae. NewYork-Presbyterian and Stanford Health Care set technical standards adopted by regional networks.
- Ambulatory Surgery Centers:Limited to scheduled cardiac procedures with predictable bypass times, favoring disposable configurations and streamlined inventory. Arizona and Nevada ASC chains are consolidating purchasing through group purchasing organizations.
- Cardiac Care Units:Step-down facilities managing post-operative support and weaning protocols, requiring portable systems for patient mobility. Berlin Charité and Tokyo University Hospital CCUs specify lightweight pump-oxygenator combinations.
- Specialty Clinics:Niche providers focusing on heart failure management and transplant evaluation, often leasing equipment rather than capital purchase. Swiss and Austrian private cardiac clinics prefer flexible service contracts.
Hospitals dominate procurement value; specialty clinics show steepest expansion trajectory.
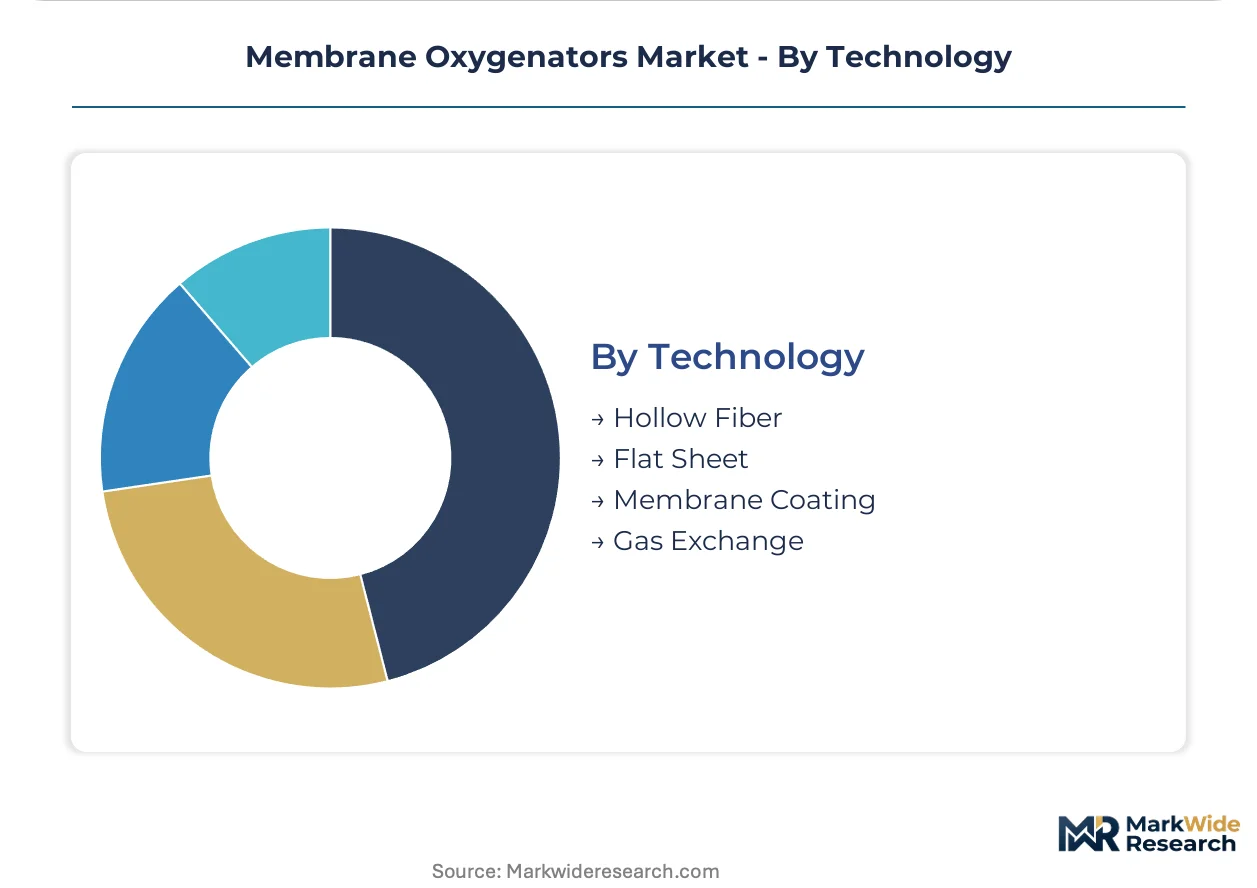
Technology:
Manufacturing process and surface engineering determine hemocompatibility performance and regulatory pathway complexity.
- Hollow Fiber:Polypropylene microfiber bundles providing high surface area-to-volume ratios and scalable production economics. This architecture supplies the majority of clinical installations worldwide due to established supply chains.
- Flat Sheet:Layered membrane configurations offering reduced priming volume and improved gas transfer efficiency at low flow rates. Pediatric specialists in Boston Children's Hospital and Great Ormond Street prefer these for neonatal ECMO.
- Membrane Coating:Surface modifications including heparin bonding, phosphorylcholine layers, and albumin passivation reducing platelet activation. Coated variants command price premiums in German and Japanese markets with stringent biocompatibility requirements.
- Gas Exchange:Core functional specification encompassing oxygen transfer rate, carbon dioxide clearance, and pressure drop characteristics. FDA and PMDA validation protocols for these metrics drive development timelines.
Hollow fiber technology leads on manufacturing scale; membrane coating innovations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Perfusionist training programs in the United States, Germany, and Japan anchor the geography's ECMO infrastructure development. These specialized workforces sustain device deployment rates that outpace broader clinical staffing growth. Hospital procurement authority concentrates where established cardiac surgery volumes justify dedicated extracorporeal support teams.
United States
Tertiary cardiac centers at Cleveland Clinic and Mayo Clinic drive specification standards adopted by regional networks. FDA Class II/III device controls govern oxygenator safety validation through premarket notification and quality system requirements. NewYork-Presbyterian and Stanford Health Care negotiate multi-year supply agreements bundling oxygenators with pumps and clinical support services.
Germany
Charité Berlin and German Heart Center Munich anchor European ECMO adoption with reimbursement frameworks recognizing extended implantation protocols. EU Medical Device Regulation imposes strengthened clinical evidence requirements and unique device identification tracking that exceed legacy CE marking thresholds. Baden-Württemberg and Bavaria host concentrated procurement authority for integrated perfusion portfolios.
Japan
Tokyo University Hospital and Osaka University Hospital sustain Asia-Pacific demand through aging cardiac surgery volumes and established procedural infrastructure. PMDA enforces stringent biocompatibility testing protocols that shape product development cycles for regional market entry. Ambulance services in Kanto prefecture pilot portable oxygenator deployment for pre-hospital cardiac arrest management.
United Kingdom
Great Ormond Street and NHS trusts in London standardize protocols for influenza-related ARDS requiring respiratory support. MHRA alignment with EU MDR clinical evidence requirements influences procurement specifications across cardiac centers. Trauma networks in Paris and London coordinate mobile ECMO response capabilities for emergency medicine applications.
Switzerland
Swiss cardiac clinics in Zurich and Geneva prefer flexible service contracts for heart failure management and transplant evaluation. Swissmedic maintains biocompatibility standards that converge with EU MDR and ISO 10993 hemocompatibility evaluations. Private specialty clinics in Austrian and Swiss metropolitan areas lease equipment rather than capital purchase oxygenator systems.
Membrane Oxygenators Market Key Industry Players
Capital-heavy producers compete with asset-light designers across membrane oxygenator supply chains. The market structure consolidates around integrated perfusion portfolios rather than standalone device transactions. Three archetypes dominate: diversified medical technology conglomerates with ECMO training infrastructure, specialized cardiovascular device manufacturers with coating capabilities, and regional suppliers serving price-sensitive procurement segments. M&A activity targets membrane surface engineering capabilities, while strategic partnerships bundle oxygenators with cannulae and pump systems.
Among diversified technology conglomerates, Getinge AB and Medtronic occupy positions anchoring integrated supply contracts with major hospital networks. LivaNova PLC exemplifies the specialized cardiovascular tier with focused oxygenator design capabilities. Terumo Corporation represents Asia-Pacific headquartered competition navigating PMDA and FDA dual regulatory pathways. These three entities collectively illustrate how geographic regulatory exposure and portfolio breadth stratify competitive positioning across the United States, European, and Japanese procurement channels.
| Leading Market Players |
|---|
| Getinge AB |
| LivaNova PLC |
| Medtronic |
| Terumo Corporation |
| EUROSETS |
| Fresenius Medical Care AG & Co. KGaA |
| Abbott Laboratories |
| Nipro Corporation |
| Chalice Medical Ltd. |
| Others |
Cost & Logistics Intelligence
Polypropylene hollow fiber supply from German and Japanese specialty polymer producers flows through membrane coating tiers before reaching hospital procurement committees, with surface-modified variants commanding premiums over commodity oxygenators in tertiary cardiac centers.
Pricing Analysis
Bundled service contracts dominate large hospital network procurement, while standalone oxygenator transactions persist in ambulatory surgery centers. Three-tier pricing structure across premium, standard, and economy levels separates heparin-coated membrane systems from uncoated hollow fiber units and disposable emergency configurations. Cost compression in the economy tier is intensifying because ASC chains consolidate purchasing through group purchasing organizations. Ambulatory surgery centers exhibit highest price sensitivity; German cardiac centers demonstrate lowest sensitivity due to reimbursement recognition of extended implantation protocols.
Supply Chain Analysis
Specialized polypropylene resin supply rests on petrochemical producers in Germany, Japan, and the United States, with membrane extrusion and coating capabilities concentrating among established medical device manufacturers. Raw material dependencies include medical-grade polypropylene, surface modification chemicals, and biocompatible housing polymers. Single-source vulnerability in hollow fiber extrusion equipment creates bottlenecks for mid-tier manufacturers seeking capacity expansion. Distribution runs through direct hospital contracts for integrated perfusion portfolios, with specialty distributors serving smaller cardiac centers and emergency medicine programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement committees shift specification standards toward membrane coating performance and documented hemocompatibility under EU MDR and PMDA frameworks.
For Market Incumbents: Extend coating technology roadmaps to capture margin pools in prolonged ECMO applications, while securing captive supply of medical-grade polypropylene to defend against resin price volatility. Backward integration into membrane extrusion or strategic polymer offtake agreements with German and Japanese chemical producers reduces single-source exposure.
For New Entrants and Emerging Players: Launch via portable oxygenator distribution partnerships with ambulance services and emergency medicine networks in Japan and the United Kingdom. Pre-hospital cardiac arrest management and inter-hospital transport applications offer penetrable white space without requiring full perfusionist staffing infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack EU MDR post-market surveillance infrastructure and unique device identification tracking capabilities. Long-term viability favors targets with ISO 10993 hemocompatibility validation and established coating chemistry platforms. Watch PMDA biocompatibility testing timeline compression as an inflection signal for Asian market access costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Coating Technology Investment | Heparin-bonded and phosphorylcholine surfaces reduce platelet activation during prolonged ECMO runs at Cleveland Clinic and Charité Berlin. |
| EU MDR Compliance Infrastructure Buildout | Post-market surveillance systems and unique device identification tracking satisfy tightened clinical evidence requirements for European cardiac center access. |
| Hospital System Partnership | Multi-year supply agreements bundling oxygenators with pumps and cannulae anchor procurement relationships at NewYork-Presbyterian and Stanford Health Care. |
| Perfusionist Training Program Expansion | Certified clinical specialist pipelines address workforce scarcity constraining ECMO program deployment rates in United States tertiary centers. |
| Portable System Development | Battery-operated configurations enable emergency department initiation and ambulance deployment for pre-hospital cardiac arrest in Kanto prefecture. |
Research Approach
Multiple input streams — structured interviews with perfusionists and cardiac surgeons, procurement database analysis, and regulatory filing review — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and ECMO program coordinators across United States, German, and Japanese tertiary centers. Secondary validation drew from FDA 510(k) filings, PMDA approval summaries, EU MDR technical documentation, hospital procurement records, and ISO 10993 biocompatibility test reports.
Data-stream reconciliation across supply-side capacity assessments and demand-side procedure volume projections shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product configuration, clinical application, end-user facility type, and membrane technology tier. CAGRs were derived from installed base replacement cycles, ECMO program expansion trajectories, and coating technology adoption curves. Forecast inputs incorporated perfusionist workforce growth rates, reimbursement framework evolution, and regulatory pathway timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden polypropylene supply disruption or accelerated EU MDR enforcement timelines. Forecasts reflect documented assumptions regarding cardiac surgery volume stability and ECMO indication expansion. Supply concentration in specialty polymer production, perfusionist training pipeline constraints, and post-market surveillance infrastructure costs represent specific risk factors that could revise projections. A small set of named triggers — PMDA testing protocol changes, major hollow fiber extrusion capacity additions, and emergency medicine reimbursement decisions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Bone Power Tools Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Intrathecal Pumps Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Artificial Retina Market
Medical Devices
Pharma Robots Market
Medical Devices
Direct Energy Medical Devices Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Automated CPR Devices Market