
 Global Electrotherapy Devices Market | 2026-2036
Global Electrotherapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrotherapy Devices Market Foresight
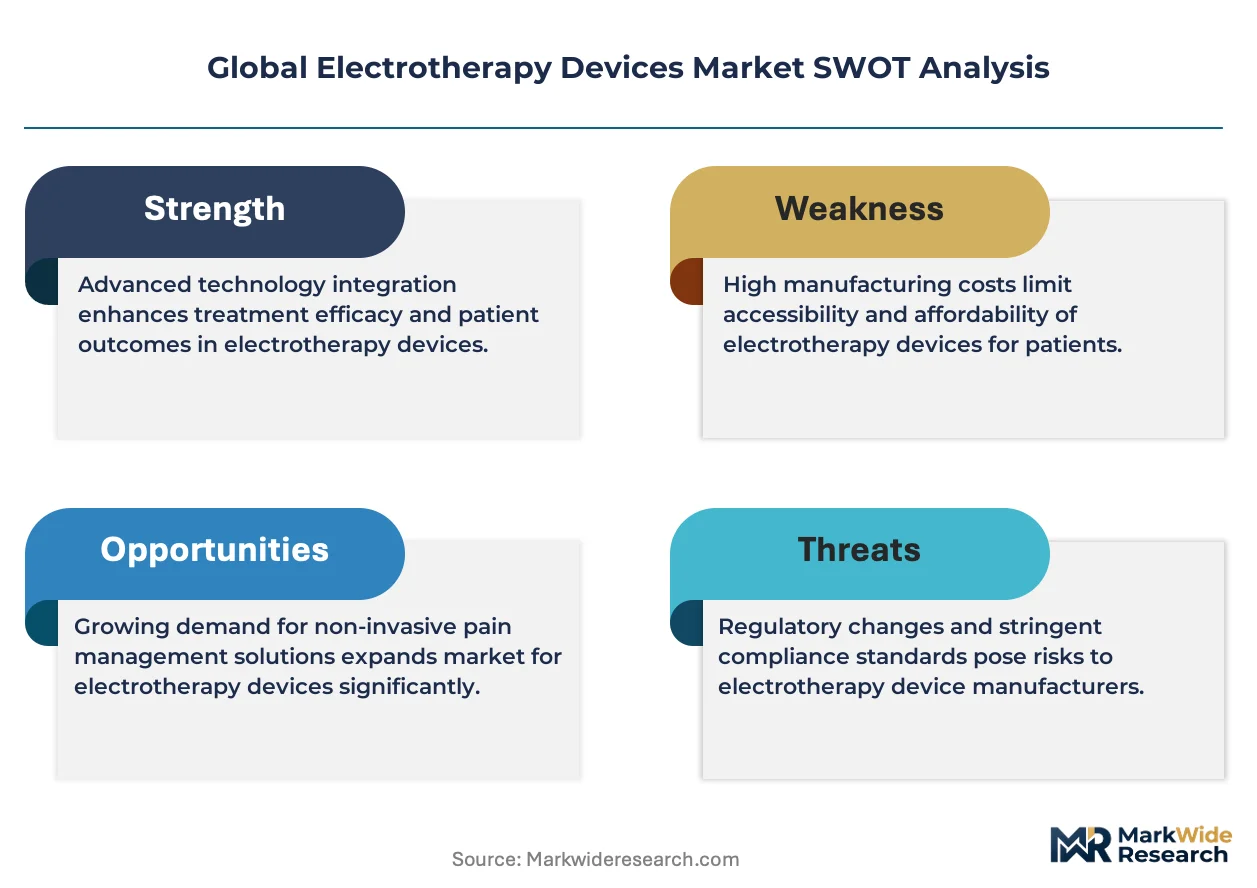
Home care settings are rotating toward portable electrotherapy units as post-acute patients prioritize convenience over clinic visits. Medtronic sustains technology leadership in implantable neurostimulation platforms with substantial R&D allocation. DJO Global dominates consumer-facing transcutaneous electrical nerve stimulation devices through direct-to-consumer channels and physical therapy partnerships. Zynex Medical specializes in prescription-strength wearable units that bridge clinical efficacy with home use compliance.
Electrotherapy devices deliver controlled electrical impulses through electrodes to modulate nerve signaling, stimulate muscle contraction, or promote tissue repair, typically operating at frequencies between 1 and 150 Hz with pulse durations measured in microseconds. Their primary commercial purpose spans pain mitigation, functional rehabilitation, and neuromuscular reeducation across acute and chronic care pathways. Transcutaneous electrical nerve stimulation occupies the largest installed base among product types due to decades of clinical validation and favorable reimbursement coding. Electrical muscle stimulation is expanding fastest in sports training centers where performance recovery protocols now incorporate neuromuscular electrical stimulation as standard practice. Home care settings represent the most contested end-user channel, with margin pools shifting toward subscription-based electrode replenishment and remote patient monitoring integrations.
The FDA enforces 510(k) clearance pathways for electrotherapy devices with stringent electrical safety testing under IEC 60601-1 standards, while the EMA's Medical Device Regulation requires clinical evidence portfolios for Class IIa and above pain management systems. Japan's PMDA maintains additional electromagnetic compatibility certifications that create non-tariff barriers for unapproved manufacturers. China's NMPA has accelerated review timelines for innovative neuromodulation devices under its priority review channel, reshaping competitive entry sequencing. Stakeholders must monitor evolving cybersecurity requirements for connected electrotherapy units as software-as-a-medical-device frameworks expand beyond traditional hardware regulation.
Market Dynamics
Home care migration is compressing traditional clinic-based revenue pools while forcing manufacturers to redesign electrode replenishment around direct-to-consumer logistics rather than institutional procurement.
Growth Catalysts
- Aging demographics in Japan, Germany, and the United States:Expanding Medicare and statutory health insurance coverage for chronic pain management creates reimbursement clarity for prescription-strength wearable units.
- MDR clinical evidence requirements:EMA's tightened post-market surveillance obligations favor established manufacturers with existing clinical portfolios, raising competitive barriers for new entrants.
- Neuromuscular electrical stimulation protocols:Sports medicine facilities and professional athletic training centers now embed electrical muscle stimulation into standardized recovery regimens.
Market Restraints
- Silver-silver chloride electrode cost volatility:Raw material price swings for conductive gel and adhesive substrates squeeze margin on disposable components.
- PMDA electromagnetic compatibility certification:Japan's additional testing layers extend time-to-market by 8-14 months for unapproved manufacturers.
- Pharmacological pain management substitution:Sustained-release opioid formulations and non-steroidal anti-inflammatory patches retain physician preference in acute post-surgical settings.
Strategic Opportunities
- China's NMPA priority review channel:Accelerated timelines for innovative neuromodulation devices enable faster competitive entry sequencing for novel waveform technologies.
- Software-as-a-medical-device frameworks:FDA's evolving guidance on connected electrotherapy units creates white space for AI-driven dosage optimization and remote monitoring integrations.
- Subscription-based electrode replenishment:Direct-to-patient logistics models capture recurring revenue streams as home care patients prioritize convenience over clinic visits.
Industry Challenges
- IEC 60601-1 electrical safety testing capacity:Limited third-party laboratory availability for high-voltage insulation and leakage current validation extends certification timelines.
- Cybersecurity integration with legacy hospital IT:Connected wearable units face interoperability friction with existing electronic health record systems and network security protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrotherapy Devices Market |
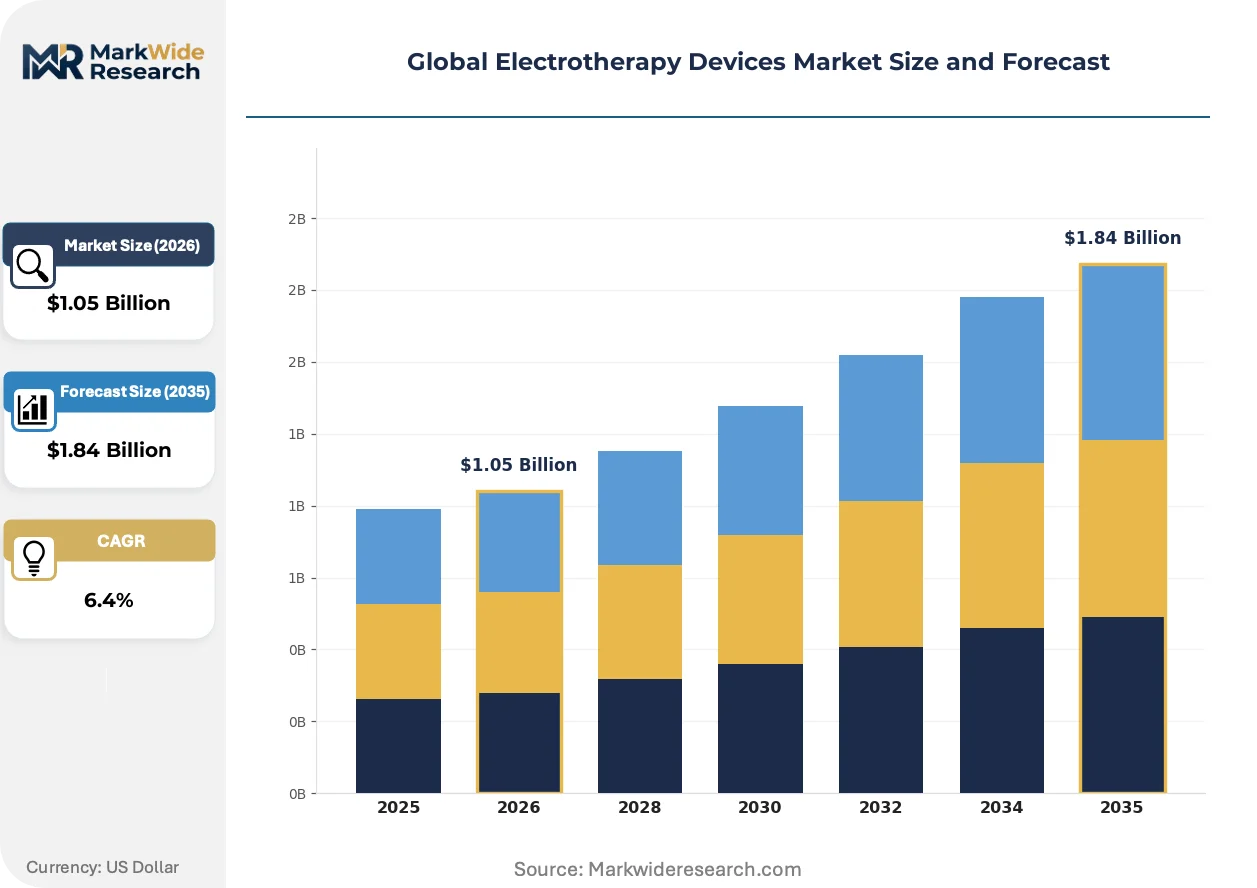
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcutaneous Electrical Nerve Stimulation, Interferential Therapy, Microcurrent Therapy, Electrical Muscle Stimulation Application: Chronic Pain Relief, Postoperative Rehabilitation, Muscle Conditioning, Neuromuscular Reeducation End User: Physiotherapy Clinics, Sports Training Centers, Chiropractic Offices, Home Care Settings Technology: Pulsed Electromagnetic Fields, Direct Current, Biphasic Pulsed Current, Russian Stimulation |
| Companies Covered | Boston Scientific Corporation, NeuroMetrix, Medtronic, Enraf-Nonius, Chattanooga Group, DJO Global, Zynex Medical, Longest Medical, BTL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrotherapy Devices Market Shifts & Advancements
Convergence of miniaturized electronics, cloud connectivity, and outcome-based reimbursement is redefining how electrotherapy devices are prescribed, monitored, and monetized across care settings.
Flexible printed circuit electrodes with micro-needle arrays are penetrating deeper tissue layers without increasing surface current density. Pain management clinics in South Korea and Germany are piloting these configurations for neuropathic conditions resistant to conventional transcutaneous delivery. The form factor is miniaturizing to patch-like wearables that patients apply independently, eliminating nursing labor from the care pathway.
EMA's Medical Device Regulation now mandates clinical evidence portfolios for Class IIa pain management systems, including post-market performance tracking. Manufacturers must maintain updated technical documentation and periodic safety reporting, increasing regulatory affairs headcount by 30-40% for mid-tier competitors. European notified bodies are prioritizing submissions with real-world evidence from connected devices, advantaging firms with existing digital infrastructure.
Patients now expect remote therapeutic monitoring with their electrotherapy prescriptions, mirroring telehealth normalization across chronic disease management. Physical therapy chains in the United States are unbundling device provision from in-clinic sessions, shipping units directly to post-acute patients with video-guided setup protocols. This channel compression reduces per-patient labor costs while capturing adherence data that supports prior authorization renewals with payers.
Global Electrotherapy Devices Market Segmentation
Electrotherapy device segmentation reveals distinct channel economics across product categories. Each dimension carries implications for margin structure, regulatory burden, and customer acquisition cost that shape competitive positioning.
Product Type:
Channel mix varies sharply across product types, with institutional procurement dominating high-voltage systems while direct-to-consumer logistics capture wearable categories.
- Transcutaneous Electrical Nerve Stimulation:Surface electrode systems deliver low-voltage pulses through conductive gel interfaces at 1-150 Hz frequencies. Demand concentrates in United States home care settings where Medicare reimbursement coding supports prescription-strength units for chronic back pain. The installed base spans decades of clinical validation.
- Electrical Muscle Stimulation:Neuromuscular activation devices induce involuntary contraction through motor nerve depolarization at higher current densities. Sports training centers in Germany and Japan embed these into standardized recovery protocols, driving replacement cycles as performance metrics validate efficacy.
- Interferential Therapy:Cross-interference of two medium-frequency carriers produces therapeutic low-frequency effects at tissue depth. Physiotherapy clinics in South Korea favor these for post-surgical rehabilitation where penetration depth matters.
- Microcurrent Therapy:Sub-sensory current levels below 1 mA target cellular repair mechanisms. Wellness channels and aesthetic medicine practices in California and Florida drive niche adoption.
Transcutaneous Electrical Nerve Stimulation dominates installed base. Electrical Muscle Stimulation is where expansion concentrates.
Application:
Cost tier segmentation separates acute intervention reimbursements from chronic management subscriptions, with neuromuscular reeducation commanding premium pricing in workers compensation channels.
- Chronic Pain Relief:Long-term neuropathic and musculoskeletal conditions require sustained electrode replenishment and device durability. Home care patients in Japan prioritize convenience over clinic visits, shifting margin pools toward subscription logistics.
- Postoperative Rehabilitation:Acute recovery protocols following orthopedic surgery demand precise dosage control and clinical oversight. Hospital discharge planners in Germany coordinate device provision through statutory health insurance pathways.
- Muscle Conditioning:Athletic performance optimization emphasizes portable form factors and training integration. Professional sports franchises in the United States specify wireless connectivity for real-time load monitoring.
- Neuromuscular Reeducation:Motor pathway restoration after stroke or injury requires patterned stimulation with biofeedback. Rehabilitation hospitals in the United Kingdom and Australia bundle these services into bundled payment models.
Chronic Pain Relief captures recurring revenue streams. Postoperative Rehabilitation shows steepest expansion trajectory as surgical volumes recover.
End User:
Customer type determines procurement authority, with institutional buyers negotiating volume discounts while individual patients prioritize convenience and brand familiarity.
- Home Care Settings:Self-administered therapy demands intuitive interfaces, electrode subscription logistics, and remote monitoring compatibility. Direct-to-patient channels in the United States bypass traditional durable medical equipment distributors.
- Physiotherapy Clinics:Multi-modality practices require versatile platforms with interchangeable electrode configurations. Reimbursement clarity in Germany supports capital investment in premium systems.
- Sports Training Centers:Performance-focused facilities prioritize rapid recovery protocols and athlete compliance. collegiate and professional programs in Japan specify electromagnetic compatibility certifications.
- Chiropractic Offices:Conservative care settings favor portable units for in-clinic application and rental programs. Practice economics in the United States favor devices with favorable prior authorization profiles.
Home Care Settings are gaining share fastest. Physiotherapy Clinics retain the deepest clinical influence on prescribing patterns.
Technology:
Supply concentration in semiconductor and electrode materials creates margin pressure that technology selection can mitigate or amplify.
- Biphasic Pulsed Current:Balanced charge delivery minimizes tissue polarization and electrode corrosion, extending disposable component life. FDA 510(k) pathways favor these configurations for safety documentation.
- Pulsed Electromagnetic Fields:Non-contact induction enables bone healing applications where electrode adhesion is impractical. Orthopedic practices in Germany and Switzerland maintain specialized reimbursement codes.
- Direct Current:Galvanic stimulation drives iontophoresis for transdermal drug delivery in dermatology and sports medicine. Compounding pharmacies in the United States coordinate prescription protocols.
- Russian Stimulation:Medium-frequency burst patterns target muscle strengthening with reduced sensory discomfort. Physical therapy education programs in Australia and Canada emphasize these techniques.
Biphasic Pulsed Current anchors mainstream clinical adoption. Pulsed Electromagnetic Fields occupy the highest price tier per treatment session.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and home care patients concentrate demand in aging economies with reimbursement clarity. Germany, Japan, and the United States anchor clinical adoption through statutory coverage and Medicare pathways. Manufacturing clusters in South Korea and Switzerland supply specialized components to these demand centers.
United States
Medicare reimbursement coding for prescription-strength wearable units drives home care migration among chronic pain patients. The FDA enforces 510(k) clearance pathways with stringent electrical safety testing under IEC 60601-1 standards. Minneapolis-St. Paul hosts implantable neurostimulation R&D facilities serving hospital discharge planners nationwide.
Germany
Statutory health insurance coverage for postoperative rehabilitation creates predictable demand through physiotherapy clinic networks. EMA's Medical Device Regulation mandates clinical evidence portfolios for Class IIa pain management systems with post-market surveillance obligations. Berlin and Munich concentrate notified body relationships and regulatory affairs expertise for European market access.
Japan
Aging demographics expand the addressable market for self-administered pain management among elderly populations. PMDA electromagnetic compatibility certifications extend time-to-market by 8-14 months for unapproved manufacturers. Tokyo and Osaka host specialized testing laboratories serving domestic and export-bound device manufacturers.
South Korea
Pain management clinics pilot flexible printed circuit electrodes with micro-needle arrays for neuropathic conditions. MFDS maintains accelerated review pathways for innovative neuromodulation devices meeting priority criteria. Seoul's Gangnam district concentrates aesthetic medicine practices driving microcurrent therapy adoption.
Switzerland
Orthopedic practices maintain specialized reimbursement codes for pulsed electromagnetic field applications in bone healing. Swissmedic coordinates with European notified bodies on MDR transition timelines for Class IIa devices. Basel and Zurich host precision electronics suppliers serving implantable stimulator manufacturers.
Global Electrotherapy Devices Market Competitive Landscape
Player mix skews toward diversified medtech conglomerates with implantable platforms alongside specialized wearable manufacturers. Consolidation pressure favors established manufacturers with existing clinical portfolios that satisfy tightened EMA post-market surveillance obligations. Two strategic archetypes dominate: implantable neurostimulation specialists with substantial R&D allocation, and consumer-facing transcutaneous device manufacturers with direct-to-consumer logistics. Competitive moves concentrate on strategic partnerships for remote patient monitoring integration and portfolio diversification into subscription-based electrode replenishment.
Within the implantable neurostimulation tier, Medtronic and Boston Scientific Corporation exemplify scale-driven R&D concentration. DJO Global and Zynex Medical occupy positions bridging clinical efficacy with home use compliance among prescription-strength wearable specialists. Chattanooga Group and BTL Industries represent European fabricators with physiotherapy clinic channel relationships. NeuroMetrix and Enraf-Nonius sit within the niche diagnostic and rehabilitation equipment segment. Longest Medical anchors Chinese manufacturing capacity serving cost-sensitive market tiers.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| NeuroMetrix |
| Medtronic |
| Enraf-Nonius |
| Chattanooga Group |
| DJO Global |
| Zynex Medical |
| Longest Medical |
| BTL Industries |
| Others |
Supply & Pricing Matrix
Long-term electrode replenishment contracts with silver-indexed pricing lock in supply access for wearable manufacturers while buffering margin volatility from conductive gel cost swings. This contract structure concentrates procurement power among incumbents with direct-to-patient logistics infrastructure, forcing mid-tier competitors toward spot-market exposure for adhesive substrates.
Pricing Analysis
Cost-plus agreements with London Metal Exchange silver indexation dominate electrode procurement, spreading raw material volatility across quarterly adjustments. Pricing stratifies across prescription-strength, over-the-counter, and wellness tiers, with FDA 510(k) certification tier commanding premium positioning. Pricing pressure stems from Medicare reimbursement compression on durable medical equipment codes, squeezing margin on standard units. Home care patients exhibit highest price sensitivity, while sports training centers prioritize performance validation over unit cost.
Supply Chain Analysis
Port congestion on transpacific lanes from Shanghai to Long Beach elevates inbound logistics costs for microelectronic components and flexible printed circuit substrates. Manufacturing concentrates in China, South Korea, and Switzerland, with semiconductor fabrication feeding from Taiwanese foundries and precision electrode assembly anchored in German physiotherapy equipment clusters. Silver-silver chloride sourcing rests on Mexican mining output and Chinese refining capacity, creating single-source vulnerability for conductive gel formulations. Distribution runs through durable medical equipment distributors in the United States and statutory health insurance procurement channels in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across home care, sports medicine, and postoperative rehabilitation creates niche entry points as patient self-administration displaces clinic-based delivery. Each segment demands distinct certification profiles and channel economics.
For Market Incumbents: Consolidate electrode replenishment logistics through captive supply of silver-silver chloride substrates, insulating margin from London Metal Exchange volatility. Acquire notified body relationships in Berlin and Munich to compress EMA Medical Device Regulation approval timelines for Class IIa pain management systems. Prioritize backward integration into flexible printed circuit manufacturing to secure micro-needle array supply for neuropathic therapy pilots. For New Entrants and Emerging Players: China's NMPA priority review channel offers fastest regulatory pathway for novel waveform technologies, enabling competitive entry sequencing ahead of PMDA electromagnetic compatibility timelines. Target home care settings with subscription-based electrode replenishment models that bypass traditional durable medical equipment distributor markups. Lead with software-as-a-medical-device positioning to capture AI-driven dosage optimization white space before FDA guidance solidifies. For Investors and Strategic Acquirers: Prescription-strength wearable specialists with existing FDA 510(k) portfolios and direct-to-patient logistics infrastructure present optimal acquisition targets. Long-term viability hinges on reimbursement clarity expansion across Medicare Advantage and statutory health insurance pathways. Monitor NMPA approval velocity for innovative neuromodulation devices as inflection signal for competitive entry sequencing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA Medical Device Regulation compliance unlocks German statutory health insurance procurement channels. |
| Hospital System Partnership | US discharge planner relationships secure postoperative rehabilitation device placement at orthopedic surgery volume centers. |
| Software Companion Development | FDA software-as-a-medical-device frameworks enable AI-driven dosage optimization for connected wearable units. |
| Reimbursement Strategy | Medicare coding clarity for prescription-strength TENS units accelerates home care migration among chronic pain patients. |
| Backward Integration | Captive silver-silver chloride electrode production insulates margin from conductive gel raw material volatility. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) filings, EMA Medical Device Regulation submissions, and CMS Medicare reimbursement databases anchors the qualitative findings. Bottom-up triangulation across product type, application, and end user segmentation layers with top-down macroeconomic calibration ensures internal consistency.
Sensitivity analysis on silver price volatility, PMDA electromagnetic compatibility timeline variance, and Medicare reimbursement compression stress-tests projection robustness across the analysis window. Modeled dimensions span transcutaneous electrical nerve stimulation, electrical muscle stimulation, and interferential therapy product categories; chronic pain relief, postoperative rehabilitation, and muscle conditioning applications; and home care settings, physiotherapy clinics, and sports training centers. CAGR derivation incorporates procedure volume trajectories, electrode replacement cycles, and wearable unit penetration curves.
Decision-makers should treat outputs as directional under assumptions of sustained Medicare reimbursement clarity and stable silver supply chains; material deviation would warrant model refresh. Regulatory timeline slippage at PMDA or reimbursement compression beyond historical Medicare patterns represent primary forecast revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
Feeding Tubes Market
Medical Devices
Global Cardiac Resuscitation Device Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
US Nebulizer Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Interatrial Shunt Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Global Bone Cement Delivery System Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Clot Management Devices Market