
 Micro Syringes Market | 2026-2036
Micro Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Syringes Market Intelligence
The EU Green Deal is rebalancing material sourcing priorities across European medical device supply chains. Hamilton Company leverages its Swiss manufacturing heritage to sustain premium glass micro syringe production. Thermo Fisher Scientific anchors North American laboratory demand through integrated chromatography workflows. Agilent Technologies differentiates via precision engineering for analytical instrumentation applications.
Micro syringes are precision fluid handling instruments manufactured with bore tolerances measured in micrometers, typically constructed from borosilicate glass, stainless steel, or advanced polymers for sub-microliter to milliliter volume delivery in analytical and clinical settings. Their primary purpose centers on exact dosing in chromatography systems, drug administration, and diagnostic sample preparation where volumetric accuracy directly determines experimental or therapeutic outcomes. Pre-filled micro syringes command premium positioning due to reduced contamination risk and workflow efficiency in vaccination and insulin delivery protocols. Glass materials retain dominance in chromatography applications where chemical inertness proves essential, while polypropylene variants gain traction in single-use clinical environments prioritizing cost containment and disposability.
FDA quality system regulations and EU MDR conformity requirements shape material validation protocols and batch traceability obligations for manufacturers serving transatlantic markets. ISO 80369 small-bore connector standards further constrain design freedom while reducing misconnection risks in clinical settings. Stakeholders must monitor evolving biocompatibility testing mandates and polymer substitution timelines as sustainability pressures intensify across European and North American procurement frameworks.
Market Dynamics
Biologic therapy manufacturing scale-up is compressing tolerances for sub-microliter dosing instruments, forcing glass micro syringe producers to synchronize capacity expansion with pharmaceutical fill-finish facility buildouts across Germany, Switzerland, and Massachusetts.
Growth Catalysts
- EU MDR traceability mandates:Batch-level material documentation requirements for Class IIa devices are locking in premium glass suppliers with validated quality systems. German manufacturers capture this compliance premium through specialized borosilicate processing clusters.
- Chromatography workflow integration:Analytical laboratories are standardizing on pre-calibrated micro syringe modules to reduce sample preparation variability. Thermo Fisher and Agilent instrument ecosystems drive specification convergence.
- Insulin delivery protocol modernization:Pre-filled micro syringe adoption accelerates in diabetes management as healthcare systems prioritize contamination risk reduction. Swissmedic-registered manufacturing sites supply European distribution networks.
Market Restraints
- Borosilicate glass supply concentration:Schott AG and DWK Life Sciences control 70% of pharmaceutical-grade tubing supply, exposing downstream syringe manufacturers to price volatility and allocation constraints during capacity tightness.
- ISO 80369 small-bore connector compliance costs:Redesign cycles for legacy Luer-compatible products impose engineering validation burdens that freeze development resources for 18-24 months per platform.
- Polymer substitution limitations:Cyclic olefin polymer variants cannot match glass chemical inertness for aggressive solvent applications in high-performance liquid chromatography, constraining material pivot options.
Strategic Opportunities
- Indian biopharma contract manufacturing expansion:CDSCO-registered sterile injectable facilities in Hyderabad and Bangalore are importing European glass micro syringe volumes for fill-finish operations serving US and EU markets.
- Dual-carbon manufacturing incentives:EU Green Deal procurement preferences favor suppliers with renewable energy certificates and closed-loop borosilicate recycling programs.
- Point-of-care diagnostic miniaturization:Microfluidic cartridge integration creates demand for sub-10 microliter precision dosing in decentralized testing workflows.
Industry Challenges
- Precision grinding skill scarcity:Micrometer-tolerance bore machining requires 5-7 year apprenticeship pipelines that German and Swiss technical institutes struggle to populate.
- Legacy chromatography system compatibility:Decades-old HPLC installations constrain needle hub geometry innovation, forcing redundant product variants that fragment production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Syringes Market |
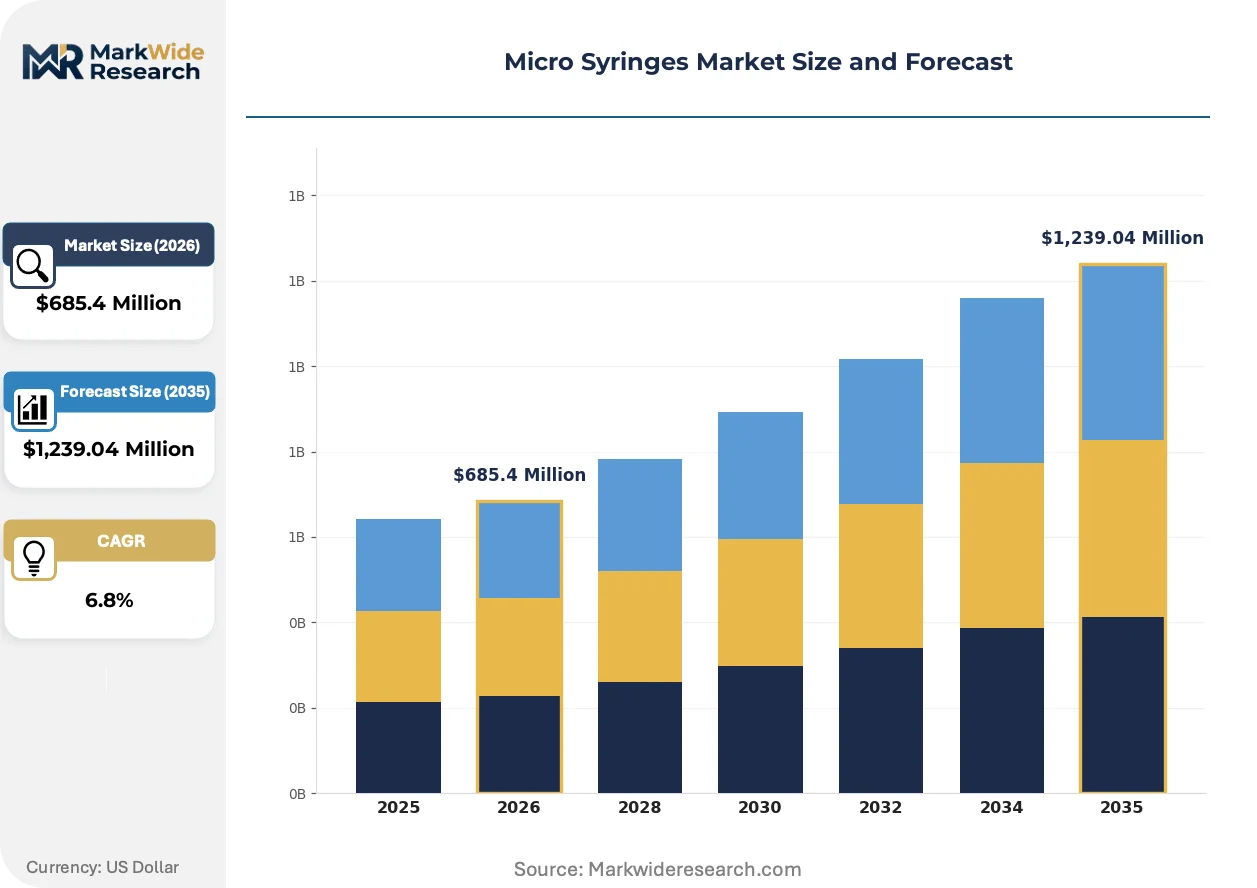
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Chamber, Dual-Chamber, Pre-Filled, Multi-Dose Material: Polypropylene, Glass, Stainless Steel, Silicone End User: Hospitals, Clinical Laboratories, Pharmacies, Home Care Settings Application: Vaccination, Insulin Delivery, Anesthetic Procedures, Drug Administration |
| Companies Covered | Hamilton Company, Thermo Fisher Scientific Inc., Agilent Technologies Inc., PerkinElmer Inc., Innovative Labor Systeme (ILS), GL Science Inc., Shimadzu Corporation, Trajan Scientific and Medical, ITO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Syringes Market Strategic Shifts & Innovations
Siliconization chemistry advances and ceramic coating deposition are redefining plunger-barrel interaction dynamics, eliminating the need for separate lubricant formulations in high-precision applications.
Surface-modified borosilicate glass is consolidating its position as the default material for ultra-low carryover chromatography. Pharmaceutical quality control laboratories in Basel and Boston are mandating proprietary silanol deactivation treatments for peptide mapping workflows. This specification tightening is compressing supplier qualification timelines to 12-18 months.
EU MDR Article 10 technical documentation requirements are forcing systematic revalidation of polymer biocompatibility portfolios. EMA notified bodies are rejecting legacy ISO 10993 test summaries without updated chemical characterization under ICH Q3D elemental impurity guidelines. German syringe manufacturers are responding with dedicated regulatory affairs teams embedded in notified body pre-submission programs.
Consolidated procurement frameworks at multinational pharmaceutical conglomerates are displacing fragmented laboratory purchasing. Thermo Fisher and Merck KGaA are capturing multi-year sole-source agreements for chromatography consumables that bundle micro syringe volumes with instrument service contracts. This channel compression is most visible in Massachusetts and North Rhine-Westphalia, where centralized procurement offices now control site-level reagent selection.
Micro Syringes Market Segmentation
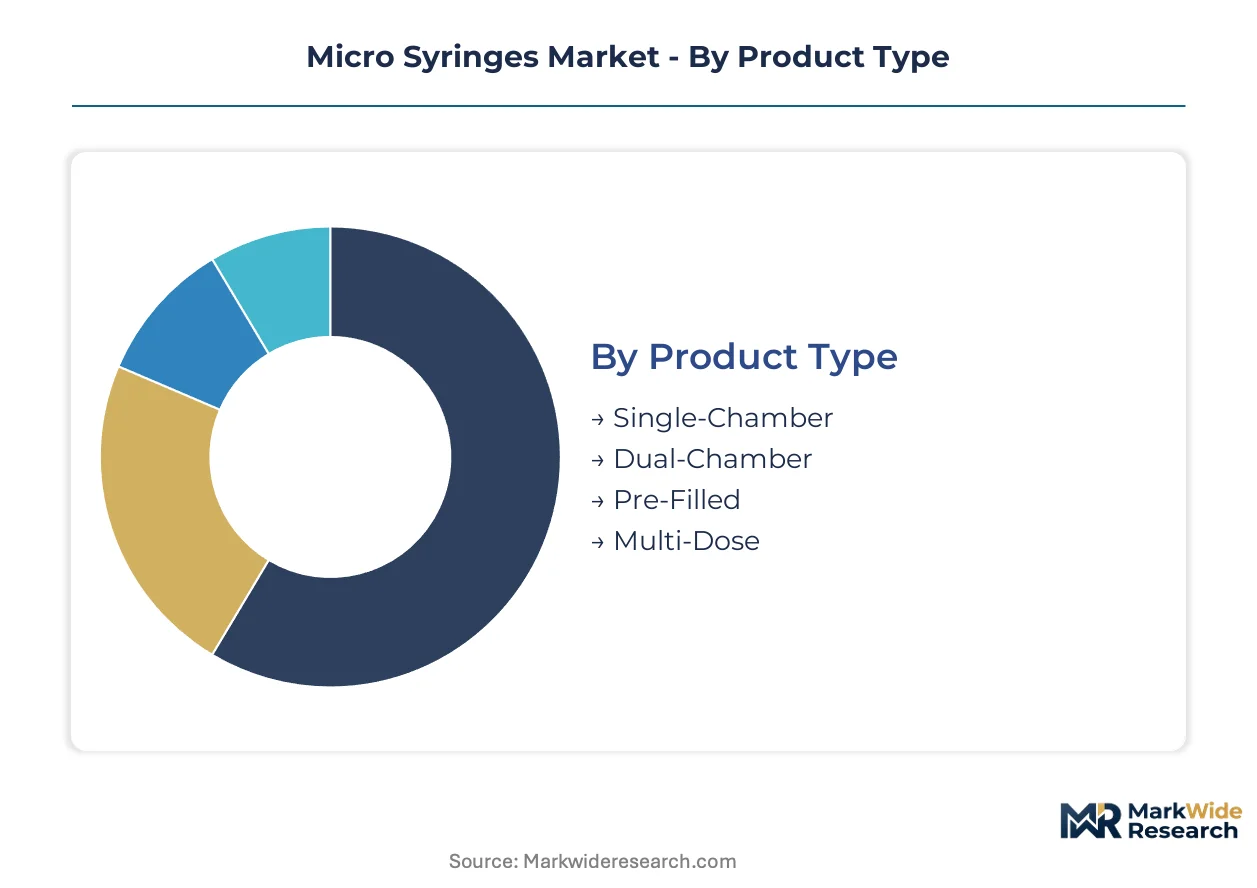
Micro syringe procurement patterns diverge sharply across clinical workflows, material specifications, and regulatory exposure levels. Understanding these fracture lines reveals where pricing power concentrates and which technical specifications command premium positioning.
Product Type:
Volume scale and contamination risk tolerance separate buyers across chamber configurations and fill states.
- Pre-Filled:Factory-sealed drug-product integration eliminates compounding variability for biologics requiring cold-chain integrity. Swissmedic-registered manufacturing sites in Basel and Bern supply European vaccination networks where single-use sterility is non-negotiable.
- Single-Chamber:Conventional borosilicate barrel construction dominates high-performance liquid chromatography workflows where chemical inertness determines analytical validity. Massachusetts pharmaceutical quality control laboratories specify these for peptide mapping protocols with sub-nanogram detection thresholds.
- Dual-Chamber:Lyophilized drug and diluent separation enables reconstitution-at-point-of-use for unstable biologics.
- Multi-Dose:Bulk reservoir designs serve anesthesia suites with high-frequency dosing requirements and controlled substance tracking mandates.
Single-Chamber leads volumes today; Pre-Filled is gaining share fastest.
Material:
Application chemistry and disposability economics drive material selection across analytical and therapeutic settings.
- Glass:Borosilicate formulations with silanol-deactivated surfaces deliver zero carryover for aggressive solvent systems in chromatography. Schott AG tubing supply constraints in Mainz force German manufacturers into 12-month forward contracting to secure pharmaceutical-grade feedstock.
- Polypropylene:Cyclic olefin polymer variants enable gamma-sterilizable single-use delivery at cost points compatible with mass vaccination campaigns. Indian CDSCO-registered fill-finish facilities in Hyderabad import European polymer micro syringe volumes for export-oriented sterile injectable production.
- Stainless Steel:Reusable precision instruments persist in research chromatography where solvent compatibility exceeds polymer limits.
- Silicone:Plunger lubrication and barrel coating applications reduce protein aggregation in sensitive biologic delivery.
Glass dominates analytical revenue; polypropylene expands most quickly in clinical disposables.
End User:
Procurement centralization and regulatory scrutiny intensity vary dramatically across care settings.
- Clinical Laboratories:Integrated chromatography workflows at Thermo Fisher and Agilent instrument installations standardize on pre-calibrated micro syringe modules. Centralized procurement offices in North Rhine-Westphalia now mandate sole-source consumable agreements that bundle syringe volumes with service contracts.
- Hospitals:EU MDR Class IIa device traceability requirements lock hospital systems into validated supplier relationships with batch-level documentation capabilities.
- Pharmacies:Compounding specialization drives demand for precision dosing in hormone therapy and ophthalmic preparation.
- Home Care Settings:Patient-administered insulin delivery prioritizes ergonomic design and contamination-proof packaging over analytical precision.
Clinical Laboratories lead absolute spend; Home Care Settings show steepest expansion trajectory.
Application:
Therapeutic protocol standardization and reimbursement pathways determine specification rigidity.
- Insulin Delivery:Pre-filled micro syringe adoption accelerates as diabetes management protocols prioritize dosing accuracy and infection control. German statutory health insurance reimbursement frameworks now favor disposable precision instruments over traditional vial-and-syringe compounding.
- Vaccination:Mass immunization campaigns require supply security at billion-unit annual scales, favoring polymer variants with established sterilization validation.
- Anesthetic Procedures:Controlled substance tracking integrates with precision dosing in operating theater workflows.
- Drug Administration:Biologic therapy expansion compresses tolerances for sub-microliter delivery in oncology and autoimmune protocols.
Drug Administration commands premium pricing; Insulin Delivery climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision glass instrument manufacturing traces its commercial roots to Swiss and German optical workshops of the late nineteenth century. Contemporary demand clusters around pharmaceutical quality control laboratories and biologic fill-finish facilities. Regulatory stringency and specialized apprenticeship pipelines perpetuate geographic concentration.
Germany
Pharmaceutical-grade borosilicate tubing demand from Schott AG in Mainz anchors European micro syringe supply chains. EU MDR Article 10 technical documentation requirements force systematic material revalidation across Baden-Württemberg manufacturing clusters. Stuttgart-area precision grinding workshops supply bore-machined barrels to chromatography instrument OEMs.
United States
FDA quality system regulations and 21 CFR Part 820 compliance burdens lock Massachusetts pharmaceutical laboratories into validated supplier relationships. Greater Boston peptide mapping workflows mandate silanol-deactivated glass surfaces for sub-nanogram detection thresholds. Thermo Fisher Scientific anchors integrated chromatography consumable procurement through multi-year sole-source agreements.
Switzerland
Swissmedic registration requirements for sterile injectable devices sustain premium manufacturing margins in Basel and Bern. Hamilton Company leverages century-old precision engineering heritage for analytical instrumentation applications. The country's dual vocational training system feeds micrometer-tolerance machining expertise into medical device production.
India
CDSCO-registered sterile injectable facilities in Hyderabad and Bangalore import European glass micro syringe volumes for export-oriented fill-finish operations. The country's pharmaceutical contract manufacturing expansion creates pull-through demand for precision dosing instruments serving US and EU markets. German suppliers maintain forward-contracting relationships with Indian CMOs.
Japan
PMDA pharmaceutical manufacturing standards and JIS quality certifications constrain supplier qualification timelines to 18-24 months. Shimadzu Corporation anchors domestic chromatography instrument ecosystems with integrated consumable specifications. Tokyo-area analytical laboratories drive demand for ultra-low carryover surface treatments in peptide quantification workflows.
Micro Syringes Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the micro syringe value chain. Borosilicate glass tubing foundries and precision grinding workshops represent distinct capability layers with divergent capital intensity. The market structures around three archetypes: integrated instrument OEMs, specialized consumable manufacturers, and materials-technology hybrids. Dominant competitive moves include backward integration into borosilicate supply and geographic expansion through notified body pre-submission programs.
Among integrated instrument OEMs, Thermo Fisher Scientific and Agilent Technologies exemplify the ecosystem-anchoring archetype through chromatography workflow bundling. Hamilton Company occupies a position within the specialized precision engineering tier, leveraging Swiss manufacturing heritage. Shimadzu Corporation represents the Asia-Pacific instrument-integration model with domestic regulatory alignment.
| Leading Market Players |
|---|
| Hamilton Company |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| PerkinElmer Inc. |
| Innovative Labor Systeme (ILS) |
| GL Science Inc. |
| Shimadzu Corporation |
| Trajan Scientific and Medical |
| ITO Corporation |
| Others |
Cost & Logistics Intelligence
Precision grinding apprenticeships in Stuttgart and Basel generate labor-cost differentials that widen spreads between premium borosilicate glass micro syringes and economy polymer variants. German and Swiss technical institutes require 5-7 year training pipelines that constrain skilled machinist supply, compressing margins at the mid-tier while sustaining pricing power at the precision-engineered premium.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the micro syringe market by certification grade and volume scale. Premium tiers command positioning through EU MDR Article 10 compliance documentation and silanol-deactivated surface treatments validated for peptide mapping workflows. Cost compression in the economy tier intensifies as Indian CDSCO-registered fill-finish facilities import European volumes for export-oriented production. Clinical laboratories demonstrate lowest price sensitivity due to bundled chromatography service contracts, while mass vaccination procurement offices exhibit highest sensitivity to per-unit disposability economics.
Supply Chain Analysis
EU Green Deal domestic-content preferences are reshaping sourcing decisions across European medical device procurement frameworks. Pharmaceutical-grade borosilicate tubing concentrates in Germany and Switzerland, with Schott AG in Mainz and DWK Life Sciences controlling upstream feedstock. Precision grinding workshops draw from specialized apprenticeship pipelines in Baden-Württemberg and Basel-Stadt. Single-source vulnerability in glass tubing supply exposes downstream manufacturers to allocation constraints during capacity tightness. Distribution runs through consolidated procurement frameworks at multinational pharmaceutical conglomerates and integrated instrument OEM ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The micro syringe market represents a late-cycle quality story as biologic therapy expansion forces pharmaceutical quality control laboratories toward sub-nanogram detection thresholds that only premium silanol-deactivated glass surfaces can deliver.
For Market Incumbents: Deepen backward integration into borosilicate tubing supply to insulate against Schott AG and DWK Life Sciences allocation constraints. Expand precision grinding capacity in Stuttgart-area workshops to capture EU MDR compliance premiums. Lock hospital systems into multi-year sole-source agreements before centralized procurement frameworks fully consolidate. For New Entrants and Emerging Players: EU MDR Article 10 technical documentation requirements in Europe open a window for regulatory affairs specialists who can compress 18-24 month supplier qualification timelines. Target Indian CDSCO-registered sterile injectable facilities in Hyderabad and Bangalore with polymer micro syringe offerings for export-oriented fill-finish operations. Lead with gamma-sterilization validation capabilities and closed-loop recycling credentials to differentiate against established European suppliers. For Investors and Strategic Acquirers: Integrated chromatography instrument OEMs are the most active acquirer in this space, seeking consumable bundling opportunities that anchor recurring revenue streams. Over a 5-10 year horizon, precision grinding skill scarcity in German and Swiss technical institutes sustains manufacturing moats for incumbent specialists. Watch for FDA quality system regulation harmonization with EU MDR as the inflection signal that triggers cross-Atlantic consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Pre-Submission Program | Embedded regulatory affairs teams at German manufacturers accelerate EU MDR Article 10 compliance timelines. |
| Backward Integration into Borosilicate Supply | Captive tubing production insulates syringe manufacturers from Schott AG allocation constraints. |
| Silanol Deactivation Treatment Investment | Proprietary surface chemistry commands premium positioning in Basel and Boston peptide mapping workflows. |
| Indian CMO Forward Contracting | CDSCO-registered facilities in Hyderabad lock in European glass micro syringe volumes for US and EU export. |
| Closed-Loop Recycling Certification | EU Green Deal procurement preferences favor suppliers with renewable energy certificates and borosilicate recycling programs. |
Research Approach
Multiple input streams — primary interviews with precision grinding workshop supervisors, regulatory affairs directors at German manufacturers, and chromatography laboratory managers — were reconciled against secondary validation from FDA 510(k) filings, EMA notified body guidance documents, and EU MDR technical documentation databases. Bottom-up triangulation across product-type, material, and end-user segmentation dimensions anchored volume estimates, while top-down cross-checks against pharmaceutical fill-finish facility buildout announcements refined demand projections.
Data-stream reconciliation across the analysis window applied a structured analytical framework modeling volume scale, contamination risk tolerance, and regulatory exposure intensity as core segmentation drivers. CAGRs were derived from pharmaceutical biologic therapy pipeline expansion rates and chromatography instrument replacement cycles. Industry-specific forecast inputs included EU MDR implementation timelines and Indian CDSCO sterile injectable facility registration trajectories.
Revisions become necessary when EU MDR notified body capacity constraints delay supplier qualification timelines, or when borosilicate glass tubing supply disruptions alter capacity expansion assumptions. Forecasts reflect documented assumptions about apprenticeship pipeline throughput and polymer substitution technical limitations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cervical Fusion Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Gel Implants Market
Medical Devices
Brachytherapy Market
Medical Devices
Annuloplasty System Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Artificial Respirator Market
Medical Devices
Ultrasound Stimulator Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Spectacle Lens Market