
 Middle East and Africa Hip and Knee Reconstruction Devices Market | 2026-2036
Middle East and Africa Hip and Knee Reconstruction Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hip and Knee Reconstruction Devices Market Intelligence
Premium-grade titanium alloy specifications are redrawing procurement standards across the Middle East and Africa hip and knee reconstruction devices landscape. Stryker Corporation leverages its cementless implant portfolio to anchor positions in Gulf state hospital tenders. Zimmer Biomet sustains competitive footing through specialized modular knee systems tailored to regional anatomical variations.
Hip and knee reconstruction devices encompass prosthetic implants and surgical instrumentation engineered from cobalt-chrome alloys, ultra-high molecular weight polyethylene, and porous titanium coatings designed to restore joint biomechanics following osteoarthritic degeneration or traumatic injury. Cementless implant technology captures expanding preference among orthopedic surgeons seeking biological fixation and reduced revision rates in younger, active patient cohorts. Knee implant demand outpaces hip reconstruction across the region, while ambulatory surgical centers represent the fastest-growing end user channel as same-day arthroplasty protocols gain clinical acceptance.
Saudi Food and Drug Authority and South Africa's Health Products Regulatory Authority enforce pre-market approval pathways and post-market surveillance mandates that elevate barriers for non-compliant manufacturers. The EU Medical Device Regulation's extraterritorial influence shapes quality expectations for imported devices entering Middle Eastern and African markets through European distribution channels. Stakeholders must monitor reimbursement policy shifts in national health insurance schemes and the pace of local manufacturing incentives to calibrate capital deployment and partnership strategies.
Market Dynamics
Cementless implant fixation is redrawing procurement criteria across Middle East and Africa hip and knee reconstruction, as Saudi Arabia's Ministry of Health and South Africa's public hospital networks prioritize biological osseointegration over traditional cemented alternatives in tender specifications.
Growth Catalysts
- Saudi Vision 2030 Health Transformation:Government-funded joint replacement programs for citizens over 65 are expanding arthroplasty capacity at King Faisal Specialist Hospital and other tertiary centers.
- Porous titanium coating advances:Sintered bead and plasma-sprayed surfaces enable faster bone ingrowth, reducing revision surgery rates in younger, active patient cohorts across Gulf state private hospitals.
- Ambulatory surgical center expansion:Same-day discharge protocols for total knee arthroplasty are gaining clinical acceptance at Dubai Healthcare City and similar integrated medical zones.
Market Restraints
- Cobalt-chrome alloy supply concentration:Foundry capacity for medical-grade castings concentrates in European and East Asian suppliers, exposing procurement to freight cost volatility and extended lead times.
- SFDA pre-market approval timelines:Saudi Food and Drug Authority's technical documentation requirements and clinical data mandates extend product registration cycles for non-established manufacturers.
- Revision surgery burden:Higher-than-expected polyethylene wear and osteolysis rates in initial implant generations create downstream cost pressures on national health insurance schemes.
Strategic Opportunities
- Egyptian manufacturing incentives:Special Economic Zone provisions and medical device localization requirements under the country's industrial development strategy create assembly and sterilization facility opportunities.
- Modular knee system customization:Anatomical sizing databases from regional patient populations enable implant geometry tailored to Middle Eastern and African skeletal morphologies.
- Digital surgical planning integration:Pre-operative templating software and patient-specific instrumentation convergence with 3D imaging workflows is compressing operative time and implant alignment variance.
Industry Challenges
- Orthopedic surgeon training pipelines:Fellowship programs in arthroplasty techniques remain concentrated in South Africa, Saudi Arabia, and UAE, creating access bottlenecks for patients in North Africa and Sub-Saharan markets.
- Implant traceability infrastructure:South Africa's Health Products Regulatory Authority mandates unique device identification compliance that requires hospital IT system upgrades and staff retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hip and Knee Reconstruction Devices Market |
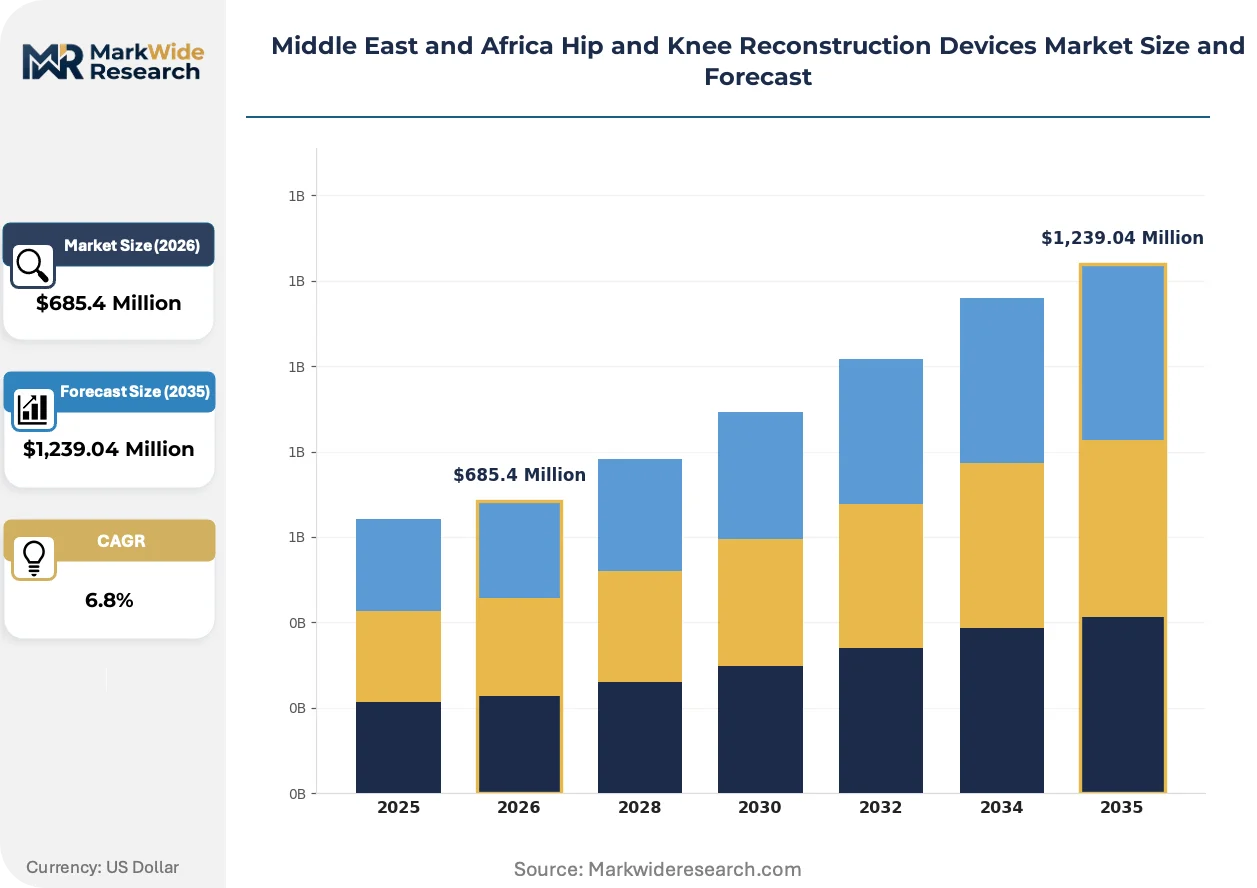
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hip Implants, Knee Implants, Surgical Instruments, Accessories Technology: Cemented Implants, Cementless Implants, Hybrid Implants, Modular Implants End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Distribution Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Johnson & Johnson, Stryker Corporation, Zimmer Biomet, Smith & Nephew, Medtronic, DePuy Synthes, B. Braun Melsungen AG, Arthrex, Medacta International, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hip and Knee Reconstruction Devices Market Strategic Shifts & Innovations
Biological fixation surfaces and digital surgical workflows are compressing traditional cemented implant dominance while regulatory traceability mandates reshape hospital procurement infrastructure across the Middle East and Africa.
3D-printed patient-specific instrumentation is displacing conventional off-the-shelf cutting guides in high-volume arthroplasty centers. King Faisal Specialist Hospital and private surgical groups in Dubai are adopting titanium-printed jigs matched to pre-operative CT scans. This displacement is compressing operative variability and reducing alignment outliers that drive early implant failure.
SFDA's alignment with EU Medical Device Regulation technical standards is elevating quality documentation requirements for imported hip and knee reconstruction devices. Manufacturers must submit clinical evaluation reports and post-market surveillance protocols that mirror European notified body expectations. South African private hospital chains are responding by consolidating supplier panels to vendors with established CE marking and SFDA dual compliance.
Hospital procurement departments are unbundling implant purchasing from instrumentation and after-sales service contracts. Saudi Arabia's National Unified Procurement Company and similar Gulf state centralized buying entities are negotiating device-only pricing while sourcing surgical training and technical support separately. This disintermediation is most visible in Riyadh and Jeddah public hospital networks, where tender structures now separate capital equipment from consumable implant bundles.
Middle East and Africa Hip and Knee Reconstruction Devices Market Segmentation
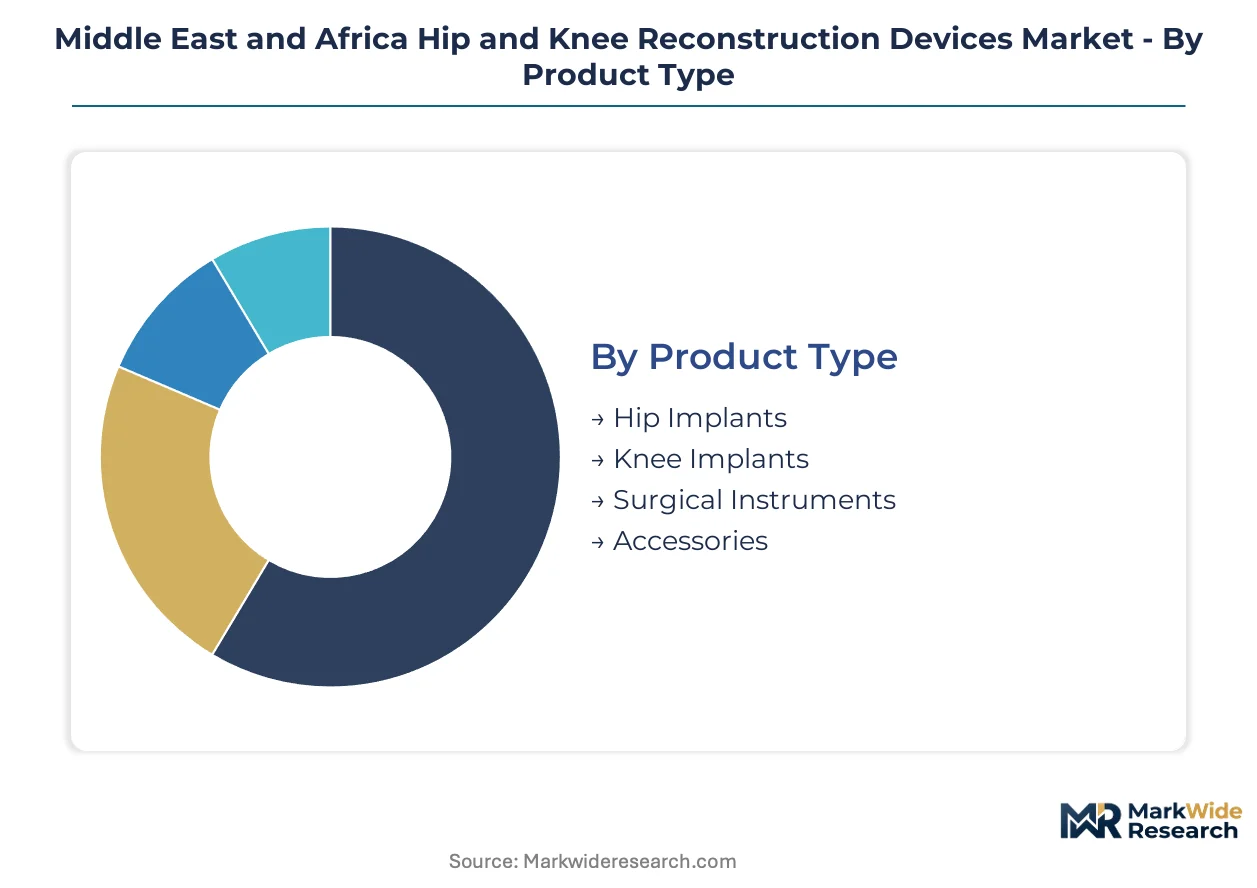
Segmentation reveals how procurement patterns diverge across Middle East and Africa hip and knee reconstruction devices. Saudi Arabia's centralized buying and South Africa's private hospital networks create distinct demand profiles that reshape product positioning.
Product Type:
Domestic demand concentrates in implants for public hospital tenders across Saudi Arabia and South Africa, while export-led surgical instruments flow through Dubai's distribution hubs serving North African markets.
- Hip Implants:Cobalt-chrome femoral stems and acetabular cups with porous titanium coatings dominate tertiary hospital procurement in Riyadh and Jeddah. Saudi Arabia's Ministry of Health prioritizes cementless fixation variants in national tender specifications for patients under 65.
- Knee Implants:Ultra-high molecular weight polyethylene tibial inserts and modular femoral components capture volume across Gulf state private hospitals. Demand concentrates in fixed-bearing designs for King Faisal Specialist Hospital and rotating-platform systems for high-activity patient cohorts in Dubai.
- Surgical Instruments:Reusable cutting guides and alignment jigs flow through Egyptian distribution channels serving North African orthopedic centers.
- Accessories:Bone cement, drainage systems, and wound closure materials complete procedure bundles in South African public hospital networks.
Knee implants hold the largest share; momentum sits with hip implants as younger patient eligibility expands.
Technology:
Cost tier stratification separates premium biological fixation from economy cemented alternatives, with hybrid designs occupying the mid-tier in price-sensitive North African markets.
- Cemented Implants:Polymethylmethacrylate bone cement fixation remains standard for elderly osteoporotic patients across South Africa's public hospital system. Lower upfront costs and established surgical training sustain procurement despite higher revision rates.
- Cementless Implants:Sintered bead and plasma-sprayed titanium surfaces enable biological osseointegration without cement. Saudi Food and Drug Authority tenders now specify cementless fixation for patients under 60, compressing traditional cemented dominance.
- Hybrid Implants:Cemented femoral stems paired with cementless acetabular cups balance cost and performance in Egyptian private hospital procurement.
- Modular Implants:Adjustable neck angles and offset configurations accommodate anatomical variation across Middle Eastern and African patient populations.
Cemented implants retain volume leadership; cementless variants are climbing the fastest as biological fixation protocols standardize.
End User:
Application patterns separate acute surgical intervention from post-operative rehabilitation, with ambulatory migration reshaping capital equipment deployment.
- Hospitals:Tertiary medical centers with dedicated orthopedic departments perform complex revision surgeries and manage high-risk patient cohorts. King Faisal Specialist Hospital and similar institutions anchor implant volume through bundled procurement contracts.
- Ambulatory Surgical Centers:Same-day discharge protocols for total knee arthroplasty are gaining clinical acceptance at Dubai Healthcare City facilities. Compressed length-of-stay targets and specialized nursing protocols enable cost-efficient joint replacement outside traditional hospital settings.
- Specialty Clinics:Orthopedic-focused practices in Johannesburg and Cairo concentrate on diagnostic workup and pre-operative patient optimization.
- Rehabilitation Centers:Post-surgical physical therapy facilities in Riyadh and Cape Town manage recovery protocols and functional outcome monitoring.
Hospitals command the dominant share; ambulatory surgical centers represent the steepest expansion trajectory as same-day protocols proliferate.
Distribution Channel:
Customer type segmentation separates institutional procurement from individual practitioner purchasing, with digital channels capturing incremental share in secondary markets.
- Direct Sales:Manufacturer field representatives negotiate directly with Saudi Arabia's National Unified Procurement Company and South African private hospital chains. Relationship-based contracting and technical training bundling sustain this channel for high-value implant systems.
- Distributors:Local medical device distributors with regulatory registration capabilities and logistics infrastructure serve fragmented demand across Egypt, Morocco, and Sub-Saharan markets. Inventory holding and credit extension functions address working capital constraints in smaller hospital networks.
- Online Sales:Digital procurement platforms capture consumables and replacement instrumentation orders from independent orthopedic practices.
- Others:Group purchasing organizations and consignment arrangements serve niche segments with irregular demand patterns.
Direct sales holds the largest share; distributor channels are gaining share fastest as manufacturers seek geographic coverage without direct regulatory registration burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade foundry capacity for cobalt-chrome and titanium alloys concentrates in European and East Asian suppliers, exposing Middle East and Africa procurement to freight cost volatility and extended lead times. Hospital networks across the region respond by consolidating supplier relationships and prioritizing vendors with established regulatory compliance in multiple jurisdictions.
Saudi Arabia
The Ministry of Health funds joint replacement surgeries for citizens over 65 through centralized procurement at King Faisal Specialist Hospital and other tertiary centers. SFDA pre-market approval pathways mandate clinical evaluation reports that mirror EU MDR technical standards. Riyadh and Jeddah public hospital networks now unbundle implant purchasing from instrumentation and service contracts.
South Africa
Private hospital chains anchor implant volume through bundled procurement contracts, while public networks manage revision surgery backlogs from earlier polyethylene wear generations. The Health Products Regulatory Authority enforces unique device identification compliance requiring hospital IT system upgrades. Johannesburg orthopedic practices concentrate on diagnostic workup and pre-operative patient optimization.
United Arab Emirates
Dubai Healthcare City facilities pioneer same-day discharge protocols for total knee arthroplasty, compressing length-of-stay targets through specialized nursing protocols. MOHAP registration requirements align with international quality documentation standards for imported devices. Dubai's distribution hubs serve as export channels for surgical instruments flowing to North African markets.
Egypt
Special Economic Zone provisions under the country's industrial development strategy create assembly and sterilization facility opportunities for implant manufacturers. The national pharmaceutical regulator maintains pre-market approval timelines that extend product registration cycles for non-established manufacturers. Cairo private hospitals balance cost and performance through hybrid cemented-cementless procurement strategies.
Israel
Orthopedic research clusters advance digital surgical planning integration with pre-operative templating software and patient-specific instrumentation. The national medical device regulator enforces post-market surveillance mandates that elevate barriers for non-compliant manufacturers. Tel Aviv-area medical technology firms develop 3D-printed cutting guides for high-volume arthroplasty centers.
Middle East and Africa Hip and Knee Reconstruction Devices Market Key Industry Players
Concentration sits with diversified multinational medical technology conglomerates that leverage established regulatory registrations and hospital contracting relationships across Gulf state and South African markets. The vendor base separates into three strategic archetypes: integrated implant-instrumentation platforms, specialized modular knee system providers, and regional distribution-focused intermediaries. Competitive positioning depends on cementless implant portfolio breadth, anatomical sizing database development, and compliance with SFDA and EU MDR dual certification requirements. M&A activity targets digital surgical planning capabilities, while strategic partnerships with ambulatory surgical center operators expand same-day protocol adoption.
Among diversified multinational platforms, Johnson & Johnson and Stryker Corporation exemplify archetypes with integrated portfolios spanning hip and knee reconstruction. Zimmer Biomet occupies a position emphasizing modular system customization. Smith & Nephew, Medtronic, and DePuy Synthes represent additional scale-driven participants, while B. Braun Melsungen AG and Arthrex sit within specialized instrumentation tiers. Medacta International anchors the mid-cap specialist segment.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Stryker Corporation |
| Zimmer Biomet |
| Smith & Nephew |
| Medtronic |
| DePuy Synthes |
| B. Braun Melsungen AG |
| Arthrex |
| Medacta International |
| Others |
Cost & Logistics Intelligence
Long-term bundled procurement contracts with Saudi Arabia's National Unified Procurement Company lock in supply access for cementless implant portfolios while anchoring price visibility across multi-year tender cycles. These arrangements tie volume commitments to fixed pricing tiers, insulating hospital networks from cobalt-chrome alloy freight volatility while constraining manufacturer margin flexibility.
Pricing Analysis
SFDA pre-market approval pathways dictate the pricing tier structure across Middle East and Africa hip and knee reconstruction devices. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked dual-certified systems from single-territory registrations and unbundled device-only tenders. Price differentiation rests on clinical data package completeness and after-sales service bundling. Cost compression in economy cemented tiers is intensifying because South African public hospital networks are unbundling instrumentation from implant purchases. Egyptian private hospitals exhibit highest price sensitivity; Gulf state tertiary centers demonstrate lowest sensitivity due to government-funded reimbursement pools.
Supply Chain Analysis
Germany and Switzerland anchor medical-grade cobalt-chrome foundry capacity for femoral stem castings, while Japan and the United States supply plasma-sprayed titanium coating equipment. Raw material flows draw from South African chromite ore processing, Chinese rare earth refining for alloy additives, and Belgian polyethylene resin production. Single-source vulnerability concentrates in European medical-grade casting capacity, exposing procurement to transcontinental logistics chokepoints. Distribution runs through Dubai's Jebel Ali Free Zone logistics hubs serving North African hospital networks, with direct sales teams managing Saudi and South African institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as ambulatory surgical center penetration for same-day knee arthroplasty remains below structural capacity across Gulf state medical zones.
For Market Incumbents: Shield cementless implant market share by accelerating porous titanium coating capacity additions in Saudi Arabia's King Salman Medical City industrial zone. Lock in King Faisal Specialist Hospital procurement committees through exclusive digital surgical planning software licensing. Regulatory compliance investment in SFDA-EU MDR dual certification creates defensible positioning against emerging modular knee system specialists. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany or the Netherlands enables rapid SFDA technical documentation alignment. Target Egyptian Special Economic Zone assembly operations as the most penetrable geography, leveraging localization incentives under industrial development provisions. Go-to-market angle centers on unbundled device-only pricing for North African distributor channels serving fragmented private hospital demand. For Investors and Strategic Acquirers: Digital surgical planning software developers with FDA-cleared pre-operative templating platforms represent the priority acquisition archetype. Long-term viability frames around cementless biological fixation protocol standardization compressing revision surgery burden across national health insurance schemes. Signal to watch: MOHAP registration timeline compression for patient-specific instrumentation categories indicating ambulatory protocol maturation.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Dual Certification Pathway | CE marking alignment accelerates Saudi tender eligibility for cementless implant portfolios. |
| Hospital System Partnership | King Faisal Specialist Hospital contracting anchors volume through bundled procurement structures. |
| Software Companion Development | Pre-operative templating integration compresses alignment variance in Dubai surgical centers. |
| Reimbursement Strategy | Saudi Vision 2030 health transformation funds expand arthroplasty eligibility for aging cohorts. |
| Geographic Manufacturing Footprint | Egyptian Special Economic Zone assembly addresses localization requirements for North African markets. |
Research Approach
A spread of perspectives from orthopedic surgeons, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions driving volume forecasts. Primary fieldwork combined structured interviews with Saudi Arabia's National Unified Procurement Company officials and South African private hospital chain supply chain directors. Secondary validation drew from SFDA medical device registration databases, EU MDR notified body certification records, and hospital procurement tender documentation. Bottom-up implant shipment data triangulated against top-down health expenditure projections across the analysis window.
Segmentation dimensions modeled include product type, fixation technology, end-user facility tier, and distribution channel structure throughout the forecast period. CAGRs derived from procedure volume growth elasticities tied to aging demographic penetration and ambulatory surgical center capacity expansion. Industry-specific forecast inputs incorporated cementless implant adoption curves in Saudi tertiary hospitals and same-day discharge protocol penetration rates at Dubai Healthcare City facilities.
Underlying assumptions cover SFDA approval timeline stability and cobalt-chrome alloy supply continuity, with deviation risk concentrated in Egyptian regulatory registration delays and freight cost volatility from European foundry sources. Forecasts reflect these documented assumptions with sensitivity scenarios for procurement unbundling acceleration. Recalibration cycles align with material shifts in national health insurance reimbursement policy and ambulatory surgical center licensing frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Heating Pads Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
China Diabetes Devices Market
Medical Devices
Endoscope Flushing Pumps Market
Medical Devices
APAC AMH Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Wearable Defibrillators Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Oxygen Generator Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Creatinine Meter Market
Medical Devices
Global Tumor Tracking Systems Market