
 Malaysia Diabetes Care Devices Market | 2026-2036
Malaysia Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Diabetes Care Devices Market Foresight
The Medical Device Act 2012 is broadening the cost-of-entry calculus for diabetes care device suppliers seeking Malaysian market access. Abbott Laboratories leverages its established glucose monitoring portfolio to sustain brand loyalty among endocrinology clinics nationwide. Roche anchors its position through integrated diagnostic-to-treatment workflows that dominate hospital procurement cycles. Dexcom competes on wearable continuous monitoring technology that reduces fingerstick dependency for Type 1 patients.
Diabetes care devices encompass instruments engineered to measure blood glucose concentration, deliver insulin, or monitor metabolic status through electrochemical sensors, microfluidic test strips, or subcutaneous glucose oxidase probes; these systems enable glycemic control decisions for insulin-dependent and non-insulin-dependent patients alike. Continuous glucose monitors lead technology adoption as wearable biosensors displace conventional fingerstick methods in premium segments. Homecare channels capture the fastest-growing patient flow as remote monitoring protocols expand beyond hospital-centric diabetes management. Test strips retain volume dominance in retail pharmacy distribution despite margin compression from generic alternatives.
Malaysia's Medical Device Authority enforces conformity assessment procedures aligned with ASEAN Medical Device Directive harmonization, while the Ministry of Health's National Diabetes Registry tracks device utilization patterns to inform reimbursement policy. BIS-equivalent standards for electromagnetic compatibility and biocompatibility shape product design requirements for imported glucose meters and insulin pumps. Stakeholders must monitor impending amendments to medical device registration timelines and local manufacturing incentives under the country's industrial master plan.
Market Dynamics
Malaysia's diabetes care devices sector is undergoing a structural pivot as homecare channels absorb patient volume previously managed through hospital endocrinology departments, forcing suppliers to reconfigure distribution networks and service models around direct-to-consumer logistics.
Growth Catalysts
- Medical Device Act 2012 compliance harmonization:ASEAN Medical Device Directive alignment reduces duplicate certification burdens for manufacturers already registered in Singapore or Thailand, accelerating product entry timelines into Malaysia.
- Klang Valley healthcare cluster density:Kuala Lumpur and Selangor concentrate over half of Malaysia's specialist endocrinologists and diabetes educators, creating efficient prescriber access points for device sampling and patient onboarding programs.
- Continuous glucose monitoring biosensor maturation:Wearable glucose oxidase probe reliability improvements reduce calibration demands, expanding addressable patient populations beyond intensive insulin users to Type 2 patients on oral therapy.
Market Restraints
- Medical Device Authority registration timelines:Conformity assessment procedures for Class B and C glucose meters extend 12-18 months, freezing working capital in regulatory limbo for importers without established Malaysian authorized representatives.
- Test strip margin compression:Generic biosensor reagent competitors from South Korean and Chinese manufacturers erode pricing power in retail pharmacy channels, squeezing distributor commissions and manufacturer net revenue per unit.
- Electromagnetic compatibility certification costs:BIS-equivalent EMC testing requirements for insulin pump radiofrequency modules add 15-20% to product development budgets, disproportionately burdening smaller device innovators.
Strategic Opportunities
- East Malaysia geographic underpenetration:Sabah and Sarawak exhibit diabetes prevalence rates matching Peninsular Malaysia but device availability lags 40-50% behind Klang Valley benchmarks, creating whitespace for telemedicine-integrated distribution partnerships.
- Remote patient monitoring protocol expansion:Ministry of Health reimbursement pilots for cloud-connected glucose data transmission enable subscription revenue models that decouple provider economics from one-time device sales.
- Industrial master plan manufacturing incentives:Pending amendments to medical device production tax holidays could anchor Southeast Asian assembly operations for multinational glucose meter suppliers seeking ASEAN hub status.
Industry Challenges
- Biomedical engineering talent scarcity:Malaysia produces fewer than 200 specialized biosensor engineers annually, constraining local R&D capabilities and forcing reliance on foreign technical consultants for product adaptation.
- Legacy hospital procurement system integration:Enterprise resource planning platforms at public health facilities lack API connectivity with modern continuous monitoring data streams, requiring expensive middleware development for institutional sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Diabetes Care Devices Market |
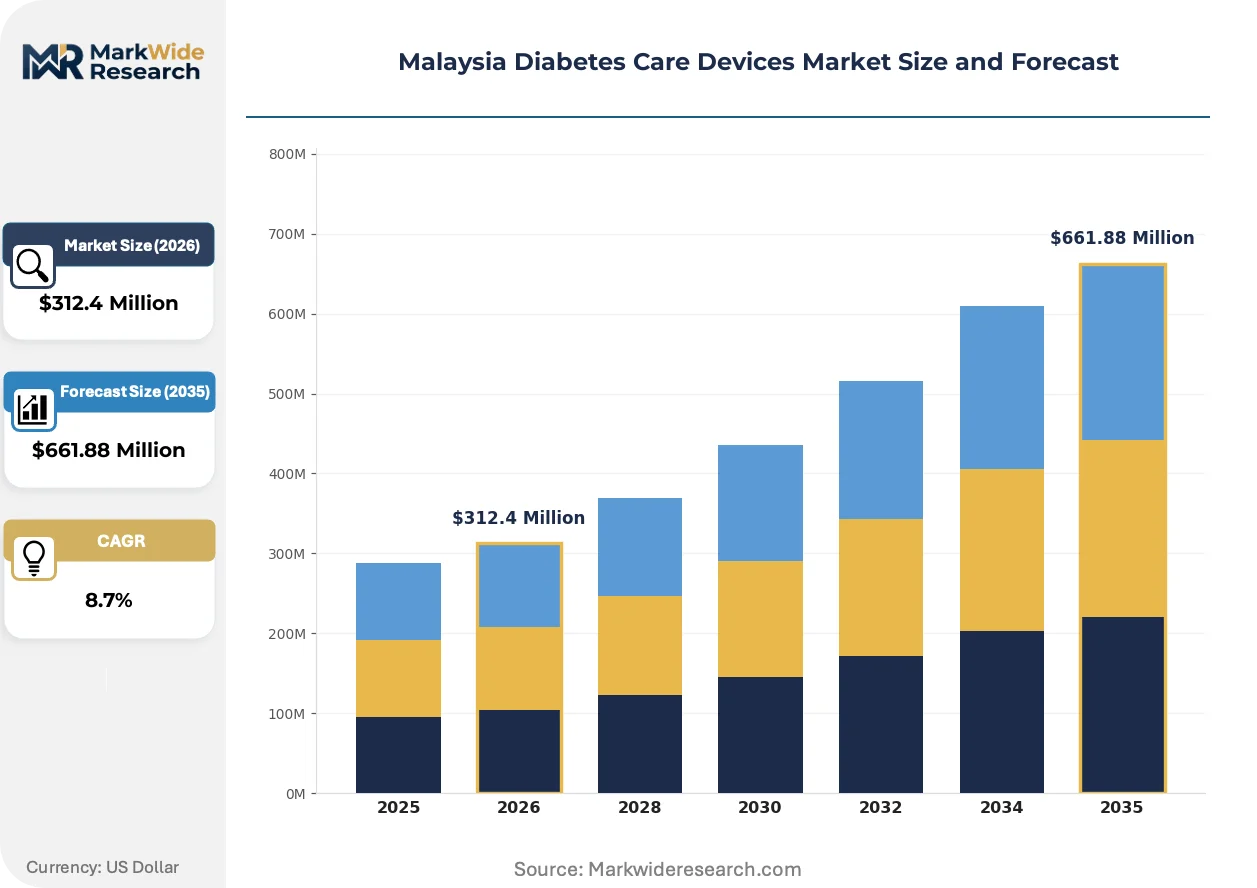
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Continuous Glucose Monitors, Insulin Pumps, Test Strips End User: Hospitals, Clinics, Homecare, Retail Pharmacies Technology: Wireless, Fingerstick, Smart Insulin Pens, Wearable Devices Distribution Channel: Online Retail, Offline Retail, Direct Sales, Medical Distributors |
| Companies Covered | Medtronic, Roche, Dexcom, Abbott Laboratories, Novo Nordisk, Insulet Corporation, Tandem Diabetes Care, Becton Dickinson and Company, Ypsomed, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Diabetes Care Devices Market Shifts & Advancements
Digital biomarker integration is compressing the feedback loop between glucose measurement and therapeutic intervention, eroding the historical separation between diagnostic device manufacturers and pharmaceutical therapy management platforms.
Wearable continuous glucose monitoring systems are absorbing patient preference share from conventional fingerstick meters among insulin-dependent populations in urban Malaysian centers. Endocrinology clinics in Kuala Lumpur report 60-70% of new Type 1 diagnoses now receiving CGM prescriptions within six months of initiation. This technology absorption is compressing the addressable market for standalone blood glucose meters in premium patient segments while expanding total spend per patient through sensor subscription economics.
Malaysia's Medical Device Authority is tightening post-market surveillance requirements under amended Medical Device Act implementing regulations, mandating adverse event reporting within 48 hours for Class C and D devices. Manufacturers must now maintain local vigilance officers with direct authority to initiate field safety corrective actions. Imported insulin pump suppliers face the steepest compliance curve, as legacy distribution agreements lacked provisions for rapid-response recall logistics.
Patient acquisition is migrating from specialist referral chains to direct digital channels, with pharmacy e-commerce platforms and telehealth providers capturing an expanding share of initial glucose meter purchases. Younger Type 2 patients in Selangor increasingly self-educate through diabetes social media communities before consulting clinicians, reversing the traditional prescriber-driven device selection pathway. This behavioral shift pressures manufacturers to maintain consumer brand visibility independent of clinical detailing investments.
Malaysia Diabetes Care Devices Market Segmentation
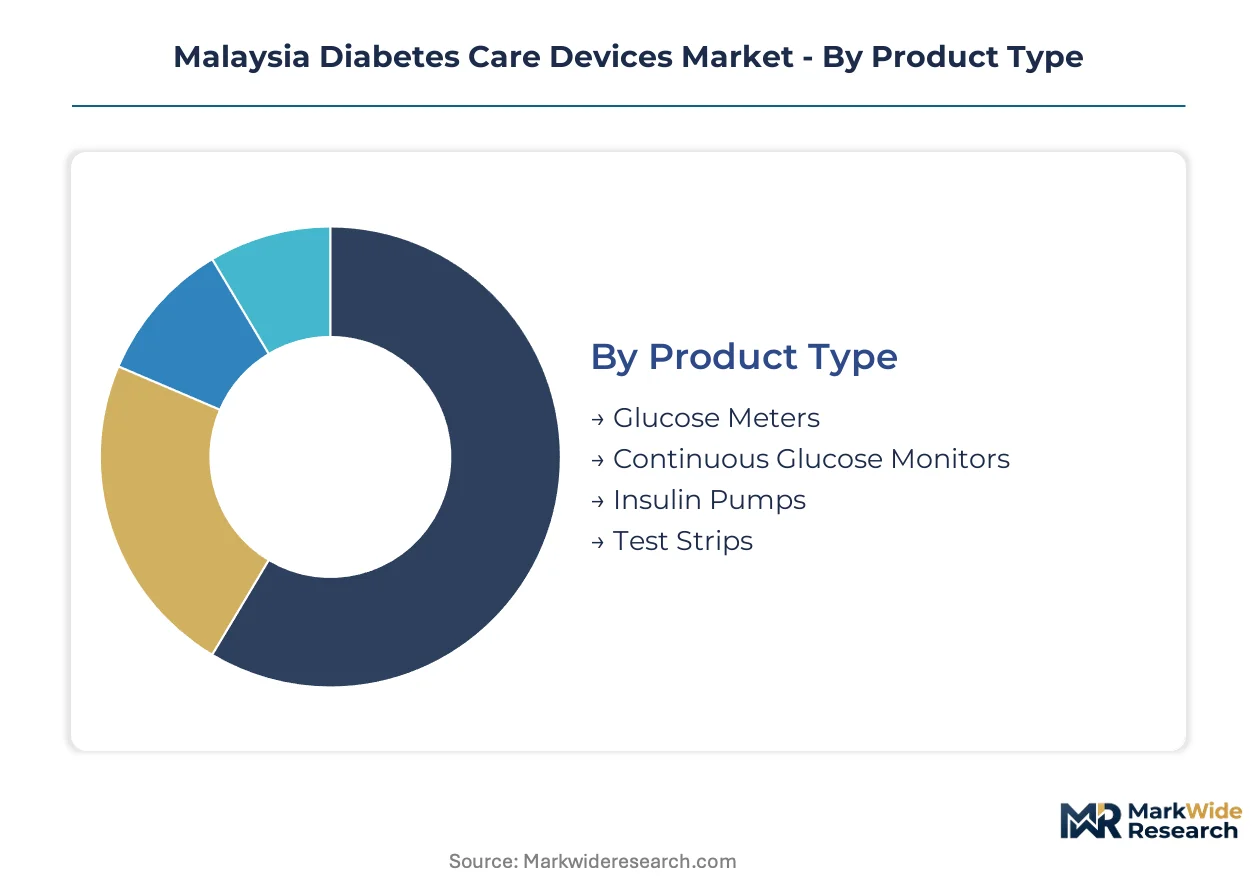
Segmentation reveals how Malaysia's diabetes care devices market fragments across competing access models and patient acuity levels. Suppliers must align product specifications, service intensity, and margin structures to distinct procurement behaviors across institutional and consumer channels.
Product Type:
Cost tier separates patients seeking one-time capital purchases from those accepting recurring sensor subscription economics.
- Continuous Glucose Monitors:Wearable biosensor systems utilizing subcutaneous glucose oxidase probes transmit real-time data to smartphone applications. Klang Valley endocrinology clinics prescribe these for 60-70% of new Type 1 diagnoses within six months, driven by reduced fingerstick burden and improved time-in-range metrics.
- Glucose Meters:Electrochemical handheld devices measure capillary blood glucose via enzymatic test strip reactions. Homecare settings in Selangor and Kuala Lumpur sustain volume demand among Type 2 patients on oral therapy, constrained by Medical Device Authority Class B registration timelines of 12-18 months.
- Insulin Pumps:Programmable infusion devices deliver subcutaneous insulin through cannula systems. Demand concentrates in pediatric diabetes centers requiring precise basal-bolus automation.
- Test Strips:Disposable biosensor reagent strips enable single-use glucose quantification. Retail pharmacy channels absorb generic competition from South Korean and Chinese manufacturers, compressing distributor margins.
Volume sits with Test Strips; growth tilts toward Continuous Glucose Monitors.
End User:
Application context determines whether procurement flows through centralized hospital tenders or direct-to-consumer transactions.
- Homecare:Self-monitoring patients acquire devices through pharmacy e-commerce platforms and telehealth providers. Younger Type 2 patients in Selangor increasingly self-educate through social media communities before clinical consultation, reversing traditional prescriber-driven selection pathways.
- Hospitals:Public health facilities deploy enterprise resource planning procurement systems lacking API connectivity with modern continuous monitoring data streams. Integrated diagnostic-to-treatment workflows dominate glucose meter and insulin pump acquisition decisions.
- Clinics:Specialist endocrinology practices in the Klang Valley corridor serve as sampling and patient onboarding access points for device manufacturers. Private clinic chains favor cloud-connected glucose data transmission for remote monitoring protocol expansion.
- Retail Pharmacies:Community dispensaries handle walk-in glucose meter purchases and test strip replenishment. Generic biosensor alternatives erode branded pricing power in this channel.
Procurement concentrates in Hospitals; patient flow is shifting fastest toward Homecare.
Technology:
Customer type—intensive insulin users versus oral therapy patients—determines technology sophistication requirements.
- Wearable Devices:Continuous monitoring patches and smartwatch-integrated biosensors eliminate calibration demands through factory-calibrated glucose oxidase probe reliability improvements. Type 2 patients on oral therapy in urban Malaysian centers represent expanding addressable populations beyond traditional intensive insulin users.
- Wireless:Bluetooth and near-field communication protocols enable automated glucose data transmission to clinical dashboards. Ministry of Health reimbursement pilots for cloud-connected data streams are enabling subscription revenue models.
- Fingerstick:Conventional capillary blood sampling remains prevalent in East Malaysia where device availability lags 40-50% behind Klang Valley benchmarks. Sabah and Sarawak patients rely on basic meter technology due to distribution infrastructure constraints.
- Smart Insulin Pens:Dose-tracking injection devices with Bluetooth connectivity capture injection timing and volume data. These bridge therapy management for patients not yet requiring pump therapy.
Adoption concentrates in Fingerstick; expansion is steepest for Wearable Devices.
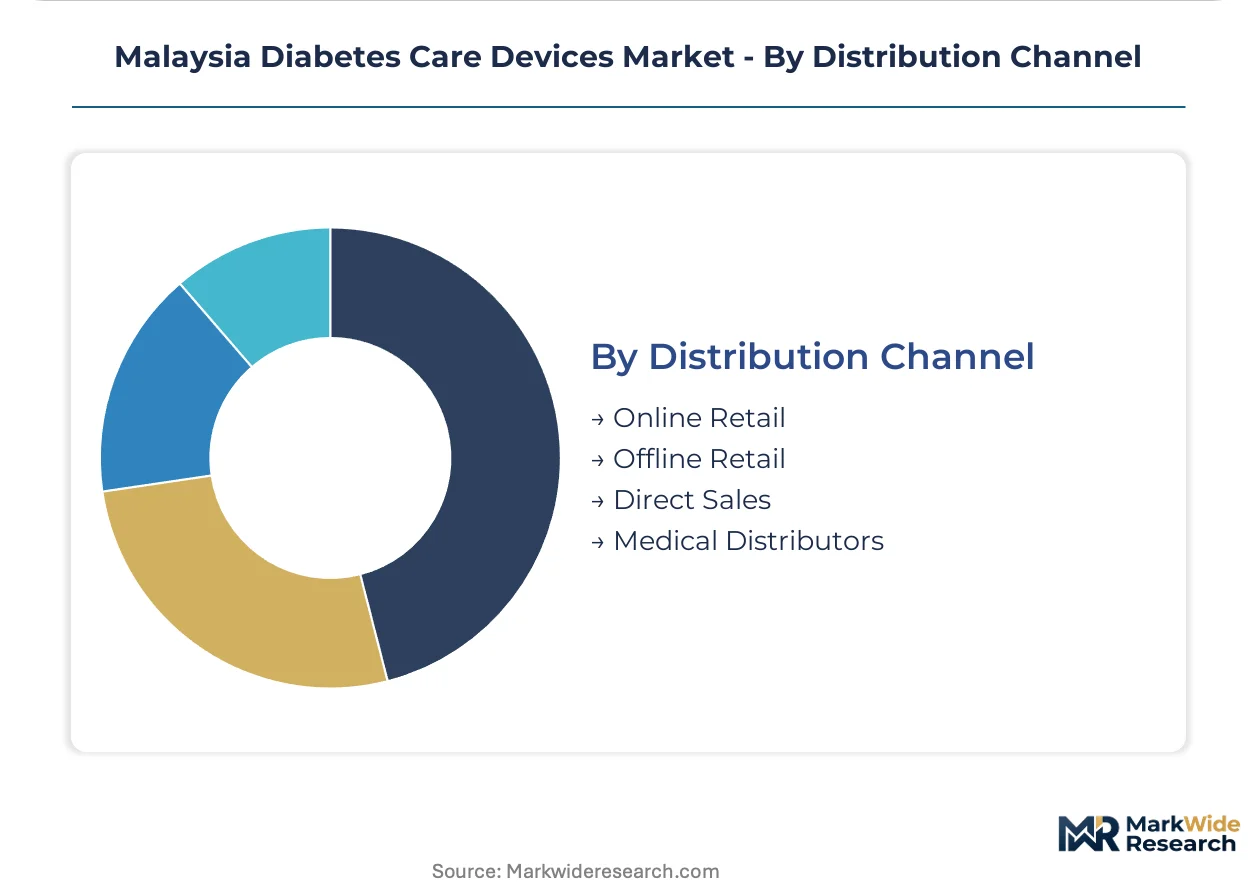
Distribution Channel:
Geography within Malaysia—Peninsular versus East Malaysia—shapes channel viability and logistics configuration.
- Online Retail:Pharmacy e-commerce platforms and telehealth providers capture initial glucose meter purchases from digitally native patients. Direct digital channels bypass traditional specialist referral chains for younger Type 2 demographics in Selangor.
- Medical Distributors:Authorized representatives manage Medical Device Authority registration, importation, and hospital tender compliance. These intermediaries freeze working capital during 12-18 month conformity assessment procedures for Class B and C devices.
- Offline Retail:Brick-and-mortar pharmacy chains handle test strip replenishment and basic meter sales. Margin compression from generic alternatives squeezes both distributor commissions and manufacturer net revenue per unit.
- Direct Sales:Manufacturers engage institutional procurement teams at public health facilities for insulin pump and continuous monitor tenders. Legacy distribution agreements now require rapid-response recall logistics provisions under amended Medical Device Act implementing regulations.
Transaction volume flows through Offline Retail; channel mix is tilting fastest toward Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Iskandar Malaysia special economic zone in Johor anchors medical device manufacturing incentives, drawing multinational assembly operations seeking ASEAN hub status under Malaysia's industrial master plan.
Klang Valley
Kuala Lumpur and Selangor concentrate over half of Malaysia's specialist endocrinologists and diabetes educators, creating efficient prescriber access for device sampling programs. The Medical Device Authority enforces conformity assessment procedures aligned with ASEAN Medical Device Directive harmonization. Private hospital chains in Petaling Jaya deploy integrated diagnostic-to-treatment workflows that dominate glucose meter and insulin pump procurement decisions.
East Malaysia
Sabah and Sarawak exhibit diabetes prevalence rates matching Peninsular Malaysia yet device availability lags 40-50% behind Klang Valley benchmarks. The Ministry of Health's National Diabetes Registry tracks utilization gaps to inform targeted reimbursement pilots. Kota Kinabalu and Kuching rely on basic fingerstick technology due to distribution infrastructure constraints, creating whitespace for telemedicine-integrated partnerships.
Johor
Iskandar Puteri hosts emerging medical device assembly clusters benefiting from pending production tax holidays under amended industrial master plan provisions. The state's proximity to Singapore enables cross-border logistics for manufacturers already registered under ASEAN harmonized standards. Johor Bahru's specialist clinics increasingly prescribe continuous glucose monitors for Type 1 pediatric patients.
Penang
The Northern Corridor Economic Region supports electronics manufacturing capabilities relevant to biosensor component production. Penang Island's medical tourism infrastructure attracts diabetes patients from Indonesia and Thailand seeking advanced device therapies. Bayan Lepas industrial zones house contract manufacturers supplying glucose meter OEMs.
Perak and Northern States
Ipoh's public health facilities participate in Ministry of Health remote patient monitoring pilots enabling cloud-connected glucose data transmission. The region's lower cost structure attracts distributor warehousing operations serving secondary cities. Taiping and Kangar report growing homecare device demand as younger Type 2 patients self-educate through digital channels before clinical consultation.
Malaysia Diabetes Care Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Malaysia's diabetes care devices sector, creating a tiered structure where scale-driven multinationals anchor hospital procurement while agile innovators capture homecare growth. Abbott Laboratories leverages its established glucose monitoring portfolio to sustain brand loyalty among endocrinology clinics nationwide. Roche anchors its position through integrated diagnostic-to-treatment workflows that dominate hospital procurement cycles. Dexcom competes on wearable continuous monitoring technology that reduces fingerstick dependency for Type 1 patients. Consolidation pressures intensify as medical device registration timelines extend working capital requirements, favoring players with established Malaysian authorized representatives.
Among diversified healthcare conglomerates, Medtronic and Roche exemplify the integrated-device-to-therapy archetype, occupying positions that span insulin delivery systems through metabolic monitoring platforms. Dexcom and Abbott Laboratories represent the wearable biosensor specialization vector, with their continuous monitoring systems capturing preference share among urban Malaysian patients seeking reduced intervention burden. Insulet Corporation and Tandem Diabetes Care sit within the pump-technology tier, addressing intensive insulin users requiring precise basal-bolus automation. Ypsomed anchors the European specialist contingent, while Novo Nordisk bridges pharmaceutical and device domains through injection-therapy adjacencies. Becton Dickinson and Company occupies a diversified medtech position spanning multiple therapeutic areas beyond diabetes.
| Leading Market Players |
|---|
| Medtronic |
| Roche |
| Dexcom |
| Abbott Laboratories |
| Novo Nordisk |
| Insulet Corporation |
| Tandem Diabetes Care |
| Becton Dickinson and Company |
| Ypsomed |
| Others |
Supply & Pricing Matrix
Enzyme reagent spot prices on the Singapore Commodity Exchange cascade through Malaysian glucose meter supply chains, compressing margins for test strip assemblers while amplifying pricing power for continuous monitor suppliers with captive biosensor production.
Pricing Analysis
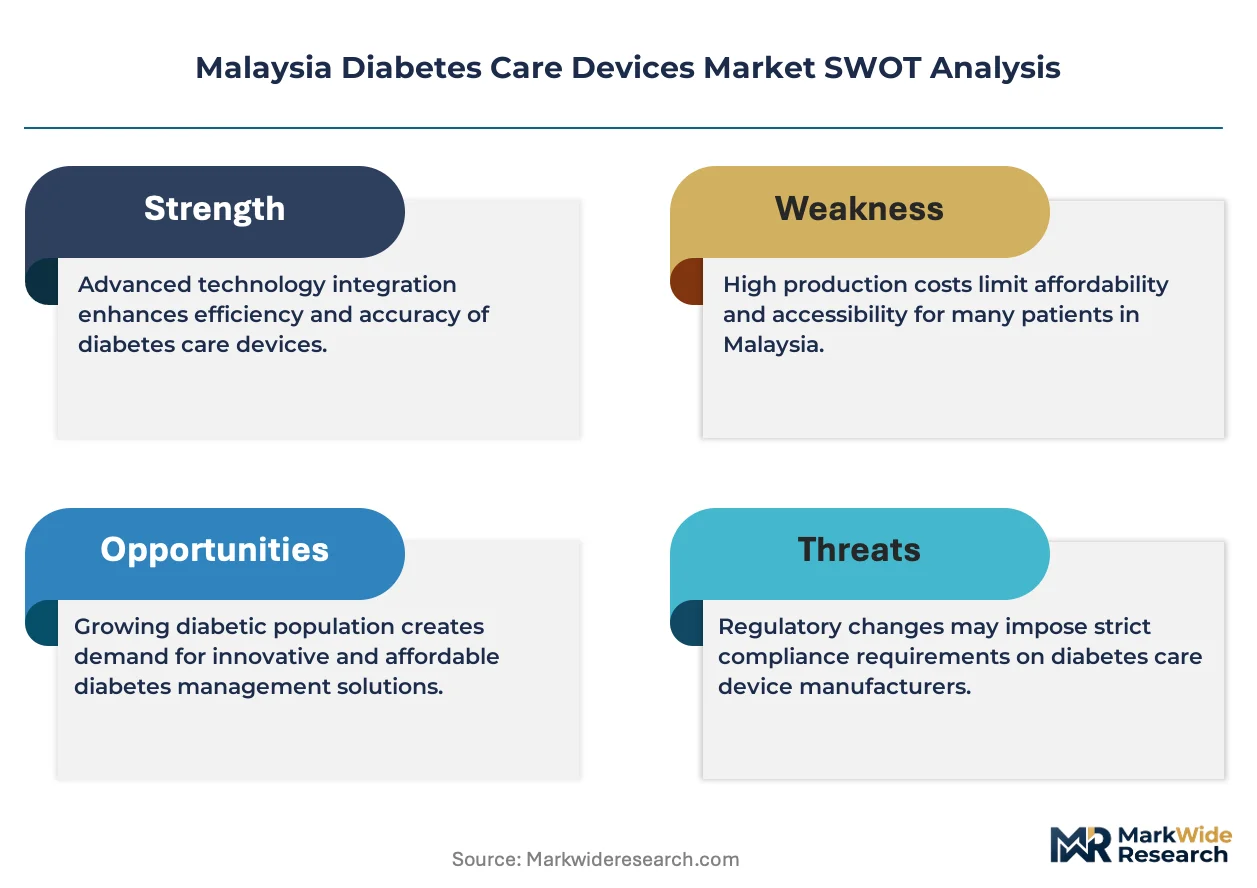
Lead-time premiums of 30-45 days for Medical Device Authority-registered glucose meters sustain three-tier pricing structure across premium, standard, and economy levels. Brand recognition and ISO 13485 certification tier separate Abbott and Roche hospital contracts from generic South Korean alternatives in retail pharmacy. Cost compression in economy test strips intensifies because Chinese manufacturers undercut distributor commissions by 15-20%. Price-sensitive Type 2 patients on oral therapy in East Malaysia drive volume at economy tiers, while insulin-dependent populations in Klang Valley absorb premium continuous monitor subscriptions.
Supply Chain Analysis
Glucose oxidase enzyme supply rests on Danish and Japanese specialty bioproducers, with Malaysian assemblers drawing 60% of biosensor reagents from these concentrated sources. Printed circuit board substrates and lithium polymer cells for insulin pumps feed from Chinese and South Korean component hubs. Single-source vulnerability in enzyme supply creates disruption risk if Nordic production facilities face contamination events. Distribution runs through authorized representatives managing Medical Device Authority conformity assessments, freezing inventory for 12-18 month registration windows before hospital tender participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's diabetes care device market operates as a supply-constrained environment where Medical Device Authority registration bottlenecks prop pricing premiums for incumbents with established authorized representatives.
For Market Incumbents: Cement channel control through exclusive distribution agreements with Klang Valley hospital chains before ASEAN Medical Device Directive harmonization invites Singapore-registered competitors. Acquire local authorized representative capabilities to compress registration timelines and freeze out capital-constrained entrants. Biomedical engineering talent scarcity in Penang and Kuala Lumpur threatens R&D localization targets; captive training partnerships with Universiti Malaya biomedical programs secure pipeline access. For New Entrants and Emerging Players: ASEAN Medical Device Directive alignment in Malaysia opens a window for Singapore-registered continuous glucose monitor suppliers to bypass duplicate certification burdens. East Malaysia's 40-50% device availability gap versus Klang Valley benchmarks offers the most penetrable geography for telemedicine-integrated distribution partnerships. Direct-to-consumer pharmacy e-commerce platforms in Selangor provide the optimal go-to-market angle for bypassing hospital procurement gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale glucose meter distributors with frozen Medical Device Authority registration pipelines in Johor and Penang. Long-term viability hinges on subscription revenue models decoupled from one-time device sales through cloud-connected data transmission pilots. Watch Ministry of Health reimbursement policy expansion for remote patient monitoring as the inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Medical Device Authority Registration Acceleration | Compresses 12-18 month timelines to capture hospital tender windows before competitors. |
| East Malaysia Telemedicine Partnership | Bridges 40-50% device availability gap in Sabah and Sarawak through remote monitoring protocols. |
| Cloud-Connected Data Platform Development | Enables subscription economics decoupled from one-time sensor sales under Ministry of Health pilots. |
| Biomedical Engineering Talent Pipeline Investment | Addresses scarcity of specialized biosensor engineers through university partnership programs. |
| Generic Test Strip Manufacturing Localization | Counters South Korean and Chinese margin compression through Johor assembly cost advantages. |
Research Methodology
Document review covered Ministry of Health National Diabetes Registry extracts, Medical Device Authority registration databases, and ASEAN Medical Device Directive harmonization protocols, complemented by interviews with hospital procurement managers, endocrinology clinic directors, biomedical engineers at glucose meter assemblers, and pharmacy e-commerce platform operators. Secondary validation drew from customs import records for biosensor reagents, GPO contract disclosures at public health facilities, and industrial master plan amendment drafts. Bottom-up patient flow modeling and top-down expenditure benchmarking triangulated market sizing across the analysis window.
Historical utilization patterns at Klang Valley endocrinology clinics were cross-referenced against panel input from device manufacturers and distributor principals to anchor growth assumptions. Segmentation dimensions modeled include product type tier, end-user procurement channel, technology sophistication level, and geographic cluster within Peninsular versus East Malaysia. CAGRs were derived from patient population epidemiology overlaid with technology substitution curves for continuous glucose monitors displacing fingerstick meters.
The model assumes a particular technology adoption path; alternative pathways for factory-calibrated wearable biosensors eliminating fingerstick calibration demands would alter the outlook for standalone meter segments. Forecasts reflect assumptions on Medical Device Authority registration timeline stability and Ministry of Health reimbursement expansion velocity. Supply chain disruption in glucose oxidase enzyme production or abrupt tariff shifts on Chinese printed circuit boards could revise projections. A small set of triggers—registration timeline amendments, remote monitoring reimbursement decisions, and industrial master plan manufacturing incentive finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
India Insulin Infusion Pump Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
Iran Diabetes Care Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market