
 Dual Balloon Angioplasty Catheter Market | 2026-2036
Dual Balloon Angioplasty Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Balloon Angioplasty Catheter Market Foresight
Software-defined pressure-monitoring features embedded in next-generation dual balloon systems is rebalancing how procurement teams evaluate total cost of ownership against upfront device pricing. Boston Scientific Corporation leverages its integrated electrophysiology and interventional cardiology platforms to cross-sell advanced catheter configurations. Medtronic plc anchors its position through deep R&D investment in drug-coated balloon adjuncts. Abbott Laboratories differentiates via proprietary balloon material formulations that optimize lesion crossing profiles.
A dual balloon angioplasty catheter employs two independent inflatable lumens mounted on a single shaft, typically constructed from polyamide or Pebax elastomer blends, designed to achieve sequential or simultaneous dilatation of stenosed coronary or peripheral vessels with controlled pressure differentials. Rapid exchange catheter configurations dominate procedural throughput in high-volume catheterization laboratories due to reduced operator exchange time and lower contrast utilization. Over-the-wire catheter platforms retain preference for complex chronic total occlusion cases where enhanced guidewire support determines procedural success. Specialty catheter variants command premium positioning in bifurcation and calcified lesion subsets where conventional balloon geometries deliver inadequate luminal gain.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence thresholds for market access across the United States and European Union. Japan's PMDA and China's NMPA impose supplementary local testing protocols that extend registration cycles for multinational manufacturers. Stakeholders must monitor evolving reimbursement benchmarks for outpatient PCI settings and the pace of biosimilar drug-coated balloon adoption that could compress conventional balloon catheter price corridors.
Market Dynamics
Software-defined pressure-monitoring capabilities embedded in next-generation dual balloon systems are compressing traditional procurement evaluation cycles as hospitals weigh total cost of ownership against upfront device pricing. This technological inflection is redistributing competitive advantage toward integrated platform vendors capable of delivering real-time procedural analytics alongside mechanical dilatation functions.
Growth Catalysts
- EU MDR conformity assessments:Tightened performance documentation requirements for balloon catheter manufacturers are accelerating consolidation among suppliers with robust clinical evidence libraries, privileging incumbents with established notified body relationships.
- Chronic total occlusion procedures:Rising procedural volumes in Japan's aging population are expanding demand for over-the-wire catheter platforms with enhanced guidewire support characteristics.
- Pebax elastomer shaft materials:Advancements in polymer blend formulations are improving lesion crossing profiles and reducing vessel trauma rates in calcified coronary interventions.
Market Restraints
- Polyamide raw material concentration:Supply of specialized medical-grade polyamides concentrates among a limited cohort of European and Japanese chemical suppliers, exposing catheter manufacturers to input cost volatility and allocation risk.
- Japan PMDA local testing protocols:Supplementary in-country validation requirements extend registration cycles for multinational manufacturers, compressing effective patent life and delaying revenue recognition.
- Drug-coated balloon substitution:Adjunctive drug-eluting technologies in peripheral vascular applications threaten to displace conventional balloon-only procedures in specific lesion subsets.
Strategic Opportunities
- Outpatient PCI reimbursement expansion:Shifting payment benchmarks toward ambulatory surgical centers in the United States create channel diversification potential for rapid exchange catheter configurations with reduced procedure time profiles.
- Integrated electrophysiology-interventional cardiology platforms:Technology convergence between arrhythmia management and coronary intervention workflows enables cross-selling of advanced catheter configurations through shared capital equipment footprints.
- Bifurcation lesion specialty variants:Underpenetrated demand for purpose-built balloon geometries in complex branching anatomy represents a premium pricing tier with limited direct competition.
Industry Challenges
- Interventional cardiology specialist training pipelines:Procedural complexity in chronic total occlusion and calcified lesion subsets outpaces fellowship program output, constraining addressable procedure volume growth.
- FDA 510(k) clinical evidence thresholds:Escalating requirements for substantial equivalence documentation extend development timelines and inflate premarket investment for novel catheter configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Balloon Angioplasty Catheter Market |
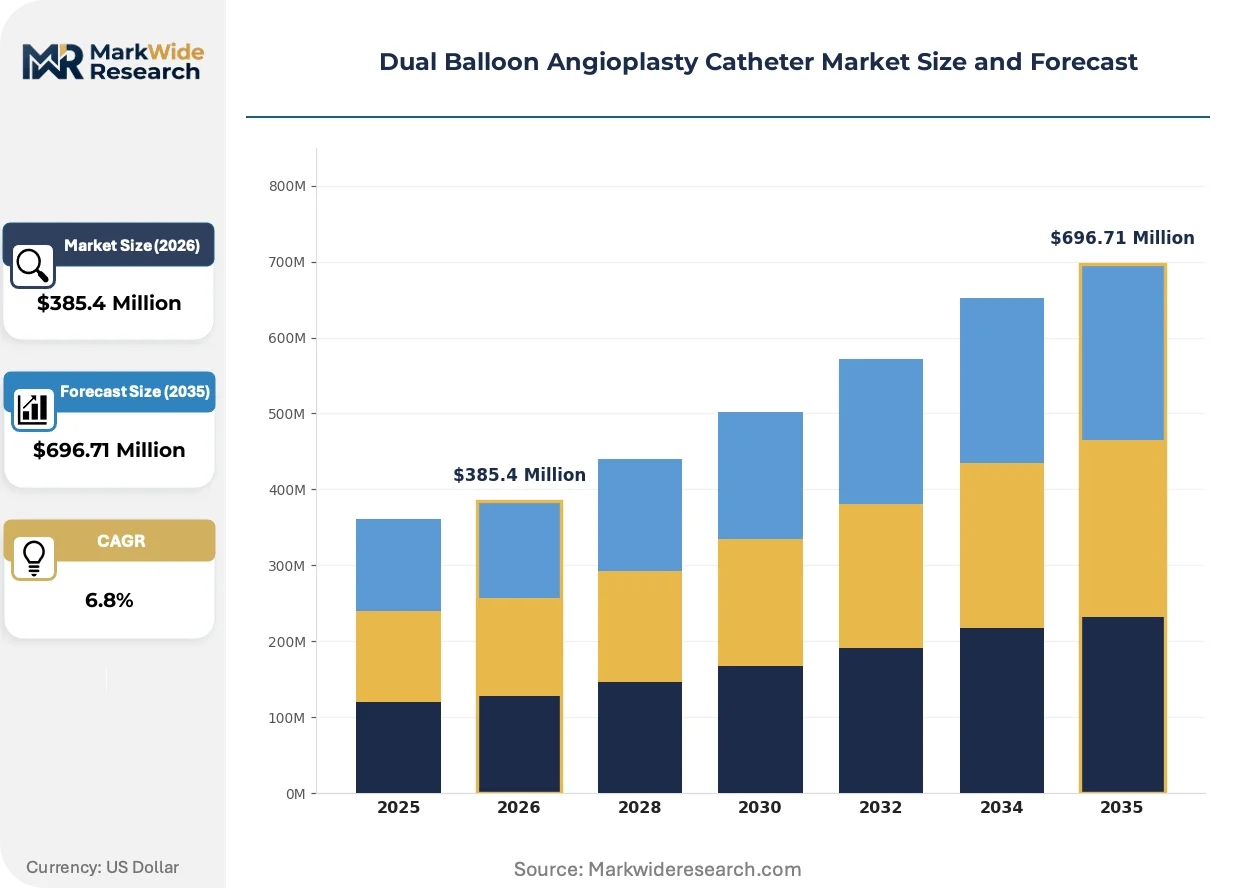
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Catheter, Over-the-Wire Catheter, Rapid Exchange Catheter, Specialty Catheter End User: Hospitals, Specialized Clinics, Ambulatory Surgical Centers, Research Institutions Delivery Mode: Percutaneous, Surgical, Endovascular, Transluminal Catheter Size: Small Diameter, Medium Diameter, Large Diameter, Extra Large Diameter |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Abbott Laboratories, Terumo Corporation, B. Braun Melsungen AG, Cardinal Health, Spectranetics, InSitu Technologies, Eucatech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Balloon Angioplasty Catheter Market Shifts & Advancements
Real-time pressure feedback integration is transforming procedural workflows from mechanical dilatation toward data-guided lesion preparation. This shift is compressing the gap between diagnostic assessment and therapeutic action within the catheterization laboratory environment.
Embedded fiber-optic pressure sensors in next-generation dual balloon catheters are enabling continuous luminal pressure monitoring during inflation sequences. High-volume catheterization laboratories in Germany and the United States are piloting these configurations to optimize balloon sizing and reduce procedural radiation exposure. This capability is expanding into standard-of-care expectations for complex PCI cases, forcing competitors without integrated sensing platforms into price-based positioning.
EU MDR technical documentation requirements are elevating clinical evidence standards for Class III device conformity assessments. Manufacturers must now submit expanded post-market surveillance protocols and systematic literature reviews that extend preparation timelines. Smaller catheter developers without dedicated regulatory affairs infrastructure are outsourcing MDR compliance to specialized consultants, eroding margin structures and accelerating acquisition activity.
Hospital procurement committees are consolidating vendor relationships around integrated platform suppliers capable of delivering capital equipment, disposables, and procedural support services through single-source contracts. This concentration is displacing standalone catheter vendors who lack complementary electrophysiology or imaging system portfolios. The United States exhibits the most pronounced procurement consolidation, with integrated delivery networks capturing increasing shares of elective angioplasty volume.
Dual Balloon Angioplasty Catheter Market Segmentation
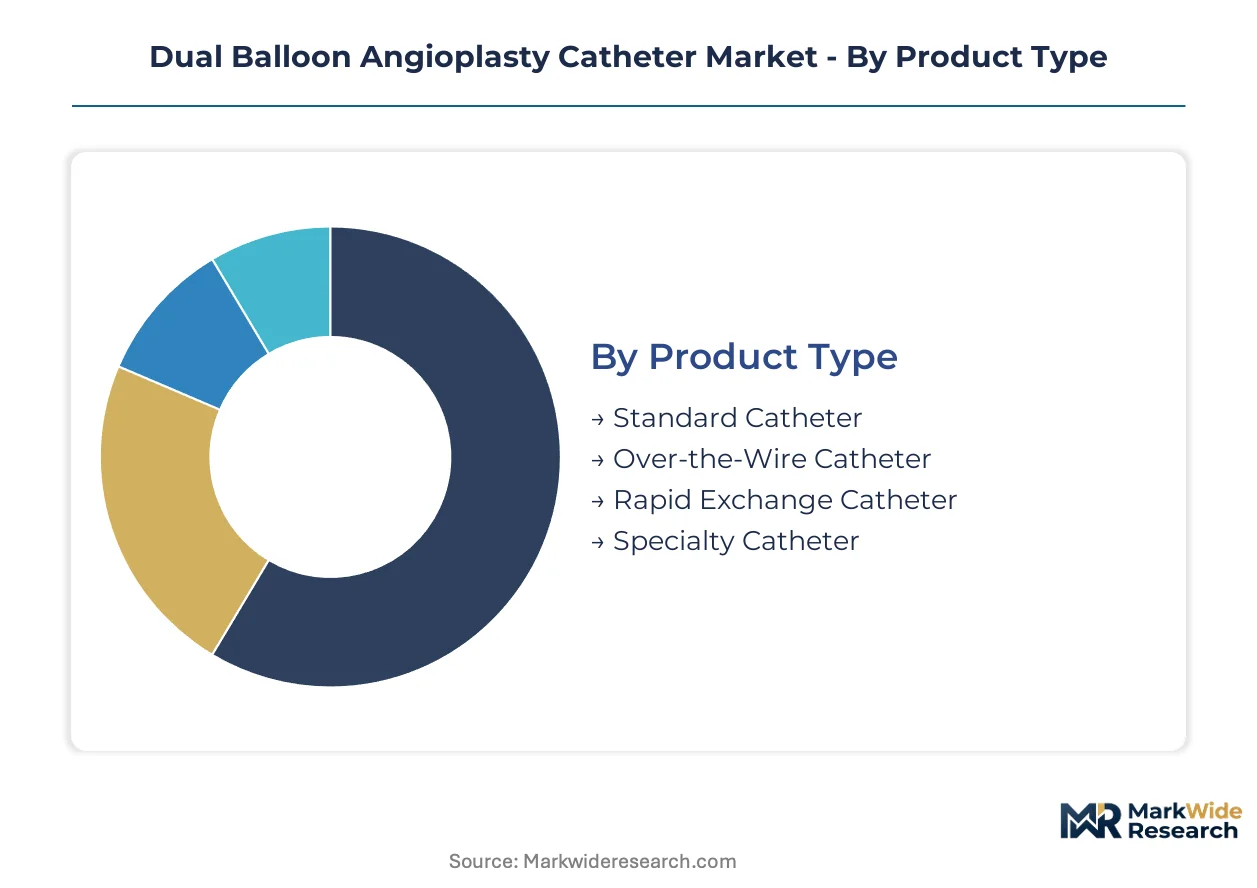
Segmentation in the dual balloon angioplasty catheter market reveals how procedural complexity, reimbursement settings, and lesion characteristics reshape procurement priorities across hospital systems and outpatient facilities.
Product Type:
Device selection hinges on procedural throughput requirements versus anatomical complexity, with catheter laboratories balancing exchange speed against guidewire support needs.
- Rapid Exchange Catheter:Features a short guidewire lumen that enables single-operator exchanges without removing the wire from the vessel. United States catheterization laboratories favor this configuration for high-volume elective PCI cases where contrast reduction and radiation exposure minimization drive protocol standardization.
- Over-the-Wire Catheter:Incorporates a full-length guidewire lumen providing superior torque response and backup support for complex chronic total occlusion interventions. Japanese hospital systems exhibit concentrated demand for this platform as aging demographics expand the addressable pool of calcified, long-segment lesions requiring enhanced wire manipulation.
- Standard Catheter:Conventional dual-lumen construction without rapid exchange functionality, retained in cost-sensitive procurement environments.
- Specialty Catheter:Purpose-built geometries including kissing balloon configurations for bifurcation anatomy and ultra-low-profile shafts for distal vessel access.
Rapid Exchange Catheters lead volumes today; Specialty Catheters are gaining share fastest in premium-tier hospital accounts.
End User:
Site-of-care economics and reimbursement differentials concentrate demand among facilities with interventional cardiology accreditation and outpatient procedure capabilities.
- Hospitals:Academic medical centers and community hospital systems maintain the deepest penetration of dual balloon catheter utilization, driven by 24/7 emergency PCI availability and complex case referral patterns. United States integrated delivery networks leverage centralized procurement to extract volume discounts from platform vendors.
- Ambulatory Surgical Centers:Freestanding outpatient facilities with catheterization laboratory certification represent the most dynamic demand expansion as CMS reimbursement shifts favor site-neutral payment for elective procedures. Germany's Kliniklandscape demonstrates comparable migration patterns as statutory health insurance funds incentivize lower-cost settings.
- Specialized Clinics:Cardiovascular-focused outpatient facilities without full surgical backup, concentrating on diagnostic catheterization and low-risk interventions.
- Research Institutions:Academic research hospitals and contract research organizations utilizing investigational device configurations for clinical trial enrollment.
Hospitals retain the dominant volume position; Ambulatory Surgical Centers show the steepest expansion trajectory as payment reform accelerates.
Delivery Mode:
Access technique selection reflects vessel territory, lesion location, and operator training pathways rather than device-specific differentiation.
- Percutaneous:Transcutaneous arterial puncture with sheath placement constitutes the standard access method for coronary and peripheral interventions across all major markets.
- Endovascular:Catheter-based approaches through remote vascular access sites dominate peripheral arterial disease treatment in femoropopliteal and below-the-knee territories.
- Transluminal:Intraluminal crossing of chronic total occlusions with specialized guidewire and microcatheter support prior to balloon dilatation.
- Surgical:Direct vessel exposure and cutdown access reserved for failed percutaneous approaches or concomitant open revascularization procedures.
Percutaneous delivery anchors current procedure volumes; Endovascular techniques are climbing fastest in peripheral vascular applications.
Catheter Size:
Balloon diameter and shaft profile specifications align with vessel caliber, lesion morphology, and guiding catheter compatibility requirements.
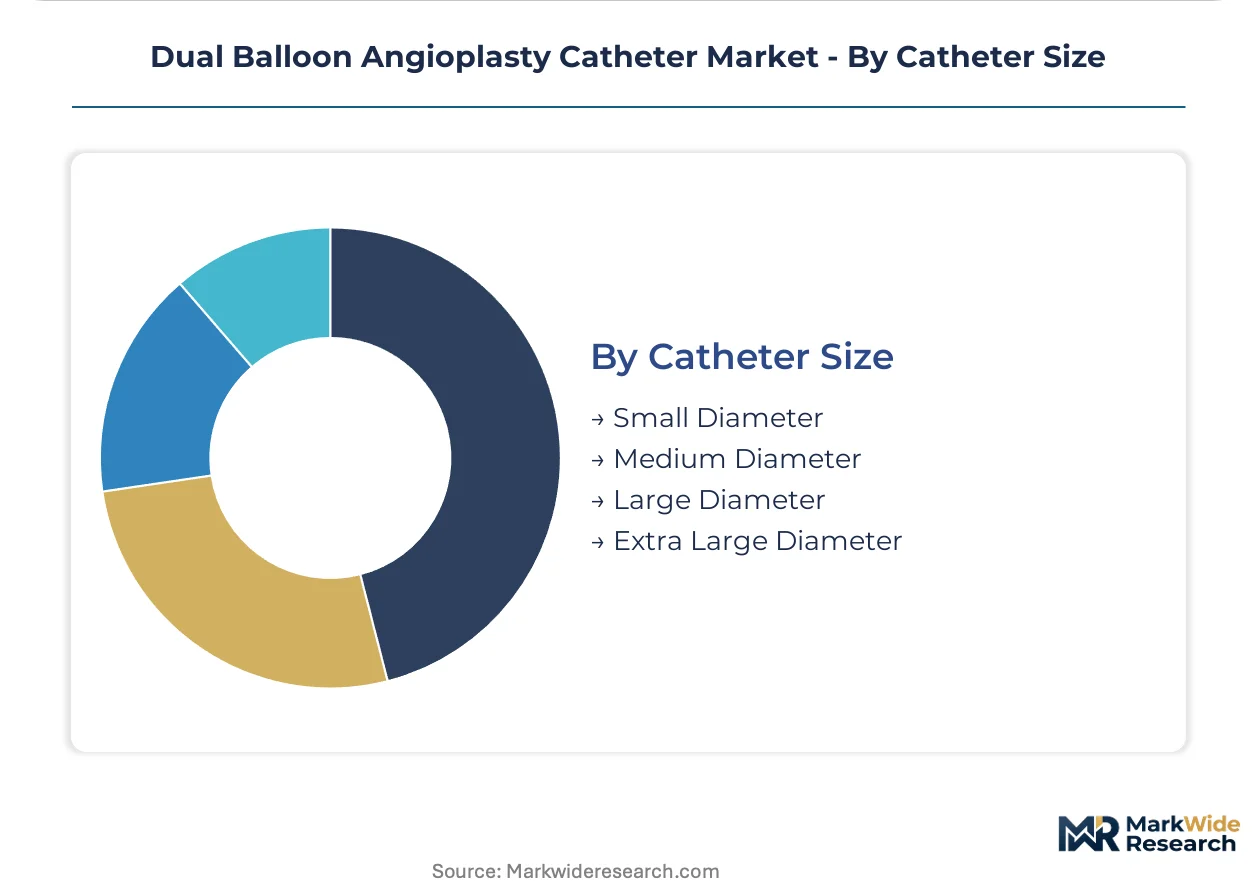
- Small Diameter:Balloon diameters below 2.0mm and low-profile shafts enable distal coronary and below-the-knee interventions where vessel caliber constraints limit device selection.
- Medium Diameter:2.0-3.5mm balloon range matching standard coronary vessel dimensions constitutes the highest-procedure-volume segment across United States and European catheterization laboratories.
- Large Diameter:3.5-5.0mm configurations address proximal coronary, renal, and iliac vessel territories with higher plaque burden and calcification prevalence.
- Extra Large Diameter:Above 5.0mm balloons for aortic, femoral, and carotid applications requiring substantial luminal gain in large-caliber vessels.
Medium Diameter catheters command the largest procedure share; Small Diameter platforms are expanding most quickly as distal vessel intervention techniques diffuse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's catheterization laboratories process higher elective PCI volumes per capita than Japan, yet Japanese hospitals maintain deeper penetration of over-the-wire platforms for chronic total occlusion cases. This procedural divergence shapes distinct procurement patterns across both markets.
United States
Integrated delivery networks in Texas and the Northeast Corridor centralize purchasing for rapid exchange catheters, prioritizing contrast reduction and radiation exposure metrics. FDA 510(k) clearance pathways enforce substantial equivalence documentation that extends development timelines for novel configurations. Boston Scientific Corporation anchors market presence through cross-selling with electrophysiology platforms in high-volume catheterization laboratories.
Germany
Statutory health insurance funds incentivize ambulatory surgical center migration, compressing procedure costs while maintaining quality benchmarks. EU MDR conformity assessments require expanded post-market surveillance protocols that privilege manufacturers with established notified body relationships. The Rhine-Ruhr and Bavarian medical device clusters concentrate R&D activity for pressure-sensing catheter innovations.
Japan
Aging demographics expand the addressable pool of calcified, long-segment lesions requiring enhanced guidewire support. PMDA local testing protocols extend registration cycles for multinational manufacturers, compressing effective patent life. Tokyo and Osaka metropolitan hospitals pilot embedded fiber-optic pressure sensors to optimize balloon sizing and reduce procedural radiation exposure.
China
NMPA registration requirements impose supplementary local validation protocols that delay market entry for foreign catheter developers. Domestic manufacturers in the Yangtze River Delta and Pearl River Delta regions scale production of cost-competitive rapid exchange platforms. Hospital procurement committees consolidate vendor relationships around suppliers offering integrated capital equipment and disposable bundles.
Switzerland
Swissmedic maintains alignment with EU MDR standards while offering streamlined pathways for innovative Class III device assessments. Geneva and Zurich academic medical centers concentrate clinical trial enrollment for next-generation dual balloon configurations with real-time pressure feedback. Premium pricing tolerance supports adoption of specialty catheter variants in complex bifurcation cases.
Dual Balloon Angioplasty Catheter Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while mid-scale specialists concentrate on niche lesion geometries and regional price-competitive positioning. The vendor base stratifies across three tiers: multinational conglomerates with electrophysiology-interventional cardiology convergence, dedicated cardiovascular device manufacturers with deep catheter R&D pipelines, and regional fabricators serving cost-sensitive procurement environments. Dominant competitive moves include M&A activity to acquire pressure-sensing technology assets and strategic partnerships with academic medical centers for clinical evidence generation.
Within the integrated platform tier, Boston Scientific Corporation and Medtronic plc exemplify vendors capable of delivering capital equipment, disposables, and procedural analytics through single-source contracts. Abbott Laboratories occupies a position emphasizing proprietary material science differentiation. Terumo Corporation represents the Asia-Pacific anchor with established PMDA regulatory navigation capabilities. These three companies collectively illustrate how geographic regulatory expertise and platform breadth determine competitive positioning in high-barrier catheter markets.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Abbott Laboratories |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Cardinal Health |
| Spectranetics |
| InSitu Technologies |
| Eucatech |
| Others |
Supply & Pricing Matrix
EU MDR sustainability documentation mandates for Class III medical devices gate qualified supplier status and premium-tier pricing access, forcing catheter manufacturers to absorb compliance costs or forfeit high-margin hospital contracts. Pebax elastomer and polyamide raw material qualification under tightened environmental standards concentrates procurement leverage among European and Japanese chemical suppliers with established notified body relationships.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard rapid exchange catheter configurations, compressing margins for multinational incumbents. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 510(k) clearance tier and integrated pressure-sensing capability. Cost compression in the standard tier intensifies because domestic Chinese manufacturers scale polymer extrusion capacity. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with single-source contracts show lowest.
Supply Chain Analysis
Dual-sourcing requirements from United States integrated delivery networks mandate multi-supplier qualification for polyamide shaft materials and balloon-forming equipment. Manufacturing concentrates in Germany, Japan, and China. Supply chains draw from medical-grade Pebax elastomers, specialized polyamide resins, and precision extrusion dies. Single-source vulnerability in European chemical feedstocks threatens allocation risk during notified body audit cycles. Distribution runs through GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Japan's extended PMDA registration cycles and Germany's accelerated EU MDR conformity pathways, rewarding manufacturers with parallel regulatory infrastructure.
For Market Incumbents: Cement platform stickiness through backward integration into Pebax elastomer compounding and captive supply of pressure-sensor modules. Drug-coated balloon substitution in peripheral applications threatens conventional balloon volumes; counter via exclusive electrophysiology-interventional cardiology bundle contracts with United States integrated delivery networks.
For New Entrants and Emerging Players: Enter via specialty catheter variants for bifurcation lesions, the most penetrable white-space segment with limited incumbent focus. Target German ambulatory surgical centers with rapid exchange configurations optimized for reduced procedure time profiles. Lead with software-defined pressure-monitoring as differentiated value proposition.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale catheter developers with established notified body relationships because EU MDR compliance costs are displacing standalone vendors. Five-to-ten year viability hinges on platform breadth across electrophysiology and interventional cardiology. Watch biosimilar drug-coated balloon adoption rates as inflection indicator for conventional balloon catheter price corridor compression.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Premarket notification for novel dual-lumen configurations opens United States hospital procurement access. |
| CE Marking Pathway | EU MDR technical documentation satisfies notified body requirements for German and Swiss market entry. |
| Hospital System Partnership | Single-source contracts with integrated delivery networks lock in rapid exchange catheter volume commitments. |
| Software Companion Development | Real-time pressure analytics integration differentiates against commodity balloon-only competitors. |
| Reimbursement Strategy | CMS outpatient PCI coding alignment enables ambulatory surgical center channel expansion. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and Switzerland, with primary inputs from each regional cluster combining interviews with interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Secondary validation draws from FDA 510(k) filings, EU MDR notified body documentation, PMDA approval databases, and hospital procurement contract records. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchor market sizing.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon. Segmentation dimensions modeled include catheter configuration type, end-user facility category, delivery access technique, and balloon diameter specification. CAGRs derive from procedure growth assumptions, technology substitution elasticities, and reimbursement benchmark evolution. Forecast inputs incorporate aging demographic projections and chronic total occlusion intervention adoption curves.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time pricing transaction data introduce uncertainty bands around competitive share estimates. Deviation in PMDA registration timeline compression or EU MDR notified body capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Connector Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Lactation Massager Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Global Wearable Skin Patch Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Asia Pacific Hearing Aids Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Cervical Spine System Market
Medical Devices
Aortic Valve Replacement Devices Market
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Medical Thermometer Market
Medical Devices
Injectable Drug Delivery Market