
 Thoracic Surgery Devices Market | 2026-2036
Thoracic Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Thoracic Surgery Devices Market Analytics
Aftermarket service revenue for robotic thoracic platforms is narrowing the margin gap against original equipment sales. Medtronic leverages its integrated surgical ecosystem to capture recurring instrument and service contracts. Intuitive Surgical dominates the installed base of robotic systems in thoracic procedures across major academic centers. Johnson & Johnson (Ethicon) anchors its position through advanced powered stapling technology designed for lung resection workflows.
Thoracic surgery devices encompass instruments and systems designed for interventions within the chest cavity, including staplers with tissue-specific compression profiles, thoracoscopes with integrated insufflation channels, and electrosurgical generators calibrated for pulmonary parenchyma. These tools enable precise dissection, resection, and reconstruction during cardiac, pulmonary, and mediastinal procedures. Surgical staplers command the largest revenue pool due to disposable cartridge replenishment cycles, while robotic surgical systems represent the fastest-expanding segment as hospitals amortize capital costs across multiple service lines. Minimally invasive surgery technology underpins procedure volume growth, though open surgery instruments retain substantial share in emergent trauma and complex redo operations.
FDA premarket notification requirements and CE marking under the EU Medical Device Regulation shape product development timelines and clinical evidence thresholds for novel thoracic devices. The EPA and OSHA frameworks additionally govern sterilization byproduct management and surgical smoke evacuation standards in operating suites. Stakeholders must monitor reimbursement parity between robotic-assisted and conventional video-assisted thoracic surgery as payers recalibrate procedure codes.
Market Dynamics
Powered stapler technology and robotic platform integration are compressing procedure times while forcing hospitals to reconfigure operating room workflows around capital-intensive system architectures.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated premarket review timelines for next-generation thoracoscopic instruments are shortening product launch cycles for US manufacturers.
- Academic medical center consolidation:Merged hospital networks in the United States are standardizing thoracic device procurement across multi-site surgical programs.
- Single-port robotic access:Reduced incision count during lobectomy procedures is expanding eligible patient populations for minimally invasive intervention.
Market Restraints
- Capital equipment amortization pressure:Robotic platform depreciation schedules strain hospital budgets when procedure volumes fall below utilization thresholds.
- Tungsten supply concentration:Surgical staple raw material sourcing from limited geographic suppliers creates input cost volatility.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations for Class III thoracic devices extend certification timelines.
Strategic Opportunities
- Japan's aging surgical workforce:Demographic pressure on thoracic surgeons creates demand for assistive automation in Nippon Medical School-affiliated hospitals.
- Disposable instrument reprocessing:Third-party sterilization services for powered stapler cartridges represent untapped aftermarket revenue streams.
- AI-powered preoperative planning:Integration of machine learning with CT segmentation is enabling patient-specific surgical pathway optimization.
Industry Challenges
- Robotic console operator certification:Proctoring requirements for thoracic-specific da Vinci credentialing limit program expansion speed.
- Legacy electrosurgical generator incompatibility:Integration friction with existing OR infrastructure delays robotic system deployment in renovated surgical suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thoracic Surgery Devices Market |
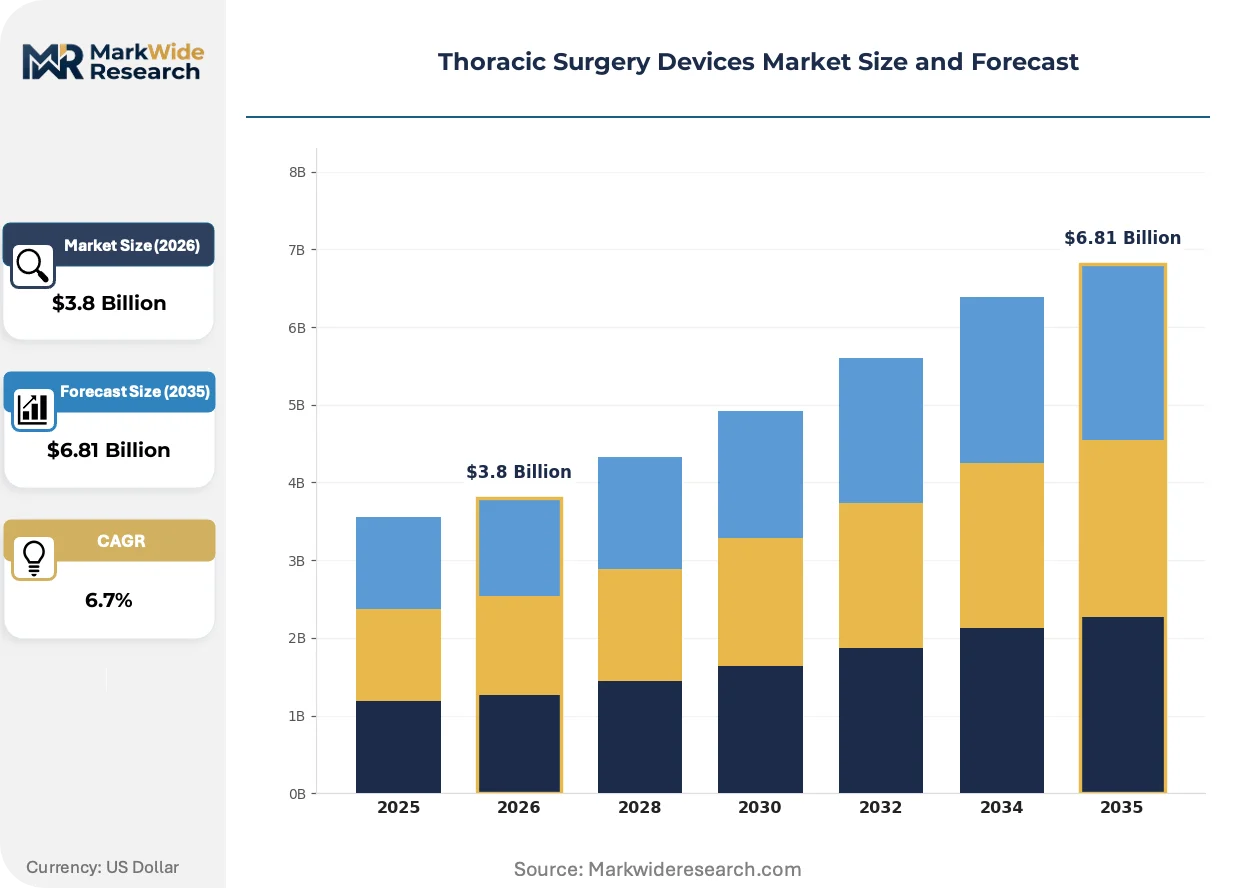
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Staplers, Thoracoscopy Instruments, Electrosurgical Devices, Robotic Surgical Systems Application: Cardiac Surgery, Lung Surgery, Mediastinal Surgery, Esophageal Surgery End User: Hospitals, Specialty Clinics, Academic Research Institutes, Outpatient Surgical Centers Technology: Minimally Invasive Surgery, Robotic Surgery, Open Surgery, Surgical Imaging |
| Companies Covered | Medtronic, Johnson & Johnson (Ethicon), Intuitive Surgical, Olympus Corporation, B. Braun, Teleflex, Richard Wolf GmbH, Medela Healthcare, LivaNova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thoracic Surgery Devices Market Evolving Landscape
Thoracic surgery is undergoing instrumentation convergence as disposable staplers absorb sensing capabilities and robotic platforms incorporate autonomous tissue recognition.
Firefly fluorescence imaging technology is digitizing real-time perfusion assessment during segmentectomy procedures. Academic centers in Germany are adopting this capability at twice the rate of community hospitals. The technology is digitizing margin verification workflows while reducing postoperative air leak rates.
REACH substance restrictions on cobalt-containing alloys are forcing European manufacturers to reformulate surgical instrument metallurgy. Stainless steel alternatives now dominate new product filings with notified bodies. Thoracic forceps and retractors face the steepest compliance transition costs.
Hospital procurement committees are consolidating vendor relationships into single-source agreements spanning staplers, energy devices, and visualization systems. Independent distributors in the United States are losing access to IDN contracts as manufacturers build direct sales organizations. This concentration is most visible in Texas and Florida where health system mergers have accelerated since 2022.
Thoracic Surgery Devices Market Segmentation
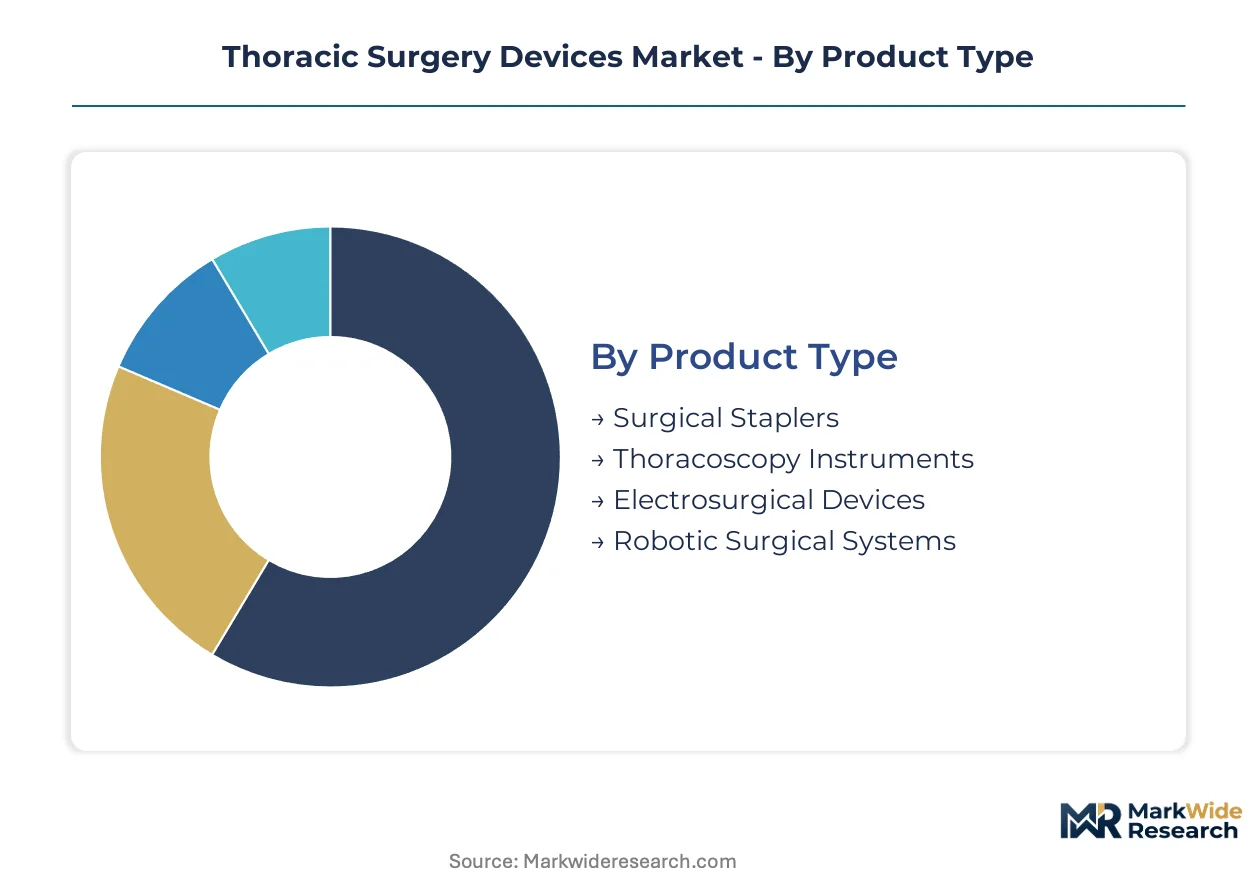
Segmentation in thoracic surgery devices reveals distinct service intensity profiles across product categories. Disposable cartridge replenishment cycles and robotic platform maintenance contracts create divergent margin architectures that shape vendor strategy.
Product Type:
After-sales-service intensity varies dramatically across this category, with robotic systems demanding multi-year service agreements while staplers rely on high-velocity cartridge replacement.
- Surgical Staplers:Disposable cartridge systems with tissue-specific compression profiles designed for pulmonary parenchyma resection. Demand concentrates in United States academic medical centers where lung cancer screening expansion drives lobectomy volume. Cartridge replenishment cycles generate recurring revenue that narrows margin volatility against capital equipment sales.
- Robotic Surgical Systems:Multi-arm platforms with thoracic-specific instrument sets enabling single-port access during segmentectomy. German university hospitals anchor European adoption as amortization across cardiac and thoracic service lines improves capital efficiency. Proctoring requirements and console certification limit deployment speed.
- Thoracoscopy Instruments:Rigid scopes with integrated insufflation channels for pleural cavity visualization.
- Electrosurgical Devices:Generators calibrated for pulmonary tissue dissection with smoke evacuation integration.
Surgical staplers hold the largest share; momentum sits with robotic surgical systems.
Application:
Procedure reimbursement differentials and clinical evidence requirements create tiered investment thresholds across surgical indications.
- Lung Surgery:Lobectomy and segmentectomy procedures driving minimally invasive platform adoption. Japanese academic centers prioritize robotic-assisted approaches for early-stage lung cancer given demographic pressure on surgical workforce. Screening program expansion in United States and Germany enlarges addressable patient populations.
- Cardiac Surgery:Coronary artery bypass and valve procedures requiring specialized thoracoscopic access. Demand clusters in United States integrated delivery networks where cardiac-thoracic service line consolidation standardizes device procurement. Cross-training requirements between cardiac and thoracic teams influence capital allocation.
- Mediastinal Surgery:Thymectomy and lymph node dissection for myasthenia gravis and staging.
- Esophageal Surgery:Minimally invasive esophagectomy with intrathoracic anastomosis.
Lung surgery commands the dominant revenue pool; cardiac surgery offers the steepest expansion trajectory as hybrid OR investments accelerate.
End User:
Capital commitment capacity and procedure volume thresholds stratify purchasing authority across care settings.
- Hospitals:Multi-service-line institutions with dedicated thoracic surgery departments and robotic program infrastructure. United States health system mergers in Texas and Florida concentrate procurement decisions into centralized value analysis committees. IDN-level contracting favors vendors offering stapler-energy-imaging bundles.
- Academic Research Institutes:University-affiliated centers with NIH or DFG funding driving clinical trial enrollment for novel device platforms. Da Vinci credentialing programs and fellowship training pipelines create installed base stickiness. Research revenue supplements clinical service line economics.
- Specialty Clinics:Focused thoracic practices with limited capital equipment budgets.
- Outpatient Surgical Centers:Ambulatory settings constrained by reimbursement parity for robotic versus conventional approaches.
Hospitals retain the largest share; academic research institutes are expanding most quickly as trial enrollment becomes a competitive differentiator.
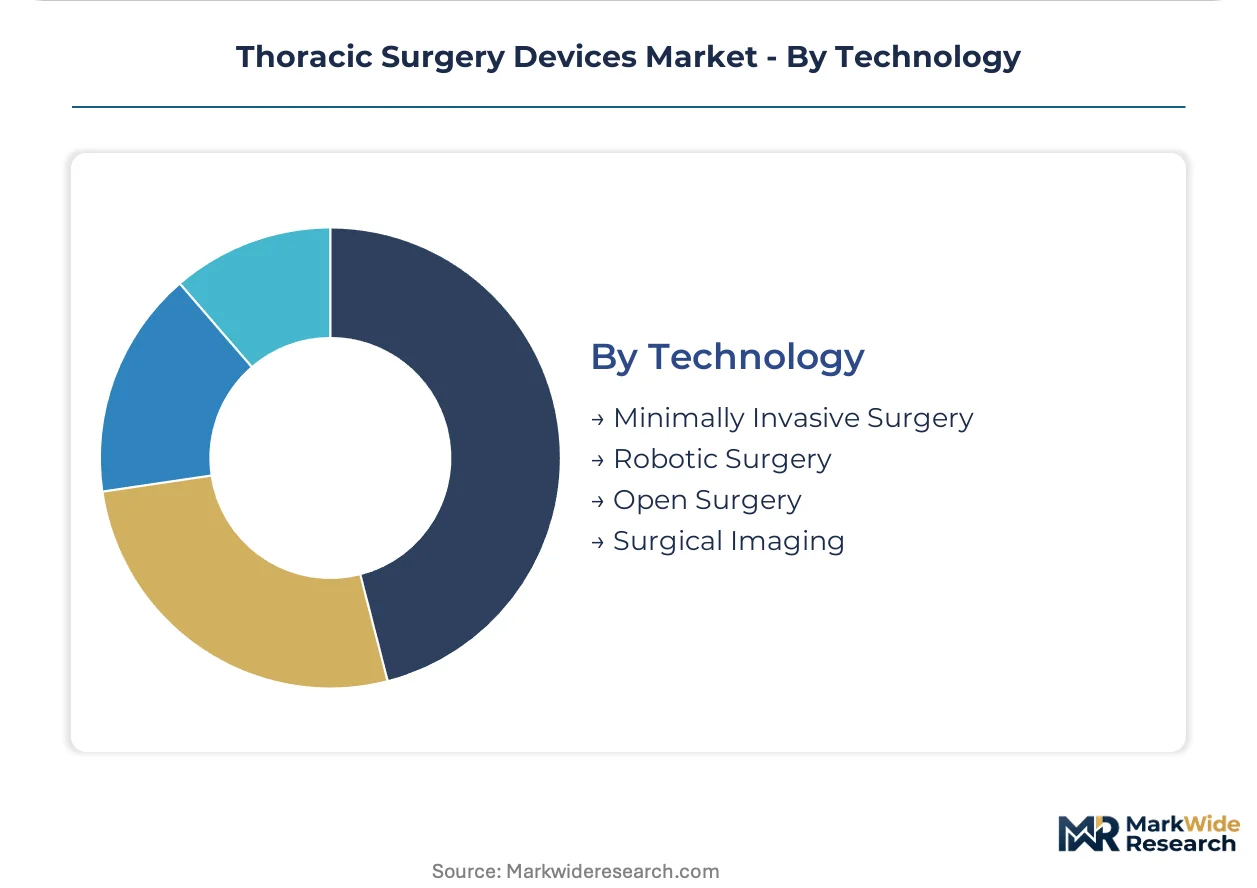
Technology:
Regulatory clearance pathways and clinical evidence thresholds segment development timelines and commercial launch strategies.
- Minimally Invasive Surgery:Video-assisted thoracoscopic surgery with standard thoracoscope and manual instrument sets. Community hospitals in United States and Germany adopt this modality as robotic capital requirements exceed budget constraints. Reimbursement parity with open procedures supports volume growth.
- Robotic Surgery:Computer-assisted platforms with wristed instrumentation and 3D visualization. FDA 510(k) pathway streamlining for next-generation instruments accelerates product launch cycles. Firefly fluorescence integration enables real-time perfusion assessment during segmentectomy.
- Open Surgery:Conventional thoracotomy instruments retaining substantial share in trauma and complex redo operations.
- Surgical Imaging:Intraoperative fluorescence and near-infrared perfusion assessment systems.
Minimally invasive surgery holds the largest share; robotic surgery is gaining share fastest as single-port access expands eligible patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across major thoracic surgery device markets. United States academic medical centers absorb premium robotic platform pricing with minimal volume sensitivity, while community hospitals in India and Southeast Asia prioritize manual stapler economics over capital-intensive system investments.
United States
Integrated delivery networks in Texas and Florida concentrate procurement authority through centralized value analysis committees. FDA 510(k) pathway streamlining accelerates premarket review timelines for next-generation thoracoscopic instruments. The Greater Boston corridor anchors robotic-assisted lobectomy adoption through Massachusetts General Hospital and Brigham and Women's Hospital fellowship training pipelines.
Germany
University hospitals amortize robotic capital costs across cardiac and thoracic service lines to improve capital efficiency. EU MDR clinical evidence requirements extend certification timelines for Class III thoracic devices. The Munich-Düsseldorf corridor leads Firefly fluorescence imaging adoption at twice the rate of community hospitals elsewhere in Europe.
Japan
Demographic pressure on the surgical workforce at Nippon Medical School-affiliated hospitals creates demand for assistive automation. PMDA regulatory frameworks govern premarket approval timelines for powered staplers and robotic platforms. The Tokyo-Osaka metropolitan corridor concentrates da Vinci credentialing programs and early-stage lung cancer screening expansion.
China
Provincial hospital budgets constrain robotic platform deployment despite rising lung cancer incidence. NMPA standards and GB certification requirements shape localization strategies for multinational device manufacturers. The Yangtze River Delta anchors domestic stapler manufacturing clusters serving cost-sensitive community hospital procurement.
India
Private hospital chains in Maharashtra and Karnataka pilot robotic thoracic programs while public sector capacity remains limited. CDSCO regulatory pathways determine import timelines for advanced powered stapling systems. The Delhi-NCR corridor concentrates mediastinal surgery volume through All India Institute of Medical Sciences and Fortis Memorial Research Institute.
Thoracic Surgery Devices Market Competitive Landscape
Capability concentration sits with integrated surgical ecosystem vendors; scale advantage sits with disposable instrument specialists. The market structure tiers around three distinct archetypes: full-stack platform providers bundling robotic systems with proprietary instrument ecosystems, component specialists dominating single-product categories through manufacturing scale, and regional assemblers serving price-sensitive procurement channels. Consolidation pressure intensifies as hospital procurement committees demand single-source agreements spanning staplers, energy devices, and visualization systems. Dominant competitive moves include direct sales organization buildouts displacing independent distributors and multi-year service contract anchoring to capture recurring instrument replenishment revenue.
Among integrated platform providers, Medtronic and Johnson & Johnson (Ethicon) occupy positions exemplifying the full-stack archetype through bundled surgical ecosystem offerings. Intuitive Surgical anchors the robotic system tier with installed base concentration across major academic centers. Olympus Corporation and B. Braun represent the diversified medical technology conglomerate structure competing through breadth across visualization, energy, and manual instrument categories. Richard Wolf GmbH exemplifies the specialized German engineering archetype in rigid endoscopy manufacturing. These entities collectively illustrate the competitive tension between capital-intensive platform dominance and high-velocity disposable replenishment economics.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson (Ethicon) |
| Intuitive Surgical |
| Olympus Corporation |
| B. Braun |
| Teleflex |
| Richard Wolf GmbH |
| Medela Healthcare |
| LivaNova |
| Others |
Value Network & Pricing Analysis
Underutilized robotic platform capacity in United States community hospitals is compressing per-procedure pricing for minimally invasive thoracic systems while simultaneously pressuring suppliers to extend service contract terms. This utilization gap forces original equipment manufacturers to bundle disposable instrument replenishment at discounted rates, reshaping margin architectures across the value chain.
Pricing Analysis
Long-term service contracts with multi-year instrument replenishment commitments dominate procurement for robotic thoracic platforms, while disposable stapler cartridges trade on spot purchasing cycles through group purchasing organizations. Price differentiation hinges on FDA 510(k) clearance tier and bundled visualization-energy system integration, with academic medical centers absorbing premium positioning against community hospital price sensitivity. Cost compression in mid-tier powered stapling systems is intensifying because tungsten supply volatility feeds raw material uncertainty into cartridge pricing. Independent distributors face the steepest buyer price resistance as integrated delivery networks consolidate vendor relationships.
Supply Chain Analysis
Export-control restrictions on precision motion-control components limit robotic platform subassembly flows from Japan and Germany into Chinese manufacturing operations. Surgical staple manufacturing concentrates in China, Mexico, and the United States, with tungsten wire drawing and cobalt alloy processing feeding from concentrated East Asian suppliers. Single-source vulnerability around high-torque surgical motors creates supply chain risk for next-generation powered stapler production. Distribution runs through direct manufacturer sales organizations displacing independent distributors, particularly in Texas and Florida where health system mergers accelerate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
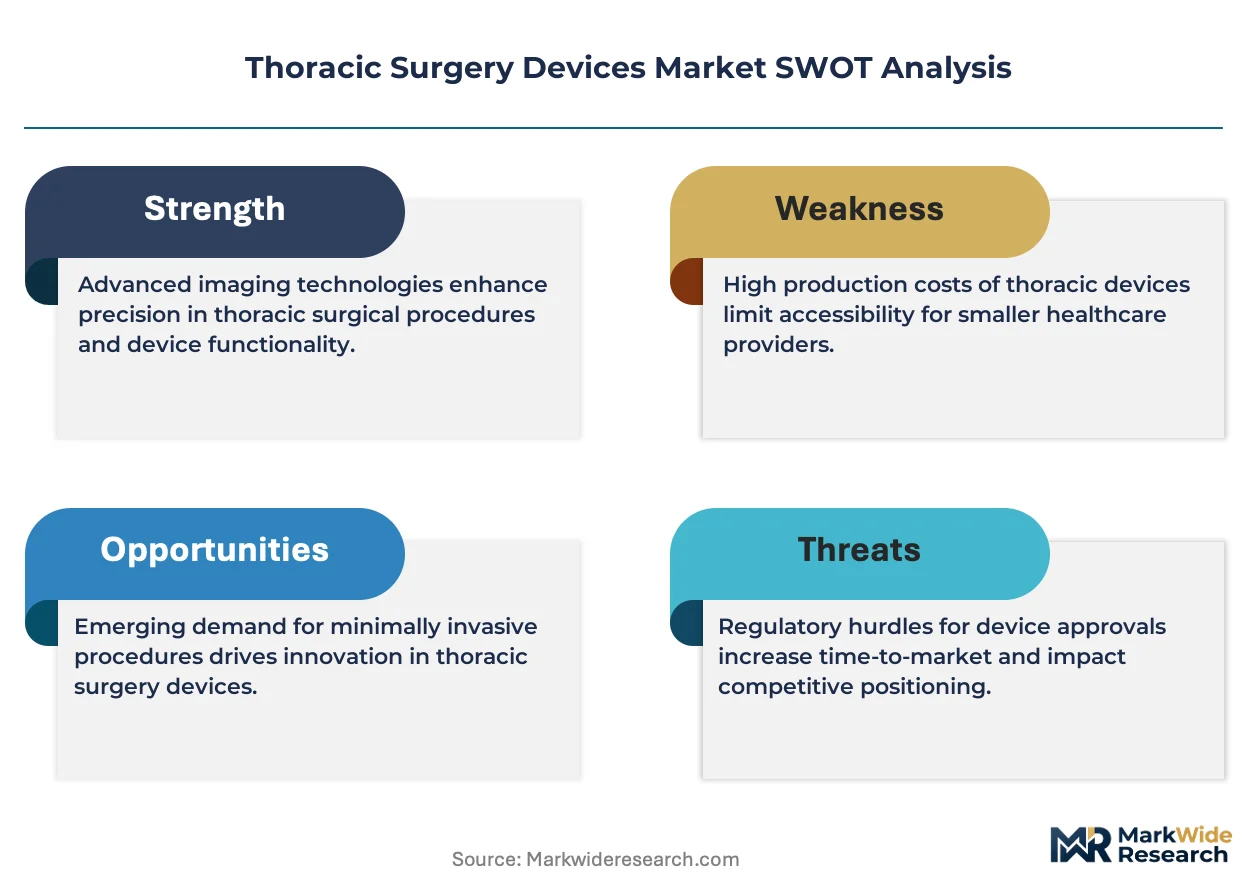
Buyer power is shifting toward integrated delivery networks in the United States as hospital consolidation in Texas and Florida concentrates procurement authority into centralized value analysis committees. This structural concentration forces vendors into single-source agreements spanning staplers, energy devices, and visualization systems.
For Market Incumbents: Entrench installed base stickiness through multi-year service contracts anchoring robotic platform maintenance with exclusive instrument replenishment terms. Deepen backward integration into tungsten wire processing to buffer raw material cost volatility from East Asian supply concentration. Prioritize CE marking pathway investment under EU MDR expanded clinical evidence requirements to defend against emerging European competitors. For New Entrants and Emerging Players: Establish a beachhead in third-party sterilization services for powered stapler cartridge reprocessing, an aftermarket segment underserved by original equipment manufacturers. Target Japan's Nippon Medical School-affiliated hospitals where demographic pressure on thoracic surgeons creates demand for assistive automation alternatives to established robotic platforms. Pursue regulatory sandbox pathways through PMDA pilot programs to accelerate market access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic surgical system manufacturing as FDA premarket validation standards tighten for next-generation platforms. Five-to-ten year viability favors vendors with installed base concentration and recurring instrument revenue streams over pure capital equipment plays. Watch reimbursement parity between robotic-assisted and conventional video-assisted thoracic surgery as the signal for demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerated premarket review timelines shorten product launch cycles for powered staplers. |
| Hospital System Partnership | Single-source agreements with Texas and Florida IDNs lock out independent distributors. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend certification timelines for Class III devices. |
| Software Companion Development | AI-powered preoperative planning with CT segmentation enables patient-specific pathway optimization. |
| Reimbursement Strategy | Parity between robotic-assisted and conventional VATS procedure codes determines platform adoption speed. |
Research Methodology
A spread of perspectives from thoracic surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare procedure code databases, and hospital procurement contract records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply-balance dynamics anchored the forecast framework, with procedure volume elasticity modeled against robotic platform installed base expansion and disposable instrument replenishment cycles. Segmentation dimensions included product type, application, end user, and technology tier alongside geographic regulatory cluster differentiation. CAGRs derived from regression analysis of historical adoption curves and elasticity-adjusted projection scenarios, with specific inputs from lung cancer screening program expansion rates and academic medical center consolidation patterns.
Sensitivities concentrate around reimbursement parity revisions, tungsten supply disruption, and EU MDR certification timeline extensions. Forecasts reflect documented assumptions regarding procedure volume growth and capital equipment amortization schedules. Material shifts in FDA premarket notification requirements or integrated delivery network merger velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Japan Respiratory Devices Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Needle-Free Vaccine Injectors Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Glass Syringe Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Global Laparoscopy Devices Market