
 Global Implantable Loop Recorder Market | 2026-2036
Global Implantable Loop Recorder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Implantable Loop Recorder Market Analysis
A shift from single-source component supply toward multi-source qualification is restructuring procurement strategies across implantable loop recorder manufacturing. Medtronic plc leverages backward integration into biosensor fabrication to protect margin pools on next-generation devices. Abbott Laboratories anchors its position through R&D intensity in miniaturized battery architectures. Boston Scientific Corporation competes by dominating channel relationships with electrophysiology labs across North American hospital networks.
An implantable loop recorder is a subcutaneous cardiac monitoring device, typically measuring 61 mm by 19 mm by 8 mm, that continuously records electrocardiographic data for up to three years to detect infrequent arrhythmias. The device employs solid-state memory and wireless telemetry to transmit captured events to remote monitoring platforms, serving primarily as a diagnostic bridge for patients with unexplained syncope or cryptogenic stroke. Wireless transmission technology leads in innovation velocity as manufacturers race to reduce latency between arrhythmic event detection and physician alert, while the hospital end-user segment sustains the deepest margin pools due to bundled procedural reimbursement and high implantation volumes. Single-use devices occupy the mature volume tier, with reusable systems gaining traction only in select research laboratory settings.
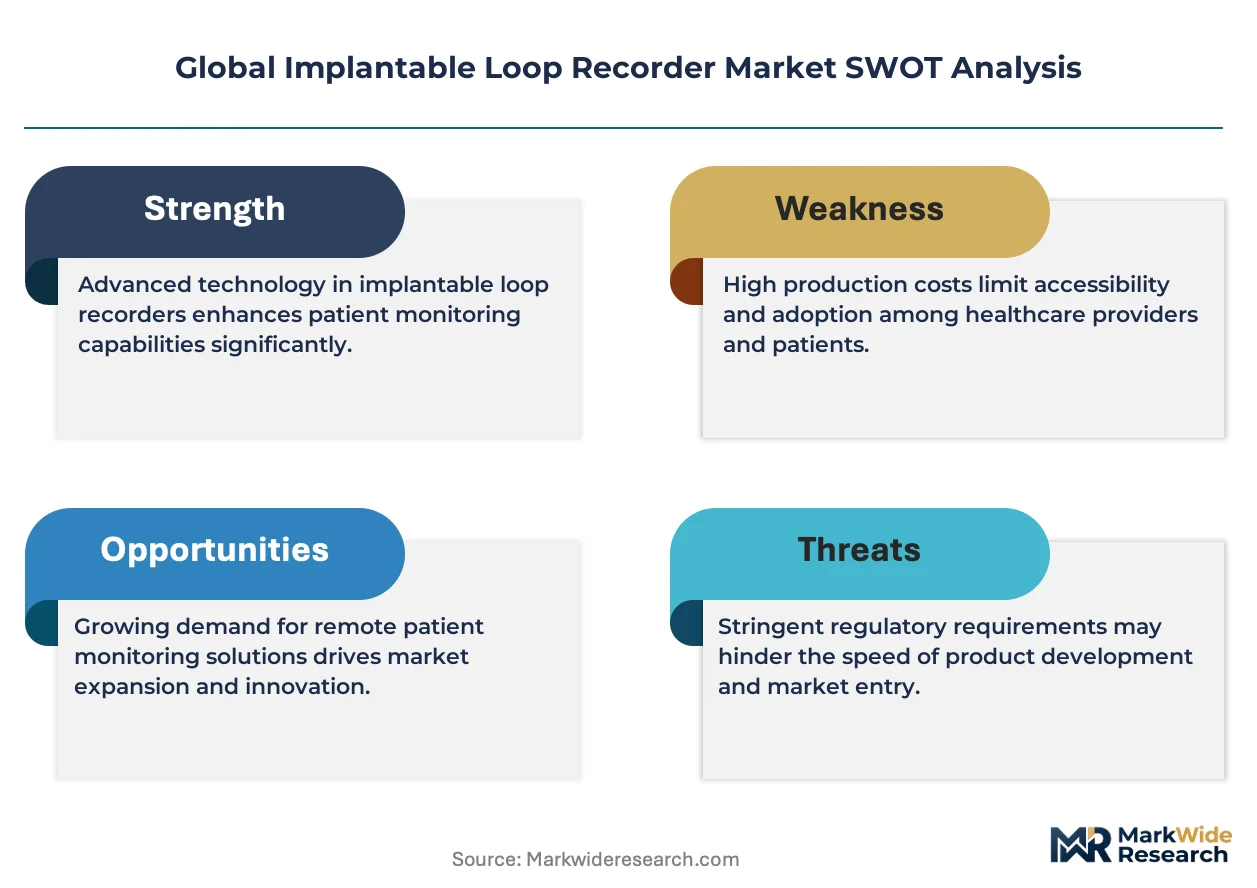
FDA premarket approval requirements and the EU MDR framework enforce escalating clinical evidence standards for implantable loop recorder biocompatibility and electromagnetic safety, directly extending development timelines and consolidating market access among well-capitalized manufacturers. Japan's PMDA adds a separate layer of domestic clinical trial obligations that filters entrants without established Asia-Pacific infrastructure. Stakeholders must monitor how emerging smart sensor integration triggers reclassification debates among regulators, as algorithm-enabled diagnostic autonomy reshapes traditional device-versus-software regulatory boundaries.
Market Dynamics
Wireless telemetry integration is compressing alert latency windows while FDA and EU MDR biocompatibility mandates extend development timelines, forcing capital reallocation toward regulatory infrastructure and away from pure R&D velocity.
Growth Catalysts
- Ambulatory monitoring expansion:Cardiology clinics in Germany and Japan are scaling implant volumes for cryptogenic stroke workups, supported by favorable procedural reimbursement frameworks.
- EU MDR framework alignment:Harmonized clinical evidence standards across member states reduce redundant certification costs for manufacturers with established European notified body relationships.
- Solid-state memory advances:Higher-density storage architectures enable three-year continuous ECG recording without device replacement, reducing total cost of ownership for hospital systems.
Market Restraints
- Precious metal input volatility:Platinum-iridium electrode costs fluctuate with mining supply disruptions, squeezing gross margins on single-use disposable components.
- Asia-Pacific clinical trial duplication:Japan's PMDA requires domestic patient cohorts regardless of FDA PMA approval, adding 18-24 months to market entry timelines.
- External Holter substitution:Two-week patch monitors from cardiac wearable manufacturers capture low-risk syncope cases that previously advanced to ILR implantation.
Strategic Opportunities
- Algorithm-enabled diagnostic autonomy:Machine learning arrhythmia classification is unifying detection and triage functions, creating software-as-medical-device revenue streams beyond hardware sales.
- Remote monitoring platform integration:Cloud-based telemetry hubs in United States hospital networks enable subscription-based recurring revenue models detached from implant procedure volume.
- Smart sensor convergence:Integration of accelerometry and temperature sensing with ECG recording expands addressable indications to heart failure monitoring and medication response tracking.
Industry Challenges
- Electrophysiology talent scarcity:Trained implanter capacity constraints in secondary United States markets limit procedural volume growth despite patient demand.
- Electromagnetic safety recertification:MRI conditional labeling upgrades require extensive coil testing, delaying product refresh cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Implantable Loop Recorder Market |
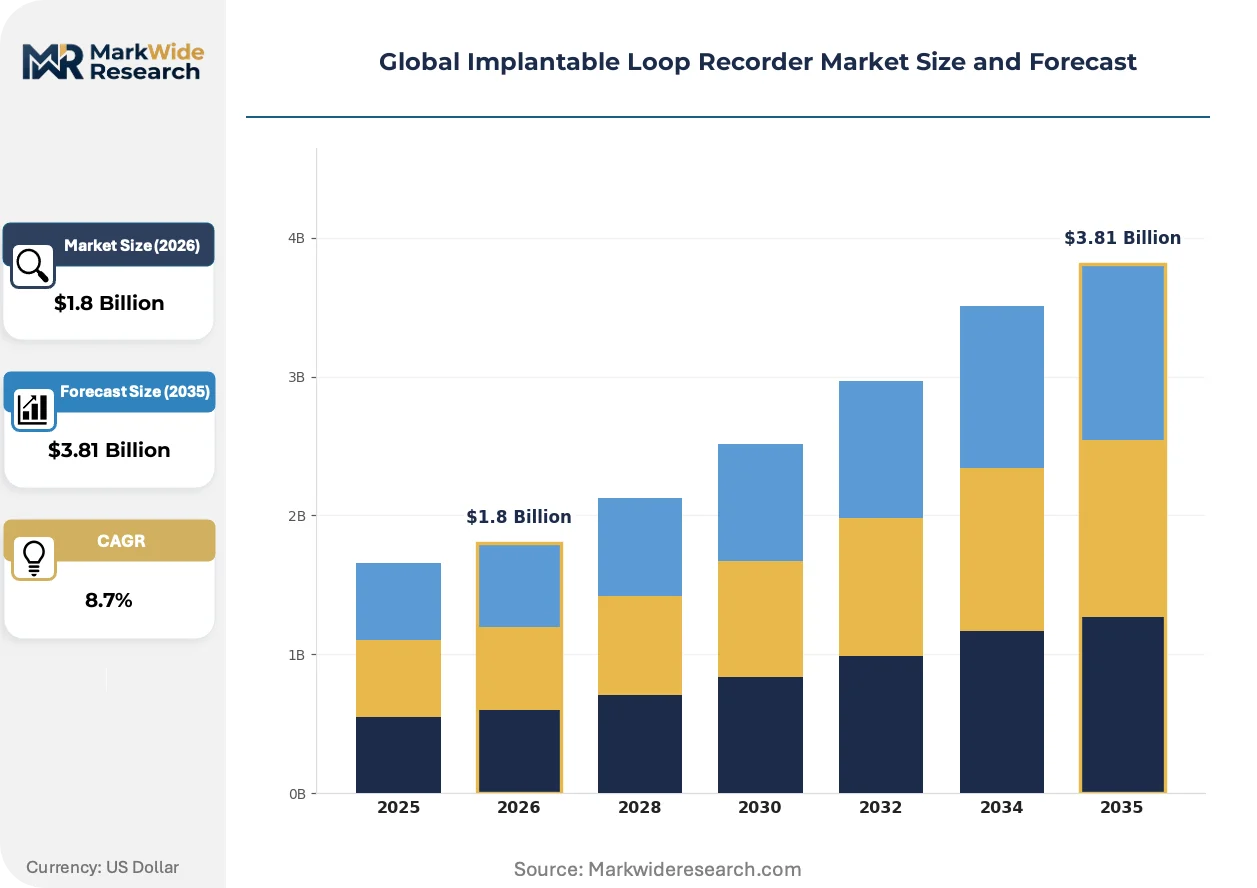
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Invasive, Non-Invasive End User: Cardiology Clinics, Hospitals, Home Healthcare, Research Laboratories Technology: Smart Sensors, Wireless Transmission, Battery-Powered, Implantable Devices Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Others |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Biotronik SE & Co. KG, Angel Medical Systems, Inc., Vectorious Medical Technologies Ltd., Koninklijke Philips N.V., GE Healthcare, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Implantable Loop Recorder Market Emerging Trajectories
Diagnostic autonomy algorithms and miniaturized power architectures are redrawing competitive boundaries between hardware incumbents and software-native entrants, while regulatory reclassification debates reshape market access requirements.
Subcutaneous leadless ECG acquisition is unifying sensing and transmission into single-chip architectures, eliminating discrete wirebond interconnections. Electrophysiology labs in United States academic medical centers are piloting these devices for same-day discharge protocols. This unification is compressing the traditional three-tier supplier base into direct semiconductor foundry relationships.
EU MDR post-market surveillance mandates now require annual periodic safety update reports with real-world performance data, elevating clinical affairs headcount requirements. Manufacturers must maintain notified body engagement across multiple member states simultaneously. Smaller device firms without captive European regulatory infrastructure face exclusion from hospital procurement frameworks.
Hospital buying committees are consolidating implantable cardiac monitor purchasing under centralized cardiology service line contracts, displacing individual physician preference item selection. Integrated delivery networks in United States metropolitan markets now negotiate multi-year supply agreements bundling devices with remote monitoring subscriptions. This concentration is most visible in Texas and Florida health systems where electrophysiology service line consolidation has accelerated since 2022.
Global Implantable Loop Recorder Market Segmentation
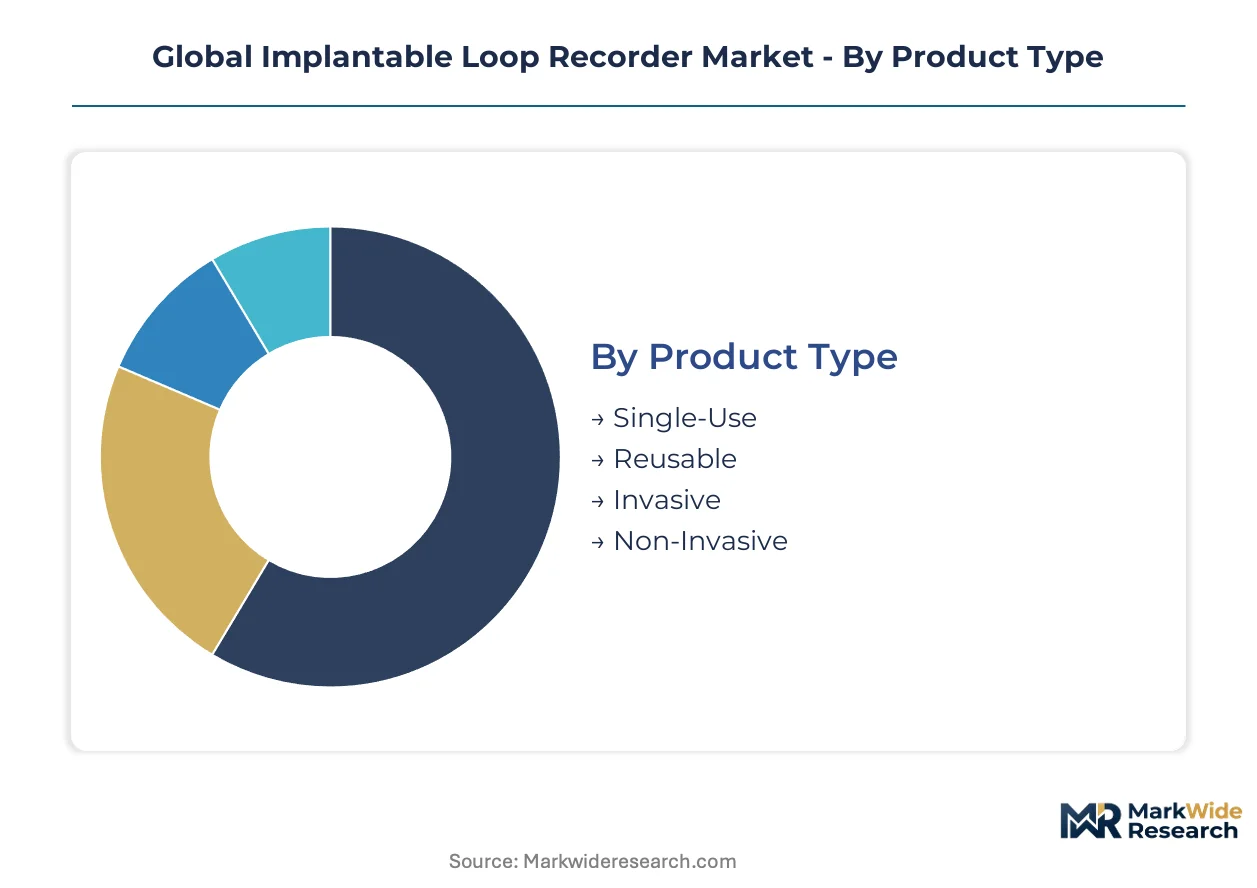
Implantable loop recorder manufacturers navigate divergent customization requirements across clinical settings, from standardized hospital procurement to tailored research laboratory specifications. Segmentation reveals how technology architecture and channel strategy determine margin capture and regulatory pathway complexity.
Product Type:
Customization intensity spans from disposable single-use units to precision-refurbished reusable systems, with invasiveness level dictating sterilization protocols and reimbursement coding.
- Single-Use:Pre-sterilized disposable units with fixed three-year battery life dominate hospital implant volumes. United States electrophysiology labs favor these devices for cryptogenic stroke protocols where device retrieval risks outweigh cost considerations.
- Reusable:Sterilizable platforms with replaceable power modules serve research laboratories in Germany conducting longitudinal arrhythmia studies. Limited commercial traction outside academic medical centers due to FDA biocompatibility recertification burdens.
- Invasive:Subcutaneous implantation requiring local anesthesia and sterile field conditions. Standard configuration for ambulatory monitoring expansion in Japan's aging demographic cohorts.
- Non-Invasive:External patch-based alternatives competing at the diagnostic threshold before ILR commitment. Two-week monitoring windows capture low-risk syncope cases in United States cardiology clinics.
Leading the category by volume: Single-Use. Growing fastest: Reusable in European research settings.
End User:
Procurement authority concentrates differently across settings, from centralized hospital buying committees to individual principal investigator discretion in research laboratories.
- Cardiology Clinics:Ambulatory-focused facilities scaling implant volumes for cryptogenic stroke workups. Germany's favorable procedural reimbursement frameworks accelerate adoption.
- Hospitals:Bundled reimbursement environments with deepest margin pools. United States integrated delivery networks negotiate multi-year supply agreements combining devices with remote monitoring subscriptions.
- Home Healthcare:Remote monitoring platform integration enables patient discharge with telemetry continuity. Emerging segment constrained by electrophysiology talent scarcity for remote troubleshooting.
- Research Laboratories:Custom protocol requirements drive small-batch manufacturing relationships. Japan's PMDA domestic trial obligations filter supplier selection to established Asia-Pacific infrastructure holders.
Hospitals command procurement volume leadership. Home Healthcare demonstrates steepest expansion trajectory as remote monitoring platforms mature.
Technology:
Component integration depth separates modular battery-powered architectures from unified smart sensor systems, with wireless transmission determining alert latency performance.
- Smart Sensors:Accelerometry and temperature sensing convergence expands indications to heart failure monitoring. Algorithm-enabled diagnostic autonomy triggers regulatory reclassification debates.
- Wireless Transmission:Solid-state memory paired with telemetry compresses physician alert windows. Race among manufacturers to reduce latency between arrhythmic detection and clinical response.
- Battery-Powered:Miniaturized lithium-carbon monofluoride cells enabling three-year continuous recording. Abbott Laboratories anchors competitive position through R&D intensity in this architecture.
- Implantable Devices:Leadless ECG acquisition unifying sensing and transmission into single-chip designs. United States academic medical centers pilot same-day discharge protocols.
Wireless Transmission leads technology deployment by volume. Smart Sensors gain share fastest as multi-parameter monitoring indications proliferate.
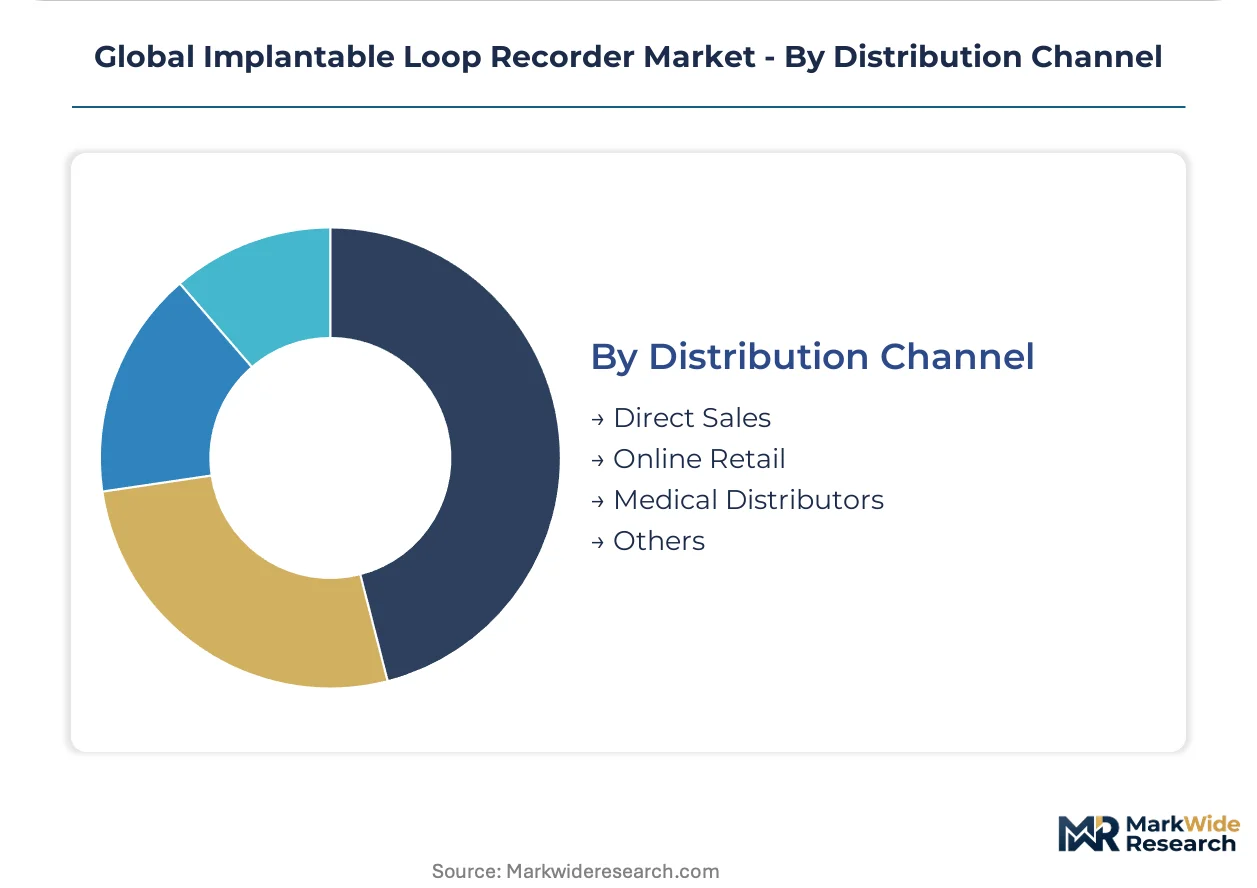
Distribution Channel:
Channel concentration reflects capital intensity requirements, from high-touch direct sales for complex implantation training to transactional online retail for accessory replenishment.
- Direct Sales:Manufacturer-employed specialists providing implanter training and remote monitoring platform integration. Dominates United States hospital network contracting.
- Online Retail:Limited to accessory and replacement components in markets with established remote monitoring infrastructure. Regulatory documentation requirements constrain device sales.
- Medical Distributors:Regional inventory holding with sterilization logistics capabilities. Critical for EU MDR post-market surveillance mandate compliance across multiple member states.
- Others:Group purchasing organizations and consignment arrangements in Texas and Florida health systems where electrophysiology service line consolidation accelerated since 2022.
Direct Sales channels capture volume leadership. Medical Distributors expand most quickly as EU MDR compliance burdens elevate clinical affairs requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum-iridium electrode supply chains anchor manufacturing concentration in Germany and the United States, while Japan's domestic clinical trial requirements filter market access to established Asia-Pacific infrastructure holders.
United States
FDA premarket approval pathways and bundled reimbursement frameworks drive hospital procurement consolidation across integrated delivery networks. Electrophysiology service line contracts in Texas and Florida health systems accelerated multi-year supply agreements since 2022. Boston Scientific Corporation dominates channel relationships with electrophysiology labs across North American hospital networks.
Germany
Favorable procedural reimbursement frameworks accelerate cardiology clinic implant volumes for cryptogenic stroke workups. EU MDR post-market surveillance mandates require annual periodic safety update reports with real-world performance data. Research laboratories in Baden-Württemberg conduct longitudinal arrhythmia studies using precision-refurbished reusable platforms.
Japan
PMDA domestic clinical trial obligations add 18-24 months to market entry timelines regardless of FDA PMA approval. Aging demographic cohorts sustain procedural volume expansion in electrophysiology infrastructure. Tokyo academic medical centers pilot leadless ECG acquisition devices for same-day discharge protocols.
United Kingdom
NHS England procurement frameworks consolidate implantable cardiac monitor purchasing under centralized cardiology service line contracts. MHRA alignment with EU MDR clinical evidence standards reduces redundant certification costs for established European notified body relationships. London teaching hospitals drive remote monitoring platform integration with cloud-based telemetry hubs.
China
NMPA regulatory pathways for implantable cardiac monitors tighten documentation requirements for long-term biocompatibility data. Domestic electrophysiology infrastructure expansion supports procedural volume growth in tertiary hospital networks. Shanghai medical device clusters attract multi-source qualification strategies from global manufacturers seeking supply chain resilience.
Global Implantable Loop Recorder Market Vendor Landscape
Backward integration into critical component supply dominates the current landscape as manufacturers protect margin pools on next-generation devices. The vendor base concentrates among well-capitalized participants with captive regulatory infrastructure across FDA, EU MDR, and PMDA jurisdictions. Three archetypes define competitive positioning: diversified medical technology conglomerates with electrophysiology channel dominance, cardiac rhythm management specialists with miniaturized power architecture expertise, and emerging smart sensor integrators pursuing algorithm-enabled diagnostic autonomy. M&A activity and vertical integration into biosensor fabrication represent the dominant competitive moves reshaping supply chain control.
Among diversified medical technology conglomerates, Medtronic plc exemplifies backward integration strategy through in-house biosensor fabrication capabilities. Abbott Laboratories anchors the specialist tier through R&D intensity in miniaturized battery architectures. Boston Scientific Corporation occupies a position defined by electrophysiology lab channel relationships across North American hospital networks.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Biotronik SE & Co. KG |
| Angel Medical Systems, Inc. |
| Vectorious Medical Technologies Ltd. |
| Koninklijke Philips N.V. |
| GE Healthcare |
| MicroPort Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks in United States metropolitan markets command procurement leverage through multi-year supply agreements that bundle implantable loop recorders with remote monitoring subscriptions. This buyer concentration shifts pricing power toward volume-based contract structures and away from list-price transactional models.
Pricing Analysis
Remote monitoring platform subscriptions bundled with device procurement dominate commercial arrangements, separating hardware acquisition from recurring telemetry service revenue. Price differentiation hinges on MRI conditional labeling tier and the scope of algorithm-enabled diagnostic autonomy included in the service tier. Cost compression in single-use disposable components intensifies as platinum-iridium electrode input volatility squeezes manufacturer gross margins. Research laboratories in Germany demonstrate lowest price sensitivity due to custom protocol requirements, while United States cardiology clinics face acute budget scrutiny under bundled reimbursement frameworks.
Supply Chain Analysis
Freight logistics for temperature-controlled biocompatible component transport add cost layers between German platinum-iridium electrode foundries and United States assembly facilities. Manufacturing concentration centers on Germany, the United States, and Japan, with each jurisdiction hosting specialized cleanroom fabrication for cardiac biosensors. Raw material dependencies include lithium-carbon monofluoride cells, solid-state memory architectures, and medical-grade silicone encapsulants. Single-source vulnerability in semiconductor foundry capacity for leadless ECG acquisition chips represents the dominant structural risk. Distribution runs through manufacturer-employed direct sales specialists for hospital network contracting, supplemented by regional medical distributors handling EU MDR post-market surveillance compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Implantable loop recorder manufacturing capacity is constrained by electrophysiology talent scarcity and cleanroom biosensor fabrication bottlenecks, propping pricing power for incumbent suppliers with captive production infrastructure.
For Market Incumbents: Hedge against algorithm-native diagnostic autonomy entrants by accelerating backward integration into semiconductor foundry relationships for leadless ECG acquisition chips. Secure multi-year platinum-iridium electrode supply agreements before mining supply disruptions intensify. Protect margin pools by embedding remote monitoring platform subscriptions into hospital system contracts before procurement consolidation completes. For New Entrants and Emerging Players: Begin with home healthcare telemetry integration, the segment demonstrating steepest expansion trajectory as remote monitoring platforms mature and electrophysiology talent scarcity constrains incumbent service capacity. Target Japan's PMDA domestic trial infrastructure gaps by partnering with established Asia-Pacific regulatory affairs consultancies. Pursue software-as-medical-device revenue streams through algorithm-enabled arrhythmia classification rather than hardware manufacturing. For Investors and Strategic Acquirers: The window for entry favors mid-cap cardiac rhythm management specialists with captive miniaturized battery architecture expertise and established European notified body relationships. Long-term viability over the next decade rests on regulatory infrastructure depth across FDA, EU MDR, and PMDA jurisdictions simultaneously. Watch for EU MDR reclassification debates around diagnostic autonomy algorithms as the inflection signal for software-native competitive displacement.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Engagement | Annual periodic safety update reports require dedicated clinical affairs headcount across multiple member states. |
| Backward Integration into Biosensor Fabrication | Medtronic plc's in-house production protects margin pools on next-generation leadless ECG acquisition devices. |
| Remote Monitoring Platform Integration | Cloud-based telemetry hubs enable subscription-based recurring revenue detached from implant procedure volume. |
| Multi-Source Qualification Strategy | Procurement resilience demands qualification of alternative platinum-iridium electrode suppliers beyond German concentration. |
| Algorithm-Enabled Diagnostic Autonomy Development | Machine learning arrhythmia classification triggers regulatory reclassification debates reshaping traditional device boundaries. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across electrophysiology lab directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA premarket approval documentation, EU MDR notified body filings, and Japan PMDA domestic trial registrations provided procedural volume and regulatory pathway intelligence. Bottom-up implant volume modeling by country and hospital system triangulated against top-down manufacturer revenue segmentation.
Granularity-level modeling deployed product type, end user, technology architecture, and distribution channel dimensions at the country level across the analysis window. CAGRs derived from logistic curve fitting to procedural volume expansion trajectories, adjusted for reimbursement framework changes and electrophysiology infrastructure buildout rates. Forecast inputs incorporated aging demographic cohort projections, cryptogenic stroke protocol adoption curves, and smart sensor convergence timelines for heart failure monitoring indications.
Underlying measurement precision varies by segment; hospital procurement data carries tighter precision than research laboratory custom manufacturing estimates. Forecasts reflect documented assumptions regarding regulatory approval timelines, reimbursement stability, and raw material supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Smart Infusion Pump Market