
 Paclitaxel Injection Market | 2026-2036
Paclitaxel Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Paclitaxel Injection Market Analysis
Oncology clinics is rebalancing toward ambulatory administration as hospitals shift complex infusions to lower-acuity settings. Bristol-Myers Squibb Company anchors the branded originator segment through decades of clinical data accumulation. Fresenius Kabi AG competes aggressively in the generic vial space across European and Asian markets. Dr. Reddy's Laboratories Ltd. extends its footprint via contract manufacturing and emerging-market registrations.
Paclitaxel injection is a taxane-class antineoplastic agent formulated as a Cremophor EL-based or albumin-bound nanoparticle suspension for intravenous administration, primarily indicated for ovarian, breast, and non-small cell lung carcinomas. Single-dose vials dominate hospital procurement due to sterility assurance and waste minimization protocols, while liposome-encapsulated formulations command premium positioning in markets prioritizing reduced hypersensitivity incidence. Pre-filled syringes represent the fastest-growing product configuration as outpatient oncology centers seek to compress preparation time and dosing error rates.
The FDA, EMA, and NMPA collectively enforce stringent sterility, endotoxin, and particulate-matter specifications that determine manufacturing facility qualification and batch-release timelines. The FDA's biosimilar interchangeability guidance and China's NMPA consistency-evaluation requirements for generic injectables are tightening quality thresholds and extending development lead times. Stakeholders must monitor regulatory divergence between major agencies to anticipate where formulation investments will yield accelerated market access versus prolonged review cycles.
Market Dynamics
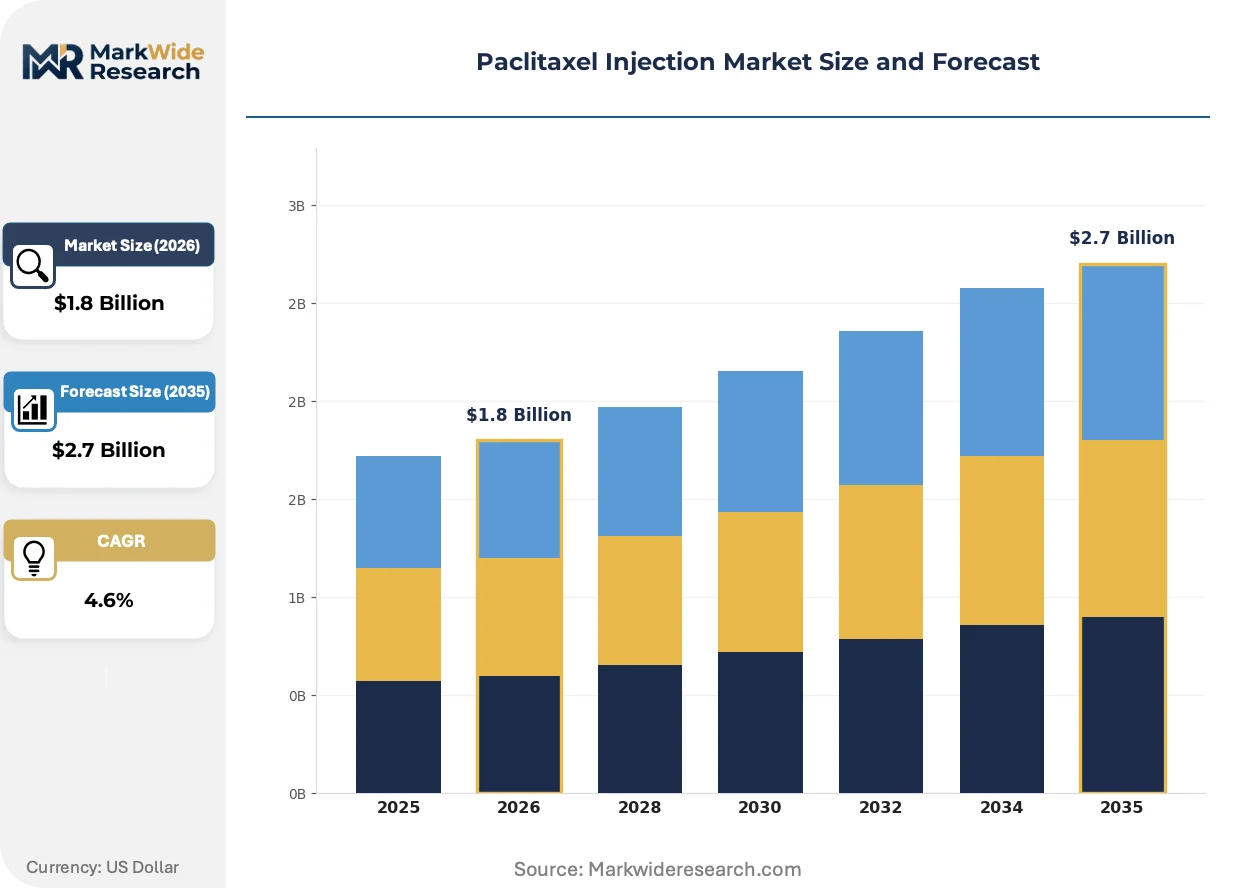
The Paclitaxel Injection Market is experiencing structural pressure from the FDA's biosimilar interchangeability pathway, which is compressing originator pricing power while accelerating generic formulation investments across manufacturing networks.
Growth Catalysts
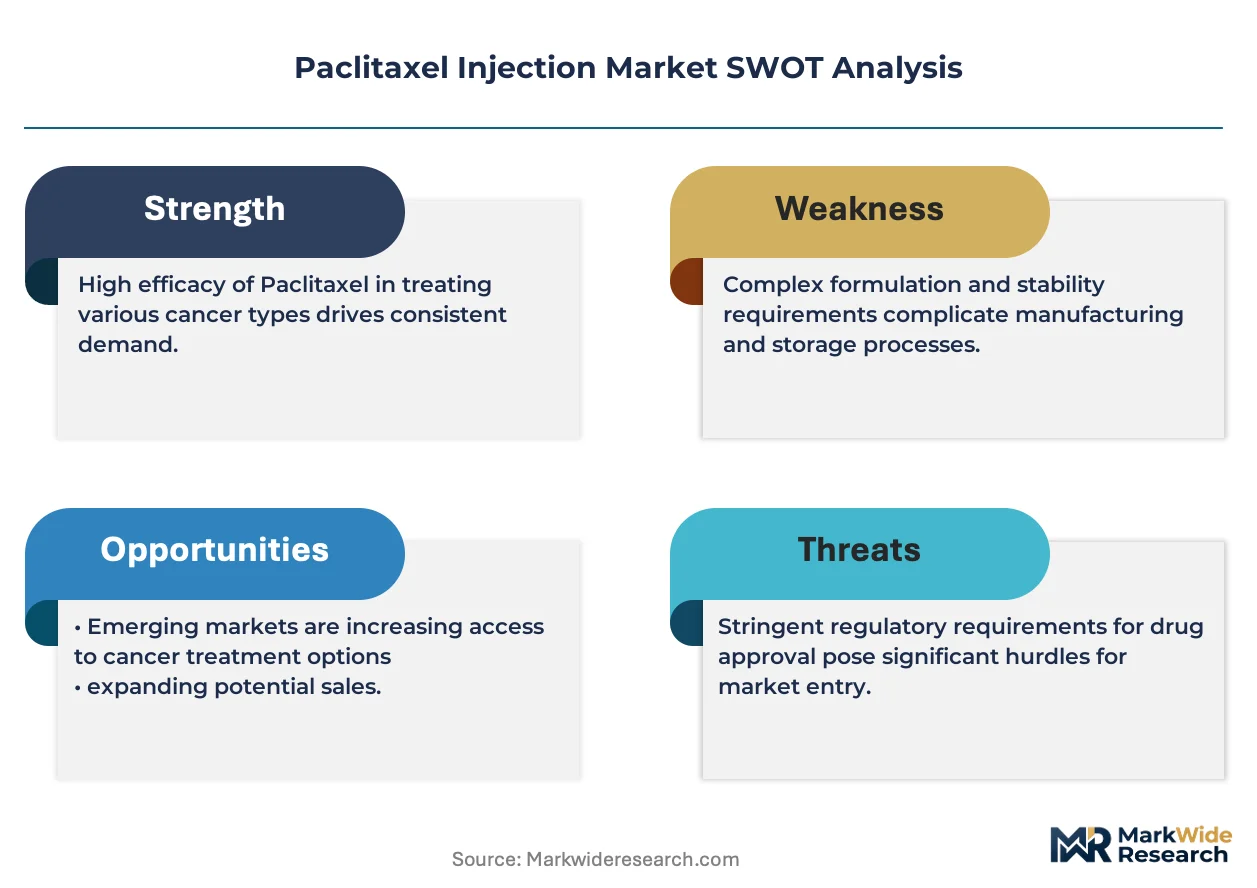
- EMA sterility harmonization:Unified endotoxin and particulate-matter standards across EU member states are reducing batch-release friction for multi-market injectable suppliers.
- Ambulatory oncology expansion:Hospital systems in the United States are relocating complex infusions to lower-acuity outpatient centers, expanding addressable vial demand.
- Nanoparticle suspension technology:Albumin-bound formulations are displacing Cremophor EL-based alternatives in hypersensitivity-sensitive patient populations.
Market Restraints
- API supply concentration:Paclitaxel active pharmaceutical ingredient production clusters in specific Asian manufacturing zones, creating single-source vulnerability.
- NMPA consistency-evaluation timelines:China's extended generic injectable review cycles are delaying market entry for new entrants by 18-24 months.
- Formulation complexity:Liposome-encapsulated variants require specialized aseptic processing capabilities that limit contract manufacturing options.
Strategic Opportunities
- Pre-filled syringe penetration:Outpatient oncology centers in Germany are adopting ready-to-administer formats to compress preparation time and dosing error rates.
- CDSCO fast-track pathway:India's abbreviated approval route for oncology injectables offers accelerated access for manufacturers with prior FDA or EMA clearance.
- Home infusion services:Specialty pharmacy networks are building ambulatory administration capabilities that bypass traditional hospital procurement.
Industry Challenges
- Aseptic processing workforce scarcity:Qualified personnel for sterile injectable manufacturing remain concentrated at established facilities, constraining capacity expansion.
- Multi-jurisdiction filing synchronization:Divergent FDA, EMA, and NMPA documentation requirements force redundant stability studies and analytical method validations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paclitaxel Injection Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Dose Vials, Multi-Dose Vials, Pre-filled Syringes, Infusion Bags End User: Hospitals, Ambulatory Surgical Centers, Oncology Clinics, Research Institutions Formulation: Concentrated Solutions, Liposome-Encapsulated, Injectable Emulsions, Sustained Release Administration Route: Intravenous, Intramuscular, Subcutaneous, Intra-arterial |
| Companies Covered | Bristol-Myers Squibb Company, Pfizer Inc., Fresenius Kabi AG, Dr. Reddy’s Laboratories Ltd., Accord Healthcare, Sun Pharmaceutical Industries Ltd., Viatris Inc., Abbott, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paclitaxel Injection Market Emerging Trajectories
Formulation technology and administration settings are converging to reshape competitive positioning in taxane-class chemotherapy delivery. Three developments warrant particular attention.
Albumin-bound nanoparticle suspension is overtaking conventional Cremophor EL-based formulations in outpatient settings where hypersensitivity monitoring resources are limited. Oncology clinics in the United States are standardizing on nanoparticle alternatives for breast and lung carcinoma protocols. This shift is compressing demand for premedication regimens and enabling same-day administration workflows.
REACH-compliant solvent alternatives are forcing reformulation investments across European manufacturing networks. EMA guidance on residual solvent limits is disqualifying legacy Cremophor EL supply chains from new product registrations. Generic manufacturers with in-house nanoparticle capabilities are capturing tender share from suppliers dependent on imported conventional formulations.
Single-dose vial procurement is fragmenting across sterility-assurance tiers rather than volume-discount brackets. Hospital systems are unbundling waste-minimization protocols from price negotiations and certifying suppliers against internal particulate-matter thresholds. This behavior is most visible in German oncology networks, where pharmacy committees are mandating closed-system transfer device compatibility for all new paclitaxel contracts.
Paclitaxel Injection Market Segmentation
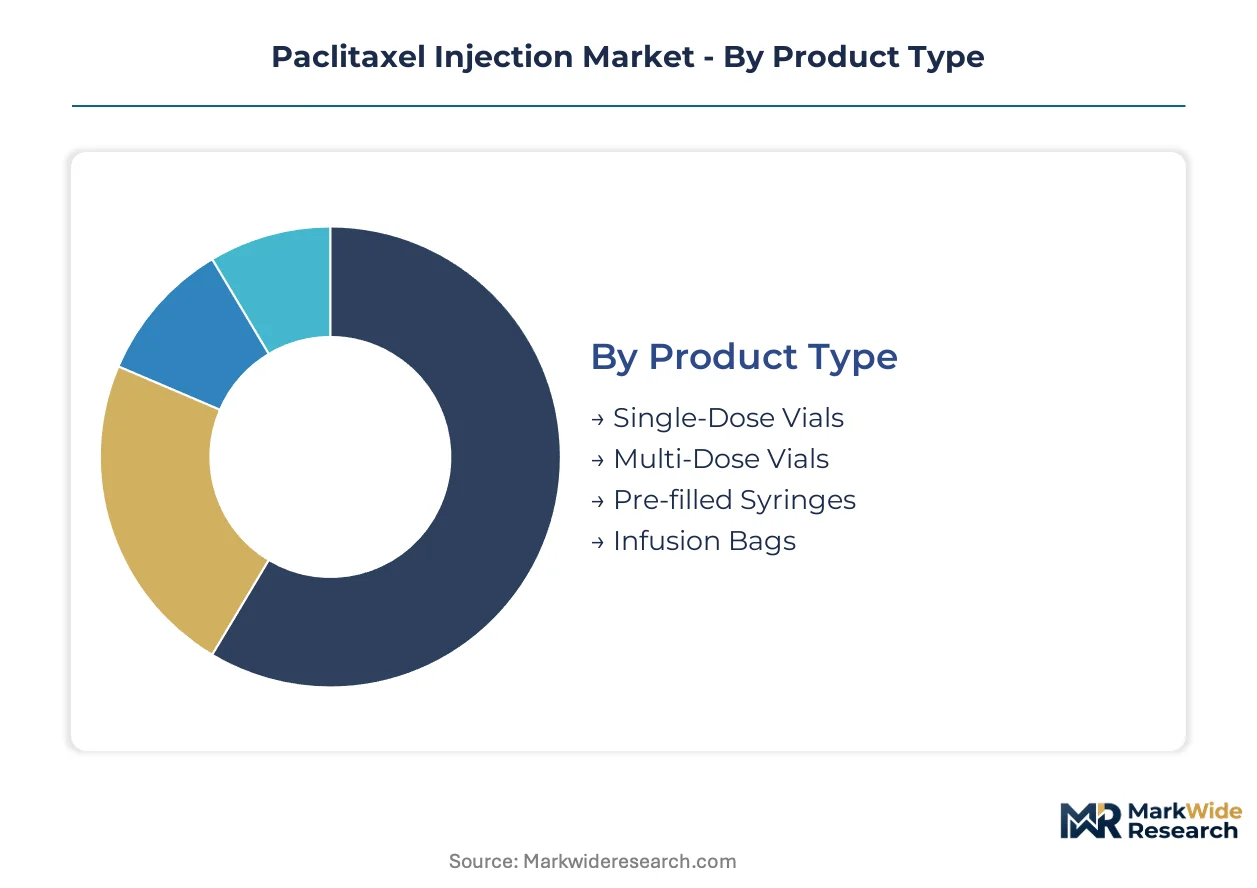
Paclitaxel injection procurement patterns diverge sharply between high-volume hospital systems and specialized outpatient settings. Formulation choice, vial configuration, and sterility assurance tiers now determine contract eligibility more than unit price alone.
Product Type:
Customization intensity varies from standard single-dose formats to patient-matched pre-filled configurations across this category.
- Single-Dose Vials:Sterile, terminally sterilized glass or polymer containers designed for one-time withdrawal and immediate administration. Hospital oncology departments in the United States specify these for Cremophor EL-based protocols where batch-to-batch sterility documentation is mandatory.
- Pre-filled Syringes:Ready-to-administer polymer or glass syringes with integrated needle safety systems. Oncology clinics in Germany are adopting these to compress preparation time and eliminate dosing error exposure in high-throughput ambulatory settings.
- Multi-Dose Vials:Rubber-stoppered containers with antimicrobial preservatives enabling multiple punctures.
- Infusion Bags:Flexible polymer reservoirs for extended infusion protocols.
Leading the category by volume: Single-Dose Vials. Growing fastest: Pre-filled Syringes.
End User:
Procurement sophistication scales from centralized hospital pharmacy committees to distributed specialty pharmacy networks.
- Hospitals:Integrated health systems with centralized oncology pharmacy operations, closed-system transfer device mandates, and waste-minimization protocols. These facilities in China concentrate demand for liposome-encapsulated formulations requiring extended infusion monitoring.
- Oncology Clinics:Dedicated cancer treatment centers operating outside hospital campuses with limited hypersensitivity response capabilities. United States outpatient networks here are standardizing on albumin-bound nanoparticle suspensions to reduce premedication burdens.
- Ambulatory Surgical Centers:Same-day surgical facilities with limited chemotherapy administration licensing.
- Research Institutions:Academic medical centers and contract research organizations conducting investigator-initiated trials.
Dominant procurement volume: Hospitals. Steepest expansion trajectory: Oncology Clinics.
Formulation:
Technology maturity spans decades-old Cremophor EL systems to emerging nanoparticle platforms with distinct manufacturing barriers.
- Concentrated Solutions:Cremophor EL-based or co-solvent systems requiring dilution prior to infusion and extended hypersensitivity monitoring. These formulations retain share in cost-sensitive markets where albumin-bound alternatives face reimbursement compression.
- Liposome-Encapsulated:Phospholipid bilayer-encapsulated paclitaxel enabling altered biodistribution and reduced toxicity profiles. Manufacturing complexity limits suppliers to facilities with specialized aseptic processing capabilities certified by EMA and FDA.
- Injectable Emulsions:Oil-in-water dispersions with surfactant stabilization.
- Sustained Release:Polymeric or lipid depot formulations extending therapeutic exposure.
Highest revenue concentration: Concentrated Solutions. Gaining share fastest: Liposome-Encapsulated.
Administration Route:
Clinical workflow requirements determine route selection from high-complexity infusion centers to simplified injection protocols.
- Intravenous:Infusion into central or peripheral venous access over hours with pump-controlled delivery. This route dominates ovarian, breast, and non-small cell lung carcinoma protocols across United States and German treatment guidelines.
- Subcutaneous:Depot or sustained-release injection into adipose tissue with reduced healthcare resource requirements. Emerging applications in maintenance therapy settings are driving formulation development investments.
- Intramuscular:Deep tissue injection with variable absorption kinetics.
- Intra-arterial:Catheter-directed delivery for localized perfusion in hepatic or limb perfusion protocols.
Standard of care by volume: Intravenous. Climbing the fastest: Subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate API synthesis and sterile injectable finishing for tax-advantaged export manufacturing. Hospital procurement networks in the United States and Germany anchor demand for high-assurance formulations.
United States
FDA's biosimilar interchangeability pathway accelerates generic entry while compressing originator pricing power across hospital formularies. The 340B drug pricing program reshapes procurement economics for oncology clinics serving underserved populations. New Jersey and Massachusetts pharmaceutical clusters host sterile injectable facilities supplying national distribution networks.
Germany
EMA sterility harmonization reduces batch-release friction for multi-market suppliers serving EU oncology networks. REACH-compliant solvent regulations disqualify legacy Cremophor EL supply chains from new product registrations. Bavarian manufacturing zones specialize in nanoparticle suspension technologies for export markets.
China
NMPA consistency-evaluation requirements extend generic injectable review timelines by 18-24 months for new market entrants. National reimbursement catalog updates prioritize albumin-bound formulations in tier-one hospital procurement. Jiangsu and Zhejiang provinces concentrate API fermentation and aseptic finishing capacity for domestic and export supply.
India
CDSCO fast-track approval routes for oncology injectables accelerate market access for manufacturers holding prior FDA or EMA clearance. Production-linked incentive schemes for pharmaceutical manufacturing attract investment in sterile injectable capacity. Hyderabad and Ahmedabad clusters specialize in contract research and manufacturing services for taxane-class formulations.
Paclitaxel Injection Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator data packages defending hospital formulary positions against biosimilar erosion. The vendor base concentrates around three strategic archetypes: originator multinationals with decades of clinical evidence, generic injectable specialists with multi-jurisdiction manufacturing footprints, and emerging-market contract manufacturers leveraging cost-optimized production. Competitive moves center on nanoparticle formulation licensing and sterile capacity expansion in tax-advantaged zones.
Within the originator tier, Bristol-Myers Squibb Company anchors the branded segment through accumulated clinical data assets. Among European generic injectable specialists, Fresenius Kabi AG occupies a position exemplifying multi-market regulatory compliance. Dr. Reddy's Laboratories Ltd. represents the emerging-market contract manufacturing archetype, extending footprint through registration strategies in priority markets.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Fresenius Kabi AG |
| Dr. Reddy's Laboratories Ltd. |
| Accord Healthcare |
| Sun Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Abbott |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Albumin-bound nanoparticle certification tiers bifurcate procurement economics between hypersensitivity-safe premium positioning and Cremophor EL-based commodity sourcing, with each tier demanding distinct API fermentation scale and aseptic finishing investments that reshape supplier margin structures across United States and German hospital networks.
Pricing Analysis
Short lead-time premiums attach to pre-filled syringe formats as German oncology clinics compress preparation workflows and eliminate compounding pharmacy delays. Three-tier pricing structure across premium nanoparticle, standard liposome-encapsulated, and economy concentrated solution levels reflects sterility assurance grade and closed-system transfer device compatibility. Price erosion runs through Cremophor EL-based vials as FDA biosimilar interchangeability accelerates generic entry. Hospital pharmacy committees in China demonstrate highest price sensitivity, while United States ambulatory networks prioritize preparation-time savings over unit cost.
Supply Chain Analysis
Regional distribution centers in Frankfurt and New Jersey anchor hub-and-spoke patterns for temperature-sensitive finished goods, with secondary spokes extending to oncology clinic networks. API synthesis clusters in Jiangsu province and Zhejiang province feed aseptic finishing operations in Bavaria and Massachusetts. Paclitaxel active pharmaceutical ingredient production draws from fermentation-derived 10-deacetylbaccatin III and semisynthetic taxane chemistry capabilities. Single-source vulnerability concentrates in Asian fermentation capacity for precursor supply. Distribution runs through specialty pharmaceutical wholesalers with cold-chain certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation is forcing consolidation among generic injectable suppliers lacking multi-jurisdiction filing capabilities, privileging scaled manufacturers with established FDA, EMA, and NMPA track records.
For Market Incumbents: Deepen backward integration into nanoparticle suspension technology to defend formulary positioning against biosimilar erosion, while expanding sterile capacity in tax-advantaged zones like India's production-linked incentive corridors to offset REACH-driven reformulation costs in European networks. For New Entrants and Emerging Players: Begin with CDSCO fast-track oncology injectable registrations leveraging prior FDA or EMA clearance to access India's abbreviated approval pathway, targeting pre-filled syringe white space in German ambulatory networks where preparation-time compression commands procurement priority. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale sterile injectable specialists possessing nanoparticle formulation licensing and existing EMA certification, given NMPA consistency-evaluation timelines extending competitive moats for compliant manufacturers. Watch NMPA batch-release acceleration signals as inflection indicator for generic entry velocity in China.| Strategic Initiative | Industry Significance |
|---|---|
| Nanoparticle Formulation Licensing | Albumin-bound technology access displaces Cremophor EL supply chains in REACH-compliant European markets. |
| Sterile Capacity Expansion | Aseptic finishing investments in Hyderabad and Ahmedabad clusters capture CDSCO fast-track oncology opportunities. |
| Multi-Jurisdiction Regulatory Filing | Synchronized FDA, EMA, and NMPA submissions reduce redundant stability study burdens for generic entrants. |
| Pre-filled Syringe Manufacturing Scale-Up | Ready-to-administer formats align with German outpatient oncology center procurement mandates. |
| Closed-System Transfer Device Compatibility | Particulate-matter certification meets German pharmacy committee contracting requirements. |
Methodological Framework
Document review covered FDA biosimilar interchangeability guidance, EMA sterility harmonization directives, and NMPA consistency-evaluation protocols, complemented by interviews with oncology pharmacy directors, sterile manufacturing executives, regulatory affairs leads, and hospital procurement managers. Secondary sources included ClinicalTrials.gov taxane protocol databases, formulary submission records, and customs trade data for API precursor movements. Bottom-up patient-volume modeling and top-down pharmaceutical spending allocation were triangulated against manufacturer capacity disclosures.
Market sizing outputs reflect segment-level demand modeling across formulation technology, vial configuration, and administration setting dimensions throughout the forecast period. CAGRs were derived from treatment protocol evolution assumptions, reimbursement catalog update trajectories, and regulatory approval pipeline tracking. Forecast inputs incorporated ambulatory oncology center expansion rates and nanoparticle formulation substitution curves.
Underlying measurement precision varies by segment; pre-filled syringe and liposome-encapsulated categories carry tighter precision than multi-dose vial estimates due to concentrated supplier disclosure. Forecasts reflect documented assumptions regarding NMPA review timeline stabilization and EMA solvent regulation enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Prescription Stimulants Market
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Alirocumab Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market