
 Middle East and Africa Refractive Surgery Devices Market | 2026-2036
Middle East and Africa Refractive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Refractive Surgery Devices Market Foresight
Modular platform configurations are broadening buyer choice across the Middle East and Africa refractive surgery landscape. SCHWIND eye-tech-solutions leverages its excimer-laser portfolio to anchor high-volume centers in South Africa and the Gulf. NIDEK sustains competitive pressure through differentiated topography-guided ablation workflows. Alcon dominates the femtosecond segment with integrated cataract-refractive platforms that extend its installed base across private hospital networks.
Refractive surgery devices comprise excimer lasers, femtosecond lasers, diagnostic aberrometers, and microkeratome systems engineered to reshape corneal curvature with sub-micron precision, typically operating at 193 nm wavelength for photoablation. These systems correct ametropia by programmed stromal tissue removal or lenticule extraction. LASIK Systems retain the largest installed base across ophthalmology clinics, though Small Incision Lenticule Extraction represents the fastest-growing technique as surgeons migrate toward flapless procedures. Keratome Devices occupy a contracting margin pool as mechanical systems face displacement by laser-assisted platforms in premium-tier facilities.
Saudi Arabia's SFDA and South Africa's national pharmaceutical regulator enforce device registration and clinical validation standards that shape market access timelines for imported laser platforms. The UAE's MOHAP and health free-zone frameworks accelerate approval pathways for manufacturers establishing regional distribution hubs. Stakeholders must monitor how Gulf regulatory harmonization and reimbursement policy divergence between public and private sectors will reshape procurement criteria and service-line investments across the forecast horizon.
Market Dynamics
Femtosecond laser platforms are displacing mechanical microkeratomes across premium ophthalmology suites in the Gulf and South Africa, compressing installed-base economics for legacy equipment vendors while elevating precision standards for corneal flap creation.
Growth Catalysts
- Medical tourism liberalization:The UAE's MOHAP and Saudi Arabia's health free-zone frameworks accelerate approval pathways for imported laser platforms, enabling private hospital chains to expand refractive service lines.
- SFDA registration harmonization:Streamlined device validation standards across Gulf Cooperation Council states reduce market access timelines for excimer and femtosecond systems.
- Flapless procedure migration:Small Incision Lenticule Extraction adoption is concentrating demand in high-volume centers capable of lenticule extraction workflows.
Market Restraints
- Capital intensity barrier:Femtosecond laser suites require substantial upfront investment, limiting procurement to private hospital networks with dedicated ophthalmology divisions.
- Import dependency concentration:Laser platform supply concentrates in German, Japanese, and US manufacturing bases, exposing buyers to currency volatility and extended lead times.
- Technical limitation in complex astigmatism:Topography-guided ablation workflows remain constrained in keratoconus-adjacent cases, restricting addressable patient populations.
Strategic Opportunities
- Egypt and North Africa penetration:Underdeveloped private ophthalmology infrastructure in Cairo and Alexandria presents first-mover positioning for modular excimer platforms.
- Integrated cataract-refractive convergence:Dual-use femtosecond systems capable of both lenticule extraction and capsulotomy are opening bundled procurement negotiations.
- South Africa diagnostic upgrade cycle:Aberrometer replacement demand in Johannesburg and Cape Town clinics creates attach revenue for laser platform vendors.
Industry Challenges
- Corneal surgeon training scarcity:Small Incision Lenticule Extraction certification programs remain limited across the Gulf, constraining procedure volume expansion.
- SFDA clinical validation timelines:Extended documentation requirements for novel ablation algorithms delay product launch windows.
- Legacy microkeratome stranded assets:Mechanical system depreciation schedules conflict with accelerated femtosecond replacement cycles in premium-tier facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Refractive Surgery Devices Market |
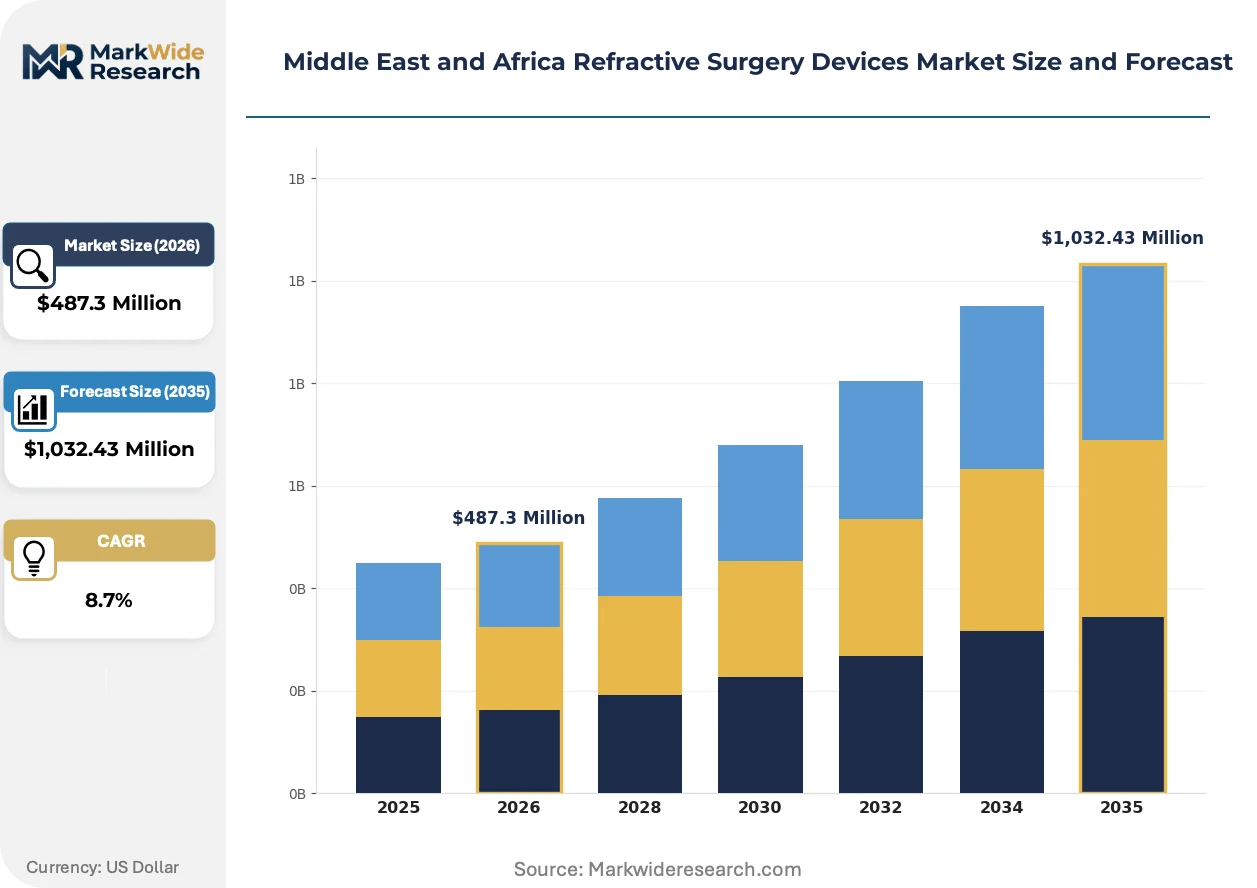
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: LASIK Systems, Laser Flap Devices, Photokeratectomy Systems, Keratome Devices End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Eye Care Centers Technique: Laser-Assisted In Situ Keratomileusis, Photorefractive Keratectomy, Small Incision Lenticule Extraction, Refractive Lens Exchange Application: Myopia Correction, Hyperopia Treatment, Astigmatism Correction, Presbyopia Management |
| Companies Covered | SCHWIND eye-tech-solutions, NIDEK, Bausch + Lomb, Topcon Corporation, Alcon, STAAR Surgical, Ziemer Ophthalmic Systems, Hoya Surgical Optics, Johnson & Johnson Services, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Refractive Surgery Devices Market Shifts & Advancements
Wavefront-optimized ablation profiles and artificial intelligence-guided treatment planning are compressing surgical variability while elevating patient-reported outcomes across Middle East and Africa ophthalmology networks.
Topography-guided excimer laser systems are decentralizing refractive surgery delivery from metropolitan hospital hubs to secondary city clinics. Regional ophthalmology groups in Saudi Arabia's Eastern Province and South Africa's KwaZulu-Natal are acquiring compact platforms for same-day procedure capacity. This diffusion is compressing patient travel burdens while fragmenting case volume concentration previously held by Dubai and Johannesburg flagship centers.
South Africa's national pharmaceutical regulator and Saudi Arabia's SFDA are tightening post-market surveillance requirements for excimer laser platforms, mandating real-world outcome registries. Manufacturers must now submit annual safety reports and device performance metrics. High-volume chains in the UAE and private hospital networks in Riyadh are responding by investing in integrated electronic medical record systems capable of automated adverse event documentation.
Service contract unbundling is altering procurement negotiations across Gulf private hospital groups. Buyers are separating equipment acquisition from maintenance agreements, engaging third-party biomedical engineering firms for laser calibration and optics servicing. This pattern is most visible in Dubai's healthcare free zones, where independent service organizations compete directly with manufacturer-affiliated technical teams for multi-year maintenance commitments.
Middle East and Africa Refractive Surgery Devices Market Segmentation
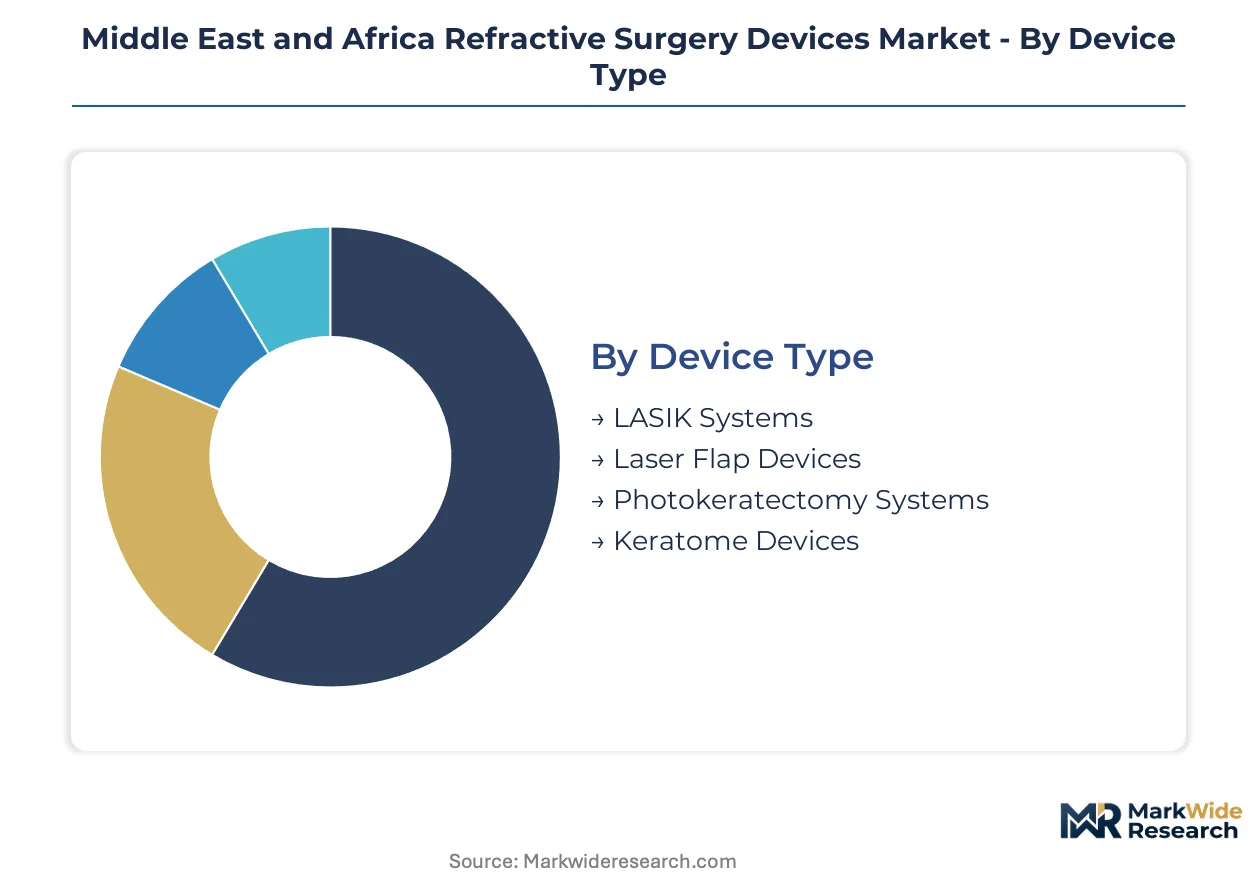
Refractive surgery device procurement in the Middle East and Africa fragments across four critical dimensions: device platform configuration, clinical setting, surgical technique, and targeted ametropia. Each segmentation layer reveals distinct buyer priorities, from capital allocation constraints in private hospital networks to technique certification availability across Gulf ophthalmology training centers.
Device Type:
Purchase decisions in this category pivot on precision tier and flap-creation methodology, with femtosecond platforms commanding premium positioning against legacy mechanical alternatives.
- LASIK Systems:These integrated excimer-laser platforms deliver stromal ablation at 193 nm wavelength with programmable tissue removal algorithms. Demand concentrates in Dubai and Riyadh flagship centers where high patient throughput justifies seven-figure capital deployment and dedicated facility infrastructure.
- Laser Flap Devices:Femtosecond laser platforms create corneal flaps through photodisruption without blade contact, elevating safety profiles and flap predictability. Private hospital chains across the UAE and Saudi Arabia prioritize these systems for medical tourism positioning and premium service-line differentiation.
- Photokeratectomy Systems:Surface ablation platforms using excimer lasers without flap creation serve thinner-cornea patients and secondary city clinics.
- Keratome Devices:Mechanical microkeratome systems face accelerating displacement as femtosecond adoption spreads through Gulf premium-tier facilities.
LASIK Systems lead on scale; Laser Flap Devices lead on momentum.
End User:
Facility type determines procurement volume, reimbursement pathway, and platform sophistication, with private hospital networks driving femtosecond adoption against public-sector capital constraints.
- Ophthalmology Clinics:Specialized refractive centers in Johannesburg and Cape Town concentrate excimer-laser case volume through dedicated surgeon teams and same-day procedure workflows. These facilities prioritize compact platform footprints and rapid patient turnover to maximize capital utilization.
- Hospitals:Private hospital networks across Saudi Arabia and the UAE integrate refractive suites into broader ophthalmology divisions, enabling cross-subsidy from cataract and retinal service lines. SFDA and MOHAP registration requirements shape procurement timelines and vendor selection criteria.
- Ambulatory Surgical Centers:Stand-alone day-procedure facilities in Dubai healthcare free zones exploit streamlined regulatory pathways and bundled pricing models.
- Eye Care Centers:Secondary city diagnostic hubs in Egypt and North Africa represent underdeveloped infrastructure with modular platform potential.
Hospitals lead on scale; Ambulatory Surgical Centers lead on momentum.
Technique:
Surgeon certification availability and patient candidacy criteria determine technique adoption curves, with flapless procedures gaining traction where training infrastructure permits.
- Laser-Assisted In Situ Keratomileusis:The dominant refractive technique combines femtosecond flap creation with excimer stromal ablation, retaining the largest installed base across Middle East and Africa ophthalmology networks. Established training pathways and predictable outcomes sustain its procedural volume leadership.
- Small Incision Lenticule Extraction:This flapless technique extracts a stromal lenticule through a small peripheral incision, eliminating flap-related complications and accelerating visual recovery. Adoption concentrates in high-volume Gulf centers where surgeon certification programs and femtosecond platform availability align.
- Photorefractive Keratectomy:Surface ablation without flap creation serves thin-cornea patients and remains relevant in cost-sensitive settings.
- Refractive Lens Exchange:Intraocular lens-based correction targets presbyopia and high ametropia outside laser-treatable ranges.
Laser-Assisted In Situ Keratomileusis leads on scale; Small Incision Lenticule Extraction leads on momentum.
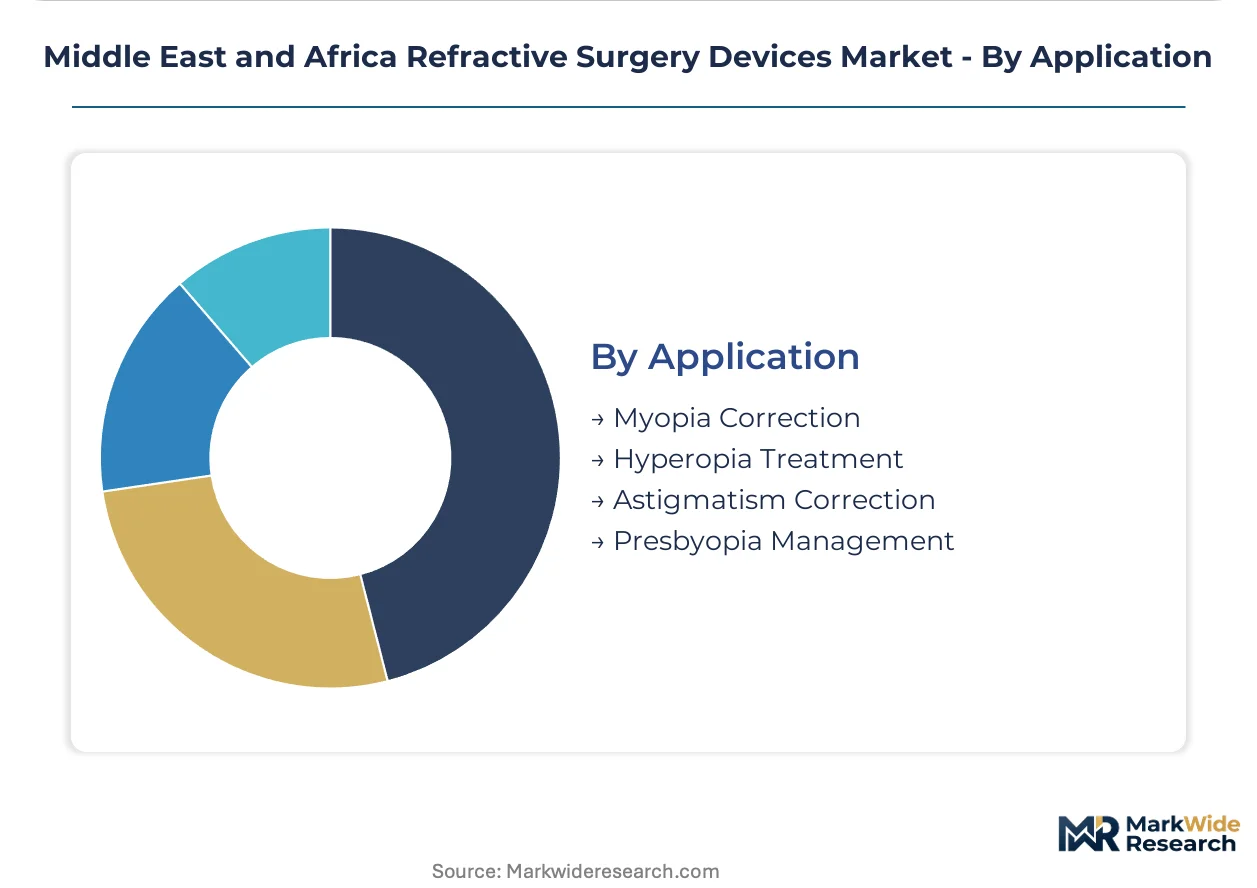
Application:
Patient demographics and ametropia prevalence shape addressable market sizing, with myopia correction dominating procedure volume across the region's young adult populations.
- Myopia Correction:Laser platforms targeting nearsightedness through stromal tissue removal address the highest-prevalence ametropia across Middle East and Africa urban populations. Demand concentrates in Saudi Arabia and South Africa where screen-intensive occupational patterns and youth demographics drive surgical candidacy.
- Astigmatism Correction:Topography-guided ablation workflows correct corneal irregularity through customized tissue removal algorithms. Technical constraints in keratoconus-adjacent cases limit addressable populations, though wavefront-optimized platforms expand treatable ranges in premium-tier Gulf facilities.
- Hyperopia Treatment:Farsightedness correction requires deeper stromal ablation, constraining candidacy in thinner-cornea patients.
- Presbyopia Management:Age-related near-vision decline drives multifocal lens and corneal inlay demand among affluent middle-aged cohorts.
Myopia Correction leads on scale; Astigmatism Correction leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refractive surgery device penetration across the Middle East and Africa traces its commercial lineage to South African and Gulf private hospital investments during the early 2000s, when excimer laser platforms first established regional installed bases before femtosecond systems expanded the addressable procedure market.
United Arab Emirates
Dubai's healthcare free zones and MOHAP regulatory frameworks attract German and Japanese laser manufacturers seeking regional distribution hubs. Medical tourism policies liberalize approval pathways for femtosecond platforms. Riyadh-based hospital chains increasingly source through Dubai logistics clusters for faster procurement cycles.
Saudi Arabia
SFDA device registration standards and clinical validation requirements shape market access timelines for imported excimer systems. Vision 2030 healthcare privatization drives private hospital network expansion into refractive service lines. Riyadh and Jeddah ophthalmology divisions concentrate high-volume LASIK and Small Incision Lenticule Extraction capacity.
South Africa
Johannesburg and Cape Town private clinics anchor regional excimer laser installed bases through dedicated surgeon teams and same-day procedure workflows. The national pharmaceutical regulator enforces post-market surveillance mandates requiring real-world outcome registries. KwaZulu-Natal secondary cities are acquiring compact topography-guided platforms for decentralized delivery.
Egypt
Cairo and Alexandria present underdeveloped private ophthalmology infrastructure with modular excimer platform potential for first-mover positioning. Import dependency and currency volatility constrain procurement timelines for premium femtosecond suites. Alexandria medical device distributors are exploring third-party biomedical engineering partnerships for laser calibration services.
Israel
Advanced ophthalmology research clusters and technology transfer relationships with German laser manufacturers accelerate wavefront-optimized ablation adoption. Regulatory alignment with CE marking standards streamlines device validation for European-imported platforms. Tel Aviv metropolitan clinics concentrate high-complexity keratoconus-adjacent case referrals from neighboring markets.
Middle East and Africa Refractive Surgery Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the precision-tier and service-integration dimensions of the Middle East and Africa refractive surgery devices market. German and Swiss manufacturers anchor the high-precision excimer and femtosecond laser segment, while Japanese and US firms compete on integrated diagnostic-to-treatment workflow platforms. The competitive structure fragments across three strategic archetypes: precision-engineering specialists, integrated ophthalmology platform vendors, and diagnostic device complement providers. Dominant competitive moves include dual-use femtosecond system development for cataract-refractive convergence and third-party service contract unbundling to capture maintenance revenue from manufacturer-affiliated technical teams.
Within the precision-engineering specialist tier, SCHWIND eye-tech-solutions and Ziemer Ophthalmic Systems represent German-origin archetypes focused on excimer and femtosecond laser platforms. Alcon occupies a position exemplifying the integrated ophthalmology platform vendor archetype through its femtosecond segment presence and cataract-refractive bundled procurement positioning. NIDEK sits within the diagnostic-to-treatment workflow specialist category, with its topography-guided ablation systems competing across premium-tier Gulf facilities.
| Leading Market Players |
|---|
| SCHWIND eye-tech-solutions |
| NIDEK |
| Bausch + Lomb |
| Topcon Corporation |
| Alcon |
| STAAR Surgical |
| Ziemer Ophthalmic Systems |
| Hoya Surgical Optics |
| Johnson & Johnson Services |
| Others |
Supply & Pricing Matrix
Optical-grade laser crystal procurement from German and Japanese precision engineering clusters cascades through three pricing tiers downstream, with femtosecond platform manufacturers absorbing upstream cost volatility while private hospital networks in the Gulf negotiate bundled service contracts that compress margin capture at the point of installation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the Middle East and Africa refractive surgery devices market, with femtosecond laser suites commanding premium positioning against mechanical microkeratome alternatives. Price differentiation hinges on CE marking tier and after-sales service bundling, with SFDA-validated platforms extracting brand premiums in Saudi Arabia. Cost compression in the standard tier is intensifying because third-party biomedical engineering firms are unbundling maintenance agreements from equipment acquisition. Public hospital procurement committees exhibit highest price sensitivity, while Dubai's private healthcare free-zone operators prioritize precision specifications over unit economics.
Supply Chain Analysis
Regional distribution centers in Dubai healthcare free zones anchor hub-and-spoke patterns that extend into Riyadh and Johannesburg private hospital networks. Manufacturing concentrates in Germany, Japan, and Switzerland for excimer and femtosecond laser platforms, with optical-grade sapphire substrates and precision motion control systems drawing from specialized component suppliers. Single-source vulnerability in femtosecond oscillator modules exposes buyers to extended lead times. Distribution runs through manufacturer-affiliated technical teams competing against independent service organizations for multi-year maintenance commitments across Gulf private hospital groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa refractive surgery devices market functions as a stable compounder, with medical tourism liberalization in Gulf Cooperation Council states generating predictable procedure volume expansion that underwrites capital deployment cycles.
For Market Incumbents: Acquire third-party biomedical engineering capabilities to capture maintenance revenue streams being unbunded from equipment sales. Defensive positioning requires dual-use femtosecond platform development for cataract-refractive convergence, countering substitute pressure from standalone diagnostic device vendors. SFDA harmonization across Gulf states accelerates certification investment leverage for platforms with established clinical validation dossiers. For New Entrants and Emerging Players: Enter via modular excimer platform deployment in Cairo and Alexandria, where underdeveloped private ophthalmology infrastructure presents first-mover positioning without direct competition from installed German and Japanese incumbents. Egypt's import dependency and currency volatility create attach revenue opportunities for third-party laser calibration partnerships. Target ambulatory surgical centers in Dubai healthcare free zones with streamlined regulatory pathways and bundled pricing models. For Investors and Strategic Acquirers: Consolidation pressure builds where service contract unbundling fragments maintenance revenue pools among independent biomedical engineering firms. The five-to-ten year viability window favors precision-engineering specialists with captive optical component supply and established SFDA registration track records. Watch for surgeon certification program expansion in Small Incision Lenticule Extraction as the inflection signal for procedure volume acceleration beyond metropolitan hospital hubs.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Femtosecond Platform Development | Cataract-refractive convergence opens bundled procurement negotiations with Saudi private hospital networks. |
| Third-Party Service Organization Partnership | Independent biomedical engineering capabilities capture maintenance revenue unbunded from manufacturer sales. |
| SFDA Registration Harmonization Investment | Streamlined Gulf Cooperation Council validation reduces market access timelines for excimer laser platforms. |
| Modular Excimer Platform Deployment | Compact configurations enable secondary city clinic penetration in Egypt and North Africa. |
| Surgeon Certification Program Expansion | Small Incision Lenticule Extraction training infrastructure unlocks flapless procedure volume growth. |
Research Methodology
Bottom-up ophthalmology clinic modeling reconciled against top-down laser platform shipment tracking forms the analytical core of this study. Primary interviews with refractive surgeons, hospital purchasing committee members, biomedical engineering directors, and GPO contracts managers were combined with secondary validation from SFDA registration databases, MOHAP approval filings, hospital procurement records, and customs trade data for optical-grade laser component imports. Triangulation between demand-side procedure volume estimates and supply-side manufacturer delivery schedules ensures consistency across the analytical framework.
Historical trendline analysis of excimer and femtosecond laser installed bases informed projection modeling across device platform configuration, clinical setting, surgical technique, and targeted ametropia dimensions throughout the forecast period. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion patterns. Forecast inputs incorporated medical tourism policy trajectories, SFDA registration timeline assumptions, and surgeon certification program availability curves specific to Small Incision Lenticule Extraction adoption.
The model holds under stable Gulf regulatory harmonization and continued healthcare privatization; deviation in currency volatility or import restriction triggers would shift procurement timelines and platform mix assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gynecological Devices Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
China General Surgical Devices Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Urology Guidewires Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Ocular Implants Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Blood Warmers Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Dosage Unit Sampling Apparatus Market