
 Lumpectomy Market | 2026-2036
Lumpectomy Market Size, Share, and Industry Trends Forecast 2026-2036
Lumpectomy Market Intelligence
The increasing availability of equipment leasing and managed service contracts for high-value surgical systems is reconfiguring the competitive landscape. This allows smaller facilities to access advanced technology without large capital outlays. Hologic leverages its strength in diagnostic and imaging technologies to offer integrated procedural solutions. Johnson & Johnson competes through its extensive portfolio of surgical instruments and broad hospital network access. Medtronic specializes in advanced surgical navigation and energy-based devices for precision procedures.
A lumpectomy is a breast-conserving surgical procedure involving the excision of a malignant tumor along with a margin of surrounding healthy tissue. The primary objective is to achieve negative surgical margins, confirmed via pathological analysis, to minimize recurrence risk. Medical imaging devices and electric surgical instruments constitute the core product segments, essential for procedural accuracy and efficacy. While hospitals remain the largest end-user segment, ambulatory surgery centers show significant procedural volume increases due to cost efficiencies.
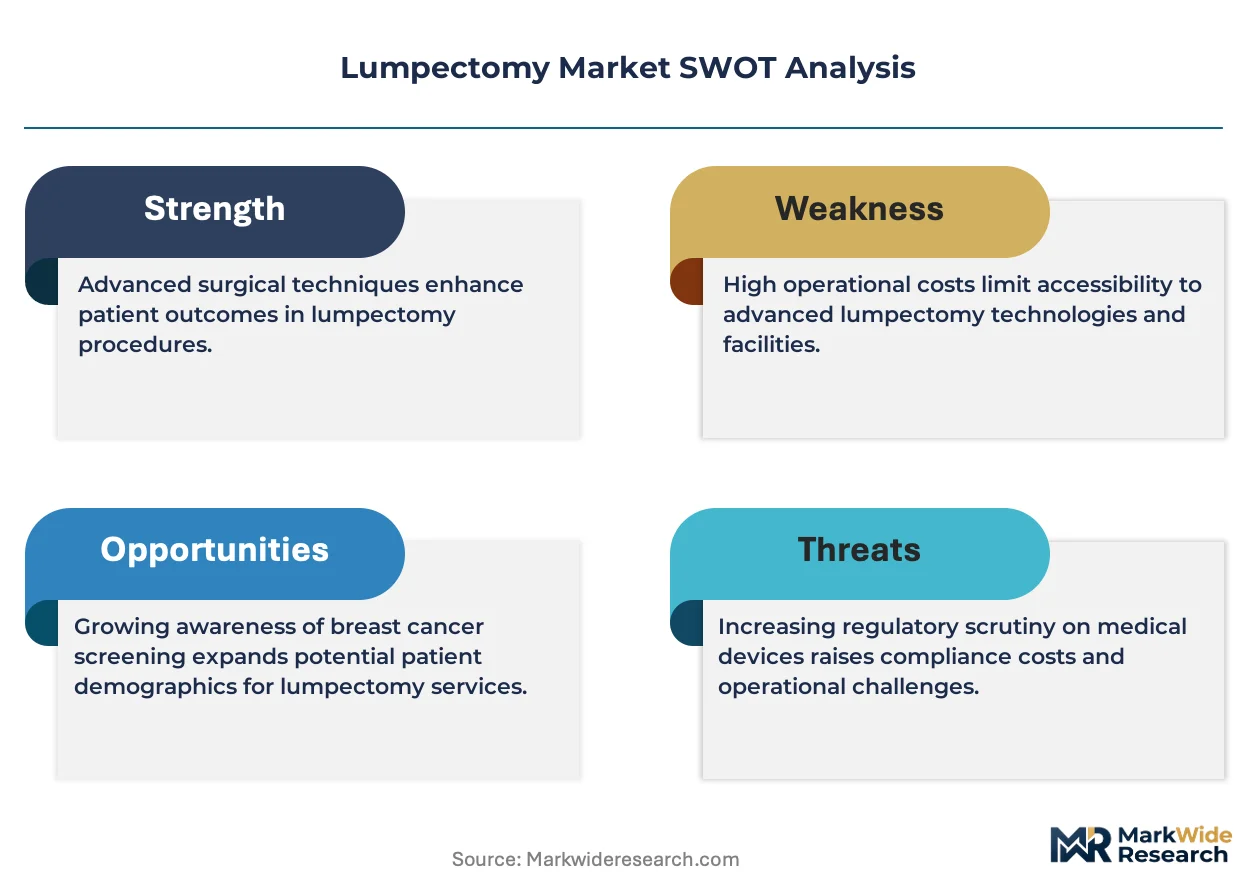
Regulatory oversight from bodies like the U.S. FDA, the European Union under its MDR, and China's NMPA dictates market entry pathways for new surgical technologies. These agencies enforce stringent requirements for clinical evidence, device safety, and manufacturing quality control. Stakeholders must navigate the trade-off between investing in high-cost robotic-assisted and 3D imaging technologies and the pressure for cost containment within healthcare systems.
Market Dynamics
The proliferation of managed service contracts and equipment leasing models is democratizing access to high-value surgical systems. This shift fundamentally alters the capital expenditure calculus for ambulatory surgery centers and smaller hospitals, reconfiguring the competitive landscape for device manufacturers.
Growth Catalysts
- Intraoperative Imaging:Advancements in 3D intraoperative imaging and specimen radiography provide real-time margin assessment. This technological progress enhances surgical accuracy, directly addressing the clinical goal of reducing re-excision rates and improving patient outcomes in a single procedure.
- National Screening Programs:Government-funded breast cancer screening initiatives in countries like Germany and the UK increase early-stage diagnosis rates. This leads to a higher volume of patients eligible for breast-conserving surgeries such as lumpectomy, supporting procedural demand.
- Ambulatory Surgery Centers:The procedural shift towards ambulatory surgery centers for less complex surgeries is a significant catalyst. These facilities favor the cost-efficiency and faster patient turnover associated with lumpectomies, driving equipment and instrument adoption in this end-user segment.
Market Restraints
- High Capital Investment:The significant capital outlay required for robotic-assisted surgical platforms and advanced 3D imaging technologies remains a primary barrier. This cost can be prohibitive for smaller hospitals or facilities in healthcare systems with constrained budgets.
- Stringent Regulatory Hurdles:The European Union's Medical Device Regulation (MDR) imposes extensive clinical evidence and post-market surveillance requirements. This creates extended and costly pathways to market for new surgical technologies, potentially delaying innovation.
- Re-excision Rates:The clinical challenge of consistently achieving negative surgical margins in the initial operation persists. High re-excision rates not only impact patient well-being but also increase overall costs for healthcare systems, acting as a restraint on procedural efficiency.
Strategic Opportunities
- Emerging Market Expansion:Expanding into healthcare systems in Brazil and India, where breast cancer incidence is rising and surgical infrastructure is modernizing, presents a significant growth avenue. Tailoring products for these cost-sensitive environments is critical for market entry.
- AI-Powered Margin Analysis:Integrating artificial intelligence with real-time pathological analysis tools offers a pathway to reduce re-excision rates. AI algorithms can provide immediate margin feedback during surgery, enhancing surgeon confidence and procedural success.
- Integrated Procedural Kits:Developing pre-packaged, single-use kits containing all necessary instruments and consumables for a lumpectomy can streamline hospital procurement and inventory management. This opportunity is especially relevant for high-volume ambulatory surgery centers seeking operational efficiencies.
Industry Challenges
- Specialized Skill Shortages:A deficit of surgeons and technicians proficient in operating advanced 3D imaging and energy-based dissection devices creates an implementation bottleneck. This skills gap can limit the adoption and effective use of new technologies in many hospitals.
- System Interoperability:Integrating new surgical navigation systems with existing hospital IT infrastructure, such as electronic health records and legacy imaging archives, presents significant technical and data security challenges for healthcare providers worldwide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lumpectomy Market |
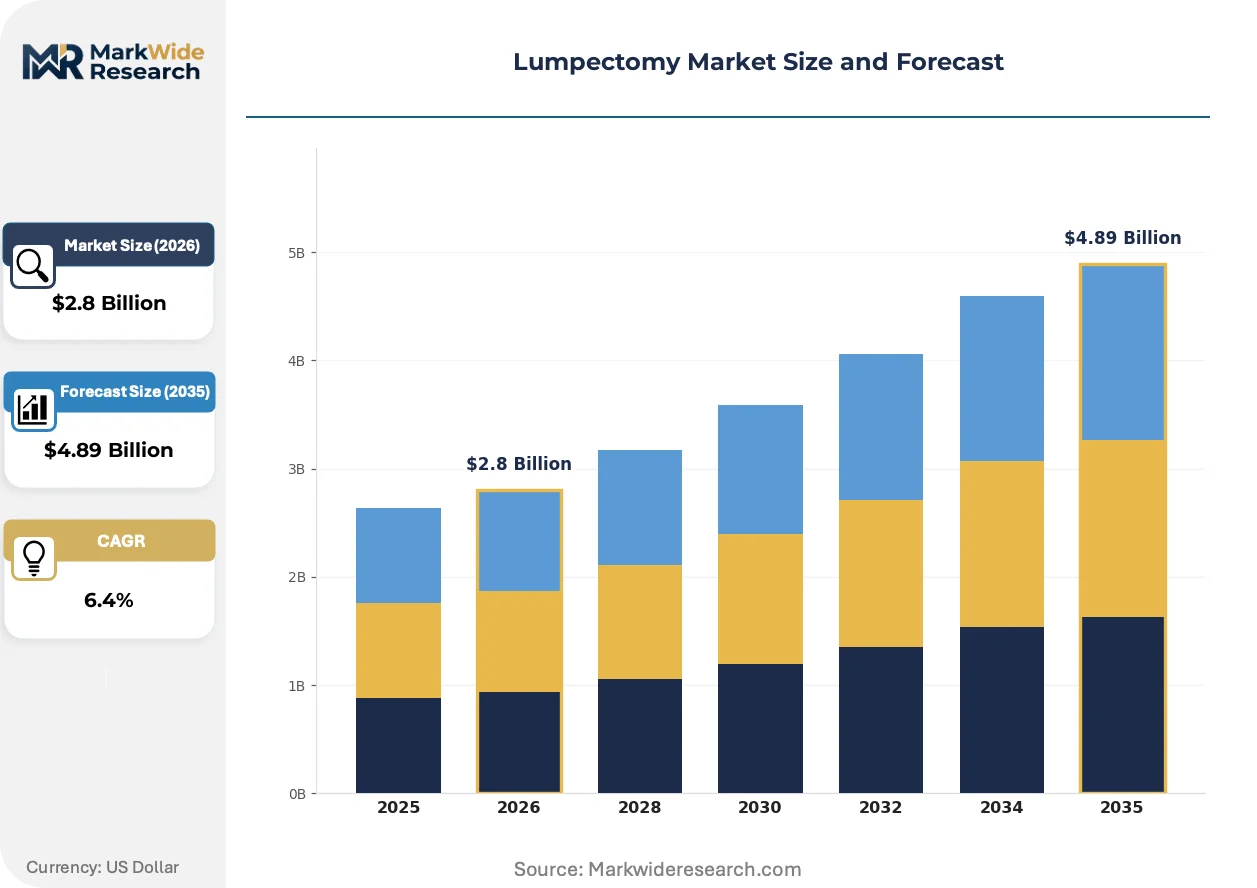
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Surgical Instruments, Manual Surgical Instruments, Medical Imaging Devices, Biopsy Devices End User: Hospitals, Ambulatory Surgery Centers, Oncology Clinics, Research Institutions Technology: Laser Surgery, Ultrasound-guided Surgery, 3D Imaging Technology, Robotic-assisted Surgery Application: Breast Cancer Treatment, Tumor Diagnosis, Reconstruction Procedures, Clinical Research |
| Companies Covered | Medtronic, Hologic, Stryker, Johnson & Johnson, Boston Scientific, Becton Dickinson and Company, Merit Medical Systems, B. Braun Melsungen AG, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lumpectomy Market Strategic Shifts & Innovations
Surgical precision and diagnostic certainty are converging, driven by digital technologies that provide real-time, data-driven feedback within the operating room. This shift is redefining procedural standards and influencing device design priorities across the industry, moving the focus toward immediate outcome validation.
Intraoperative magnetic resonance imaging (iMRI) and 3D specimen radiography provide immediate, high-resolution views of excised tissue and surgical margins. Academic medical centers and specialized cancer treatment facilities are leading adoption, integrating these tools directly into surgical workflows. This real-time feedback is collapsing the time between tissue excision and pathological confirmation, reducing the need for secondary re-excision procedures.
The U.S. FDA's framework for Software as a Medical Device (SaMD) is establishing new validation pathways for AI-driven diagnostic and surgical planning algorithms. This regulatory clarity encourages investment in software that assists surgeons in identifying tumor boundaries and predicting margin status from preoperative imaging. Medical imaging software developers are most affected, now navigating specific cybersecurity and clinical validation requirements to gain market access.
A preference for integrated procedural solutions over standalone capital equipment is becoming more pronounced among hospital procurement departments. This trend favors vendors that can bundle imaging systems, surgical instruments, and consumables into a single platform, displacing single-product suppliers. This purchasing behavior is particularly evident in large hospital networks in the United States and Germany, where operational efficiency is a key priority.
Lumpectomy Market Segmentation
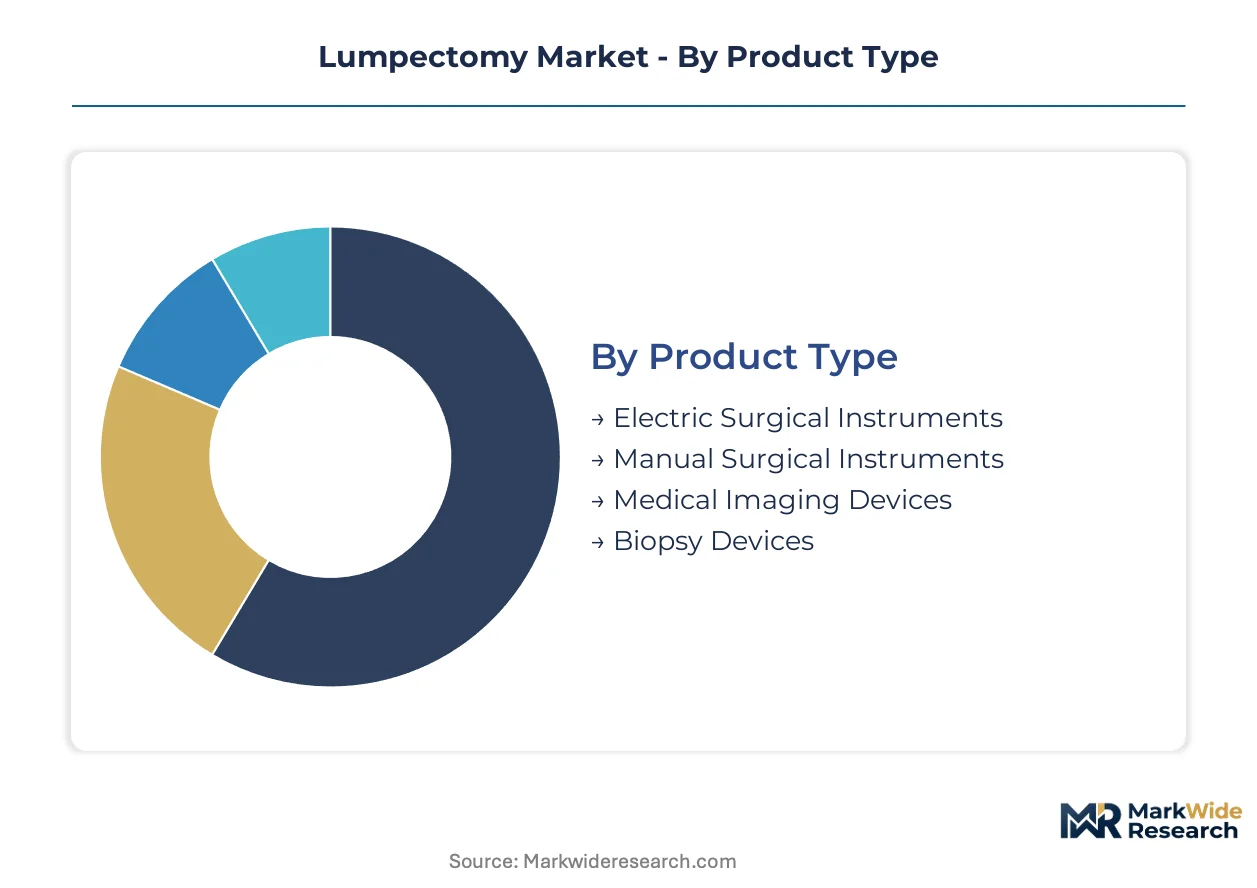
The Lumpectomy Market segmentation provides a granular view of the procedural landscape and technological adoption. Understanding these distinct categories helps stakeholders identify specific growth pockets and operational efficiencies. This detailed breakdown informs strategic investment decisions across the healthcare value chain.
Product Type:
The product type segment exhibits a blend of mature and emerging solutions critical for lumpectomy procedures.
- Medical Imaging Devices:These advanced systems provide real-time visualization and diagnostic certainty during surgical planning and intraoperative margin assessment. Demand concentrates in specialized cancer treatment facilities and large hospital networks across Germany and the United States, driven by their ability to reduce re-excision rates.
- Electric Surgical Instruments:These devices facilitate precise tissue dissection and coagulation, enhancing surgical efficiency and minimizing patient trauma. Hospitals and ambulatory surgery centers globally drive demand for these instruments, seeking improved procedural outcomes and faster patient recovery.
- Manual Surgical Instruments:This category encompasses traditional scalpels, retractors, and clamps, forming the foundational toolkit for most surgical interventions.
- Biopsy Devices:Instruments designed for obtaining tissue samples for pathological analysis play a critical role in initial diagnosis and margin assessment.
Manual Surgical Instruments retain volume leadership; Medical Imaging Devices hold the steepest expansion curve.
End User:
The end-user segmentation reflects varying operational scales and patient volumes across different healthcare settings.
- Hospitals:These institutions represent the largest end-user segment, performing a high volume of complex lumpectomy procedures and housing advanced surgical and diagnostic equipment. Demand for integrated procedural solutions in hospitals across the European Union and India is substantial due to comprehensive patient care requirements.
- Ambulatory Surgery Centers:These facilities focus on cost-efficient, less complex surgical interventions, demonstrating significant procedural volume increases. Their preference for streamlined workflows and bundled kits drives equipment adoption in the United States and the United Kingdom.
- Oncology Clinics:Specialized clinics provide focused cancer care, often handling pre-operative diagnostics and post-operative follow-up for lumpectomy patients.
- Research Institutions:These entities utilize lumpectomy-related technologies for clinical trials, anatomical studies, and the development of new surgical techniques.
Hospitals remain the primary revenue generator; Ambulatory Surgery Centers are expanding quickly.
Technology:
Technological advancements within lumpectomy procedures focus on enhancing precision and diagnostic accuracy during tumor excision.
- 3D Imaging Technology:This technology provides volumetric visualization of breast tissue and tumors, aiding in precise surgical planning and real-time margin assessment. Academic medical centers in Japan and Canada are integrating 3D imaging into their surgical suites to improve patient outcomes.
- Robotic-assisted Surgery:These platforms offer enhanced dexterity, visualization, and precision for minimally invasive lumpectomy procedures. High capital investment limits their adoption primarily to large university hospitals and specialized cancer centers in the United States and Germany.
- Laser Surgery:This technique uses focused light to precisely cut or ablate tissue, offering potential benefits in reducing bleeding and improving cosmetic outcomes.
- Ultrasound-guided Surgery:This widely adopted method uses real-time ultrasound imaging to guide surgeons during tumor localization and excision.
Ultrasound-guided Surgery maintains broad applicability; 3D Imaging Technology is gaining market share rapidly.
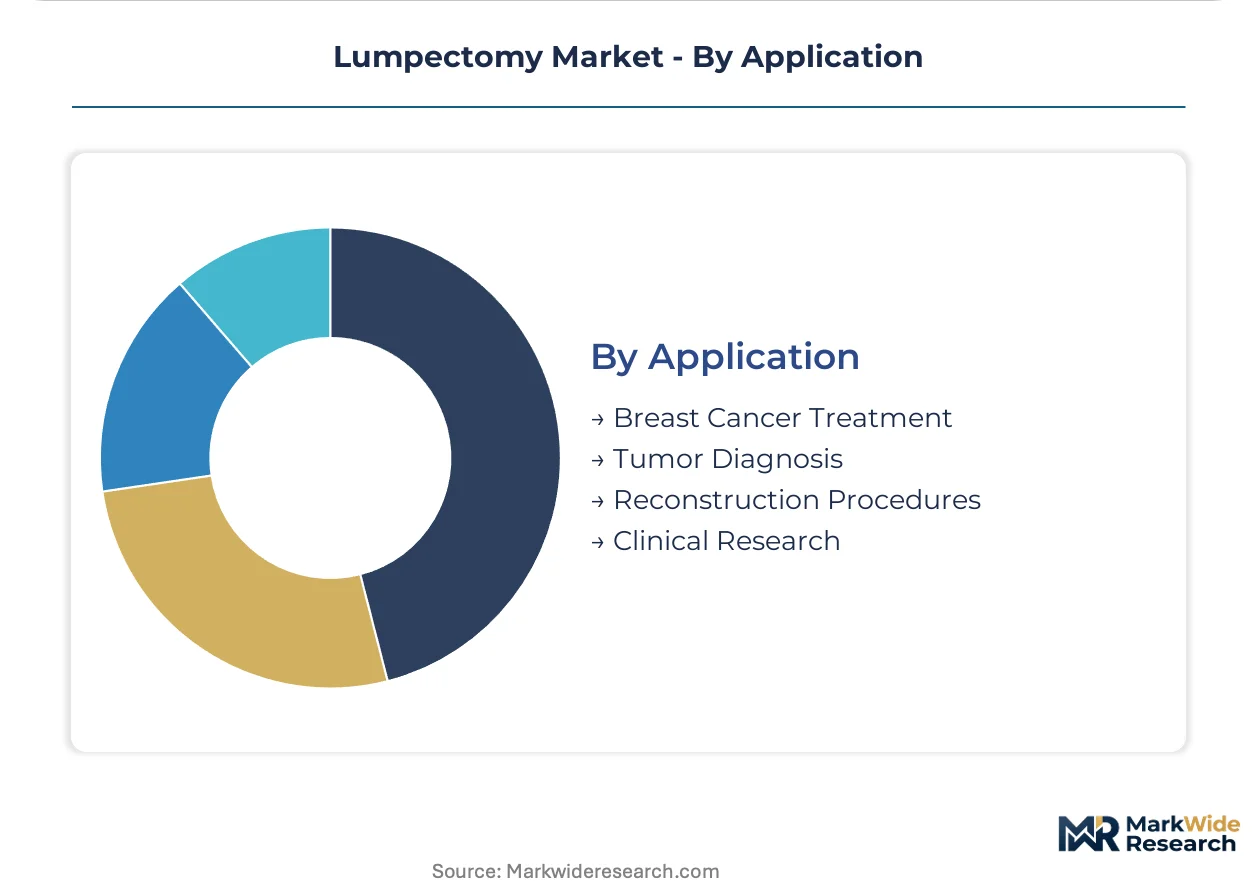
Application:
The application segments reflect the primary clinical objectives driving lumpectomy procedures across healthcare settings.
- Breast Cancer Treatment:This segment represents the primary application, focusing on the surgical removal of malignant tumors while preserving breast tissue. Demand for effective treatment solutions is consistently high across all developed and emerging healthcare markets.
- Tumor Diagnosis:Lumpectomy procedures are crucial for obtaining definitive pathological diagnoses of suspicious breast lesions. The need for accurate diagnosis drives consistent demand in oncology centers globally.
- Reconstruction Procedures:This application involves subsequent surgeries to restore breast aesthetics after tissue removal, often performed in conjunction with lumpectomy.
- Clinical Research:This segment includes the use of lumpectomy techniques and associated technologies for investigational studies and the development of new treatment protocols.
Breast Cancer Treatment represents the core demand; Tumor Diagnosis shows consistent growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry characterizes the Lumpectomy Market, with established healthcare systems in Germany dictating premium values for advanced technologies, while emerging markets like India prioritize cost-efficiency in technology adoption.
United States
Demand for lumpectomy procedures in the United States is driven by the rapid adoption of advanced 3D imaging and robotic-assisted surgical platforms. The U.S. FDA maintains stringent regulatory pathways for new medical devices, ensuring high safety and efficacy standards. Major medical technology clusters in Boston and California lead in developing and integrating these innovative surgical solutions.
Germany
Germany exhibits strong demand for lumpectomy devices, supported by its sophisticated healthcare infrastructure and national breast cancer screening programs. European Union's Medical Device Regulation (MDR) significantly influences device design and market entry protocols for manufacturers. Cities like Munich and Berlin serve as hubs for advanced medical technology, driving innovation in surgical tools.
India
India's Lumpectomy Market is expanding due to rising breast cancer incidence and ongoing modernization of its surgical infrastructure. The CDSCO regulates medical device approvals, balancing patient access with safety standards for imported and domestically produced equipment. Bangalore and Hyderabad are emerging as key centers for medical device manufacturing and distribution, catering to cost-sensitive demands.
Brazil
Brazil presents a significant growth avenue, driven by increasing breast cancer prevalence and the country's efforts to improve healthcare access. ANVISA oversees the regulatory framework for medical devices, impacting market entry strategies for international and local players. The São Paulo region acts as a primary healthcare hub, facilitating the adoption of new surgical techniques and equipment.
Japan
Japan's market is characterized by academic medical centers integrating advanced 3D imaging technology to enhance surgical precision. The PMDA ensures rigorous evaluation of medical devices, emphasizing clinical evidence and patient safety. Tokyo's medical research institutions and university hospitals adopt cutting-edge lumpectomy procedures.
Lumpectomy Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical elements for surgical systems. The market structure exhibits a tiered consolidation, with a few large players offering integrated procedural solutions alongside numerous specialized instrument providers. Strategic archetypes include comprehensive solution providers, specialized technology innovators, and broad-portfolio instrument manufacturers. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants.
Integrated solution providers such as Medtronic, with its focus on advanced surgical navigation and energy-based devices, exemplify the precision technology segment. Hologic occupies a position among companies leveraging diagnostic and imaging strengths to offer integrated procedural solutions for lumpectomy. Johnson & Johnson represents a broad-portfolio player, anchoring its competitive stance through an extensive range of surgical instruments and wide hospital network access.
| Leading Market Players |
|---|
| Medtronic |
| Hologic |
| Stryker |
| Johnson & Johnson |
| Boston Scientific |
| Becton Dickinson and Company |
| Merit Medical Systems |
| B. Braun Melsungen AG |
| Smith & Nephew |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialized component manufacturing for advanced imaging systems drives both supplier behavior and premium pricing for high-precision lumpectomy devices. This dynamic encourages vertical integration among larger device manufacturers seeking to control critical input costs and ensure supply stability.
Pricing Analysis
Configured-to-order pricing for robotic-assisted platforms and 3D imaging systems contrasts with standard pricing for manual surgical instruments. The dominant pricing model is a hybrid of value-based contracts for integrated solutions and per-unit transactional pricing for consumables. Price differentiation stems from advanced feature sets and comprehensive after-sales service. Pricing softness reflects cost containment pressures from ambulatory surgery centers and public healthcare systems. Smaller hospitals and ambulatory surgery centers exhibit the highest price sensitivity.
Supply Chain Analysis
Export-control regimes on advanced microelectronics and specialized optics limit the free flow of critical components for medical imaging devices. Geographic supply concentration for these high-value components rests in countries like the United States, Japan, and Germany. Raw material dependencies include specialized medical-grade polymers and high-purity metals for instrument manufacturing. Regulatory restrictions, particularly the European Union's MDR, pose a significant structural risk, extending market entry timelines. Distribution predominantly runs through direct sales teams for large capital equipment and specialized distributors for instruments and consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lumpectomy Market is experiencing a buyer-power shift, driven by the consolidation of purchasing decisions within large hospital networks and the increasing influence of group purchasing organizations.
For Market Incumbents:
Harden proprietary technology stacks by investing heavily in AI-powered margin analysis and 3D intraoperative imaging R&D. This counters the threat of specialized software entrants and margin pressure from cost-conscious buyers. Expand global channel control, especially in emerging markets like India, to secure new patient populations. Focus on comprehensive regulatory compliance expertise, particularly navigating the European Union's MDR, as a strategic lever against less agile competitors.
For New Entrants and Emerging Players:
Establish a beachhead in the ambulatory surgery center segment by offering integrated procedural kits and flexible equipment leasing models. This addresses the significant procedural volume increases in these cost-efficient facilities. Target AI-powered diagnostic software for real-time margin assessment as a white-space opportunity, leveraging the U.S. FDA's SaMD framework. A direct-to-hospital sales model focused on operational efficiency and faster patient turnover provides a strong go-to-market angle.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting in an upward direction across advanced imaging and robotic-assisted surgery sub-segments, signaling long-term growth potential. Target specialized AI software developers focused on real-time pathological analysis or manufacturers of advanced 3D intraoperative imaging components. The increasing stringency of regulatory oversight, such as the European Union's MDR, represents a key inflection indicator to watch, favoring companies with robust compliance records and established market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Integrated Margin Analysis Tools | Enhances surgical accuracy for surgeons, reducing re-excision rates for patients. |
| Expand Managed Service and Leasing Contracts | Democratizes access to advanced technology for smaller facilities and ambulatory surgery centers. |
| Secure European Union MDR Compliance | Ensures market access and strengthens competitive positioning for medical device manufacturers in Germany. |
| Form Strategic Partnerships with Hospital Networks | Streamlines procurement processes and accelerates adoption of integrated procedural solutions in the United States. |
| Tailor Products for Emerging Market Needs | Captures growth in Brazil and India, where breast cancer incidence is rising and surgical infrastructure is modernizing. |
Research Approach
Desk research of industry reports, regulatory filings, and academic publications preceded structured interviews with clinicians, hospital purchasing managers, and medical device manufacturers. This primary and secondary data combination enabled a comprehensive understanding of market dynamics and technology adoption. Top-down and bottom-up triangulation validated market sizing and growth projections across various segments.
Assumptions regarding consistent regulatory frameworks and stable healthcare spending policies were held fixed across the analysis window. The analytical framework modeled market evolution across product type, end user, technology, application, and regional regulatory environments. Compound Annual Growth Rates were derived from historical data trends and projected adoption rates of advanced surgical technologies. Key forecast inputs included breast cancer incidence rates and the expansion of national screening programs.
Sensitivities concentrate around unforeseen regulatory shifts or significant technological breakthroughs that could alter current market trajectories. Forecasts reflect these underlying assumptions at the time of analysis. Material shifts in global healthcare expenditure or major changes to medical device approval pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Middle East and Africa General Surgical Devices Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Global Surgical Case Carts Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market