
 Surgical Visualization Market | 2026-2036
Surgical Visualization Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Visualization Market Outlook
A shift from outsourced camera sensor procurement to in-house CMOS design is repositioning supply economics across the Surgical Visualization Market. Karl Storz leverages its Tuttlingen manufacturing base to sustain end-to-end endoscope production. Olympus Corporation anchors its competitive stance through dominant positions in flexible gastrointestinal visualization systems. Siemens Healthineers competes by integrating advanced imaging modalities with surgical navigation platforms.
Surgical visualization encompasses camera systems, display monitors, and image processing hardware that capture, transmit, and enhance intraoperative visual fields with resolutions reaching 4K and beyond, serving primarily to reduce surgical invasiveness while improving anatomical precision. Endoscopy Systems command the largest product category share due to recurring instrument replacement cycles and expanding procedural indications. Visualization Software represents the fastest-expanding segment as hospitals integrate AI-assisted image analysis and surgical planning tools. High Definition technology remains the installed-base standard, though 3D Imaging and Augmented Reality configurations are capturing premium replacement demand in neurosurgery and cardiothoracic applications.
FDA 510(k) clearance pathways shape product development timelines and commercialization sequencing for US market entrants, while CE marking under the EU Medical Device Regulation governs access to European surgical suites. The country's national pharmaceutical regulator in Japan enforces PMDA quality standards that filter which visualization platforms enter its high-value hospital procurement system. Stakeholders must monitor how FDA digital health guidance and EU AI Act risk classifications will reshape software-enabled visualization product categories.
Market Dynamics
CMOS sensor design is migrating from merchant supply to captive semiconductor fabrication, compressing cost structures and tightening quality control across endoscope manufacturing networks.
Growth Catalysts
- Minimally invasive procedure volume:Laparoscopic and arthroscopic interventions are displacing open surgery across tertiary hospitals, requiring upgraded visualization infrastructure with 4K resolution standards.
- EU Medical Device Regulation compliance mandates:CE marking under MDR is accelerating hospital replacement of legacy visualization systems that lack updated clinical evidence packages.
- AI-assisted surgical planning:Machine learning algorithms for anatomical segmentation are integrating with preoperative imaging, pulling demand for compatible display and processing hardware into neurosurgery suites.
Market Restraints
- CMOS wafer supply concentration:Taiwan and South Korea fabrication facilities control advanced image sensor output, exposing manufacturers to geopolitical disruption and allocation constraints.
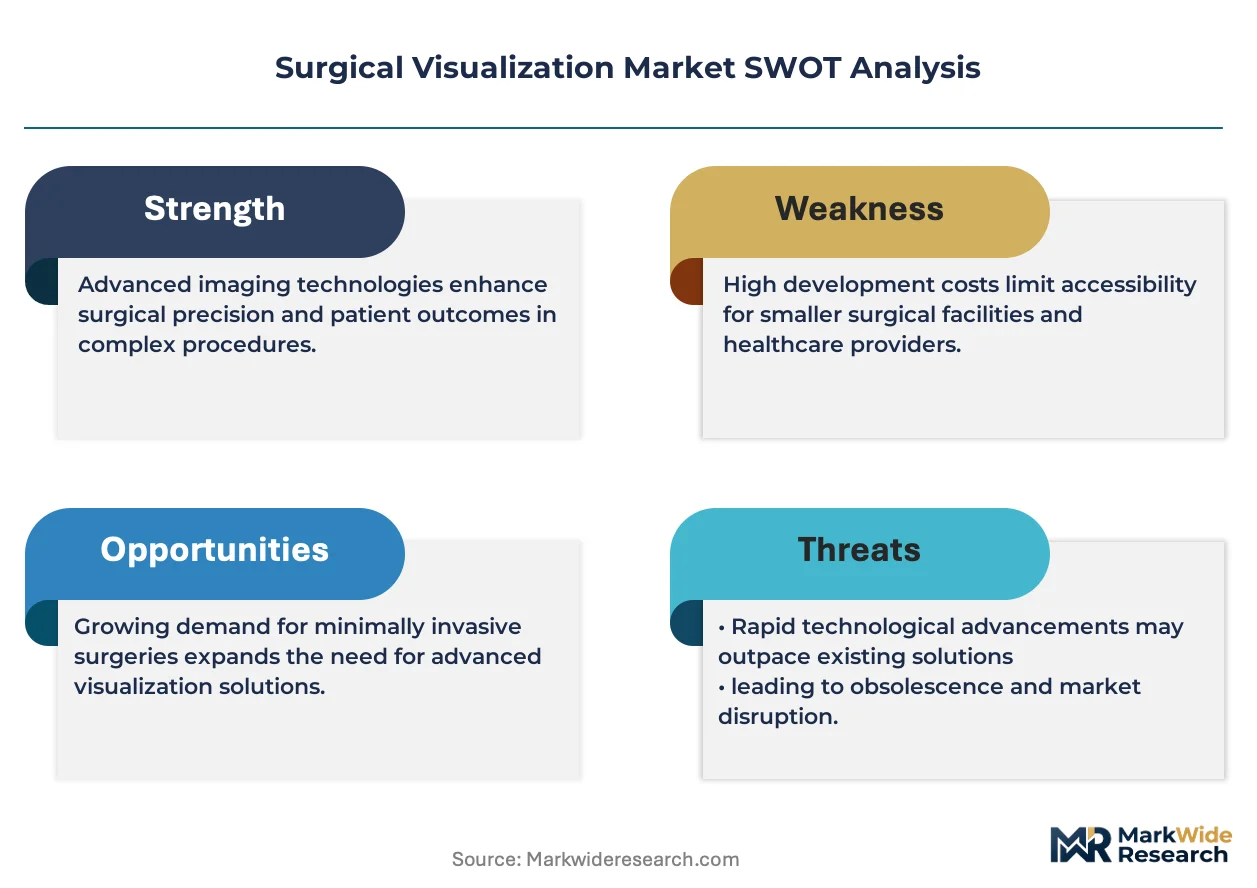
- FDA 510(k) pathway complexity:Substantial equivalence determinations for iterative hardware updates are extending commercialization timelines by twelve to eighteen months for US entrants.
- Capital equipment replacement cycles:Hospital budget compression is stretching endoscope system refresh intervals from five to seven years, dampening near-term revenue velocity for manufacturers.
Strategic Opportunities
- Ambulatory surgical center penetration:Freestanding outpatient facilities in the United States are installing compact visualization suites for cataract and orthopedic procedures, creating a channel distinct from integrated health systems.
- Augmented reality overlay integration:Heads-up displays projecting patient-specific anatomical data are converging with robotic surgical platforms, opening premium positioning in cardiac and spinal applications.
- Japan PMDA fast-track pathways:Priority review designations for breakthrough device designations are compressing regulatory timelines for AI-enabled visualization software seeking entry to high-value hospital procurement.
Industry Challenges
- Optical engineer talent scarcity:Specialized expertise in miniature lens design for flexible endoscopes is concentrating at Tuttlingen and Tokyo clusters, constraining expansion capacity for second-tier manufacturers.
- Legacy system integration complexity:New visualization hardware must interface with installed surgical navigation and robotic platforms through proprietary data protocols, extending deployment timelines and service costs.
- Software validation burden:FDA digital health guidance requiring clinical evidence for AI-enabled image enhancement is forcing manufacturers to fund prospective studies before commercial release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Visualization Market |
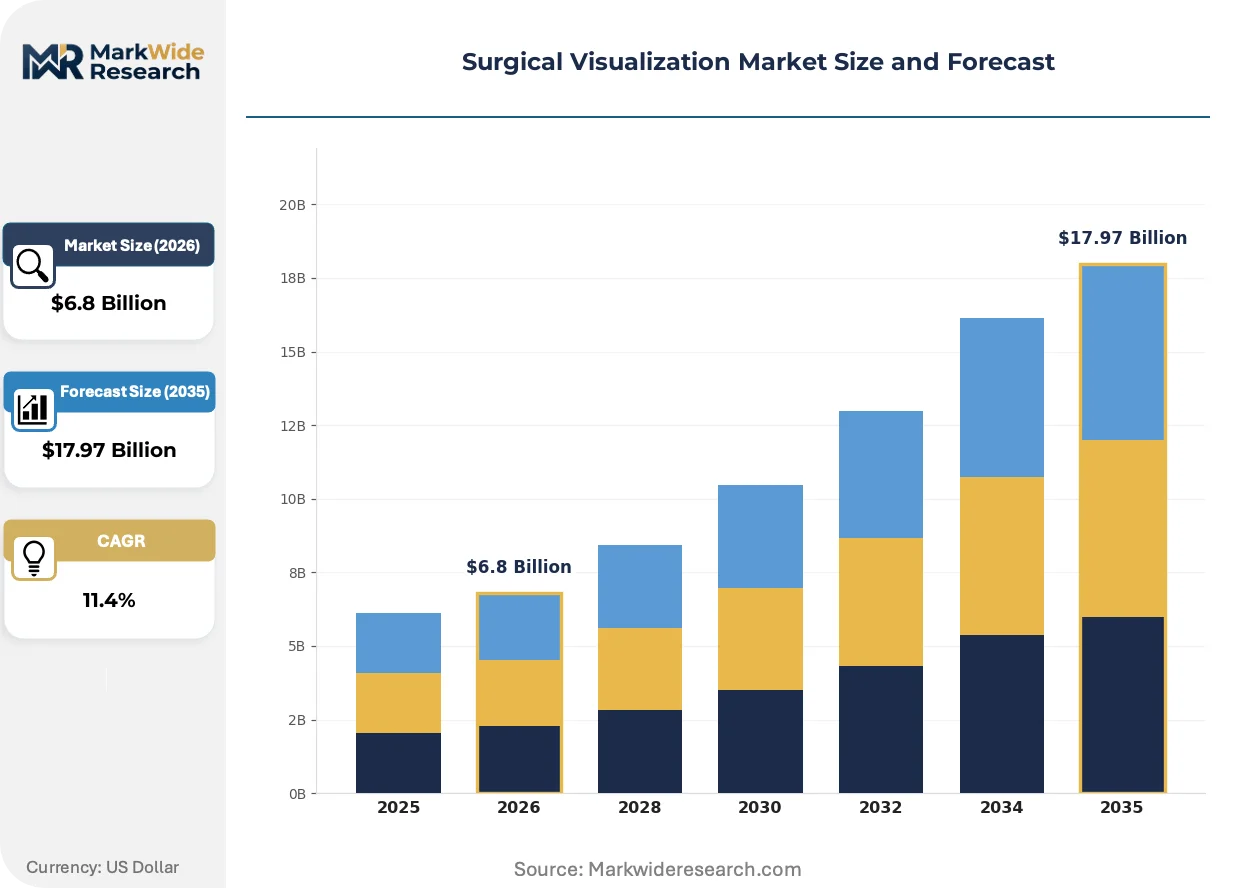
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopy Systems, Surgical Cameras, Visualization Software, Projection Systems Technology: 3D Imaging, Augmented Reality, High Definition, Wireless Connectivity End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutes Application: General Surgery, Neurosurgery, Orthopedic Surgery, Cardiothoracic Surgery |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Stryker Corporation, Olympus Corporation, Medtronic, Karl Storz, Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Visualization Market Strategic Shifts
Computational imaging and real-time data fusion are compressing the gap between raw sensor capture and clinically actionable visualization, restructuring how surgical teams interact with anatomical information.
4K and 8K resolution standards are expanding into standard-of-care expectations for minimally invasive procedures across German and Japanese university hospitals. Tertiary medical centers in North America are completing fleet upgrades to ultra-high-definition camera heads and matching display arrays. This resolution migration is expanding into mid-tier community hospitals that previously standardized on 1080p systems, compressing the addressable market for legacy HD equipment.
EU AI Act risk classifications are reshaping software development roadmaps for visualization platforms with embedded machine learning. High-risk categorization for real-time diagnostic assistance is forcing manufacturers to implement post-market surveillance systems and algorithmic transparency documentation. Visualization software with predictive tissue classification features is most affected, with developers in Ireland and the Netherlands restructuring quality management systems to satisfy conformity assessment body requirements.
Hospital procurement departments are consolidating vendor relationships through integrated visualization and surgical platform contracts. Single-source agreements spanning camera systems, insufflators, and energy devices are displacing point-solution purchasing in integrated delivery networks. This behavior is most visible in United States health systems pursuing standardization across multi-hospital footprints to compress service contract complexity and training overhead.
Surgical Visualization Market Segmentation
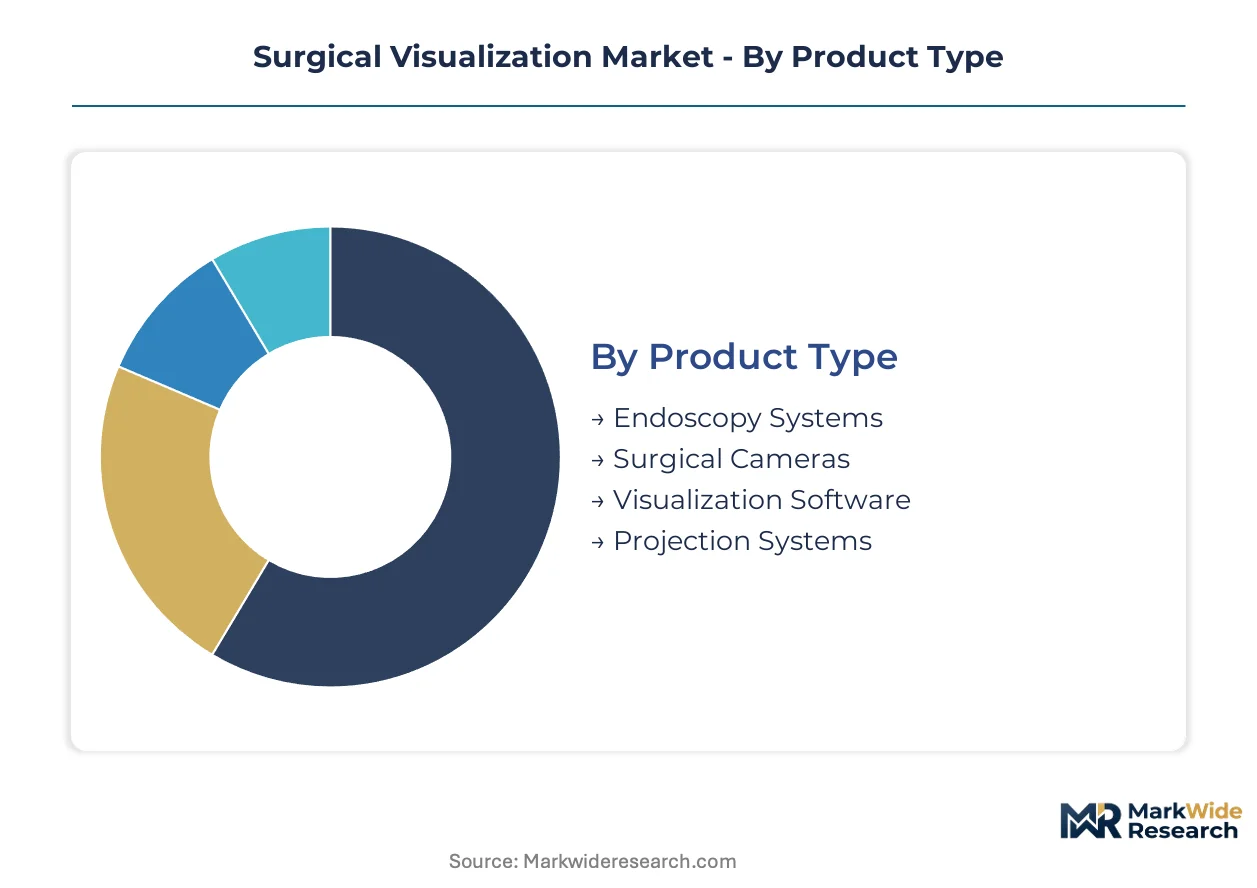
Surgical visualization equipment fragments across hardware, software, and service layers that command distinct procurement cycles and margin profiles. Manufacturers configure product portfolios around specific procedure types and facility infrastructure constraints.
Product Type:
Supply concentration in CMOS sensor fabrication and endoscope lens grinding favors integrated manufacturers with captive production capabilities.
- Endoscopy Systems:Rigid and flexible optical assemblies with integrated light sources and camera heads dominate procedural volume across gastrointestinal and laparoscopic interventions. German university hospitals and Japanese tertiary centers anchor replacement demand as legacy systems age beyond serviceability windows.
- Surgical Cameras:Modular camera heads with 4K and 8K sensor arrays attach to diverse endoscope and microscope platforms. North American integrated delivery networks are standardizing on single-vendor camera fleets to compress training and service contract complexity.
- Visualization Software:Image processing, surgical planning, and AI-assisted anatomical segmentation platforms. FDA digital health guidance and EU AI Act risk classifications are reshaping development roadmaps and clinical evidence requirements.
- Projection Systems:Large-format surgical displays and heads-up visualization arrays for operating theater integration. Compact form factors are penetrating ambulatory surgical center buildouts where space constraints dominate procurement criteria.
Today's leader: Endoscopy Systems. Tomorrow's challenger: Visualization Software.
Technology:
Cost tiers separate established standards from premium configurations that command 40-60% price premiums and extended replacement cycles.
- High Definition:1080p resolution remains the installed-base standard across community hospitals and mid-tier surgical suites. Budget compression is stretching refresh intervals, compressing near-term revenue velocity for manufacturers dependent on replacement volume.
- 3D Imaging:Stereoscopic visualization systems with depth perception enhancement for complex anatomical navigation. Neurosurgery and cardiothoracic departments in German and Japanese university hospitals are capturing premium replacement demand.
- Augmented Reality:Real-time anatomical overlay and patient-specific data projection converging with robotic surgical platforms. FDA breakthrough device designations are accelerating regulatory pathways for integrated AR-navigation systems.
- Wireless Connectivity:Cable-free camera transmission reducing clutter and sterilization burden in operating theaters. Signal latency constraints currently limit penetration to diagnostic and minor procedural applications.
High Definition commands current procurement volume. 3D Imaging and Augmented Reality are climbing the fastest as tertiary centers complete fleet upgrades.
End User:
Customer type determines capital availability, procurement centralization, and service contract structure across facility categories.
- Hospitals:Tertiary medical centers with integrated operating theater infrastructure and dedicated biomedical engineering staff. Consolidated vendor relationships through enterprise-wide visualization platform contracts are displacing point-solution purchasing.
- Ambulatory Surgical Centers:Freestanding outpatient facilities performing cataract, orthopedic, and gastrointestinal procedures. United States certificate-of-need deregulation is accelerating greenfield construction and compact visualization suite installation.
- Clinics:Office-based procedural settings with limited capital budgets and space constraints. Flexible endoscope and portable camera configurations dominate procurement specifications.
- Research Institutes:Preclinical and clinical trial facilities requiring specialized imaging modalities and data capture protocols. Custom software integration and algorithm development partnerships characterize vendor relationships.
Hospitals retain procurement volume leadership. Ambulatory Surgical Centers represent the steepest expansion trajectory as outpatient migration accelerates.
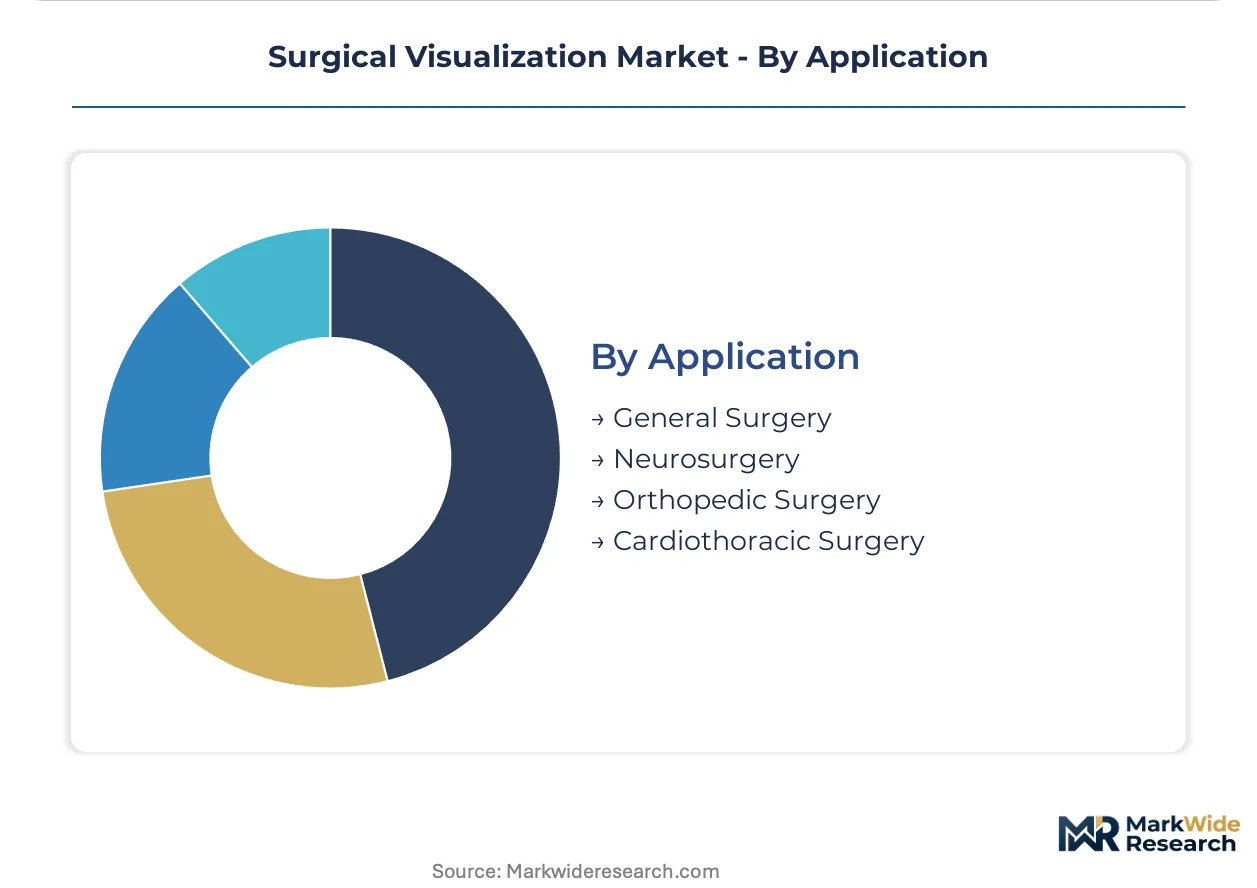
Application:
Procedure complexity and reimbursement levels shape visualization technology requirements and replacement urgency across surgical disciplines.
- General Surgery:Laparoscopic cholecystectomy, hernia repair, and appendectomy procedures with established minimally invasive protocols. High procedural volume drives recurring instrument replacement cycles and standardized 4K camera specifications.
- Neurosurgery:Cranial and spinal interventions demanding submillimeter anatomical precision and extended depth-of-field visualization. 3D imaging and augmented reality integration are capturing premium positioning in university hospital settings.
- Orthopedic Surgery:Arthroscopic joint repair and replacement procedures with rigid endoscope and camera head configurations. Ambulatory surgical center penetration is expanding addressable volume beyond traditional hospital settings.
- Cardiothoracic Surgery:Minimally invasive cardiac valve repair and thoracic interventions requiring specialized visualization and perfusion integration. Regulatory complexity and capital intensity concentrate procurement among integrated health systems.
General Surgery anchors current procedural volume. Neurosurgery commands premium technology adoption as AR-navigation platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tuttlingen anchors the global surgical visualization supply base through Karl Storz's integrated endoscope manufacturing. Demand concentration spans university hospital networks in Germany, Japan, and the United States where tertiary centers drive premium technology adoption.
United States
Integrated delivery networks are consolidating vendor relationships through enterprise-wide visualization platform contracts. FDA 510(k) clearance pathways shape product development timelines for Class II medical devices entering the market. The Greater Boston corridor hosts surgical navigation and robotics clusters where augmented reality integration is accelerating.
Germany
University hospitals in Baden-Württemberg and Bavaria are expanding procurement of 3D imaging suites for minimally invasive procedures. CE marking under the EU Medical Device Regulation governs access to European surgical suites and accelerates compliance investments. The Tuttlingen manufacturing cluster sustains end-to-end endoscope production through captive optical engineering capabilities.
Japan
Tertiary medical centers in Tokyo and Osaka are completing fleet upgrades to ultra-high-definition camera heads and matching display arrays. PMDA quality standards filter which visualization platforms enter the high-value hospital procurement system. The Nagoya corridor concentrates flexible endoscope development expertise alongside precision optics manufacturing.
China
Domestic manufacturers are expanding CMOS sensor design capabilities to reduce dependence on Taiwan and South Korea fabrication facilities. NMPA regulatory pathways are lengthening for imported visualization hardware as local substitution policies advance. The Yangtze River Delta hosts emerging endoscope assembly clusters serving mid-tier hospital procurement.
South Korea
Advanced image sensor fabrication facilities in Seoul and Gyeonggi Province control critical CMOS wafer output for global endoscope manufacturers. MFDS quality standards shape market entry requirements for visualization platforms seeking hospital procurement contracts. The Busan-Ulsan corridor supplies precision optical components to German and Japanese endoscope assemblers.
Surgical Visualization Market Competitive Environment
Global majors compete with regional champions across regulatory compliance and integrated platform contracting. The vendor base separates into consolidated multinationals with diversified medical technology portfolios and specialized endoscope manufacturers with captive optical production. Three archetypes dominate: integrated imaging conglomerates, dedicated endoscopy specialists, and emerging robotics-visualization hybrids. Competitive moves concentrate on M&A for AI software capabilities and strategic partnerships for semiconductor supply security.
Within the integrated imaging tier, Siemens Healthineers and GE Healthcare occupy positions spanning diagnostic imaging through surgical navigation platforms. Olympus Corporation and Karl Storz exemplify the dedicated endoscopy specialist archetype with concentrated expertise in flexible and rigid optical systems respectively. Stryker Corporation represents the surgical platform integrator model where visualization hardware converges with robotic and navigation technologies.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Stryker Corporation |
| Olympus Corporation |
| Medtronic |
| Karl Storz |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Others |
Value Chain & Pricing Dynamics
CMOS wafer pricing indices from Taiwan and South Korea fabrication facilities cascade through endoscope manufacturing networks, compressing margins on standard-definition camera heads while amplifying premium capture for 3D imaging and augmented reality configurations that command higher price floors.
Pricing Analysis
Input-cost pass-through from semiconductor fabrication runs through three-tier pricing structure across premium, standard, and economy levels. Premium tiers absorb CMOS cost volatility through integrated software bundling and extended service contracts, while standard tiers face compression from hospital procurement consolidation. Price differentiation hinges on FDA 510(k) clearance tier and volume scale commitments. Margins are tightening in the standard tier due to elongated replacement cycles stretching toward seven years. Ambulatory surgical centers exhibit highest price sensitivity; German university hospitals show least sensitivity given bundled platform contracting.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, while advanced CMOS sensor output concentrates in Taiwan and South Korea fabrication facilities. German optical glass and Japanese precision lens grinding feed into endoscope assembly at Tuttlingen and Tokyo clusters. Single-source vulnerability in CMOS wafer allocation exposes manufacturers to geopolitical disruption and foundry capacity constraints. Distribution runs through integrated delivery network procurement offices in the United States and hospital purchasing consortiums in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in surgical visualization rests on CMOS sensor backward integration and the premium-tier shift toward AI-enabled software bundles that decouple revenue from hardware replacement cycles.
For Market Incumbents: Lock in semiconductor supply security through captive fabrication partnerships or long-term offtake agreements with Taiwan and South Korea foundries. Consolidate channel control by expanding enterprise-wide visualization platform contracts that bundle camera systems, software licenses, and service agreements to raise switching costs against emerging robotics-visualization hybrids. For New Entrants and Emerging Players: Wireless connectivity modules with sub-10ms latency specifications offer a technology-first wedge into diagnostic endoscopy applications where cable management burdens constrain incumbent solutions. Target ambulatory surgical center buildouts in United States certificate-of-need deregulated states where compact visualization suite demand outpaces established vendor service capacity. Pursue direct-to-facility sales models bypassing integrated delivery network procurement gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-enabled visualization software developers holding FDA breakthrough device designations and EU AI Act conformity assessment body pre-certifications. Five-to-ten year viability favors platforms with recurring revenue models and algorithmic update pathways rather than pure hardware plays. Monitor PMDA priority review designation announcements as inflection indicators for Japan market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Sensor Backward Integration | Captive semiconductor supply secures margin control against Taiwan and South Korea foundry allocation constraints. |
| FDA Breakthrough Device Designation | Accelerated 510(k) pathways compress commercialization timelines for AI-enabled surgical planning platforms. |
| EU AI Act Conformity Pre-Certification | Early quality management system alignment reduces post-market surveillance burden for high-risk algorithmic features. |
| Ambulatory Surgical Center Partnership | Direct channel access bypasses integrated delivery network procurement consolidation in United States outpatient migration. |
| Software Companion Development | Recurring license revenue decouples growth from capital equipment replacement cycles stretching toward seven years. |
Study Parameters
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at visualization platform manufacturers grounded qualitative findings. Secondary validation drew from FDA 510(k) premarket notification databases, CE marking certificates under EU MDR, PMDA quality standard filings, hospital procurement contract disclosures, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation cross-checked unit shipment estimates against capital equipment budget allocations across facility tiers.
Bottom-up modeling aggregated procedure volume forecasts by surgical discipline against visualization system penetration rates and replacement cycle assumptions across the projection horizon. Top-down analysis calibrated aggregate market sizing against manufacturer revenue disclosures and GPO contract value ranges. Segmentation dimensions spanned product type, technology tier, end-user facility category, and application specialty. CAGR derivation incorporated historical replacement cycle compression, regulatory approval velocity, and software attach rate trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMOS wafer supply disruption, FDA digital health guidance evolution, and EU AI Act enforcement interpretation. Forecasts reflect documented assumptions regarding procedure volume migration, reimbursement stability, and hospital capital budget allocation priorities. A small set of named triggers warrants ongoing watch: Taiwan semiconductor foundry utilization rates, FDA breakthrough device designation velocity, and Japan PMDA priority review queue depth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Resectoscopes Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Global Surgical Instrument Tracking System Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Surgical Tubing Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market