
 Handheld Arthroscopic Instruments Market | 2026-2036
Handheld Arthroscopic Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Arthroscopic Instruments Market Foresight
Asset-light leasing and pay-per-procedure financing is narrowing the capital barrier for mid-sized orthopedic clinics seeking advanced arthroscopic toolsets. Smith & Nephew leverages its integrated sports medicine portfolio to sustain recurring blade and shaver revenue. Arthrex anchors its position through dense surgeon training networks and proprietary suture anchor ecosystems. Karl Storz competes on optical precision, dominating rigid endoscope quality benchmarks that hospitals specify in tenders.
Handheld arthroscopic instruments comprise manually operated graspers, scissors, suture passers, and dissectors fabricated from surgical-grade stainless steel or titanium alloys with insulated electrosurgical coatings, designed for minimally invasive joint visualization and tissue manipulation through small portal incisions. Suture passers command premium positioning due to technical complexity in rotator cuff repair, while dissectors represent the fastest-growing product category as hip arthroscopy volumes expand. Among end users, ambulatory surgery centers are displacing hospital inpatient volumes for knee and shoulder procedures, concentrating margin pools in outpatient procurement channels.
FDA 510(k) clearance pathways and EU MDR conformity requirements shape product development timelines and sterilization validation standards for manufacturers seeking market access. ISO 13485 quality management systems and ASTM surgical instrument material specifications further constrain supplier qualification. Stakeholders must monitor how MDR transition bottlenecks and notified body capacity constraints alter competitive entry timing across European markets.
Market Dynamics
Ambulatory surgery centers in Germany and the United States are consolidating procurement volumes for knee and shoulder arthroscopy, compressing hospital inpatient shares and forcing instrument suppliers to reconfigure service models around outpatient workflow economics.
Growth Catalysts
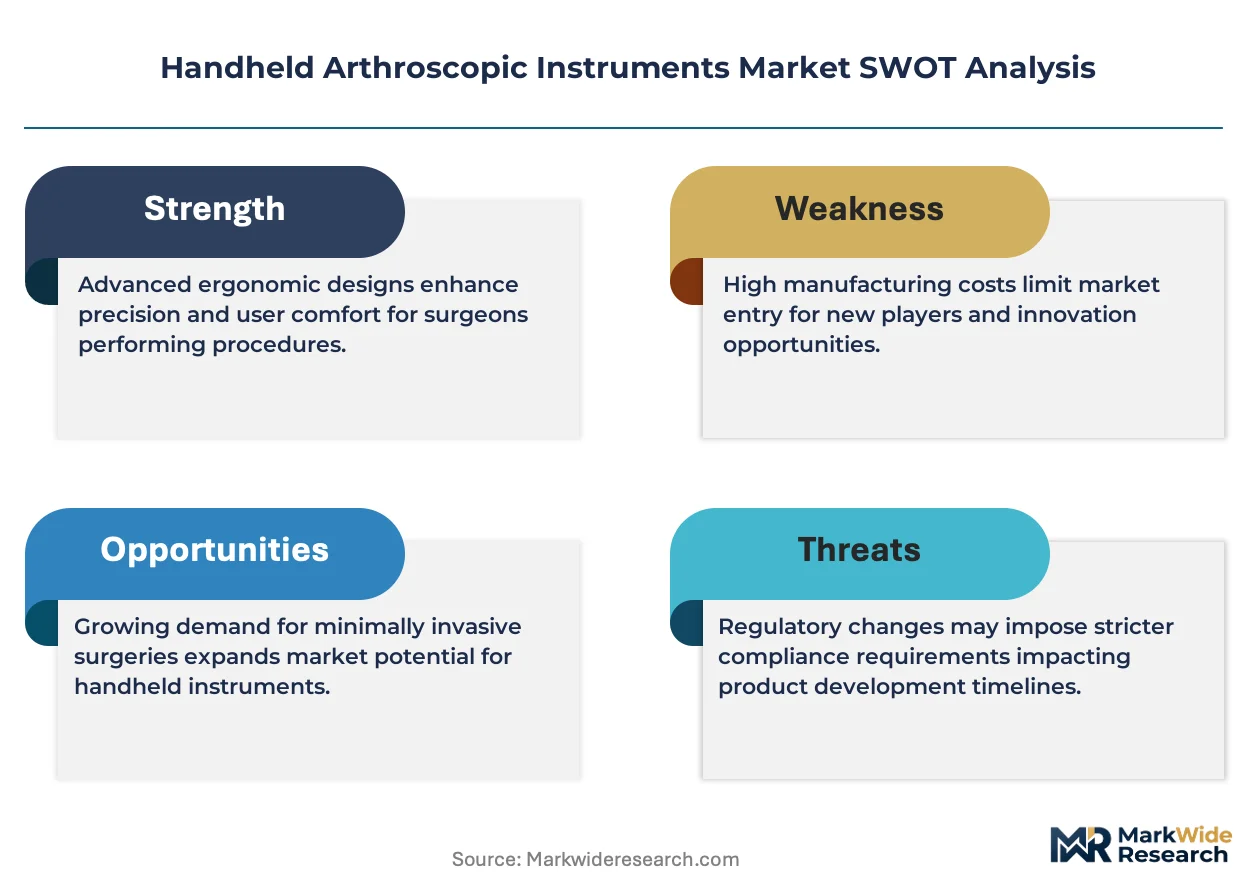
- EU MDR compliance deadlines:Manufacturers accelerating sterilization validation investments are capturing notified body capacity before bottlenecks harden, securing first-mover positioning in European tenders.
- Titanium alloy instrument adoption:Lighter-weight graspers and scissors reduce surgeon fatigue during extended rotator cuff repairs, driving replacement cycles in high-volume orthopedic clinics.
- German precision manufacturing clusters:Concentrated supplier networks in Tuttlingen and Solingen shorten lead times for electrosurgical-coated dissectors serving Benelux and Nordic markets.
Market Restraints
- Surgical-grade stainless steel price volatility:Nickel and chromium input cost swings compress margin predictability for mid-tier instrument fabricators without long-term raw material hedging.
- Notified body concentration in Germany and Netherlands:EU MDR audit queue bottlenecks extend time-to-market for suture passer innovations, advantaging incumbents with established technical files.
- Open surgery persistence in hip interventions:Anatomical complexity and learning curve barriers limit arthroscopic dissector penetration against traditional approaches in certain patient populations.
Strategic Opportunities
- Pay-per-procedure financing:Asset-light leasing models unlock mid-sized orthopedic clinics in Spain and Italy previously excluded by capital expenditure thresholds for advanced shaver systems.
- Hip arthroscopy expansion:Femoroacetabular impingement diagnosis rates create unmet demand for curved dissectors and specialized retractors in sports medicine practices.
- ISO 13485 certification arbitrage:Suppliers achieving quality management alignment ahead of MDR enforcement capture procurement specifications requiring documented traceability.
Industry Challenges
- Electrosurgical coating technician scarcity:Insulated instrument fabrication requires specialized plasma deposition expertise concentrated among German and Swiss suppliers, constraining production scaling.
- 510(k) predicate device navigation:FDA substantial equivalence determinations for novel suture passer geometries face heightened scrutiny, extending regulatory timelines without predicate clarity.
- Legacy sterilization infrastructure incompatibility:Newer titanium alloy instruments require modified autoclave protocols, forcing ambulatory surgery centers to revalidate workflows or outsource processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Arthroscopic Instruments Market |
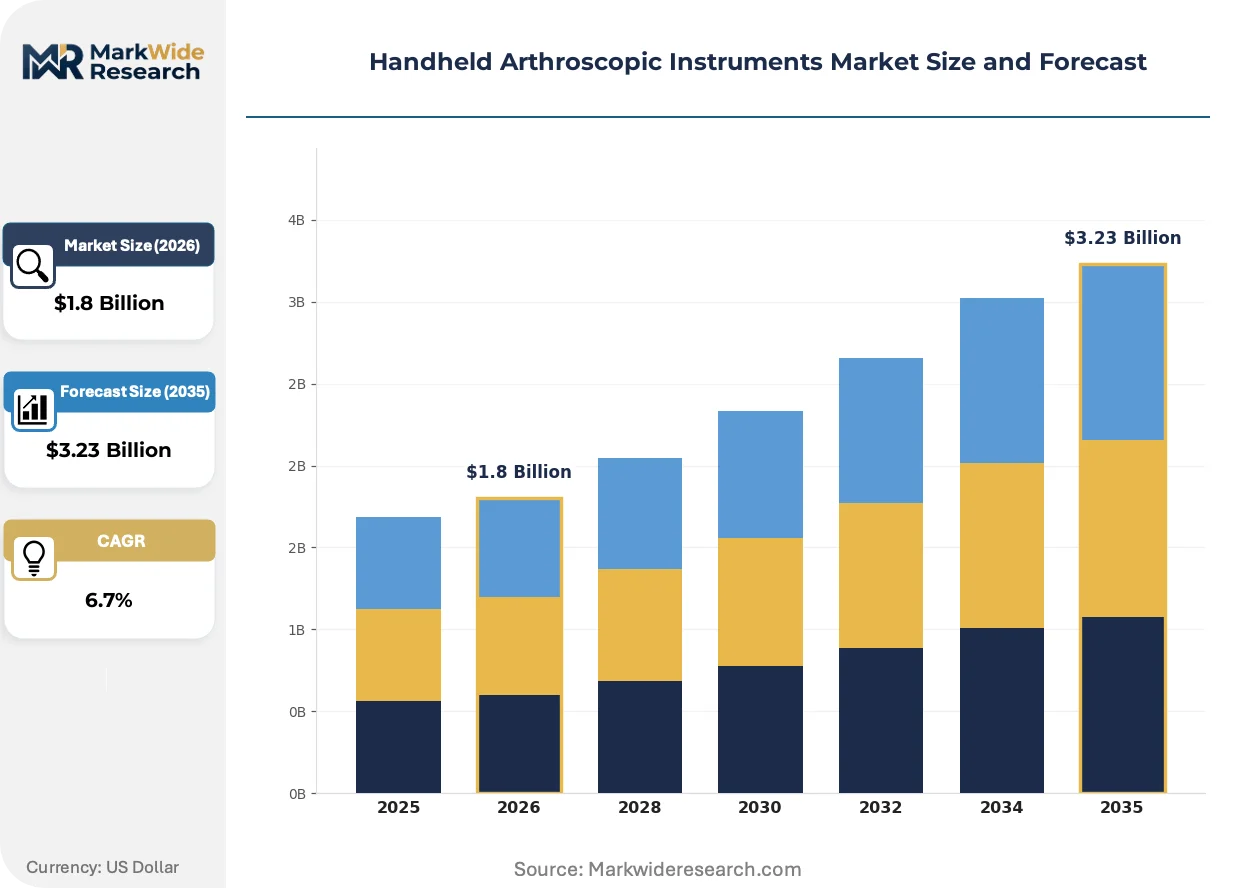
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graspers, Scissors, Suture Passers, Dissector End User: Hospitals, Ambulatory Surgery Centers, Orthopedic Clinics, Research Laboratories Technology: Electrosurgical Devices, Laser Instruments, Optical Systems, Digital Imaging Application: Knee Surgery, Shoulder Repair, Hip Arthroscopy, Ankle Procedures |
| Companies Covered | Smith & Nephew, Johnson & Johnson, Medtronic, Arthrex, Stryker, Zimmer Biomet, Conmed, Olympus, Karl Storz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Arthroscopic Instruments Market Shifts & Advancements
Handheld arthroscopic instrument development is converging around material science advances, regulatory compliance automation, and procurement model restructuring that collectively redefine competitive differentiation beyond traditional feature sets.
Carbon-reinforced PEEK composite instrument handles are hybridizing with traditional metal shafts to reduce thermal conductivity during electrosurgical activation. High-volume shoulder specialists in German outpatient clinics are piloting these configurations to minimize collateral tissue damage. This material convergence is hybridizing supply chain requirements, forcing coating subcontractors to develop adhesion protocols for dissimilar substrates.
EU MDR technical documentation mandates are compressing product development timelines through structured quality management system integration. Manufacturers embedding post-market surveillance data loops into design controls are securing notified body confidence faster than peers relying on legacy paper-based submissions. Suture anchor and passer categories face the steepest compliance burden given their permanent implant adjacency classifications.
Surgeon preference cards are digitizing through hospital information system integration, enabling real-time consumption tracking that unbundles instrument sets from procedure-based billing. Ambulatory surgery centers in Bavaria and North Rhine-Westphalia are piloting consignment inventory models where suppliers retain ownership until point-of-use activation. This consumption-pattern shift is visible most acutely in Germany, where integrated care contracts pressure orthopedic networks to demonstrate supply cost transparency.
Handheld Arthroscopic Instruments Market Segmentation
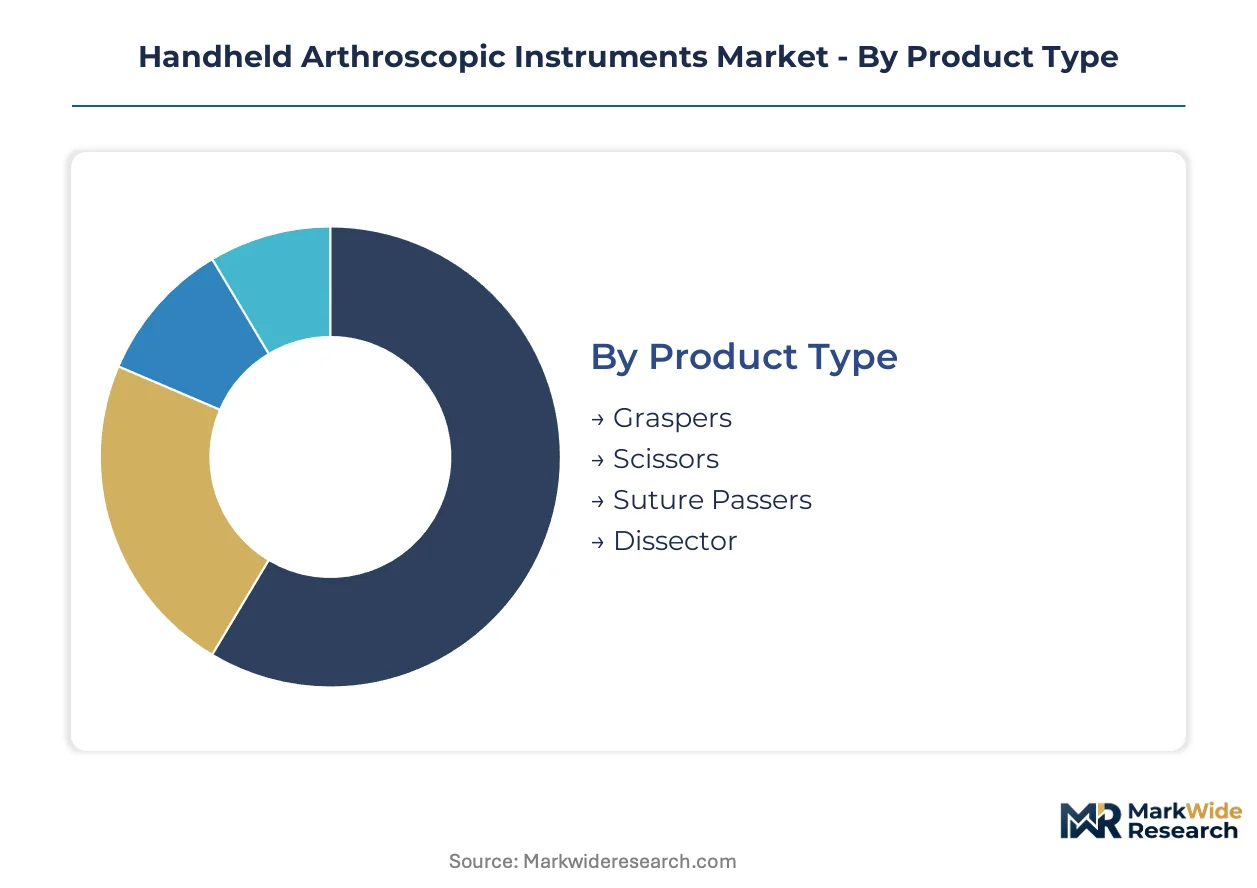
Segmentation in handheld arthroscopic instruments reveals how procurement priorities diverge across surgical settings and anatomical applications. Understanding these divisions exposes where margin pools concentrate and which technical specifications command premium positioning in tenders.
Product Type:
Maturity varies sharply across this category, with established mechanical designs competing against electrosurgical-enhanced formats still penetrating high-volume clinics.
- Graspers:Fabricated from surgical-grade stainless steel or titanium alloys with insulated electrosurgical coatings, these instruments dominate knee and shoulder volume in German outpatient networks. Procurement specifications increasingly require ergonomic handle geometries that reduce fatigue during extended rotator cuff repairs.
- Suture Passers:Technical complexity in rotator cuff repair applications commands premium positioning, with curved and straight configurations specified separately in surgeon preference cards. German precision manufacturing clusters in Tuttlingen supply the majority of European demand for these high-margin instruments.
- Scissors:Manual and powered variants serve tissue debridement across multiple joint applications, with titanium alloy adoption accelerating in high-volume orthopedic clinics seeking reduced weight.
- Dissector:Curved and angled configurations address femoroacetabular impingement in hip arthroscopy, where anatomical complexity drives specialized instrument demand.
Graspers retain volume leadership; dissectors hold the steepest expansion curve.
End User:
Procurement authority is shifting toward outpatient channels as reimbursement models compress hospital inpatient economics.
- Hospitals:Academic medical centers maintain bulk purchasing leverage for comprehensive instrument sets, though their share of knee and shoulder procedures is compressing under integrated care contracts in Germany and the United States.
- Ambulatory Surgery Centers:These facilities now concentrate margin pools for arthroscopic knee and shoulder repair, displacing hospital inpatient volumes and forcing suppliers to reconfigure service models around rapid instrument turnover and consignment inventory.
- Orthopedic Clinics:Mid-sized practices in Spain and Italy are unlocking access through asset-light leasing models that circumvent capital expenditure thresholds for advanced shaver systems.
- Research Laboratories:Preclinical testing facilities drive demand for prototype instruments and validation batches, particularly in German medical device development clusters.
Ambulatory surgery centers are capturing procedure volume fastest; hospitals maintain the largest installed base.
Technology:
Cost tier differentiation separates capital-intensive integrated systems from disposable-enhanced manual instruments.
- Electrosurgical Devices:Plasma-deposited insulated coatings on graspers and scissors enable hemostasis during tissue manipulation, with German and Swiss suppliers dominating specialized fabrication expertise that constrains production scaling.
- Laser Instruments:Tissue ablation applications in synovectomy and chondroplasty remain niche due to capital equipment requirements and specialized training protocols.
- Optical Systems:Rigid endoscopes with precision-ground lens systems anchor visualization quality benchmarks that Karl Storz and competitors specify in hospital tenders.
- Digital Imaging:Camera heads and image processing units are integrating with handheld instruments through proprietary connector ecosystems that lock purchasing decisions to platform choices.
Optical systems command the highest average selling prices; digital imaging is expanding most quickly through platform integration mandates.
Application:
Volume concentration in knee repair contrasts with emerging demand complexity in hip interventions.
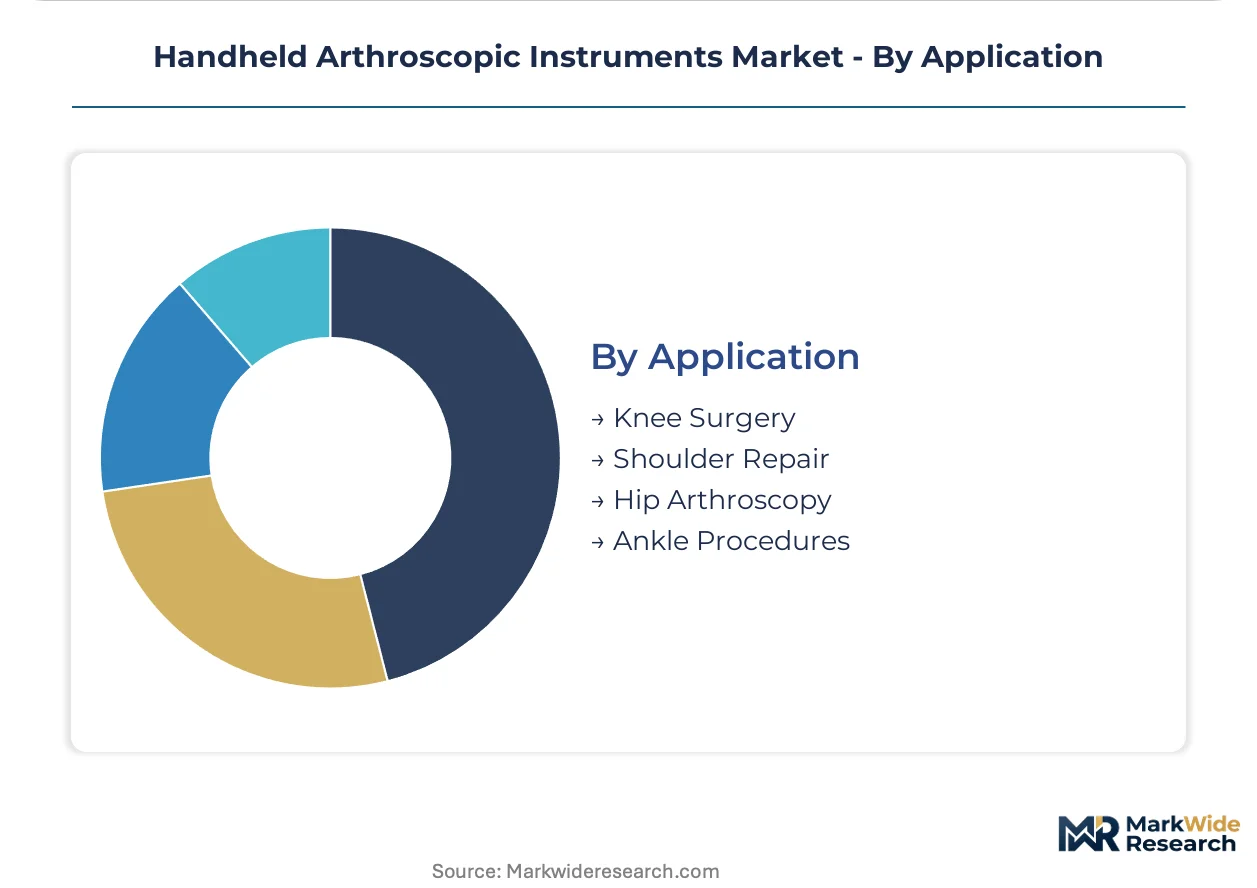
- Knee Surgery:Meniscal repair and anterior cruciate ligament reconstruction drive the highest instrument consumption volumes, with standardized portal configurations enabling economies in instrument set design.
- Shoulder Repair:Rotator cuff procedures demand specialized suture passers and graspers with angled shafts, creating preference fragmentation that complicates standardization efforts.
- Hip Arthroscopy:Femoroacetabular impingement diagnosis rates are climbing in sports medicine practices, generating unmet demand for curved dissectors and specialized retractors that accommodate constrained joint access.
- Ankle Procedures:Arthroscopic ankle fusion and impingement release represent lower absolute volumes but higher instrument specificity requirements per procedure.
Knee surgery retains volume leadership; hip arthroscopy holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement incentives for outpatient joint repair are accelerating procurement shifts toward ambulatory channels in developed healthcare systems. Germany's integrated care contracts compress hospital inpatient economics while precision manufacturing clusters shorten lead times for electrosurgical-coated instruments. Regulatory compliance timelines in the United States and European Union are elevating entry barriers for mid-tier suppliers.
United States
CMS reimbursement parity for ambulatory surgery centers drives knee and shoulder procedure migration away from hospital inpatient settings. FDA 510(k) clearance pathways shape sterilization validation standards for titanium alloy graspers and suture passers. The Greater Boston corridor anchors preclinical testing facilities that validate prototype instruments for rotator cuff repair applications.
Germany
Integrated care contracts pressure orthopedic networks to demonstrate supply cost transparency and rapid instrument turnover. EU MDR conformity requirements and notified body audit queues extend time-to-market for novel dissector geometries. The Tuttlingen and Solingen precision manufacturing clusters dominate European supply for electrosurgical-coated instruments serving Benelux and Nordic markets.
France
ANSM oversight of medical device vigilance systems elevates post-market surveillance requirements for suture anchor adjacent classifications. Regional health agency procurement consolidation in Île-de-France concentrates tender volumes for comprehensive arthroscopic instrument sets. The Auvergne-Rhône-Alpes medical technology corridor hosts validation laboratories supporting MDR technical documentation preparation.
United Kingdom
NHS England integrated care board procurement frameworks standardize surgeon preference card specifications across hospital networks. MHRA recognition of EU MDR certificates during transition periods maintains market access continuity for German and Swiss suppliers. The Oxford-Cambridge arc concentrates sports medicine research facilities driving hip arthroscopy technique adoption.
Italy
Regional health system budget constraints accelerate pay-per-procedure financing adoption among mid-sized orthopedic clinics in Lombardy and Veneto. Ministry of Health medical device registration requirements align with EU MDR implementation timelines. The Emilia-Romagna medical device district hosts coating subcontractors developing plasma deposition protocols for carbon-reinforced PEEK composite handles.
Handheld Arthroscopic Instruments Market Competitive Landscape
On the supply side, the industry is consolidating around integrated sports medicine portfolios that capture recurring blade and shaver revenue through proprietary ecosystems. Tiered competitive positioning separates premium optical precision specialists from mid-tier mechanical instrument fabricators and emerging material science innovators. Dominant competitive moves include strategic partnerships between coating subcontractors and original equipment manufacturers, plus backward integration into titanium alloy forging capabilities that secure raw material cost predictability.
Among diversified orthopedic conglomerates, Smith & Nephew and Johnson & Johnson occupy positions that exemplify integrated portfolio strategies spanning implants, instruments, and biologics. Arthrex represents the specialist archetype, anchoring competitive positioning through dense surgeon training networks and proprietary suture anchor ecosystems that lock purchasing decisions to platform choices. Karl Storz sits within the optical precision tier, where rigid endoscope quality benchmarks specified in hospital tenders create defensive moats against mechanical instrument competitors.
| Leading Market Players |
|---|
| Smith & Nephew |
| Johnson & Johnson |
| Medtronic |
| Arthrex |
| Stryker |
| Zimmer Biomet |
| Conmed |
| Olympus |
| Karl Storz |
| Others |
Supply & Pricing Matrix
German precision manufacturing clusters in Tuttlingen and Solingen concentrate electrosurgical coating expertise, anchoring premium margin capture for titanium alloy instruments serving ambulatory surgery centers in Benelux and Nordic markets. This upstream concentration of specialized plasma deposition capability creates pricing power asymmetries that downstream buyers navigate through consignment inventory and pay-per-procedure financing structures.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-validated premium tiers and standard mechanical instrument offerings. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, EU MDR conformity, and sterilization validation depth. Cost compression in mid-tier stainless steel graspers is intensifying because nickel and chromium input volatility erodes fabricator margins without hedging programs. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Extended payment terms from German and Swiss coating subcontractors to original equipment manufacturers compress working capital cycles throughout the value chain. Supply concentrates in Germany for electrosurgical instrument fabrication, Switzerland for precision optical components, and Italy for carbon-reinforced PEEK composite handle development. Raw material dependencies center on surgical-grade titanium alloys, nickel-chromium stainless steel, and plasma deposition gases. Single-source vulnerability in electrosurgical coating technician pools constrains production scaling. Distribution runs through orthopedic GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized plasma deposition expertise for insulated instrument fabrication represents a binding constraint that shapes competitive outcomes across all tiers. Firms controlling this scarce technical capability capture disproportionate returns regardless of downstream brand positioning.
For Market Incumbents: Pre-empt coating subcontractor consolidation by securing exclusive capacity agreements with Tuttlingen-based plasma deposition specialists before notified body bottlenecks harden. Deepen backward integration into titanium alloy forging to secure raw material cost predictability against nickel price volatility. Lock in ambulatory surgery center procurement through consignment inventory models that embed switching costs. For New Entrants and Emerging Players: Build out hip arthroscopy dissector portfolios targeting Spanish and Italian orthopedic clinics excluded by capital thresholds from integrated shaver systems. The pay-per-procedure financing white space in Southern European mid-sized practices offers the most penetrable entry vector. Lead with asset-light leasing propositions that circumvent hospital GPO contract barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed German precision manufacturers holding notified body relationships and established EU MDR technical files. The five-to-ten year viability window favors platforms with surgeon training network density and proprietary suture anchor ecosystems. Monitor FDA 510(k) clearance queue lengths as an inflection indicator for regulatory capacity constraints advantaging incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Notified body capacity capture before audit queue bottlenecks harden secures European tender positioning. |
| Plasma Deposition Partnership | Exclusive coating subcontractor agreements lock in electrosurgical instrument fabrication capacity against technician scarcity. |
| Surgeon Training Network Expansion | Dense education infrastructure anchors proprietary suture passer ecosystem loyalty in rotator cuff repair. |
| Consignment Inventory Deployment | Point-of-use activation models align supplier ownership with ambulatory surgery center workflow economics. |
| Titanium Alloy Forging Integration | Captive raw material supply hedges nickel price volatility for high-volume graspers and scissors. |
Research Methodology
Cross-validation between hospital procurement database analysis and surgeon preference card audits anchors the qualitative findings in observable transaction patterns. Primary interviews with orthopedic surgeons, ambulatory surgery center administrators, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body registers, hospital tender documentation, and ASTM surgical instrument standards. Bottom-up instrument set pricing analysis triangulates against top-down market sizing from manufacturer revenue disclosures.
Calibration against historical procedure volume trajectories and reimbursement rate shifts informs the projection framework. Segmentation modeling spans product type, end user channel, application anatomy, and technology format across the analysis window. CAGRs derive from fitted growth curves adjusted for regulatory transition impacts and material substitution patterns. Forecast inputs incorporate EU MDR implementation timelines and ambulatory surgery center reimbursement parity expansion.
Stress conditions across nickel price volatility bands, notified body audit queue durations, and hip arthroscopy adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about sterilization validation standards and integrated care contract penetration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Dissolvable Sutures Market