
 Surgical Hemostats Market | 2026-2036
Surgical Hemostats Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Hemostats Market Analysis
EU MDR is broadening the cost-of-entry calculus for surgical hemostat manufacturers seeking CE marking. Johnson & Johnson leverages its pre-existing clinical dossiers to sustain European market access. Baxter International anchors its position through specialized hemostasis portfolios aligned with notified body expectations. B. Braun Melsungen AG competes by extending manufacturing scale across multiple hemostatic form factors.
Surgical hemostats comprise flowable, mechanical, and active agents—typically oxidized cellulose, gelatin sponges, or thrombin-based formulations—engineered to accelerate clot formation and reduce intraoperative blood loss during open and laparoscopic procedures. Passive hemostats, particularly oxidized regenerated cellulose matrices, dominate current volume due to established reimbursement pathways and surgeon familiarity. Combination hemostats represent the fastest-expanding product category as manufacturers integrate mechanical substrates with active biologics to address refractory bleeding in cardiac and orthopedic surgery applications.
FDA premarket notification requirements, EU MDR technical documentation mandates, and Japan PMDA quality management system inspections collectively shape product development timelines and commercial launch sequencing across major markets. ISO 10993 biocompatibility testing standards further constrain material selection and validation protocols for absorbable hemostatic devices. Stakeholders must monitor evolving notified body capacity constraints in Europe and FDA guidance on human-derived tissue products to anticipate regulatory bottlenecks that could alter competitive timelines.
Market Dynamics
EU MDR technical documentation mandates are compressing commercial timelines for absorbable hemostatic agents, forcing manufacturers to front-load clinical validation costs and restructure European launch sequencing around notified body capacity constraints.
Growth Catalysts
- Cardiac surgery volume expansion:Rising coronary artery bypass grafting procedures in the United States and Germany pull demand for combination hemostats with active thrombin components.
- EU MDR Article 117:Stricter biocompatibility requirements for absorbable devices are accelerating substitution toward validated oxidized cellulose platforms with established ISO 10993 dossiers.
- Laparoscopic technique diffusion:Minimally invasive surgical adoption across Japanese tertiary hospitals expands addressable indications for flowable hemostatic agents.
Market Restraints
- Lyophilized thrombin input costs:Bovine and human plasma sourcing volatility constrains margin stability for active hemostat formulations.
- European notified body concentration:Only twelve designated entities handle MDR Class III device reviews, creating regulatory bottlenecks for new market entrants.
- Mechanical hemostat substitution ceiling:Oxidized regenerated cellulose matrices face technical limitations in coagulopathic patients, restricting penetration in high-bleed-risk procedures.
Strategic Opportunities
- Pediatric cardiac surgery:Underpenetrated demand in US children's hospitals creates white space for biocompatible hemostats with reduced immunogenicity profiles.
- Japan PMDA QMS harmonization:Streamlined inspection protocols for ISO 13485-certified manufacturers accelerate commercial access to Asia-Pacific's second-largest surgical device market.
- Integrated delivery network procurement consolidation:Centralized purchasing by US health systems enables premium hemostat category management and long-term supply agreements.
Industry Challenges
- Biocompatibility validation timelines:ISO 10993-6 implantation studies and cytotoxicity testing extend product development cycles by eighteen to twenty-four months.
- Legacy sterilization infrastructure:Ethylene oxide processing capacity constraints force manufacturers to revalidate gamma or e-beam alternatives for gelatin-based hemostats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Hemostats Market |
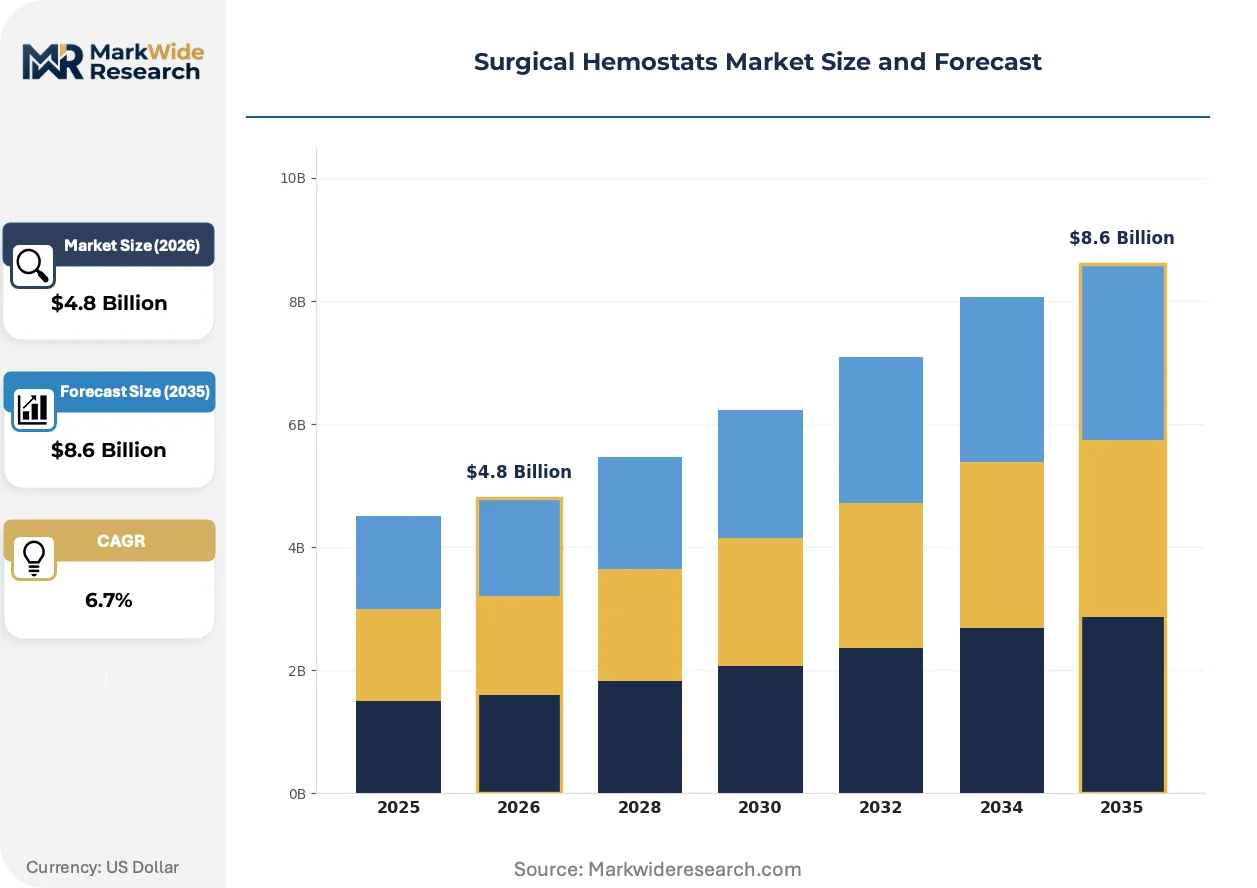
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Hemostats, Passive Hemostats, Combination Hemostats, Topical Hemostats End User: Hospitals, Ambulatory Surgical Centers, Trauma Centers, Specialty Clinics Application: Cardiac Surgery, General Surgery, Orthopedic Surgery, Gastrointestinal Surgery Form: Spray, Gel, Powder, Patch |
| Companies Covered | Johnson & Johnson, Baxter International, B. Braun Melsungen AG, Pfizer, BD, Teleflex, Stryker Corporation, Integra LifeSciences, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Hemostats Market Emerging Trajectories
Combination hemostat architectures are displacing single-mechanism products as surgeons demand simultaneous mechanical compression and active clotting acceleration in complex procedures.
Flowable hemostatic matrices incorporating oxidized cellulose and bovine thrombin are decentralizing surgical site preparation from central pharmacy mixing to point-of-use application. Cardiac surgery teams in Cleveland Clinic and Mayo Clinic facilities now deploy these systems directly in hybrid operating suites. This capability compression eliminates preoperative workflow friction and reduces blood product transfusion dependency.
EU MDR Annex I general safety and performance requirements are forcing hemostat manufacturers to generate clinical evidence beyond predicate equivalence. The regulation demands post-market clinical follow-up for absorbable devices, which extends CE marking timelines and favors incumbents with existing patient registries. German and French notified bodies are prioritizing reviews for hemostats with drug-device combination status.
US integrated delivery networks are consolidating hemostat procurement under value-analysis committees that unbundle product selection from individual surgeon preference. These committees now mandate standardized formularies across member hospitals, replacing decentralized operating room stock decisions. The shift is most visible in Texas and California health systems where three-tier pricing structures separate premium combination agents from standard mechanical hemostats.
Surgical Hemostats Market Segmentation
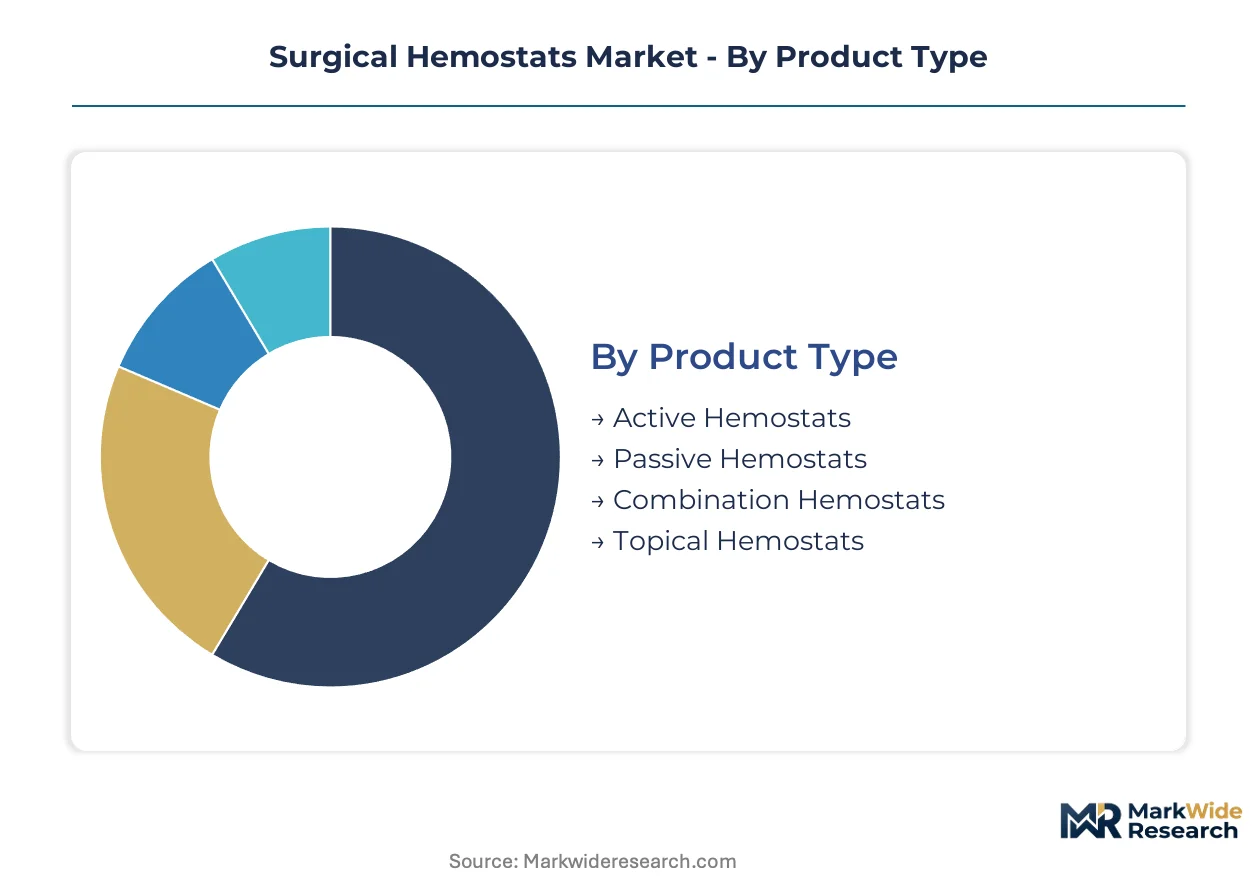
Surgical hemostat purchasing decisions pivot on procedure complexity, bleeding risk profiles, and institutional formulary standardization. Segmentation reveals how product architectures align with specific surgical workflows and regulatory validation requirements across care settings.
Product Type:
Upgrade cycles favor validated platforms with established ISO 10993 dossiers over novel formulations requiring extended clinical validation.
- Passive Hemostats:Oxidized regenerated cellulose matrices and gelatin sponges provide mechanical compression without active biologics. Demand concentrates in United States community hospitals where established reimbursement pathways and surgeon familiarity sustain volume leadership despite technical limitations in coagulopathic patients.
- Combination Hemostats:Integrated mechanical substrates with thrombin or fibrin sealants address refractory bleeding in complex procedures. Cleveland Clinic and Mayo Clinic cardiac surgery teams in the United States drive adoption through point-of-use deployment in hybrid operating suites, eliminating central pharmacy mixing delays.
- Active Hemostats:Thrombin-based formulations accelerate clot formation through direct enzymatic action. Bovine and human plasma sourcing volatility constrains margin stability for manufacturers.
- Topical Hemostats:Surface-applied agents for minor bleeding control in dermatologic and dental procedures. Japanese tertiary hospitals show expanding uptake for outpatient applications.
Passive hemostats sit at the top of the volume ranking, with combination hemostats climbing the fastest.
End User:
Customer type determines procurement leverage, with centralized purchasing power reshaping supplier relationships across care delivery networks.
- Hospitals:Integrated delivery networks in Texas and California health systems mandate standardized formularies across member facilities, replacing decentralized operating room stock decisions with value-analysis committee oversight.
- Ambulatory Surgical Centers:Cost-sensitive settings favor mechanical hemostats with immediate availability and minimal storage requirements. German outpatient surgery expansion drives regional demand concentration.
- Trauma Centers:Emergency bleeding control requires rapid-deployment formats with minimal preparation. United States Level I trauma facilities in urban corridors sustain premium pricing tolerance for combination agents.
- Specialty Clinics:Concentrated procedure volumes enable product-specific training and workflow optimization. French ophthalmologic and orthopedic specialty networks show targeted adoption patterns.
Hospitals command the dominant procurement volume position, while ambulatory surgical centers are gaining share fastest as procedure migration accelerates.
Application:
Procedure-specific bleeding profiles dictate hemostat selection, with cardiac and orthopedic applications driving premium product uptake.
- Cardiac Surgery:Coronary artery bypass grafting and valve replacement procedures generate the steepest demand for combination hemostats with active thrombin components. United States and German surgical volume expansion pulls manufacturer R&D investment toward validated cardiac indications.
- Orthopedic Surgery:Joint replacement and spinal fusion procedures require flowable agents for irregular bone surfaces. Japanese tertiary hospital adoption of minimally invasive techniques expands addressable indications for spray and gel formats.
- General Surgery:Broad procedural diversity sustains demand across multiple hemostat categories. Cost containment pressures in European public health systems favor mechanical platforms.
- Gastrointestinal Surgery:Laparoscopic resections and bariatric procedures demand hemostats compatible with insufflation environments. French and German hepatobiliary centers show specialized formulation preferences.
Cardiac surgery anchors premium product revenue, with orthopedic surgery expanding most quickly as joint replacement volumes rise.
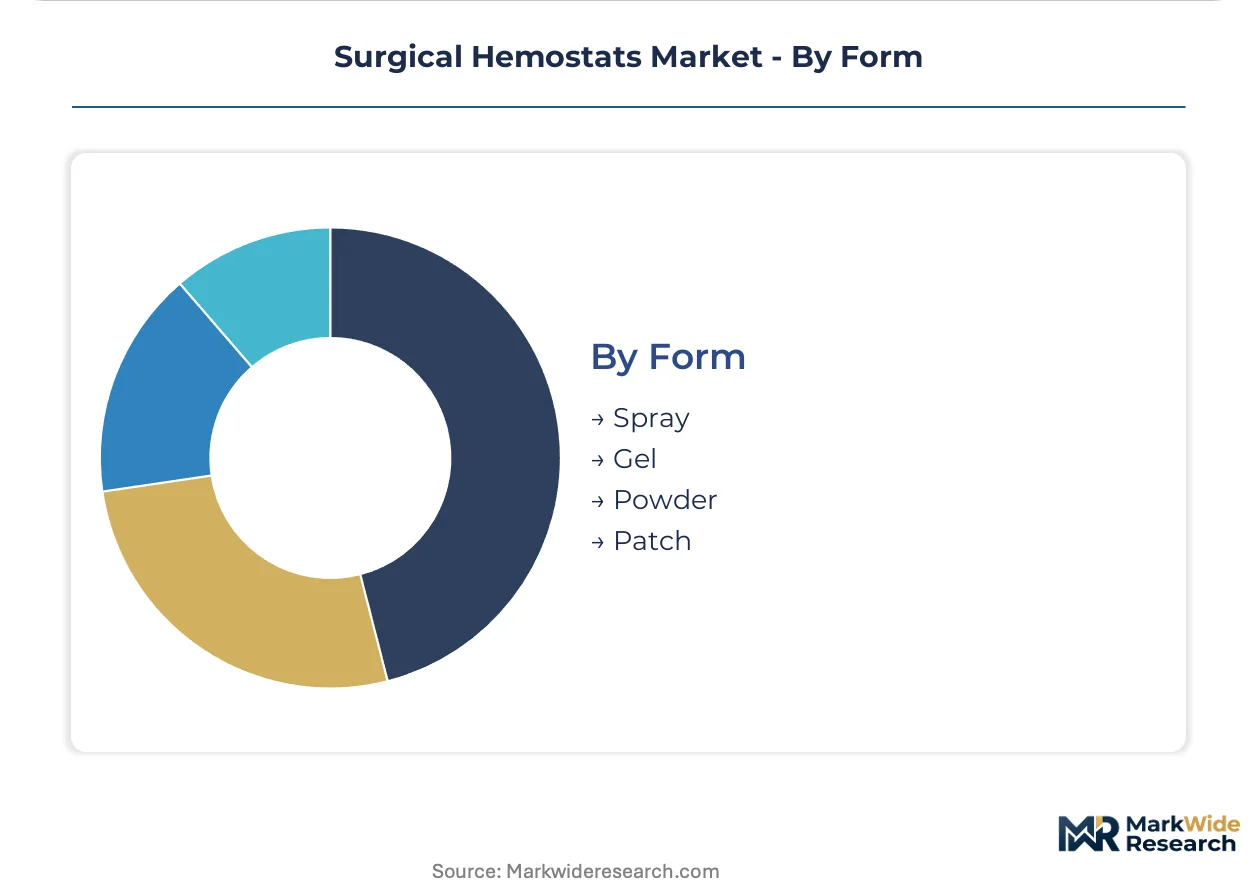
Form:
Format selection reflects surgical access constraints and site preparation workflow requirements across open and minimally invasive approaches.
- Spray:Aerosolized delivery enables rapid coverage of irregular surfaces in laparoscopic and open procedures. United States integrated delivery networks prioritize spray formats for operating room efficiency gains.
- Powder:Dry particulate application suits diffuse bleeding scenarios in thoracic and hepatic surgery. German surgical centers show preference for powder formats in trauma applications.
- Gel:Viscous matrices conform to tissue topography with controlled application. Japanese minimally invasive adoption drives gel format volume in Asia-Pacific.
- Patch:Pre-formed sheets provide mechanical compression with standardized dosing. Cost-sensitive European procurement favors patch formats for predictable unit economics.
Spray formats lead current volume rankings, with powder configurations gaining share fastest as trauma and thoracic applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac surgeon density in the United States and Germany anchors regional demand concentration, with specialized training programs sustaining procedure volume leadership across North America and Western Europe.
United States
Cleveland Clinic and Mayo Clinic cardiac surgery teams drive combination hemostat adoption through point-of-use deployment in hybrid operating suites. FDA premarket notification requirements shape product development timelines for absorbable devices. Texas and California integrated delivery networks consolidate procurement under value-analysis committees, replacing decentralized operating room stock decisions with standardized formularies.
Germany
Coronary artery bypass grafting volume expansion pulls demand for thrombin-based combination agents. EU MDR technical documentation mandates compress commercial timelines, forcing manufacturers to front-load clinical validation costs. Berlin and Frankfurt hepatobiliary centers show specialized formulation preferences for laparoscopic resections, expanding addressable indications for flowable formats.
Japan
Minimally invasive surgical adoption across Tokyo and Osaka tertiary hospitals expands demand for spray and gel hemostatic configurations. PMDA quality management system inspections for ISO 13485-certified manufacturers accelerate commercial access timelines. Kansai region orthopedic centers drive uptake for flowable agents in joint replacement procedures.
France
Public health system cost containment pressures favor mechanical hemostat platforms with established reimbursement pathways. ANSM prioritizes reviews for drug-device combination hemostats under EU MDR Article 117. Lyon and Paris surgical clusters concentrate specialized training for complex cardiac procedures, sustaining premium product demand.
United Kingdom
NHS procurement consolidation shifts hemostat selection toward standardized mechanical platforms with predictable unit economics. MHRA post-Brexit regulatory alignment with EU MDR extends validation requirements for absorbable devices. London and Manchester teaching hospitals anchor demand for validated oxidized cellulose matrices in general surgery applications.
Surgical Hemostats Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with pre-existing clinical dossiers and specialized hemostasis portfolios. Market concentration favors incumbents possessing established ISO 10993 biocompatibility testing records and notified body relationships. Three archetypes dominate: integrated device manufacturers with broad surgical portfolios, specialized hemostasis-focused divisions within larger healthcare conglomerates, and regional manufacturers competing on manufacturing scale across multiple form factors. Competitive moves center on regulatory dossier leveraging and manufacturing capacity expansion to address EU MDR bottlenecks.
Among diversified healthcare conglomerates, Johnson & Johnson and Baxter International exemplify archetypes positioned to sustain European market access through pre-existing clinical validation infrastructure. B. Braun Melsungen AG occupies a position representing manufacturing scale competition across multiple hemostatic form factors. These three entities anchor the competitive landscape by exemplifying distinct strategic postures: dossier leverage, specialized portfolio alignment, and manufacturing breadth respectively.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Baxter International |
| B. Braun Melsungen AG |
| Pfizer |
| BD |
| Teleflex |
| Stryker Corporation |
| Integra LifeSciences |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Integrated delivery network procurement consolidation in the United States and Germany is compressing supplier margins while rewarding manufacturers with validated ISO 10993 dossiers and established notified body relationships, forcing supply chain restructuring toward centralized distribution hubs and long-term contract structures.
Pricing Analysis
Bundled service contracts combining hemostat supply with technical training and formulary management are displacing per-unit transactional pricing in United States health systems. Three-tier pricing structure across premium combination agents, standard mechanical platforms, and economy cellulose matrices reflects certification grade and surgeon training requirements. Pricing pressure stems from European public health system cost containment mandates favoring mechanical platforms with predictable unit economics. Ambulatory surgical centers in Germany exhibit highest price sensitivity due to immediate availability requirements and minimal storage infrastructure, while United States Level I trauma facilities tolerate premium pricing for rapid-deployment combination formats.
Supply Chain Analysis
ISO 13485 certification and EU MDR technical documentation validation function as supply chain gating mechanisms that concentrate qualified manufacturing among established players with notified body relationships. Production concentrates in the United States, Germany, and Ireland for oxidized cellulose matrices and gelatin sponges, while bovine thrombin sourcing draws from Argentina and New Zealand plasma collection networks. Single-source vulnerability in lyophilized thrombin supply creates exposure to bovine spongiform encephalopathy regulatory restrictions and plasma fractionation capacity constraints. Distribution runs through hospital system central pharmacies and group purchasing organization contracts rather than direct-to-operating-room channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in surgical hemostats rests on manufacturers capturing premium positioning through combination product architectures while driving cost discipline in mechanical platform production, as European procurement consolidation and United States value-analysis committee standardization simultaneously reward scale and clinical validation depth.
For Market Incumbents: Hedge against mechanical hemostat substitution ceilings by accelerating thrombin-gelatin combination pipeline development and securing backward integration into bovine plasma sourcing. Invest in notified body relationship capacity to navigate EU MDR Article 117 bottlenecks before competitor dossiers mature. Prioritize long-term supply agreements with Texas and California integrated delivery networks to lock in formulary position ahead of procurement consolidation waves. For New Entrants and Emerging Players: Direct-to-ambulatory-surgical-center digital procurement platforms offer the most penetrable route for mechanical hemostat market entry, particularly in German outpatient surgery expansion corridors. Target Japanese tertiary hospital spray and gel format demand as PMDA QMS harmonization accelerates commercial access timelines. Position flowable hemostatic matrices for orthopedic joint replacement applications where minimally invasive technique diffusion creates unmet workflow needs. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized hemostasis divisions possessing established ISO 10993-6 implantation study records and active European notified body engagement. Long-term viability favors manufacturers with dual mechanical-active product portfolios capable of serving both cost-constrained European public systems and premium United States cardiac surgery segments. Monitor FDA guidance evolution on human-derived tissue products as an inflection indicator for thrombin-based formulation competitive timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation mandates compress timelines for absorbable hemostat approvals. |
| Hospital System Partnership | Integrated delivery network formulary standardization in Texas and California locks in volume commitment. |
| Backward Integration | In-house bovine plasma sourcing mitigates lyophilized thrombin input cost volatility. |
| Reimbursement Strategy | Established CMS pathways for oxidized cellulose sustain mechanical hemostat volume leadership. |
| Software Companion Development | Point-of-use mixing systems for flowable agents eliminate central pharmacy workflow friction. |
Methodological Framework
Bottom-up hospital and ambulatory surgical center demand modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with cardiac surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EU MDR notified body designation records, hospital procurement databases, and CMS Medicare reimbursement schedules. Cross-referencing clinician preference data against actual formulary adoption patterns enabled triangulation of stated versus revealed demand.
Historical surgical volume trendlines across cardiac, orthopedic, and general procedure categories informed projection frameworks segmented by product architecture, end-user facility type, application specialty, and delivery format. CAGRs were derived from elasticity-adjusted penetration curves for combination versus mechanical platforms, incorporating Japanese PMDA QMS inspection timeline assumptions and European notified body capacity constraints as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path favoring combination hemostat architectures; alternative pathways emphasizing purely mechanical solutions in cost-constrained European systems would alter the outlook. Forecasts reflect assumptions regarding EU MDR implementation pace, plasma sourcing stability, and laparoscopic technique diffusion rates. A model refresh is warranted upon material change in FDA guidance on human-derived tissue products or European notified body designation expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Special Purpose Needles Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Heavy Power Surgical Tools Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Global Hernia Repair Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
India General Surgical Devices Market