
 South Korea General Surgical Devices Market | 2026-2036
South Korea General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea General Surgical Devices Market Analytics
Ambulatory surgical centers is repositioning device procurement toward disposable-ready instrument sets and compact electrosurgical platforms. Medtronic PLC leverages its integrated energy portfolio to anchor hospital contracts across Seoul and Busan. B. Braun Melsungen AG sustains manufacturing scale through its regional distribution hub, while Stryker Corporation differentiates via specialized orthopedic handpiece lines tailored to Korean surgical preferences.
General surgical devices encompass manually operated and powered instruments—including scalpels, forceps, scissors, and suture devices—fabricated from medical-grade stainless steel, titanium alloys, or polymer composites, designed for tissue manipulation, incision, closure, and hemostasis during operative procedures. Electrosurgical and robotic surgical technologies command premium positioning as hospitals modernize operating suites, whereas manual surgical instruments retain volume dominance in cost-sensitive procurement tiers. Suture devices capture concentrated margin pools through absorbable polymer innovations, while orthopedic and cardiovascular applications drive replacement cycles amid aging demographics.
MFDS enforces Good Manufacturing Practice standards and post-market surveillance protocols that elevate barriers for non-compliant imports, while the Ministry of Health and Welfare shapes reimbursement ceilings that directly influence hospital purchasing committees. KHIDI promotes domestic medical technology development through targeted R&D subsidies, channeling capital toward indigenous manufacturers. Stakeholders must monitor reimbursement rate negotiations and MFDS predicate device pathways as decisive filters for market access and portfolio prioritization.
Market Dynamics
Hybrid operating theater construction across Seoul's tertiary hospital cluster is compressing procurement cycles for integrated surgical platforms while elevating technical specifications for device interoperability.
Growth Catalysts
- MFDS GMP alignment:Post-market surveillance protocols under MFDS are accelerating domestic manufacturer capability upgrades, narrowing quality gaps with imported systems.
- Ambulatory expansion:Day surgery centers in Gyeonggi Province are pulling compact electrosurgical units into high-volume outpatient settings.
- Absorbable polymer R&D:KHIDI subsidies are channeling capital toward indigenous suture innovation, reducing import dependency for advanced closure devices.
Market Restraints
- Titanium alloy cost volatility:Raw material price swings for surgical-grade metals are compressing margin pools in manual instrument manufacturing.
- Import concentration:Premium robotic surgical systems remain captive to single-source supply chains from North American and European OEMs.
- MFDS predicate pathway friction:Novel device categories lacking established predicates face extended regulatory review timelines.
Strategic Opportunities
- Busan-Ulsan corridor:Secondary metropolitan hospital networks outside Seoul remain underpenetrated for integrated energy platforms.
- Digital surgery convergence:Electrosurgical generators paired with real-time tissue feedback algorithms are opening premium positioning in hepatobiliary procedures.
- National Health Insurance alignment:Reimbursement code expansions for minimally invasive techniques are creating procurement pull-through for advanced instrumentation.
Industry Challenges
- Biomedical engineer scarcity:Operating theater integration specialists capable of calibrating hybrid suite configurations remain concentrated in Seoul.
- Legacy system interoperability:Retrofitting electrosurgical units into existing OR infrastructure requires customized interface development.
- MFDS quality system audit density:Annual surveillance inspections for Class IV devices consume substantial regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea General Surgical Devices Market |
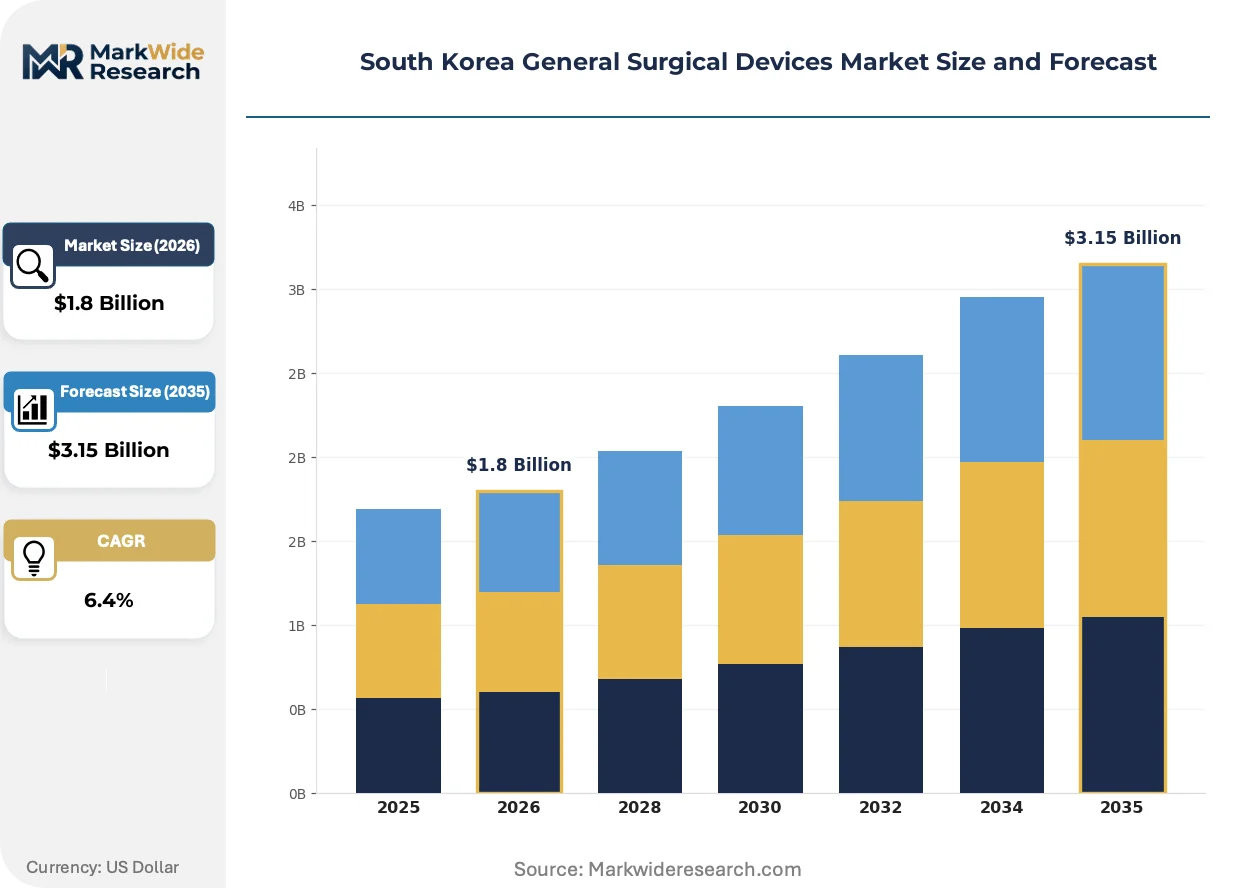
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Suture Devices End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Technology: Electrosurgical, Laser Surgical, Robotic Surgical, Manual Surgical Application: Orthopedic, Cardiovascular, Neurological, General Surgery |
| Companies Covered | B. Braun Melsungen AG, Conmed Corporation, Medtronic PLC, Olympus Corporation, Boston Scientific Corporation, Stryker Corporation, Getinge AB, Mediintech, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea General Surgical Devices Market Evolving Landscape
Device functionality is fragmenting across procedure-specific modules rather than consolidating into universal platforms, forcing manufacturers to recalibrate R&D roadmaps around surgical specialty depth.
Single-use polymer-composite instrument kits are decentralizing sterilization workflows from central supply departments to point-of-use disposal systems. Regional hospitals in Daegu and Daejeon are piloting these kits for laparoscopic cholecystectomy volumes exceeding 200 procedures monthly. This shift is compressing capital expenditure for autoclave infrastructure while elevating recurring consumable revenue streams for suppliers.
MFDS post-market surveillance amendments are tightening adverse event reporting windows from 30 days to 15 days for Class III and IV devices. Manufacturers must now deploy real-time complaint handling systems or risk license suspension. Orthopedic power tool suppliers are responding by embedding lot-traceable RFID tags into handpiece housings for automated field performance monitoring.
Hospital purchasing committees are unbundling after-sales service contracts from capital equipment pricing, treating maintenance as separately negotiable spend categories. This behavior is most pronounced in Seoul's university-affiliated hospitals where biomedical engineering departments have expanded in-house repair capabilities. Device vendors now compete on hourly service rates and spare parts availability rather than bundled warranty terms.
South Korea General Surgical Devices Market Segmentation
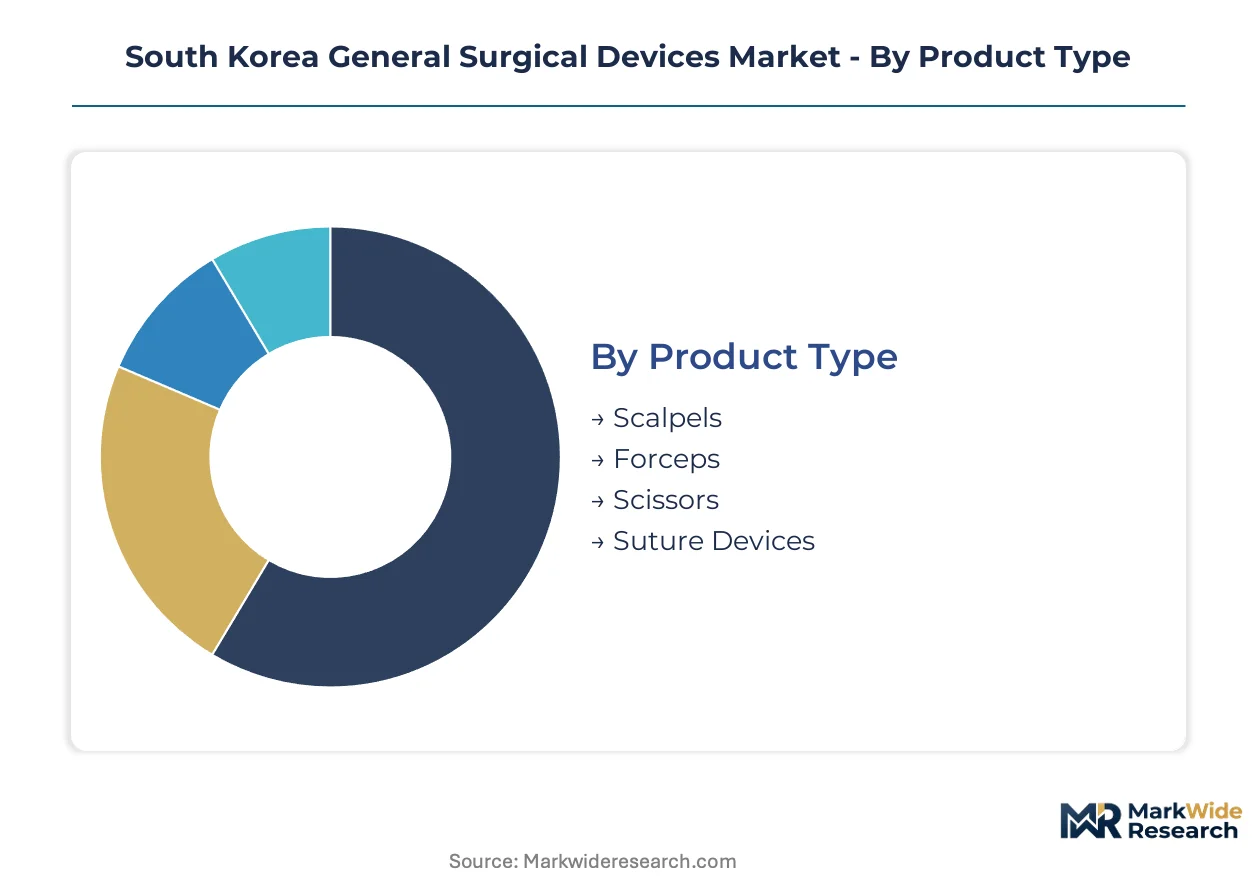
Device segmentation in South Korea reflects capital deployment patterns across Seoul's metropolitan hospital cluster and procurement hierarchies shaped by MFDS quality tiers. Understanding these divisions clarifies where procurement committees allocate budget versus where KHIDI subsidies redirect indigenous manufacturing investment.
Product Type:
Capital requirements vary sharply across this category, with electrosurgical platforms demanding substantial upfront investment while manual instruments require minimal fixed asset deployment.
- Scalpels:Medical-grade stainless steel and ceramic variants dominate tertiary hospital procurement. Seoul's university-affiliated hospitals are standardizing on safety-engineered designs with retractable blades to reduce sharps injuries in high-volume general surgery suites.
- Forceps:Titanium alloy and polymer-composite forceps command premium positioning in cardiovascular applications. Demand concentrates in Busan's secondary metropolitan networks where hybrid operating theater construction is elevating specifications for atraumatic tissue handling.
- Scissors:Tungsten carbide-edged instruments retain volume dominance across cost-sensitive procurement tiers.
- Suture Devices:Absorbable polymer innovations are reducing import dependency for advanced closure systems.
Suture devices absorb the bulk of installed capacity; scalpel safety-engineered variants are expanding most quickly.
End User:
Customer type determines purchasing committee composition and technical specification authority, with tertiary hospitals maintaining separate biomedical engineering departments absent in smaller facilities.
- Hospitals:Tertiary institutions in Seoul's metropolitan cluster drive procurement for integrated surgical platforms with interoperability requirements. MFDS Class IV device registrations concentrate here due to predicate pathway familiarity among regulatory affairs staff.
- Ambulatory Surgical Centers:Day surgery facilities in Gyeonggi Province are pulling compact electrosurgical units into high-volume outpatient settings. Disposable-ready instrument sets are displacing central sterilization workflows in centers exceeding 200 monthly laparoscopic procedures.
- Specialty Clinics:Orthopedic and ophthalmic focused facilities prioritize procedure-specific instrument modules over universal platforms.
- Research Laboratories:KHIDI-subsidized R&D facilities in Daedeok Innopolis are piloting next-generation suture materials and bioresorbable fixation devices.
Hospitals dominate current procurement volume; ambulatory surgical centers are gaining share fastest.
Technology:
Technology tier correlates directly with reimbursement ceiling alignment under the national health insurance system, creating procurement pull-through for minimally invasive techniques.
- Electrosurgical:Generators with real-time tissue feedback algorithms are opening premium positioning in hepatobiliary procedures. Seoul's tertiary hospitals are unbundling after-sales service contracts from capital equipment pricing for these systems.
- Manual Surgical:Stainless steel and titanium alloy instruments retain volume dominance in cost-sensitive procurement tiers. Raw material price volatility for surgical-grade metals is compressing margin pools in domestic manufacturing.
- Laser Surgical:Precision cutting applications in ophthalmology and dermatology maintain niche positioning.
- Robotic Surgical:Premium systems remain captive to single-source supply chains from North American and European OEMs, with MFDS predicate pathway friction extending review timelines for novel categories.
Manual surgical technology anchors current installed base; electrosurgical platforms are climbing the fastest.
Application:
Application segmentation tracks demographic pressure points, with aging population dynamics driving replacement cycles in orthopedic and cardiovascular segments.
- Orthopedic:Power tool suppliers are embedding lot-traceable RFID tags into handpiece housings to comply with MFDS post-market surveillance amendments. Daegu and Daejeon regional hospitals are piloting single-use polymer-composite instrument kits for high-volume joint procedures.
- Cardiovascular:Minimally invasive valve repair and coronary bypass techniques are elevating demand for precision suturing systems. Reimbursement code expansions are creating procurement pull-through for advanced instrumentation in Seoul's cardiovascular specialty centers.
- Neurological:Microsurgical instrument requirements command specialized manufacturing capabilities concentrated among premium European suppliers.
- General Surgery:Laparoscopic cholecystectomy and appendectomy volumes sustain baseline demand for standard instrument sets across all facility tiers.
General surgery maintains broadest installed capacity; orthopedic applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area's designation as a free economic zone for medical technology accelerates device manufacturing concentration. Tax incentives channel foreign direct investment toward electrosurgical platform assembly. Gyeonggi Province's satellite cities absorb overflow production capacity from the capital cluster.
Seoul Capital Area
Hybrid operating theater construction at Severance Hospital and Samsung Medical Center drives procurement for integrated surgical platforms. MFDS Class IV device registrations concentrate here due to regulatory affairs expertise density. Gangnam-gu's medical device corridor hosts service centers for robotic surgical system calibration.
Busan-Ulsan
Secondary metropolitan hospital networks expand cardiovascular procedure volumes. The Ministry of Health and Welfare's regional reimbursement rate harmonization reduces pricing friction for advanced instrumentation. Ulsan's industrial port infrastructure supports titanium alloy raw material importation for domestic instrument fabrication.
Daegu-Gyeongbuk
Regional hospitals pilot single-use polymer-composite instrument kits for high-volume laparoscopic procedures. KHIDI's Daegu satellite office channels R&D subsidies toward indigenous suture material development. Kyungpook National University Hospital anchors specialty training for electrosurgical platform operation.
Daejeon-Sejong
Daedeok Innopolis research laboratories prototype next-generation bioresorbable fixation devices. The national government's administrative relocation to Sejong creates demand for ambulatory surgical center infrastructure. KAIST-affiliated startups commercialize real-time tissue feedback algorithms for hepatobiliary applications.
Gwangju-Honam
Underpenetrated orthopedic procedure markets present expansion targets for power tool suppliers. Honam University's medical school trains biomedical engineers for regional hospital biomedical departments. Naju's medical device industrial complex offers manufacturing cost advantages below Seoul wage benchmarks.
South Korea General Surgical Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy platform vendors commanding premium positioning against domestic assembly operations. The vendor base concentrates around three tiers: multinational OEMs with full regulatory compliance infrastructure, regional distributors with localized service networks, and domestic manufacturers leveraging KHIDI subsidies for R&D acceleration. Strategic moves center on unbundling after-sales service contracts from capital equipment pricing and embedding traceability technologies to satisfy MFDS post-market surveillance amendments.
Among Germany-based surgical device conglomerates, B. Braun Melsungen AG and Getinge AB exemplify the integrated supply chain archetype, combining manufacturing scale with regional distribution hub deployment. Medtronic PLC, as an Ireland-headquartered multinational, occupies a position representing the premium-tier electrosurgical and robotic platform specialist. These three entities anchor the competitive structure through their respective archetype dominance rather than direct segment overlap.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Conmed Corporation |
| Medtronic PLC |
| Olympus Corporation |
| Boston Scientific Corporation |
| Stryker Corporation |
| Getinge AB |
| Mediintech |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Titanium alloy spot prices on the London Metal Exchange cascade through South Korean surgical instrument manufacturing, compressing margin pools for domestic producers while amplifying procurement premiums for hospitals demanding accelerated delivery timelines. This raw material volatility stratifies pricing across MFDS-certified tiers, with Seoul's tertiary institutions absorbing cost pass-throughs more readily than regional facilities in Daegu or Gwangju.
Pricing Analysis
Expedited lead-time premiums command fifteen to twenty percent markups over standard delivery windows for electrosurgical generators and robotic surgical platforms. Pricing stratifies across premium, standard, and economy tiers based on MFDS device classification and after-sales service bundling. Cost compression in manual instrument manufacturing intensifies as titanium alloy and medical-grade stainless steel inputs fluctuate. Ambulatory surgical centers in Gyeonggi Province exhibit highest price sensitivity, while Seoul's university-affiliated hospitals prioritize interoperability specifications over unit cost.
Supply Chain Analysis
Titanium alloy feedstock rests on Japanese and Chinese specialty metal producers, with South Korean domestic smelters capturing limited upstream share. Surgical-grade polymer composites and tungsten carbide cutting edges draw from German and US precision component manufacturers. Single-source vulnerability concentrates in robotic surgical system supply chains tethered to North American and European OEMs. Distribution runs through regional distribution hubs in Seoul and Busan, with B. Braun and Medtronic maintaining captive logistics networks for Class III and IV device categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's general surgical devices sector sits in a technology-transition phase, with single-use polymer-composite instrument kits displacing central sterilization workflows and real-time tissue feedback algorithms repositioning electrosurgical platform value propositions.
For Market Incumbents: Acquire biomedical engineering talent pools concentrated in Seoul's university-affiliated hospital clusters to defend service contract profitability against unbundling trends. Deepen backward integration into titanium alloy processing capabilities to offset raw material volatility compressing manual instrument margins. Prioritize MFDS Class IV predicate pathway expertise as regulatory affairs bandwidth becomes a scarce competitive moat. For New Entrants and Emerging Players: Digital distribution channels through GPO procurement platforms offer lower-friction entry points than direct hospital sales forces. Target Busan-Ulsan corridor secondary metropolitan networks where integrated energy platform penetration lags Seoul benchmarks. Pursue KHIDI R&D subsidy alignment for indigenous suture material development, leveraging Daedeok Innopolis laboratory partnerships for technology validation. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic manufacturers with captive MFDS quality system infrastructure in Gyeonggi Province satellite cities. Five-to-ten year viability hinges on reimbursement code expansion sustainability under National Health Insurance alignment. Watch MFDS post-market surveillance amendment enforcement density as inflection indicator for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Class IV Predicate Pathway Investment | Accelerates market access for novel electrosurgical platforms in Seoul's tertiary hospital cluster. |
| Single-Use Polymer-Composite Kit Manufacturing Scale-Up | Captures recurring consumable revenue streams displacing central sterilization infrastructure. |
| Real-Time Tissue Feedback Algorithm Development | Opens premium positioning in hepatobiliary procedures at Samsung Medical Center and Severance Hospital. |
| Busan-Ulsan Corridor Distribution Hub Deployment | Reduces logistics friction for secondary metropolitan hospital networks underpenetrated for integrated platforms. |
| KHIDI R&D Subsidy Alignment for Indigenous Suture Innovation | Channels capital toward absorbable polymer development reducing import dependency for advanced closure devices. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and MFDS regulatory affairs specialists. Hospital procurement databases, KHIDI subsidy disbursement records, and National Health Insurance reimbursement code filings provided demand-side validation. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure allocations across the analysis window.
Data-stream reconciliation integrated electrosurgical platform installation records, manual instrument import manifests, and robotic surgical system service contract registrations. Segmentation dimensions modeled include product type, end-user facility tier, technology tier, and application specialty across the projection horizon. CAGRs derived from procedure volume trajectories, capital expenditure patterns in hybrid operating theater construction, and reimbursement alignment dynamics for minimally invasive techniques.
Inputs from MFDS adverse event reporting systems and KHIDI R&D disbursement databases were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around quarterly estimates. Forecasts reflect assumptions regarding MFDS predicate pathway review timelines, titanium alloy price trajectory stability, and National Health Insurance reimbursement code expansion continuity. A small set of triggers—MFDS quality system audit density escalation, major titanium supply disruption, or reimbursement harmonization policy reversal—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Disposable Surgical Devices Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Homecare Surgical Drains Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Global Surgical Case Carts Market
Surgical Instruments
Heavy Power Surgical Tools Market
Surgical Instruments
Surgical Visualization Market