
 Open Angle Glaucoma Market | 2026-2036
Open Angle Glaucoma Market Size, Share, and Industry Trends Forecast 2026-2036
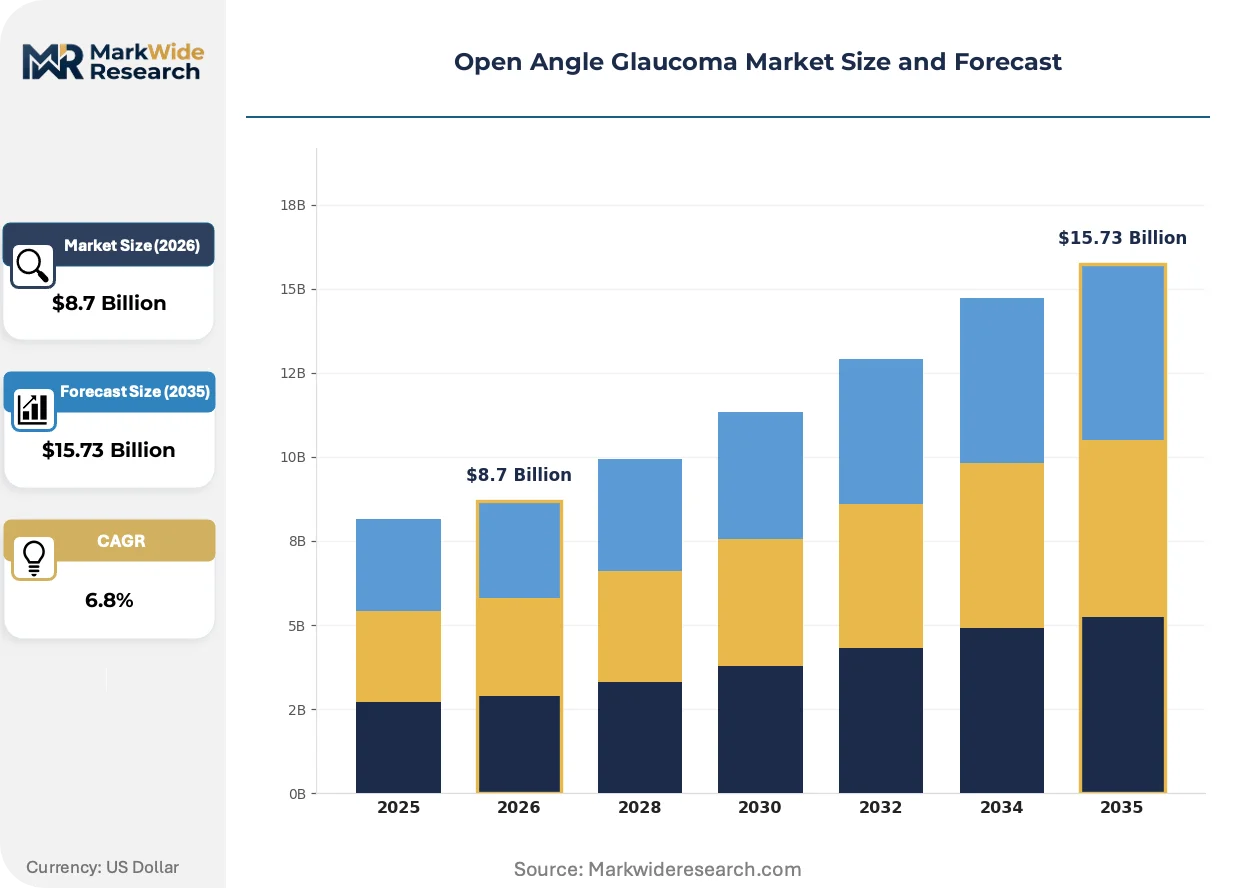
Open Angle Glaucoma Market Outlook
North American pharmaceutical manufacturing is consolidating around ophthalmic specialty capacity. Pfizer Inc. leverages its established glaucoma portfolio across hospital and clinic channels. Merck & Co. Inc. sustains competitive presence through beta blocker formulations with proven efficacy profiles. Alcon Inc. dominates surgical segment supply with integrated device and pharmaceutical offerings for filtration procedures.
Open angle glaucoma denotes a progressive optic neuropathy characterized by elevated intraocular pressure with an open anterior chamber angle, requiring sustained pressure reduction to preserve retinal ganglion cells and visual field integrity. Prostaglandin analogues anchor first-line therapy due to superior efficacy and once-daily dosing convenience, while the surgical delivery method represents the fastest-expanding margin pool as micro-invasive stent technologies displace conventional trabeculectomy. Ophthalmology clinics concentrate procedural volume and drive adoption of combination therapies across adult and geriatric patient cohorts.
FDA oversight governs new drug approvals and device clearances for intraocular pressure-lowering therapies, while EMA standards shape parallel development pathways for European market access. The EU MDR intensifies clinical evidence requirements for sustained-release implants and surgical micro-stents. Stakeholders must monitor reimbursement policy evolution for minimally invasive glaucoma surgery across Medicare and private payer frameworks to align portfolio investments with shifting site-of-care economics.
Market Dynamics
Sustained-release drug delivery systems are compressing dosing frequency requirements and reshaping competitive positioning between pharmaceutical and surgical intervention categories. FDA premarket approval pathways for implantable devices have intensified clinical evidence demands, filtering market entrants toward integrated platform strategies.
Growth Catalysts
- EU MDR compliance frameworks:Stricter clinical evidence requirements for sustained-release implants are accelerating consolidation around established manufacturers with robust regulatory affairs capabilities.
- Ophthalmology clinic networks:Ambulatory surgical centers concentrate procedural volume and drive standardization of micro-invasive stent protocols across metropolitan markets.
- Prostaglandin analogue formulations:Once-daily dosing convenience anchors patient adherence and preserves first-line therapy positioning against surgical alternatives.
Market Restraints
- Specialized surgical training requirements:Micro-invasive glaucoma surgery demands fellowship-level expertise, constraining addressable procedural volume to academic medical centers and high-volume private practices.
- Reimbursement uncertainty:Medicare contractor variability in minimally invasive glaucoma surgery coverage creates site-of-care arbitrage risks for capital equipment investments.
- Generic prostaglandin penetration:Patent expirations on latanoprost and bimatoprost formulations compress branded pharmaceutical margins and redirect R&D toward device-drug combinations.
Strategic Opportunities
- Combination therapy platforms:Fixed-dose prostaglandin-beta blocker formulations address polypharmacy burden in refractory patient cohorts.
- Telemedicine-enabled monitoring:Remote intraocular pressure tracking via home tonometry devices expands reach into rural and underserved urban corridors.
- Sustained-release anterior segment implants:Biodegradable drug-eluting devices reduce administration burden for elderly populations with caregiver dependency.
Industry Challenges
- Retinal ganglion cell preservation endpoints:Regulatory acceptance of surrogate markers for visual field progression remains inconsistent across FDA and EMA review divisions.
- Supply chain sterilization capacity:Ethylene oxide processing constraints for silicone stent components create batch release bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open Angle Glaucoma Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prostaglandin Analogues, Beta Blockers, Alpha Agonists, Carbonic Anhydrase Inhibitors Delivery Method: Topical, Oral, Injectable, Surgical End User: Ophthalmology Clinics, Hospitals, Homecare Settings, Research Institutes Age Group: Pediatric, Adult, Geriatric, Others |
| Companies Covered | Pfizer Inc., Merck & Co. Inc., AbbVie Inc., Novartis AG, Alcon Inc., Bausch Health Companies Inc., Aerie Pharmaceuticals Inc., Glaukos Corporation, Santen Pharmaceutical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open Angle Glaucoma Market Strategic Shifts
Product development trajectories are converging on patient adherence solutions and procedural efficiency gains. Technology investments prioritize reducing treatment burden while preserving therapeutic efficacy across diverse demographic cohorts.
Micro-invasive stent technologies are overtaking conventional trabeculectomy in surgical volume across United States ophthalmology clinics. Surgeons at ambulatory surgical centers adopt single-use delivery systems that compress operative time and reduce postoperative monitoring requirements. This shift is enabling same-day discharge protocols and expanding addressable patient populations beyond academic referral networks.
FDA sustained-release drug delivery guidance documents have tightened bioequivalence standards for implantable ocular devices. Manufacturers must now demonstrate 90-day stability data and terminal sterilization validation prior to premarket submission. Ophthalmic specialty divisions within larger pharmaceutical portfolios are responding by acquiring device platform capabilities rather than developing internally.
Patient self-monitoring behaviors are reshaping chronic disease management expectations in glaucoma care. Home tonometry devices and smartphone-based visual field screening applications are displacing clinic-dependent follow-up schedules for stable patients. United States Medicare Advantage plans are piloting remote monitoring reimbursement codes, creating precedent for value-based contracting in ophthalmology service lines.
Open Angle Glaucoma Market Segmentation
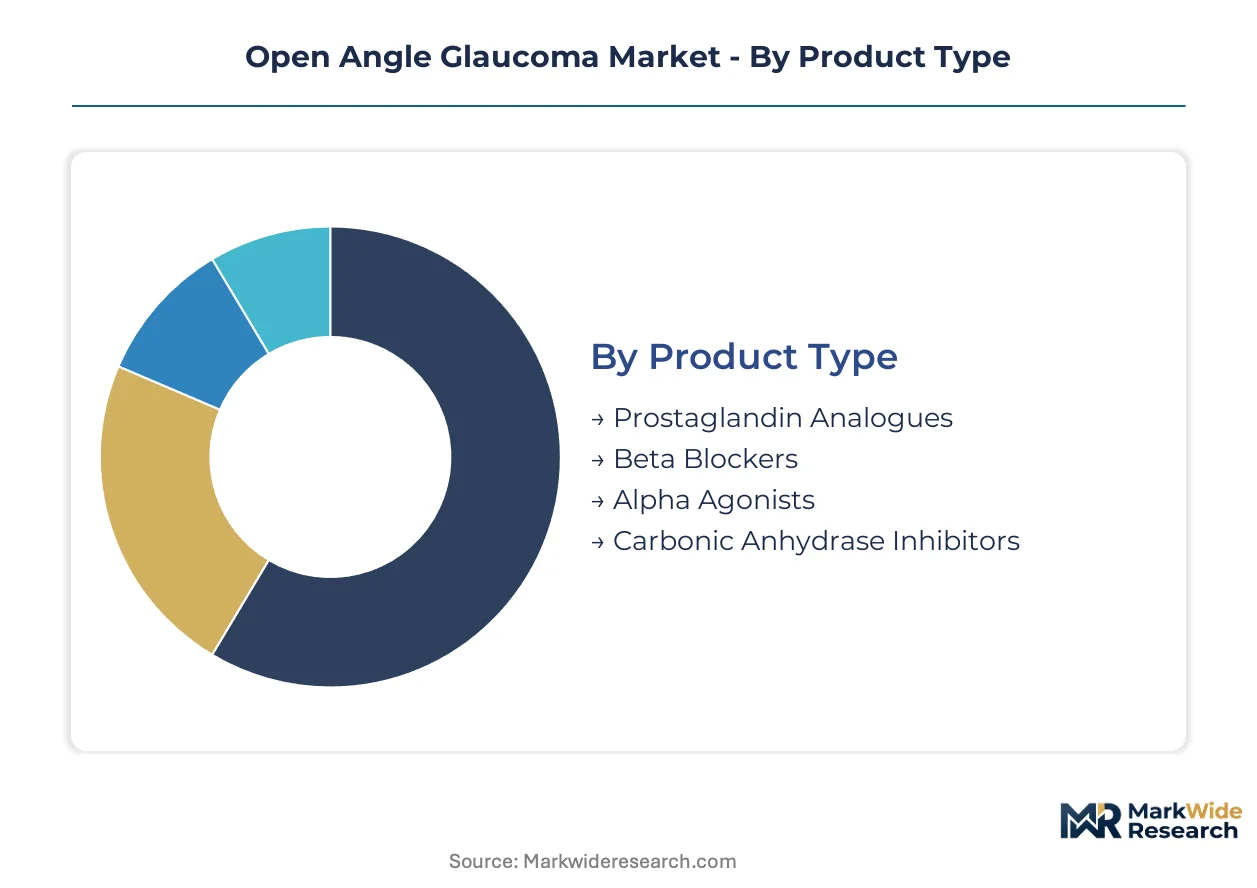
Open angle glaucoma treatment selection hinges on disease stage, patient compliance capacity, and surgical candidacy. Segmentation reveals where pharmaceutical maintenance yields to procedural intervention, and which patient demographics drive volume concentration versus premium pricing.
Product Type:
Volume anchors in prostaglandin analogues due to once-daily dosing adherence advantages, while premium capture concentrates in combination formulations addressing refractory cases.
- Prostaglandin Analogues:Latanoprost and bimatoprost derivatives enhance uveoscleral outflow through FP receptor agonism. Demand concentrates in United States Medicare Part D formularies where generic penetration has compressed unit pricing but expanded prescription volume.
- Beta Blockers:Timolol and carteolol formulations reduce aqueous humor production via non-selective beta-adrenergic blockade. Ophthalmology clinics in Germany and Japan sustain prescribing volume for patients with contraindications to prostaglandin therapy.
- Alpha Agonists:Brimonidine tartrate offers dual mechanism outflow enhancement and production suppression for combination regimens.
- Carbonic Anhydrase Inhibitors:Dorzolamide and brinzolamide serve as adjunctive therapy for insufficient monotherapy response.
Today's leader: Prostaglandin Analogues. Tomorrow's challenger: fixed-dose combinations spanning Beta Blockers with Alpha Agonists.
Delivery Method:
Application site determines reimbursement coding complexity and patient adherence economics across ambulatory and institutional settings.
- Topical:Eye drop formulations dominate prescription volume through self-administration convenience and pharmacy distribution accessibility. United States ophthalmology clinics drive 90-day supply protocols for stable patients.
- Surgical:Micro-invasive stent implantation and trabeculectomy procedures command premium reimbursement within ambulatory surgical center fee schedules. United States metropolitan markets concentrate procedural volume where fellowship-trained surgeons maintain active practices.
- Injectable:Intravitreal and periocular depot formulations address compliance failure in caregiver-dependent populations.
- Oral:Systemic carbonic anhydrase inhibitors retain niche indication for acute pressure spikes and preoperative preparation.
Topical administration retains volume dominance. Surgical delivery climbs fastest as MIGS protocols displace conventional filtration surgery.
End User:
Site-of-care economics fragment procurement authority between integrated health systems and independent specialty practices.
- Ophthalmology Clinics:Independent and multispecialty group practices concentrate glaucoma management volume through dedicated diagnostic equipment and surgical scheduling capacity. United States private equity-backed clinic rollups standardize formularies across metropolitan networks.
- Hospitals:Academic medical centers and community hospitals manage complex cases requiring combined cataract-glaucoma procedures or resident training involvement.
- Homecare Settings:Visiting nurse services support medication administration for homebound geriatric patients with functional limitations.
- Research Institutes:Clinical trial sites and academic laboratories drive investigational product demand for novel mechanism evaluation.
Ophthalmology clinics command procedural margin. Hospital systems capture complex case referral.
Age Group:
Disease prevalence and treatment tolerance diverge sharply across developmental stages, shaping formulation selection and monitoring intensity.
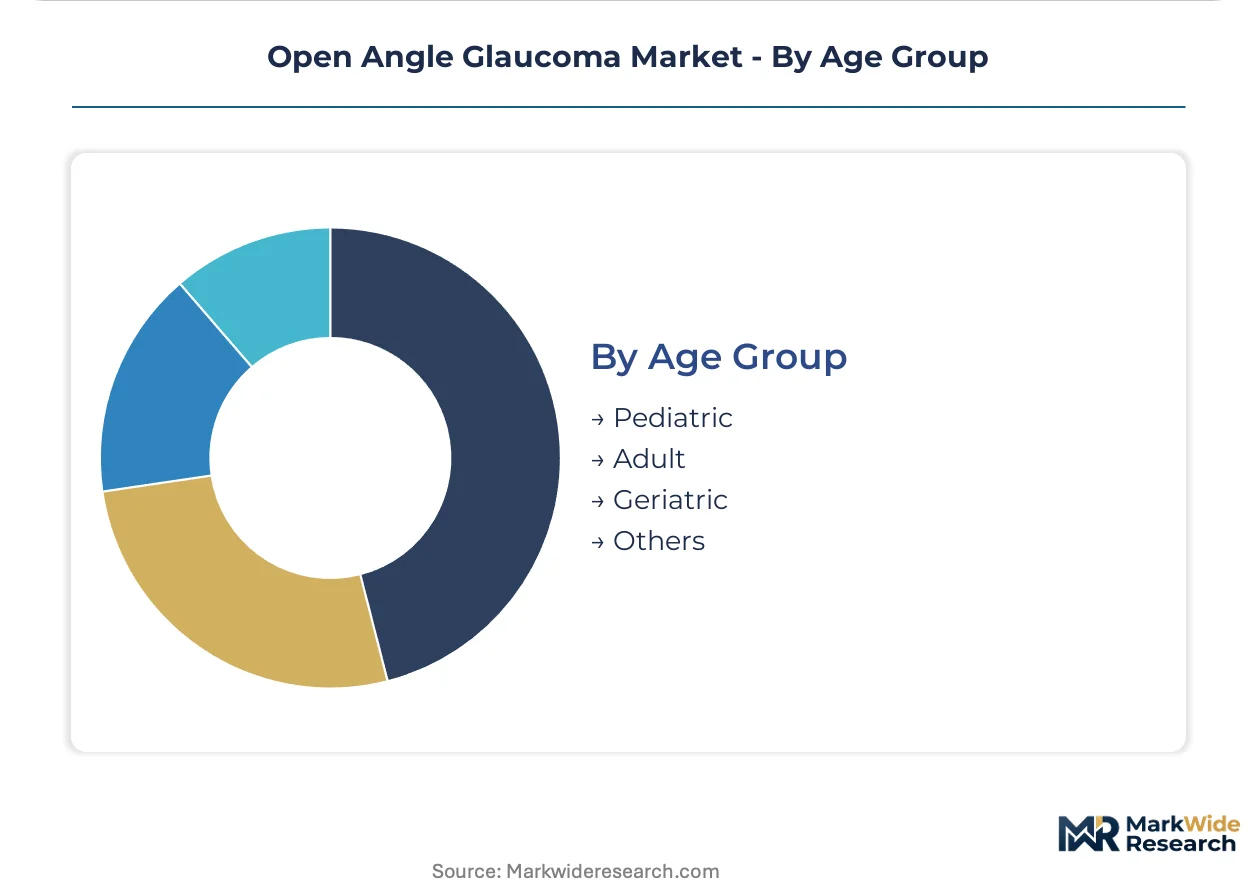
- Geriatric:Patients over 65 years constitute the dominant addressable population with elevated primary open angle glaucoma prevalence and polypharmacy complexity. United States Medicare fee-for-service and Advantage plans drive reimbursement policy for this cohort.
- Adult:Working-age patients between 18 and 64 prioritize preserved visual field for occupational licensing requirements and driving privilege maintenance.
- Pediatric:Juvenile open angle glaucoma and secondary forms require specialized surgical intervention due to medication compliance challenges in developmental populations.
- Others:Pregnancy-related and steroid-induced secondary glaucomas demand temporary management protocols.
Geriatric patients generate volume concentration. Adult segments sustain premium pricing for preservative-free and combination formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting ophthalmic device manufacturing toward jurisdictions with streamlined clinical trial frameworks and favorable reimbursement negotiation environments. Production capacity is clustering where FDA premarket approval pathways intersect with Medicare reimbursement certainty.
United States
Medicare Advantage expansion and aging demographic concentration drive procedural volume in metropolitan ophthalmology networks. FDA sustained-release drug delivery guidance shapes premarket submission requirements for implantable devices. The Boston-Cambridge corridor anchors glaucoma device R&D clusters where venture-backed startups partner with academic medical centers.
Germany
Statutory health insurance reimbursement stability supports adoption of micro-invasive surgical techniques in ambulatory settings. EU MDR compliance requirements for sustained-release implants filter market entrants toward established manufacturers with robust quality management systems. The Rhine-Main region concentrates ophthalmic surgical training centers that standardize MIGS protocols across Central European markets.
Japan
PMDA consultation pathways for combination device-drug products accelerate commercialization timelines for novel delivery platforms. National health insurance price listing revisions every two years create predictable reimbursement windows for innovative therapies. The Kanto region hosts specialized ophthalmology clinics that drive adoption of preservative-free prostaglandin formulations.
Switzerland
Swissmedic parallel review procedures with EMA reduce regulatory duplication for sustained-release implants seeking European market access. Premium pricing tolerance for innovative therapies supports orphan indication development in refractory glaucoma subtypes. The Basel-Zurich corridor concentrates pharmaceutical manufacturing infrastructure with integrated device assembly capabilities.
India
CDSCO accelerated approval pathways for medical devices with predicate approvals in regulated markets attract multinational manufacturing investments. Government Production Linked Incentive schemes for pharmaceuticals extend to active pharmaceutical ingredient synthesis for prostaglandin analogues. The Hyderabad-Bengaluru corridor hosts contract research organizations conducting bioequivalence studies for generic ophthalmic formulations.
Open Angle Glaucoma Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue sustained-release implant and surgical micro-stent segments. The market exhibits moderate consolidation with tiered positioning across pharmaceutical maintenance therapy and procedural intervention categories. Three archetypes dominate: integrated ophthalmic specialty divisions within diversified pharmaceuticals, pure-play surgical device manufacturers, and generic formulation specialists. Competitive moves center on portfolio diversification into combination therapies and strategic partnerships to access ambulatory surgical center distribution channels.
Among diversified pharmaceutical incumbents, Pfizer Inc. and Merck & Co. Inc. exemplify the integrated portfolio archetype spanning hospital and clinic channels. Alcon Inc. occupies a position representing surgical segment supply with integrated device and pharmaceutical offerings. These three entities anchor competitive dynamics through established regulatory affairs capabilities and reimbursement infrastructure access.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Novartis AG |
| Alcon Inc. |
| Bausch Health Companies Inc. |
| Aerie Pharmaceuticals Inc. |
| Glaukos Corporation |
| Santen Pharmaceutical Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Branded prostaglandin analogue and generic formulation divergence manifests in starkly different margin structures and supply chain configurations. Premium-originator formulations command pharmacy reimbursement through FDA-approved labeling advantages, while generic manufacturers anchor procurement in India and China API sourcing with compressed distribution layers.
Pricing Analysis
Distributor margins absorb the primary pricing tension between originator and generic tiers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA approval status and preservative-free certification. Price differentiation hinges on formulation complexity and Medicare Part D formulary positioning. Pricing pressure stems from latanoprost patent expiration cascades redirecting volume toward Indian API-sourced alternatives. Ambulatory surgical centers exhibit lowest price sensitivity for MIGS devices, while retail pharmacy channels face intense generic substitution economics.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume prostaglandin demand through GPO-negotiated contracts. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, with silicone stent component manufacturing anchored in Germany and the United States. Supply chain vulnerability rests on ethylene oxide sterilization capacity constraints for implantable devices. Distribution runs through ophthalmology clinic networks and ambulatory surgical center procurement committees with divergent technical specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA sustained-release drug delivery guidance operates as a regulatory compounder, intensifying clinical evidence requirements that filter development programs toward capital-rich incumbents and reshape competitive entry economics.
For Market Incumbents: Extend device platform capabilities through acquisition rather than internal development to compress premarket approval timelines. Consolidate ambulatory surgical center distribution relationships before MIGS reimbursement codes stabilize. Vertical integration into silicone component molding addresses ethylene oxide sterilization bottlenecks threatening batch release schedules. For New Entrants and Emerging Players: Rural ophthalmology clinics with limited fellowship-trained surgeon access represent the most penetrable buyer archetype for telemedicine-enabled monitoring solutions. Target caregiver-dependent geriatric populations with biodegradable implant formulations addressing adherence failure. Pursue Swissmedic parallel review pathways to leverage EMA clinical data for accelerated European market entry. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed standalone revenue bases for sustained-release implant developers. Five-to-ten year viability favors platform companies with integrated pharmaceutical-device portfolios over single-mechanism drug developers. Monitor Medicare contractor variability in MIGS coverage as the critical inflection signal for surgical segment capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Implantable device submissions require 90-day stability data and terminal sterilization validation per FDA guidance. |
| EU MDR Compliance Investment | Stricter clinical evidence requirements for sustained-release implants filter entrants toward established quality systems. |
| Ambulatory Surgical Center Partnership | Same-day discharge protocols expand addressable volume beyond academic referral networks. |
| Biodegradable Implant Development | Drug-eluting devices reduce administration burden for elderly populations with polypharmacy complexity. |
| Telemedicine Reimbursement Strategy | Medicare Advantage pilot codes for home tonometry create precedent for value-based ophthalmology contracting. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's regulatory and reimbursement stakeholders. Drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided qualitative inputs through structured interviews. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Granularity-level modeling distinguished prostaglandin analogues, beta blockers, alpha agonists, and carbonic anhydrase inhibitors by delivery method and end-user site-of-care. Patient population segmentation by age cohort and disease stage informed demand projection across the analysis window. CAGRs were derived from procedure volume trends, generic penetration curves, and MIGS adoption rates. Reimbursement policy evolution and EU MDR implementation timelines served as critical forecast inputs.
Underlying measurement precision varies by segment; surgical delivery method estimates carry tighter precision than emerging sustained-release implant categories. Forecasts reflect assumptions regarding Medicare Advantage expansion, EU MDR enforcement consistency, and prostaglandin generic substitution velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Global Autoimmune Disease Therapeutics Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market