
 Surgical Tubing Market | 2026-2036
Surgical Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Tubing Market Intelligence
Aftermarket service revenue for catheter system maintenance is reshaping margin distribution across the surgical tubing value chain. Saint-Gobain Performance Plastics leverages its fluoropolymer expertise to dominate high-performance catheter liner supply. Zeus Industrial Products anchors North American demand through precision extrusion capabilities for neurovascular applications. RAUMEDIC AG competes on pharmaceutical-grade silicone tubing with integrated cleanroom manufacturing in Germany.
Surgical tubing comprises hollow cylindrical conduits manufactured from elastomeric or thermoplastic polymers, typically extruded to inner diameters ranging from 0.005 to 0.5 inches with wall thickness tolerances of ±0.0005 inches, designed to transport fluids, gases, or mechanical actuation in sterile clinical environments. Silicone tubing leads product type revenue due to its biocompatibility profile and autoclavability, while polyurethane tubing represents the fastest-expanding category driven by its tensile strength advantages in minimally invasive catheter systems. Medical grade material specifications command premium positioning over industrial and food grades, with pharmaceutical grade requirements tightening further for drug delivery applications.
The FDA enforces biocompatibility standards under ISO 10993 for implantable tubing durations exceeding thirty days, while the EU MDR mandates enhanced clinical evidence for Class III device incorporation, and the EPA regulates phthalate content in PVC formulations through TSCA Section 6 restrictions. These frameworks compel manufacturers to maintain dual regulatory dossiers and accelerate migration toward phthalate-free polymer alternatives. Stakeholders must monitor evolving FDA guidance on nitrosamine impurities in rubber-based tubing and prepare supply chain disclosures ahead of full EU CSRD implementation.
Market Dynamics
FDA biocompatibility testing escalation for long-term implantables is compressing supplier qualification timelines while hospital procurement consolidation favors manufacturers with captive resin-to-tubing production control.
Growth Catalysts
- Ambulatory Surgery Center Expansion:Catheterization procedure migration from inpatient settings to ASCs in the United States is expanding addressable tubing volumes for minimally invasive applications.
- EU MDR Implementation:Enhanced clinical evidence requirements for Class III device incorporation are elevating barriers for non-specialized suppliers and concentrating demand on certified manufacturers.
- Silicone Autoclavability:Reprocessing economics in cost-constrained hospital systems favor tubing materials that withstand repeated sterilization cycles without degradation.
Market Restraints
- Medical-Grade Silicone Feedstock Concentration:Pharmaceutical-grade silicone raw material supply concentrates among a limited pool of chemical producers, exposing converters to input cost volatility and allocation risk.
- Phthalate Substitution Timeline:EPA TSCA Section 6 restrictions on PVC plasticizers compel reformulation investments while performance-equivalent alternatives remain commercially immature for certain compliance profiles.
- ISO 10993 Testing Burden:Extended biocompatibility evaluation protocols for implantable durations exceeding thirty days elongate product development cycles and freeze working capital in pre-revenue inventory.
Strategic Opportunities
- Neurovascular Application Expansion:Precision extrusion capabilities for micro-diameter tubing in stroke intervention devices open premium positioning beyond commoditized cardiovascular segments.
- EU CSRD Supply Chain Disclosure:Early preparation for corporate sustainability reporting requirements creates competitive differentiation for manufacturers with transparent polymer sourcing and carbon footprint documentation.
- Drug-Device Convergence:Pharmaceutical-grade tubing specifications for combination products command margin expansion as biologics delivery systems integrate tubing as a functional component rather than commodity input.
Industry Challenges
- Cleanroom Manufacturing Scale-Up:ISO Class 7 and Class 8 certified production capacity expansion requires capital deployment with extended depreciation timelines and utilization risk.
- Nitrosamine Impurity Monitoring:Evolving FDA guidance on rubber-based tubing contaminants demands analytical capability investments and supply chain requalification without finalized compliance thresholds.
- Precision Extrusion Talent Scarcity:Tight tolerance manufacturing expertise for sub-0.010 inch inner diameter tubing concentrates among aging specialist workforces with limited apprenticeship pipeline replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Tubing Market |
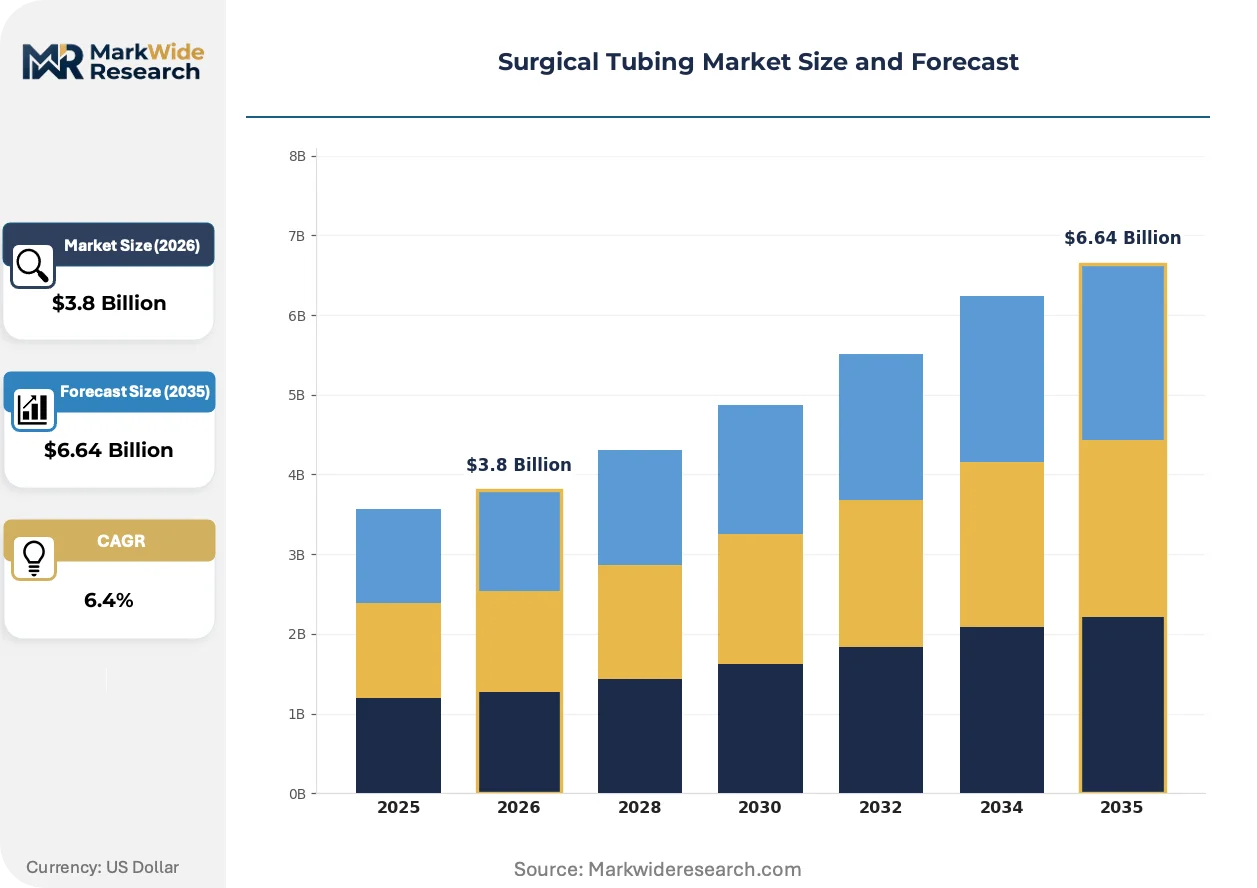
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Tubing, PVC Tubing, Polyurethane Tubing, Latex Tubing, Thermoplastic Elastomer Tubing Material Grade: Medical Grade, Industrial Grade, Food Grade, Pharmaceutical Grade Application: Catheterization, Drainage, Fluid Transfer, Peristaltic Pumping, Respiratory Devices End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Home Care Providers |
| Companies Covered | Saint-Gobain Performance Plastics, Teleflex, Zeus Industrial Products, RAUMEDIC AG, Tekni-Plex, W. L. Gore & Associates, Kent Elastomer Products, Freudenberg Medical, MicroLumen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Tubing Market Strategic Shifts & Innovations
Material science convergence with regulatory science is compressing product development paradigms while digital manufacturing integration redefines quality assurance economics across sterile tubing supply chains.
Multi-layer co-extrusion technology is hybridizing fluoropolymer barrier properties with elastomeric flexibility in catheter liner construction. Neurovascular device manufacturers are adopting these constructions at accelerated qualification paces. This hybridizing architecture is collapsing the historical trade-off between chemical resistance and mechanical compliance that previously forced discrete material selection.
EU MDR technical documentation requirements are mandating clinical performance evidence for tubing incorporated into permanent implant devices. Manufacturers are restructuring quality management systems to maintain parallel regulatory dossiers. Class III cardiovascular applications face the steepest compliance cost escalation, prompting portfolio rationalization toward higher-margin specialty segments.
Hospital procurement consolidation is compressing supplier bases toward vertically integrated manufacturers with resin compounding through finished tubing capabilities. Group purchasing organizations are awarding multi-year contracts contingent on documented supply security and regulatory file ownership. This concentration is most visible in United States health system networks where standardization incentives override historical multi-sourcing preferences.
Surgical Tubing Market Segmentation
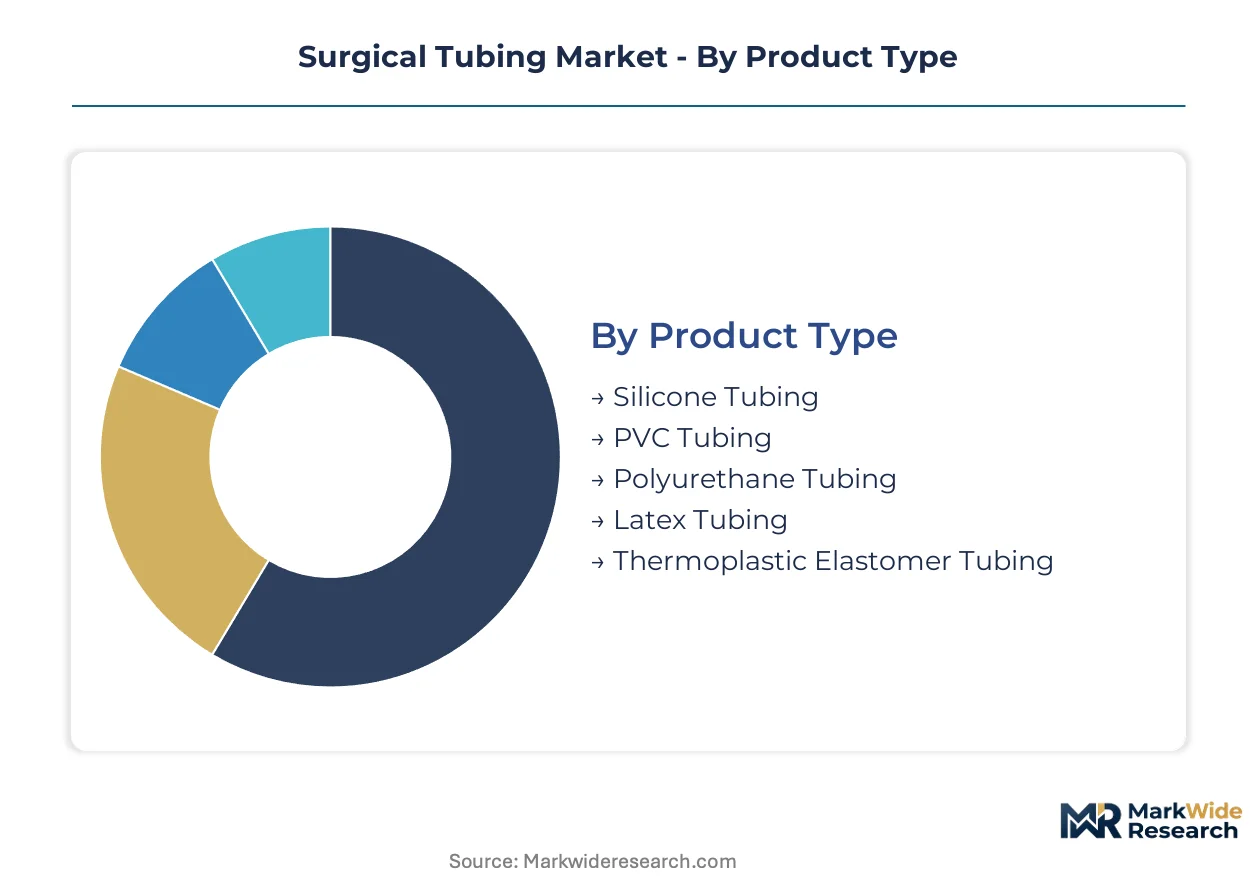
Surgical tubing segmentation reflects divergent technical requirements across sterile fluid management, implantable device integration, and single-use disposables. Material specifications and regulatory classifications create tiered pricing architectures that reshape supplier competitive positioning. End-user concentration in consolidated hospital networks versus fragmented home care channels determines go-to-market economics for manufacturers.
Product Type:
Mature silicone formulations dominate established catheter applications while polyurethane compounds capture emerging minimally invasive segments demanding higher tensile performance.
- Silicone Tubing:Elastomeric polydimethylsiloxane formulations deliver biocompatibility profiles and autoclavability for repeated sterilization cycles. Demand concentrates in United States hospital systems where reprocessing economics favor durable materials over single-use alternatives.
- Polyurethane Tubing:Segmented polyether-urethane constructions provide superior abrasion resistance and kink recovery for neurovascular catheter navigation. German and Japanese device manufacturers are expanding procurement of these high-performance specifications for stroke intervention platforms.
- PVC Tubing:Plasticized polyvinyl chloride remains cost-dominant for drainage and fluid transfer applications where implantation duration stays below thirty days.
- Latex Tubing:Natural rubber latex persists in peristaltic pumping mechanisms requiring exceptional elastic memory and fatigue resistance.
- Thermoplastic Elastomer Tubing:SEBS and TPO compounds bridge silicone flexibility with thermoplastic processability for rapid-cycle injection molding of disposable components.
Silicone tubing retains volume leadership; polyurethane tubing holds the steepest expansion curve.
Material Grade:
Cost tier stratification separates commodity industrial specifications from pharmaceutical-grade certifications commanding substantial price premiums and extended qualification timelines.
- Medical Grade:ISO 10993-tested polymers meet biocompatibility thresholds for patient contact under thirty days. United States ASC networks standardize on these specifications for cost-controlled outpatient catheterization.
- Pharmaceutical Grade:USP Class VI and EP 3.1.9 compliant materials with documented extractables profiles support drug-device combination products. EU MDR technical documentation requirements are elevating procurement concentration on certified European converters with integrated cleanroom capacity.
- Industrial Grade:Unregulated elastomer formulations serve equipment manufacturing and non-patient-contact fluid handling at substantial cost discounts.
- Food Grade:FDA 21 CFR 177-compliant polymers migrate into medical applications where regulatory exposure remains minimal and cost pressure dominates.
Medical grade specifications capture the highest shipment volumes; pharmaceutical grade commands the most rapid demand acceleration.
Application:
Customer type differentiation separates high-volume disposable catheterization from capital-intensive respiratory device platforms with extended replacement cycles.
- Catheterization:Multi-lumen extrusions for cardiovascular and urological access represent the largest addressable volume segment. United States hospital procurement consolidation is compressing supplier bases toward manufacturers with captive resin compounding.
- Peristaltic Pumping:Precision-bore tubing with tight wall thickness tolerances enables accurate fluid metering in drug infusion and diagnostic instrumentation. German laboratory equipment manufacturers specify pharmaceutical-grade silicone for extended pump head longevity.
- Drainage:Large-bore PVC and silicone constructions for post-surgical and wound management applications compete primarily on unit cost.
- Fluid Transfer:General-purpose tubing for IV sets and blood handling balances biocompatibility requirements against high-throughput manufacturing economics.
- Respiratory Devices:Corrugated and smooth-bore configurations for ventilator circuits and anesthesia delivery face stringent flammability and phthalate-content regulations.
Catheterization applications generate the dominant revenue share; peristaltic pumping exhibits the most aggressive growth trajectory.
End User:
Supply concentration varies sharply between consolidated hospital networks with group purchasing organization leverage and fragmented home care channels requiring specialized distribution infrastructure.
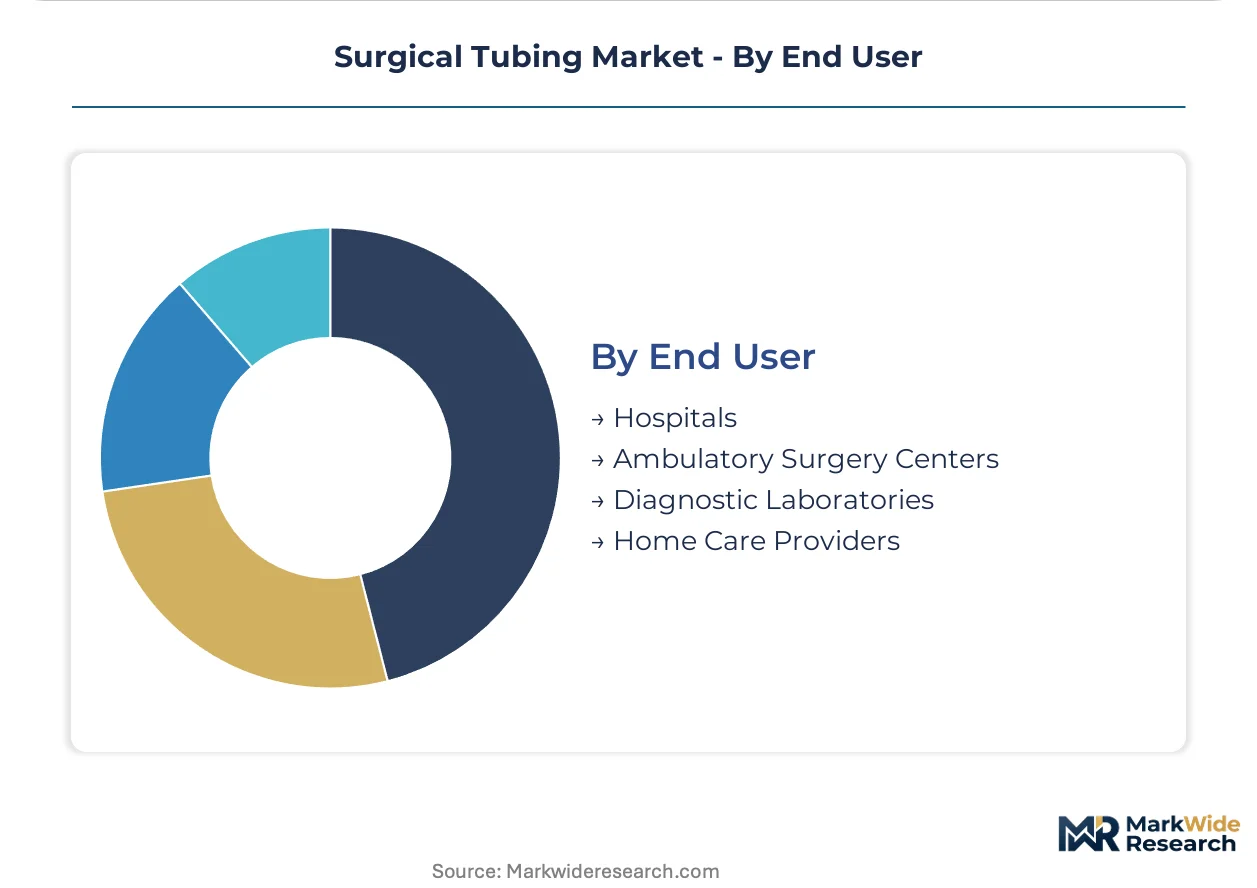
- Hospitals:Integrated delivery networks in the United States award multi-year contracts contingent on regulatory file ownership and documented supply security. Saint-Gobain and Zeus Industrial Products anchor procurement through vertical manufacturing control.
- Ambulatory Surgery Centers:Outpatient catheterization migration is expanding addressable volumes for single-use disposable tubing with simplified sterilization requirements. RAUMEDIC AG targets this channel with pharmaceutical-grade silicone from German cleanroom facilities.
- Diagnostic Laboratories:Automated analyzer OEMs specify precision-extruded peristaltic pump tubing with lot-to-lot dimensional consistency.
- Home Care Providers:Distributed enteral feeding and respiratory therapy markets demand cost-optimized PVC and TPE formulations with patient-friendly handling characteristics.
Hospitals retain the largest procurement volume; ambulatory surgery centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized tubing converters cluster in industrial corridors with adjacent polymer science infrastructure and established medical device manufacturing ecosystems. Germany, the United States, Japan, and Switzerland anchor production capacity through integrated cleanroom facilities and captive resin formulation capabilities.
United States
Ambulatory surgery center expansion in Texas and Florida is driving catheterization procedure volumes for outpatient tubing consumption. FDA biocompatibility testing requirements for implantable durations exceeding thirty days compress supplier qualification timelines. Minnesota's Twin Cities corridor concentrates precision extrusion specialists serving neurovascular device OEMs with micro-diameter specifications.
Germany
Pharmaceutical-grade silicone demand from combination product manufacturers is accelerating cleanroom capacity investments in Bavaria. EU MDR technical documentation mandates for Class III device incorporation elevate procurement concentration on certified converters with integrated quality systems. RAUMEDIC AG's Heuchelheim facility anchors European supply of pharmaceutical-grade tubing with lot-to-lot extractables documentation.
Japan
Stroke intervention device manufacturers in the Kansai region are expanding procurement of high-tensile polyurethane micro-tubing for neurovascular navigation systems. PMDA quality management system inspections for foreign manufacturers tighten supply chain documentation requirements. Tokyo-Yokohama medical device clusters concentrate demand for precision-extruded peristaltic pump tubing in automated diagnostic analyzers.
Switzerland
Drug-device convergence applications from Basel-based pharmaceutical headquarters command premium positioning for pharmaceutical-grade tubing with documented leachables profiles. Swissmedic device licensing requirements for permanent implant incorporation mandate clinical performance evidence. The Lake Geneva corridor concentrates catheter system assemblers sourcing barrier-layer fluoropolymer liners for cardiovascular platforms.
China
Domestic catheter OEMs in the Yangtze River Delta are qualifying local silicone tubing converters to reduce import dependency for cost-sensitive drainage applications. NMPA medical device registration reforms for Class III implants are elevating documentation standards for tubing suppliers. Suzhou's medical device industrial park hosts expanding cleanroom extrusion capacity targeting peristaltic pump specifications for laboratory automation.
Surgical Tubing Market Key Industry Players
Integrated material specialists and precision extrusion houses split the market between resin-to-finished-product control and tolerance-critical micro-diameter applications. Supplier consolidation favors manufacturers with captive compounding capabilities that can document supply security for hospital procurement networks. Three archetypes dominate: diversified polymer conglomerates with medical divisions, dedicated medical tubing specialists with cleanroom assets, and regional converters serving cost-optimized disposable segments. Competitive dynamics center on backward integration into resin formulation and geographic expansion of ISO Class 7 certified production footprints.
Among diversified industrial material groups, Saint-Gobain Performance Plastics exemplifies the fluoropolymer-barrier archetype for catheter liner applications. Zeus Industrial Products occupies a central position in North American precision extrusion for neurovascular micro-tubing specifications. RAUMEDIC AG represents the European pharmaceutical-grade silicone specialist model with integrated cleanroom manufacturing.
| Leading Market Players |
|---|
| Saint-Gobain Performance Plastics |
| Teleflex |
| Zeus Industrial Products |
| RAUMEDIC AG |
| Tekni-Plex |
| W. L. Gore & Associates |
| Kent Elastomer Products |
| Freudenberg Medical |
| MicroLumen |
| Others |
Cost & Logistics Intelligence
Single-source dependency on pharmaceutical-grade silicone feedstock concentrates pricing power among a limited pool of chemical producers, compressing margin spreads between premium and standard tiers while forcing converters toward backward integration into resin formulation. This input bottleneck simultaneously elevates cost volatility exposure and rewards manufacturers with captive compounding capabilities that can document supply security for hospital procurement networks.
Pricing Analysis
ISO 10993 biocompatibility certification dictates the pricing tier structure across implantable and short-term contact applications. Three-tier pricing stratifies across pharmaceutical-grade, medical-grade, and industrial-grade specifications, with USP Class VI documentation commanding substantial premiums. Cost compression in standard medical-grade segments is intensifying because hospital procurement consolidation favors volume contractors, while pharmaceutical-grade buyers show lowest price sensitivity due to regulatory file dependency.
Supply Chain Analysis
Freudenberg Medical and Tekni-Plex anchor contract manufacturing capacity for precision-extruded catheter components, with specialized cleanroom assets concentrated in Germany, the United States, and Switzerland. Raw material sourcing draws from Dow Corning silicone polymers, Lubrizol thermoplastic polyurethanes, and Arkema fluoropolymer resins. Single-source vulnerability in pharmaceutical-grade silicone monomers creates allocation risk during supply disruptions. Distribution runs through group purchasing organizations in United States hospital networks and direct OEM partnerships in European device manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision extrusion expertise for sub-0.010 inch inner diameter tubing concentrates among aging specialist workforces with limited apprenticeship pipeline replenishment, creating a structural capability gap that rewards early investment in talent development and automated manufacturing systems.
For Market Incumbents: Insulate market position by deepening backward integration into pharmaceutical-grade silicone compounding and expanding ISO Class 7 certified production footprints in Bavaria and Minnesota to counter emerging Asian converters. Prioritize regulatory file ownership investments ahead of EU MDR technical documentation mandates for Class III device incorporation. For New Entrants and Emerging Players: Build out specialized capabilities in neurovascular micro-diameter extrusions where tolerance-critical specifications command premium positioning beyond commoditized cardiovascular segments. Target ambulatory surgery center channels with pharmaceutical-grade silicone tubing bundled with simplified sterilization protocols to bypass entrenched hospital GPO relationships. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by elevating barriers for non-specialized suppliers and concentrating demand on certified manufacturers with integrated quality systems. Five-to-ten year viability favors converters with documented extractables profiles and cleanroom assets. Watch FDA guidance finalization on nitrosamine impurities in rubber-based tubing as a signal for supply chain requalification spending inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO Class 7 certification in Bavaria addresses EU MDR concentration requirements for pharmaceutical-grade supply. |
| Backward Integration into Resin Compounding | Captive silicone formulation secures allocation priority during pharmaceutical-grade feedstock constraints. |
| Neurovascular Micro-Extrusion Investment | Sub-0.010 inch precision capabilities open premium positioning beyond commoditized cardiovascular segments. |
| Hospital System Partnership | Multi-year GPO contracts with United States integrated delivery networks lock in volume commitments. |
| Regulatory File Ownership | Direct control of ISO 10993 dossiers accelerates supplier qualification for implantable device OEMs. |
Research Approach
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and precision extrusion specialists and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and SEC filings of listed medical device component suppliers. Bottom-up volume modeling triangulated with top-down market sizing across material grade, application, and end-user dimensions.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeling spanning product type, material certification tier, application category, and end-user channel. CAGRs were derived from regression analysis of historical shipment data and forward projection of procedure volume drivers. Forecast inputs incorporated ambulatory surgery center expansion trajectories and evolving biocompatibility testing protocol burdens for long-term implantables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic converters or accelerated phthalate substitution timelines would shift outcomes. Quarterly review of FDA guidance publication schedules, EU MDR notified body capacity constraints, and pharmaceutical-grade silicone producer allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Dental Surgical Microscopes Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Surgical Snare Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market