
 Surgical Hand-Access Port Market | 2026-2036
Surgical Hand-Access Port Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Hand-Access Port Market Analytics
Premium-grade silicone construction is bifurcating the competitive landscape between value-oriented suppliers and specification leaders. Medtronic plc leverages its integrated surgical ecosystem to sustain channel dominance across integrated delivery networks. Johnson & Johnson anchors its position through deep laparoscopic instrument portfolios that bundle hand-access ports with stapling and energy platforms. Karl Storz SE & Co. KG differentiates via rigid endoscope compatibility and specialized port geometries for single-incision procedures.
A surgical hand-access port is a specialized device inserted through the abdominal wall that maintains pneumoperitoneum while permitting surgeon hand introduction, typically constructed from medical-grade silicone or polyurethane with a self-sealing valve mechanism rated for pressures of 12-15 mmHg. The device enables manual tissue manipulation, suturing, and specimen retrieval during laparoscopic operations without converting to open surgery. Single-port configurations command the strongest margin pools as hospitals seek reduced incision counts for patient satisfaction metrics, while robotic assistance segments attract the fastest development activity from OEMs building compatibility with da Vinci and competing platforms. Ambulatory care facilities represent an emerging volume channel as same-day discharge protocols expand eligible procedures beyond traditional hospital settings.
FDA 510(k) premarket notification requirements govern device clearance timelines in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards for Class IIa and IIb port systems entering European markets. The FDA's ongoing emphasis on biocompatibility testing per ISO 10993 series standards directly shapes material selection decisions among manufacturers. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA digital health pre-certification pilots that could reshape traditional submission pathways for smart port technologies incorporating pressure-sensing capabilities.
Market Dynamics
Single-incision laparoscopy is compressing multi-port configurations as tertiary hospitals prioritize reduced incision counts for patient satisfaction metrics and faster discharge protocols.
Growth Catalysts
- MDR harmonization:EU Medical Device Regulation standardization accelerates cross-border product approvals for Class IIa port systems, reducing redundant clinical trials across member states.
- Silicone material advances:Medical-grade silicone formulations with enhanced tear resistance enable thinner port walls without sacrificing pneumoperitoneum integrity at 15 mmHg operating pressures.
- Japan's aging surgical population:METI-backed initiatives promoting minimally invasive techniques in Tokyo and Osaka medical centers expand eligible patient pools for hand-assisted procedures.
Market Restraints
- Medical-grade silicone feedstock volatility:Petrochemical-derived silicone precursor costs fluctuate with crude oil indices, compressing margins for specification-grade port manufacturers.
- Notified body capacity constraints:EU MDR implementation bottlenecks delay CE marking timelines for new port geometries, freezing product launches for 12-18 month intervals.
- Single-port technical ceiling:Instrument triangulation limitations in confined single-incision configurations restrict complex procedures, preserving multi-port demand for advanced oncologic resections.
Strategic Opportunities
- Ambulatory surgery center penetration:Same-day discharge protocols in United States outpatient facilities create volume channels beyond traditional hospital integrated delivery networks.
- Robotic platform convergence:Hand-access port compatibility engineering for da Vinci and competing surgical robotic systems opens premium pricing tiers for OEMs with integration capabilities.
- FDA breakthrough device designation:Pressure-sensing smart ports with real-time pneumoperitoneum monitoring qualify for expedited review pathways, compressing time-to-market for innovative submissions.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 series compliance documentation requirements strain regulatory affairs teams, extending pre-submission preparation cycles.
- Laparoscopic fellowship training gaps:Hand-assisted technique proficiency varies across surgical residency programs, creating adoption friction in community hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Hand-Access Port Market |
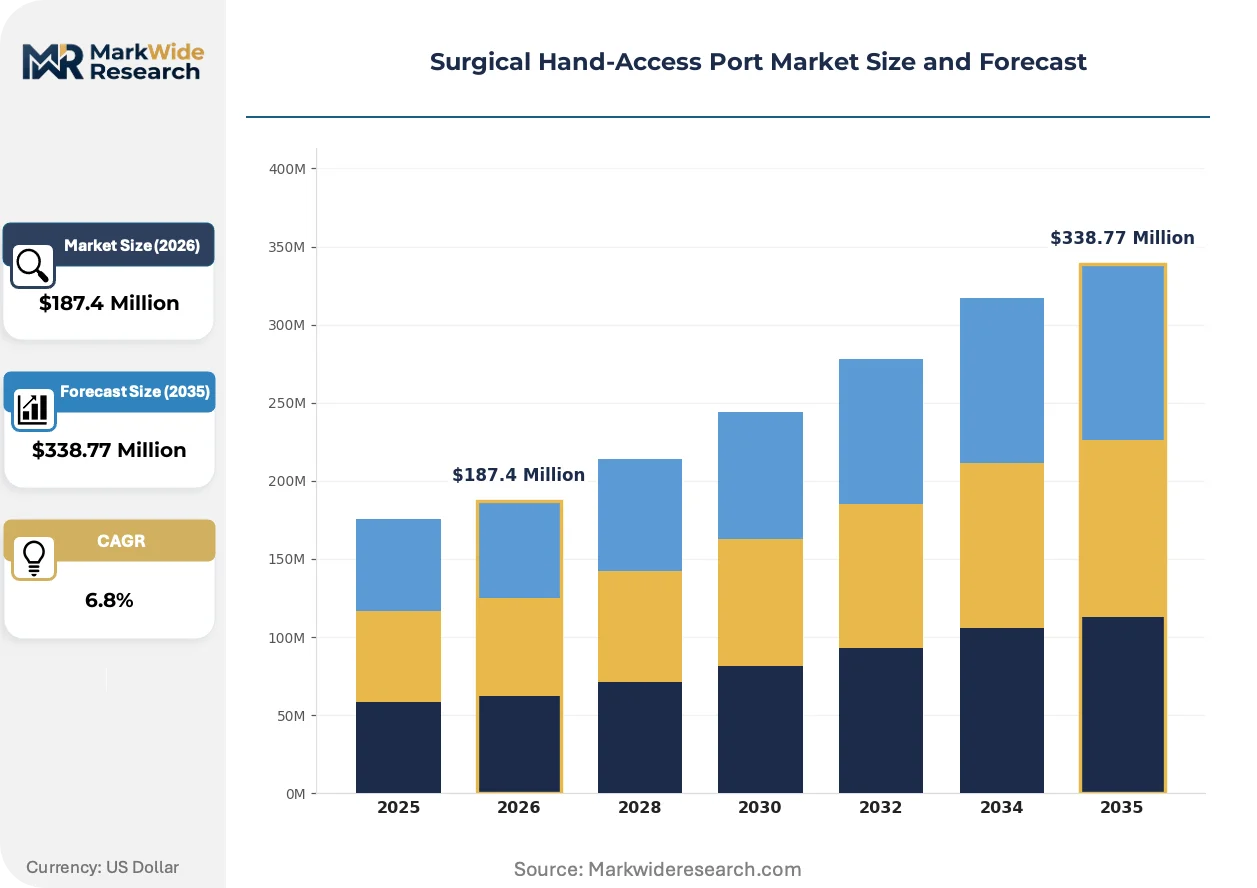
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Port, Dual Port, Multi-Port, Robotic Assistance End User: Hospitals, Surgery Centers, Ambulatory Care Facilities, Clinics Application: General Surgery, Urological Surgery, Gynecological Surgery, Bariatric Surgery Material: Silicone, Polyurethane, Stainless Steel, Biodegradable Polymers |
| Companies Covered | Medtronic plc, Johnson & Johnson, Stryker Corporation, CONMED Corporation, Applied Medical Resources, B. Braun Melsungen AG, Karl Storz SE & Co. KG, Olympus Corporation, Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Hand-Access Port Market Evolving Landscape
Device intelligence and material science are converging to redefine performance benchmarks, with pressure-monitoring capabilities and advanced elastomers displacing passive mechanical designs.
Smart port architectures with embedded pressure sensors and wireless data transmission are decomposing the traditional separation between access devices and insufflation systems. Tertiary hospitals in the United States and Germany are piloting these integrated platforms for real-time pneumoperitoneum monitoring during extended procedures. This convergence is compressing the addressable market for standalone insufflator hardware while elevating port system ASPs through bundled intelligence.
EU MDR Article 10 clinical evidence requirements are forcing manufacturers to generate prospective performance data for Class IIb port systems with novel valve mechanisms. The regulation mandates post-market clinical follow-up studies that extend surveillance obligations beyond legacy MDD timelines. Small and mid-cap suppliers without established clinical affairs infrastructure are outsourcing trial management to contract research organizations, altering competitive cost structures.
Hospital procurement committees are consolidating vendor relationships through integrated delivery network frameworks that bundle hand-access ports with energy devices and stapling platforms. This concentration displaces standalone port purchasing in favor of multi-year supply agreements with primary surgical device OEMs. The shift is most visible in United States health systems pursuing standardization across affiliated ambulatory surgery centers.
Surgical Hand-Access Port Market Segmentation
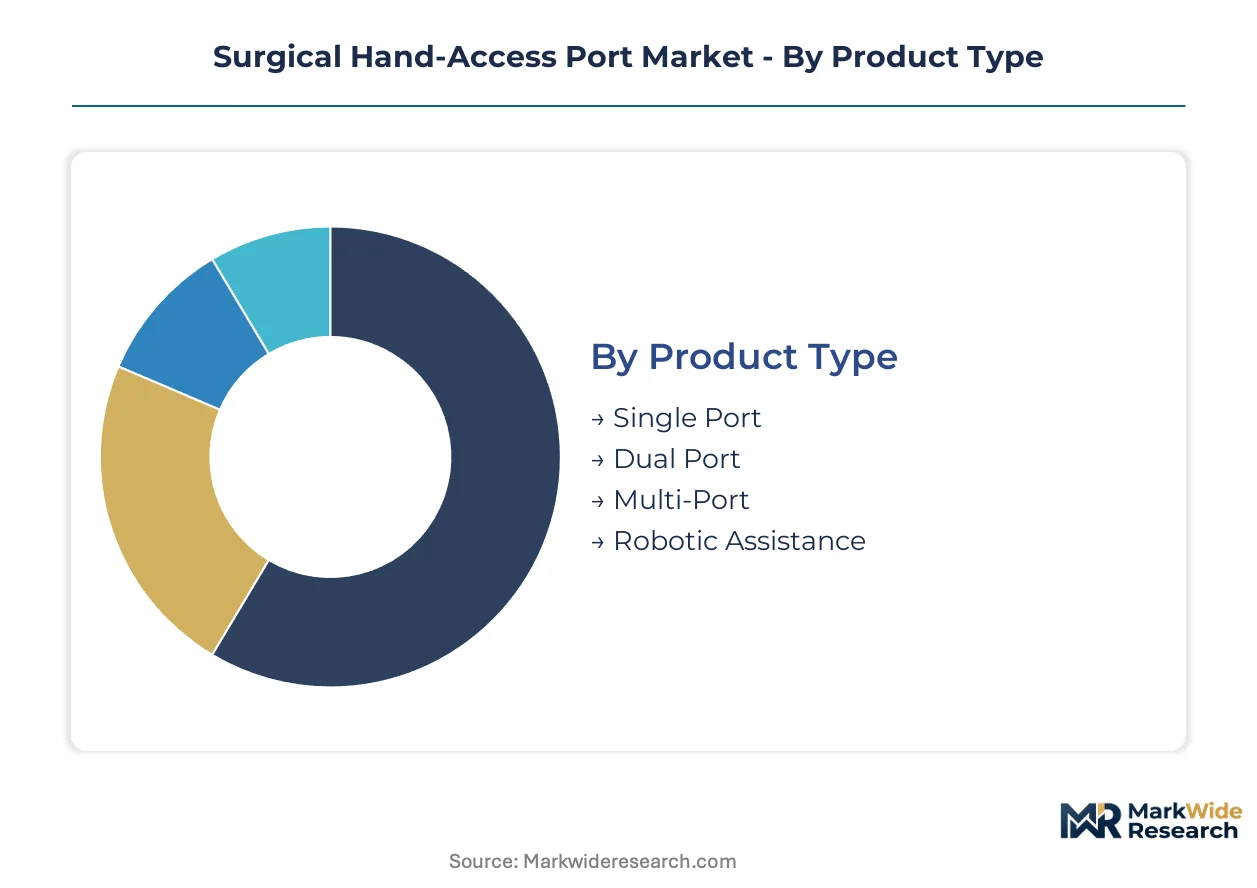
Surgical hand-access port manufacturers compete across four distinct segmentation axes where product specifications, procedural applications, and institutional purchasing power create divergent margin profiles. Understanding substitution dynamics within each dimension reveals where specification leaders defend premium positioning against value-oriented challengers.
Product Type:
Multi-port configurations face the strongest substitution pressure as single-incision techniques and robotic platforms compress demand for traditional laparoscopic access arrays.
- Single Port:Self-sealing silicone platforms with integrated insufflation valves enable hand-assisted procedures through a single abdominal incision while maintaining pneumoperitoneum integrity at 15 mmHg. Demand concentrates in tertiary hospitals across the United States and Germany where patient satisfaction metrics and cosmetic outcomes drive procurement decisions for cholecystectomy and colectomy procedures.
- Dual Port:Two-channel configurations balance hand access with instrument triangulation for complex tissue manipulation requiring bimanual technique. Adoption clusters in academic medical centers performing advanced oncologic resections where instrument crowding in single-port setups limits operative precision.
- Multi-Port:Traditional three-to-five port arrays retain volume in rural and community hospital settings where capital constraints delay single-port platform acquisition.
- Robotic Assistance:Compatibility-engineered ports for da Vinci and competing surgical robotic systems command premium pricing through integrated delivery network bundled purchasing agreements.
Multi-port configurations anchor the volume base while robotic assistance segments gain share at the steepest rate.
End User:
Cost tier stratification separates capital-rich integrated delivery networks from price-sensitive independent surgical facilities.
- Hospitals:Tertiary academic centers and community hospitals generate the majority of procedural volume through established laparoscopic suites with dedicated minimally invasive surgery fellowship programs.
- Surgery Centers:Freestanding ambulatory surgery facilities in the United States pursue same-day discharge protocols that expand eligible hand-assisted procedures beyond traditional hospital settings.
- Ambulatory Care Facilities:Outpatient clinics with limited procedural capacity represent an emerging channel as regional anesthesia techniques enable office-based laparoscopic interventions.
- Clinics:Physician office laboratories and small-group practices concentrate demand for basic single-port configurations in metropolitan markets with high specialist density.
Hospitals retain the dominant procurement position while surgery centers expand most quickly as site-of-service migration accelerates.
Application:
Procedure complexity and reimbursement levels determine specification requirements across surgical specialties.
- General Surgery:Cholecystectomy, appendectomy, and hernia repair procedures generate the highest absolute port consumption through standardized multi-port configurations in high-volume community hospital settings.
- Urological Surgery:Nephrectomy and prostatectomy applications demand specialized port geometries with extended working lengths to accommodate retroperitoneal access and deep pelvic dissection.
- Gynecological Surgery:Hysterectomy and myomectomy procedures in United States and Japanese medical centers drive single-port adoption for cosmetic outcomes and reduced postoperative pain scores.
- Bariatric Surgery:Sleeve gastrectomy and gastric bypass applications require reinforced port materials to withstand morbid obesity patient body habitus and extended operative durations.
General surgery anchors procedural volume while bariatric applications climb the fastest as metabolic surgery eligibility expands.
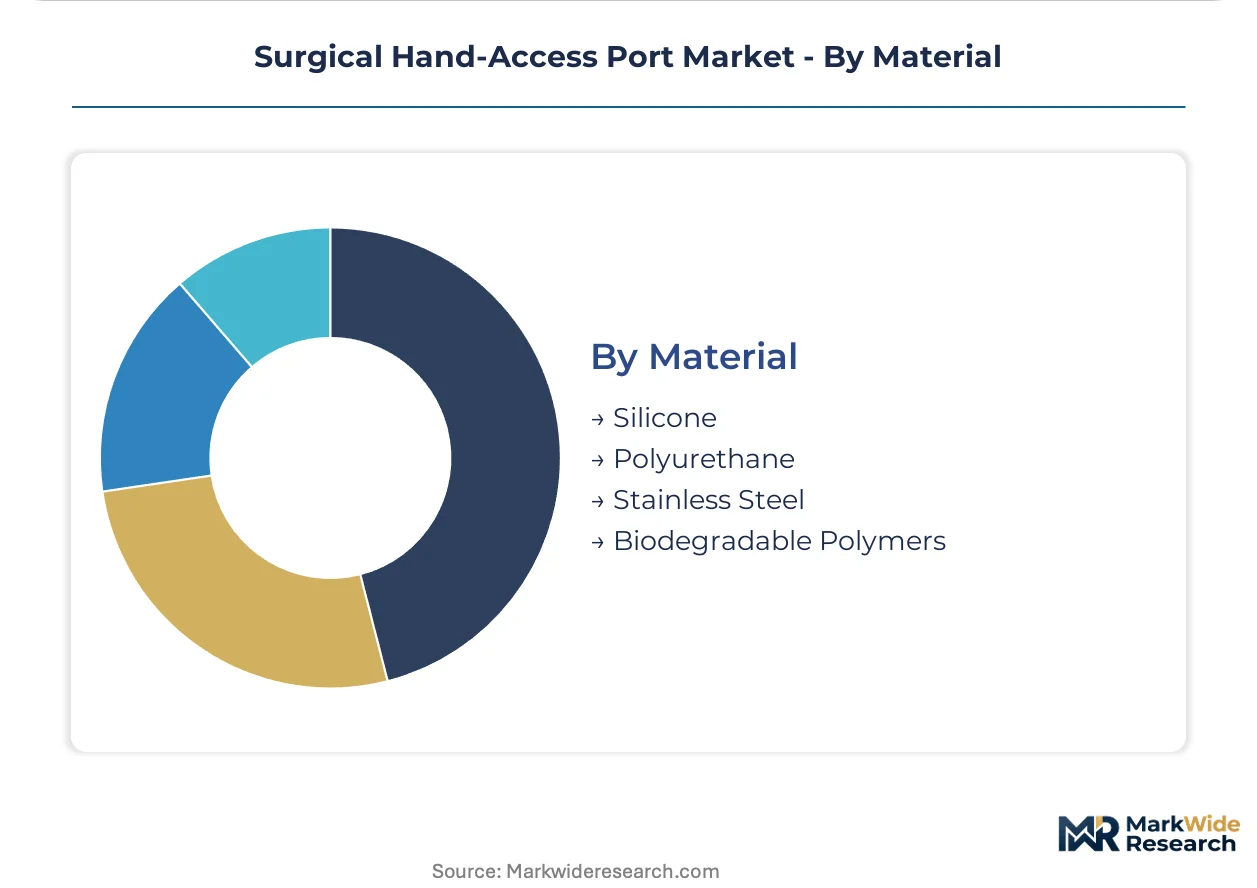
Material:
Supply concentration in medical-grade silicone feedstock shapes competitive cost structures and biocompatibility compliance pathways.
- Silicone:Medical-grade elastomer formulations with ISO 10993 biocompatibility certification dominate specification-grade port manufacturing. Tear-resistant silicone variants enable thinner wall designs that reduce insertion force without compromising pneumoperitoneum seal integrity.
- Polyurethane:Alternative elastomer platforms offer cost advantages in price-sensitive markets while meeting equivalent pressure ratings for standard laparoscopic procedures.
- Stainless Steel:Rigid port components and valve housings provide structural reinforcement in reusable port systems for cost-conscious healthcare systems with established sterilization infrastructure.
- Biodegradable Polymers:Experimental absorbable materials under development for temporary access applications eliminate retrieval procedures in select pediatric and trauma settings.
Silicone anchors material demand while biodegradable polymers attract the steepest development investment from OEMs targeting sustainability metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone compounding capacity clusters in Germany, Japan, and the United States, concentrating specification-grade port manufacturing among integrated surgical device OEMs with captive polymer processing capabilities.
United States
Tertiary hospital networks in Cleveland, Houston, and the Boston metro area drive single-port adoption for cholecystectomy and colectomy volumes. FDA 510(k) clearance pathways shape product development timelines, with breakthrough device designations accelerating review for pressure-sensing smart ports. The Mayo Clinic Rochester and Cleveland Clinic anchor clinical validation partnerships for novel valve mechanisms.
Germany
Academic medical centers in Berlin, Munich, and Heidelberg prioritize reduced incision counts for patient satisfaction metrics and faster discharge protocols. EU MDR notified body capacity constraints delay CE marking timelines for new port geometries, freezing product launches for extended intervals. The Tübingen and Freiburg surgical clusters generate prospective clinical data for Class IIb system submissions.
Japan
METI-backed initiatives promoting minimally invasive techniques in Tokyo and Osaka medical centers expand eligible patient pools for hand-assisted procedures. PMDA consultation pathways for novel medical devices compress pre-market approval timelines for innovative port designs. The Nagoya and Sendai metropolitan areas concentrate laparoscopic fellowship training programs that standardize hand-assisted technique proficiency.
United Kingdom
NHS integrated care systems in London, Manchester, and Birmingham consolidate vendor relationships through multi-year supply agreements that bundle hand-access ports with energy platforms. MHRA recognition of EU MDR certificates maintains market access continuity post-Brexit. The Oxford and Cambridge surgical research clusters pilot pressure-monitoring integrated platforms for real-time pneumoperitoneum surveillance.
India
Private hospital chains in Mumbai, Delhi-NCR, and Bengaluru absorb multi-port configurations as capital constraints delay single-platform acquisition in tier-2 cities. CDSCO medical device rules mandate registration for imported Class B and C port systems, extending commercialization timelines for foreign OEMs. The Hyderabad and Chennai medical device manufacturing corridors develop domestic silicone molding capabilities for cost-competitive port production.
Surgical Hand-Access Port Market Competitive Landscape
Concentration sits with diversified surgical device conglomerates that leverage integrated delivery network purchasing agreements to bundle hand-access ports with stapling, energy, and visualization platforms. Three to five mid-cap specialists compete on specification-grade silicone formulations and specialized port geometries for single-incision procedures. Strategic moves center on robotic platform compatibility engineering and ambulatory surgery center distribution partnerships that bypass traditional hospital procurement committees.
Among diversified medical technology conglomerates, Medtronic plc, Johnson & Johnson, and Stryker Corporation exemplify the integrated ecosystem archetype that dominates channel access across United States health systems. These entities occupy positions where laparoscopic instrument portfolios create natural bundling economics for hand-access port placement. Karl Storz SE & Co. KG represents the visualization-anchored specialist model, while B. Braun Melsungen AG sits within the European-centered surgical supplies tier with regional manufacturing footprint advantages.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson |
| Stryker Corporation |
| CONMED Corporation |
| Applied Medical Resources |
| B. Braun Melsungen AG |
| Karl Storz SE & Co. KG |
| Olympus Corporation |
| Smith & Nephew plc |
| Others |
Value Network & Pricing Analysis
Polyurethane substitution for medical-grade silicone in price-sensitive procurement tiers simultaneously shifts manufacturing geography toward India and compresses margin pools for specification-grade suppliers tethered to German and Japanese polymer compounding infrastructure.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across premium, standard, and economy levels, with breakthrough-designated smart ports commanding substantial premiums over conventional mechanical valves. Price differentiation rests on ISO 10993 certification grade and robotic platform compatibility, with da Vinci-integrated configurations least exposed to cost compression. Pricing pressure stems from hospital procurement consolidation through integrated delivery networks that leverage multi-year bundling agreements. Ambulatory surgery centers exhibit highest price sensitivity, while tertiary academic centers prioritize specification compliance over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate among United States hospital networks, while European manufacturers maintain strategic silicone precursor stockpiles against petrochemical volatility. Geographic supply concentration centers on Germany, Japan, and the United States for medical-grade silicone compounding, with India developing domestic molding capabilities. Raw material dependencies include petrochemical-derived silicone precursors, stainless steel valve components, and specialized elastomer formulations. Single-source vulnerability in notified body certification creates bottleneck risk for EU market entry. Distribution runs through surgical device distributors and integrated delivery network direct contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
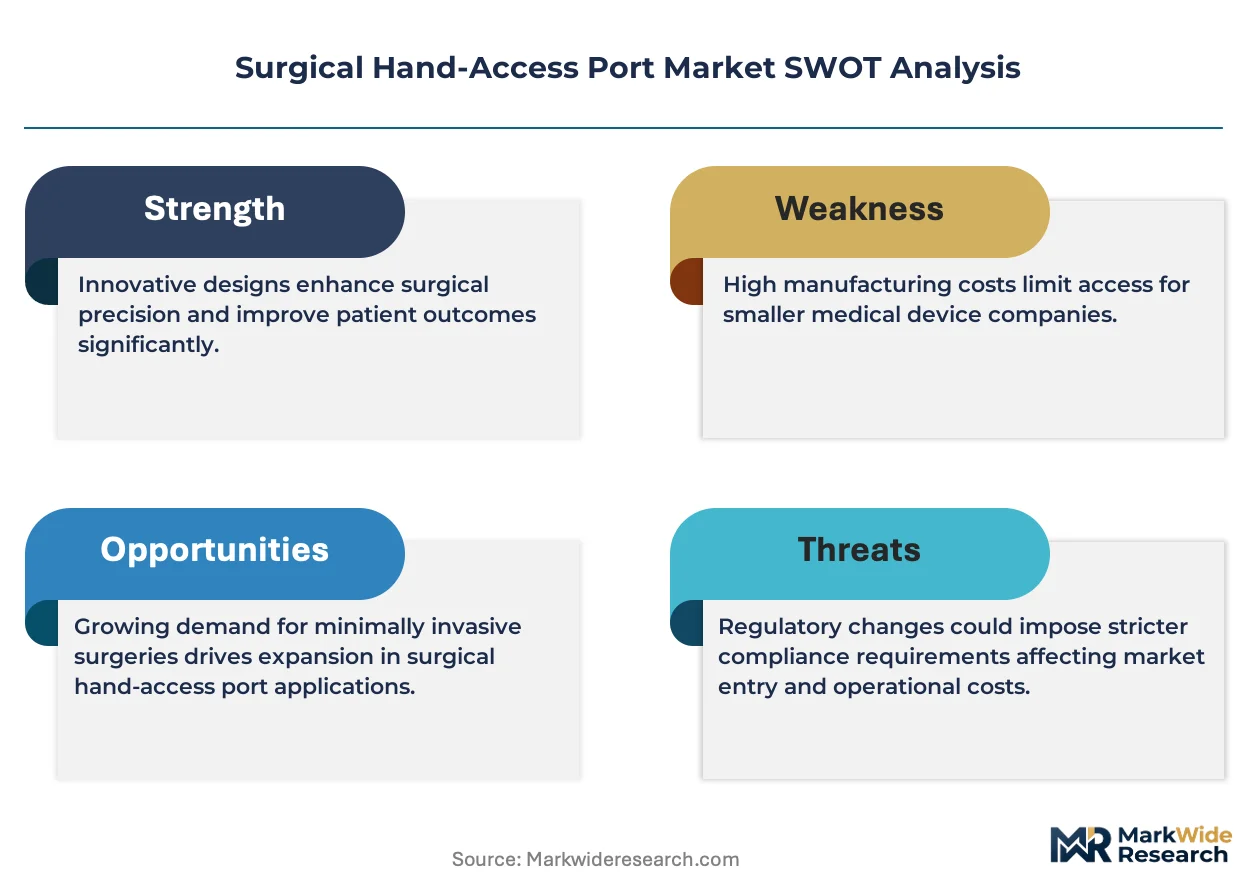
Incumbent OEMs face substitution defense imperatives as robotic surgical platforms and single-incision techniques threaten traditional multi-port volume anchors.
For Market Incumbents: Fortify ecosystem lock-in through robotic compatibility engineering and backward integration into medical-grade silicone compounding. Prioritize CE marking pathway investments to preempt MDR notified body capacity constraints. Channel control through ambulatory surgery center distribution partnerships defends against procurement committee consolidation. For New Entrants and Emerging Players: Differentiate on specialized port geometries for bariatric applications and biodegradable polymer platforms targeting sustainability procurement criteria. White-space concentration sits with India's private hospital chains and United States surgery centers seeking cost-competitive alternatives to bundled OEM agreements. Direct contracting with regional GPOs bypasses integrated delivery network exclusion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap specialists possessing clinical affairs infrastructure but lacking robotic platform integration capabilities. Long-term viability favors entities with demonstrated MDR compliance execution and established surgeon training partnerships. Watch FDA breakthrough device designation grants as inflection indicators for smart port technology validation.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Platform Compatibility Engineering | da Vinci integration unlocks premium pricing tiers through bundled purchasing agreements with United States health systems. |
| MDR CE Marking Pathway Investment | Notified body relationship development compresses approval timelines for Class IIb valve mechanism innovations. |
| Ambulatory Surgery Center Distribution Partnership | Same-day discharge protocol expansion creates volume channels beyond traditional hospital procurement committees. |
| Biodegradable Polymer R&D Program | Absorbable material platforms align with sustainability metrics in European hospital procurement frameworks. |
| Surgeon Training Fellowship Sponsorship | Standardized hand-assisted technique proficiency reduces adoption friction in community hospital settings. |
Research Methodology
A standing panel of laparoscopic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR notified body registers, hospital procurement databases, and CMS procedure volume data. Primary fieldwork combined structured interviews with regulatory affairs leads at diversified OEMs and distribution channel partners at surgical device distributors. Bottom-up port shipment modeling and top-down minimally invasive procedure volume estimates were triangulated for consistency.
Outputs were validated against external benchmarks including insufflator hardware shipment correlations and robotic surgical system installation trajectories across the projection horizon. Segmentation dimensions modeled include product type, end user institution tier, surgical application specialty, and material composition grade. CAGRs were derived from procedure volume elasticity analysis and port utilization ratios per surgical specialty. Forecast inputs incorporated MDR implementation timelines and ambulatory surgery center site-of-service migration patterns.
The analysis sits within stated boundaries; outcomes outside sustained minimally invasive surgery adoption rates or notified body capacity normalization would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway stability and silicone feedstock cost trajectories. Revision becomes warranted when robotic platform penetration crosses thresholds that materially displace hand-assisted technique volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
US Integrated Operating Rooms Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Global Surgical Suction Instruments Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Global Gauze Swabs Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Global Powered Surgical Instruments Market