
 Global Surgical Case Carts Market | 2026-2036
Global Surgical Case Carts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Case Carts Market Foresight
Stainless steel is shifting toward polymer composites and hybrid aluminum structures in surgical case cart construction, reducing unit weight while maintaining load capacity for instrument sets. STERIS plc leverages its sterilization ecosystem to bundle case cart offerings with terminal cleaning workflows. Capsa Healthcare anchors its position through configurable modular platforms that adapt to orthopedic and cardiovascular procedure kits. Pedigo Products competes on domestic manufacturing scale, sustaining shorter lead times for hospital capital committees.
Surgical case carts are wheeled containment systems engineered from medical-grade stainless steel, aluminum, or polymer composites, typically rated for loads exceeding 300 pounds and designed to maintain sterile barrier integrity through sealed gasket doors and HEPA-compatible ventilation. Their primary purpose is to transport pre-sterilized instrument trays from central supply to operating rooms while preventing contamination. Stainless steel variants still dominate installed base due to durability and autoclave compatibility, though modular case carts represent the fastest-growing product configuration as facilities reconfigure surgical suites for multi-specialty use. Ambulatory surgical centers drive disproportionate demand growth within the end user segment, as these facilities prioritize compact footprints and rapid turnover between ophthalmology and pain management procedures.
FDA quality system regulation and ISO 13485 medical device standards govern material traceability, weld integrity, and bioburden control in case cart manufacturing, creating compliance barriers for non-specialized metal fabricators. The EU Medical Device Regulation and CE marking requirements extend these constraints for European market access, particularly for electropolished surfaces and passivation documentation. REACH chemical restrictions on hexavalent chromium plating further narrow supplier options for corrosion-resistant finishes. Stakeholders must monitor how evolving sustainability mandates from ECHA and state-level health systems reshape material specifications and supplier qualification timelines.
Market Dynamics
The surgical case cart market is reconfiguring around material substitution pressures as polymer composites and hybrid aluminum structures displace stainless steel in new procurement cycles, driven by ambulatory surgical center demand for lighter, modular containment systems.
Growth Catalysts
- Outpatient Volume Expansion:Ambulatory surgical centers in the United States are accelerating replacement of fixed cabinetry with mobile case cart systems to support same-day discharge protocols and rapid room turnover.
- FDA Quality System Regulation:The agency's sterilization validation requirements for medical device manufacturing are elevating supplier qualification barriers, favoring specialized fabricators with documented bioburden control capabilities.
- Multi-Specialty Surgical Suites:Hospital infrastructure renewal projects are specifying configurable modular platforms that adapt instrument storage between orthopedic, cardiovascular, and ophthalmology procedure kits without dedicated fixed installations.
Market Restraints
- Stainless Steel Input Volatility:Medical-grade 304 and 316L stainless pricing fluctuates with nickel and chromium commodity markets, compressing margins for manufacturers maintaining legacy all-metal product lines.
- EU Medical Device Regulation Compliance Burden:CE marking documentation requirements for electropolished surfaces and passivation records extend supplier qualification timelines by 12-18 months for European market access.
- REACH Chemical Restrictions:ECHA limitations on hexavalent chromium plating narrow corrosion-resistant finish options, forcing suppliers toward more expensive PVD coatings or electropolishing alternatives.
Strategic Opportunities
- Indian ASC Buildouts:The country's expanding network of ambulatory surgical centers under Ayushman Bharat presents untapped demand for compact, lightweight case cart configurations suited to space-constrained urban facilities.
- Terminal Cleaning Workflow Integration:Sterilization equipment manufacturers can bundle case cart offerings with automated washer-disinfector systems, capturing recurring service revenue beyond hardware sales.
- ISO 13485 Certification Arbitrage:Medical device quality management certification is becoming a procurement gatekeeper; suppliers achieving this standard gain preferred vendor status with integrated health systems consolidating purchasing.
Industry Challenges
- Weld Integrity Certification Bottlenecks:FDA and ISO 13485 requirements for traceable weld documentation create backlogs at specialized fabrication shops, extending lead times for hospital capital committees.
- Legacy Fleet Retrofit Complexity:Health systems with installed bases of fixed stainless steel cabinetry face capital planning friction when evaluating modular replacement versus incremental upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Case Carts Market |
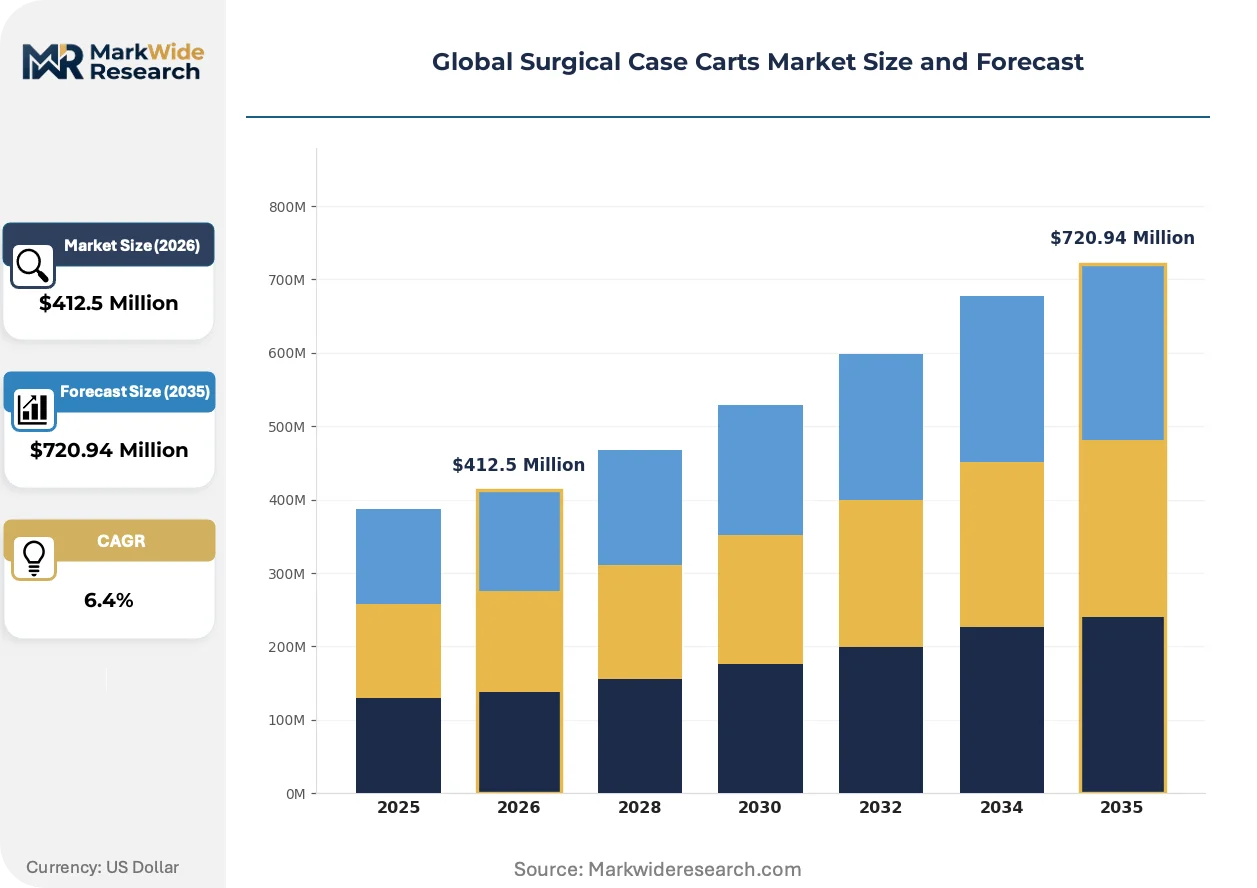
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Case Carts, Modular Case Carts, Specialty Case Carts, Customizable Case Carts Material: Stainless Steel, Aluminum, Plastic Composite, Carbon Steel, Polypropylene Application: Orthopedic Surgery, Cardiovascular Procedures, Neurosurgery, General Surgery, Urology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Outpatient Facilities, Long-Term Care Centers |
| Companies Covered | STERIS plc, Capsa Healthcare, Pedigo Products, Lakeside Manufacturing, MAC Medical, Bailida Medical, InterMetro Industries Corporation, Getinge, Future Health Concepts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Case Carts Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are compressing product development cycles while expanding the addressable market beyond traditional hospital settings into outpatient and mobile surgical environments.
Polymer composite case cart construction is converging with radio-frequency identification tracking systems to enable real-time instrument set location monitoring through sealed, non-metallic enclosures that do not interfere with RFID signal transmission. Ambulatory surgical centers in Germany and the United States are piloting these configurations for high-value orthopedic implant kits. This convergence is compressing the traditional separation between physical containment and digital supply chain visibility, forcing stainless steel-centric manufacturers to develop hybrid material competencies or cede the RFID-integrated segment.
REACH chemical restrictions on hexavalent chromium plating are reshaping surface treatment specifications across European procurement tenders, with ECHA enforcement extending to passivation documentation for medical-grade aluminum and stainless steel substrates. Manufacturers serving the EU market are accelerating migration to citric acid passivation and PVD coating alternatives. Electropolished stainless steel case carts bound for European hospital systems now require batch-level chemical composition certificates, increasing documentation costs but creating compliance-based differentiation for qualified suppliers.
Consolidated purchasing by United States integrated delivery networks is compressing vendor qualification timelines and unbundling after-sales service from hardware procurement. Health systems operating 15-plus surgical sites are centralizing case cart specifications to leverage volume pricing, displacing the previous facility-level capital planning autonomy. This concentration is most visible in Texas and Florida health system expansions, where standardized modular platforms are specified across greenfield ambulatory surgical center buildouts to simplify central supply training and spare parts inventory management.
Global Surgical Case Carts Market Segmentation
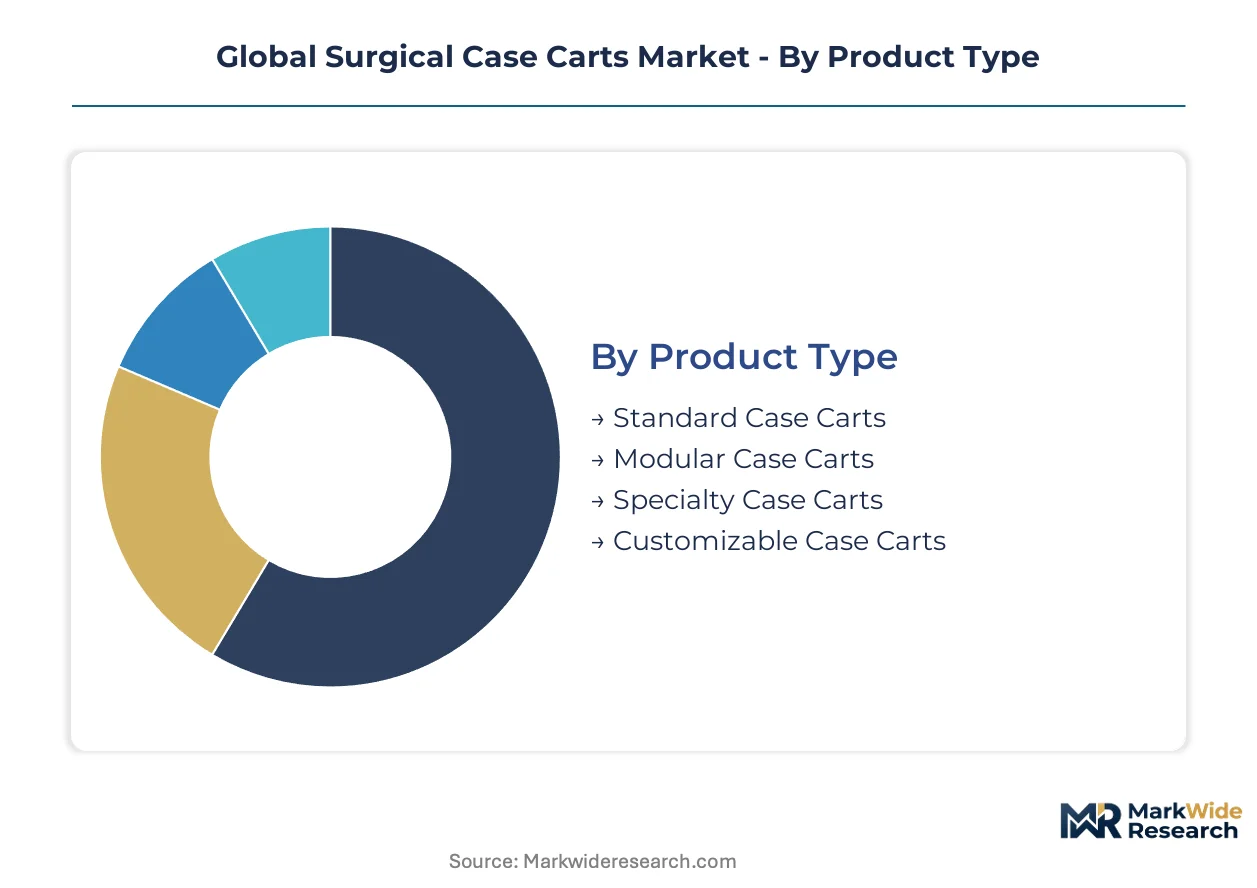
Surgical case cart procurement varies sharply across facility types and procedure requirements. Material selection and modularity drive capital committee decisions more than unit price alone.
Product Type:
Capital committees prioritize configurability against fixed infrastructure constraints.
- Standard Case Carts:Fixed-configuration stainless steel units with welded shelving and sealed gasket doors dominate legacy hospital installations. Demand concentrates in United States health systems completing deferred replacement cycles of aging central supply fleets.
- Modular Case Carts:Reconfigurable platforms with interchangeable shelving, drawer systems, and procedure-specific inserts support multi-specialty surgical suites. Ambulatory surgical centers in Texas and Florida specify these for rapid turnover between ophthalmology and pain management procedures.
- Specialty Case Carts:Purpose-built designs accommodate robotic instrument sets, navigation systems, and implant trays exceeding standard dimensions.
- Customizable Case Carts:Engineer-to-order configurations match unique facility workflows and branding requirements.
Volume sits with Standard Case Carts; growth tilts toward Modular Case Carts.
Material:
Weight reduction and autoclave compatibility frame material trade-offs.
- Stainless Steel:Medical-grade 304 and 316L alloys withstand repeated steam sterilization and aggressive cleaning chemistries. United States hospital infrastructure renewal sustains procurement despite commodity price volatility in nickel and chromium markets.
- Aluminum:Hybrid structures with anodized or powder-coated surfaces cut unit weight by 40-50 percent versus steel equivalents. German and United States ambulatory surgical centers favor these for manual transport and space-constrained storage.
- Plastic Composite:Glass-reinforced polymer enclosures enable RFID signal transmission without metallic interference.
- Carbon Steel:Lower-cost substrates with epoxy or powder coatings serve non-sterile logistics applications.
- Polypropylene:Injection-molded components provide chemical resistance and color-coding for procedure identification.
Installed base concentrates in Stainless Steel; new procurement shifts toward Aluminum and Plastic Composite.
Application:
Instrument set complexity and sterilization frequency determine cart specifications.
- Orthopedic Surgery:Heavy-duty platforms rated for 400-plus pounds accommodate power tools, implant trays, and navigation equipment. United States health systems specify reinforced shelving and locking caster systems for joint replacement case volumes.
- Cardiovascular Procedures:Catheter and stent inventory demands compact, multi-drawer configurations with tamper-evident sealing. German cardiac centers prioritize traceability documentation for high-value consumables.
- Neurosurgery:Microinstrument sets require vibration-dampening inserts and climate-controlled compartments.
- General Surgery:Versatile configurations serve laparoscopic and open procedure diversity.
- Urology:Compact footprints suit cystoscopy and endourology suites with limited floor space.
Procurement volume clusters in Orthopedic Surgery; specification complexity peaks in Cardiovascular Procedures.
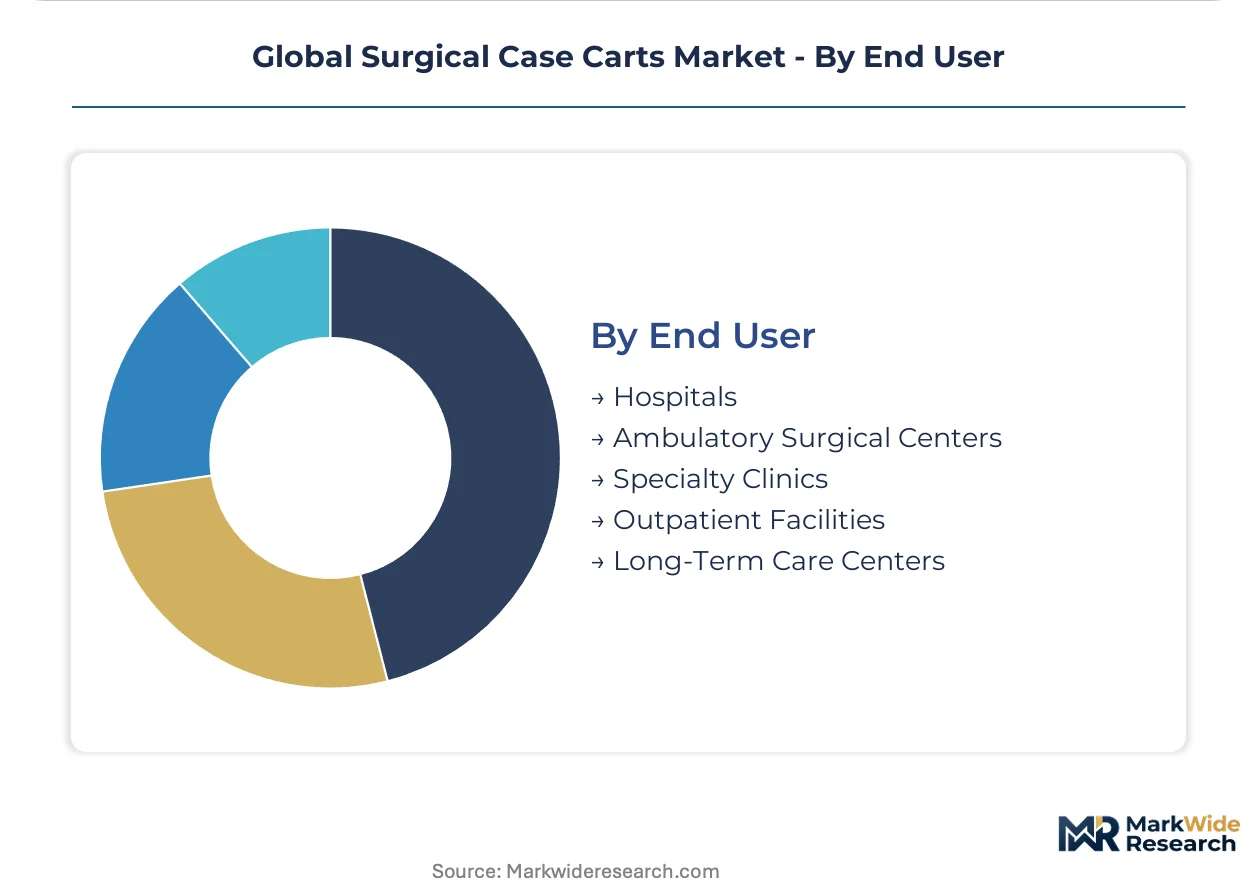
End User:
Facility scale and case mix drive purchasing authority centralization.
- Hospitals:Integrated delivery networks consolidate specifications across 15-plus surgical sites to leverage volume pricing and simplify central supply training. Texas and Florida health system expansions standardize modular platforms across greenfield and renovation projects.
- Ambulatory Surgical Centers:Compact footprints and rapid room turnover requirements favor lightweight, mobile configurations over fixed cabinetry. United States same-day discharge protocols accelerate replacement of legacy storage systems.
- Specialty Clinics:Procedure-focused facilities prioritize dedicated instrument sets for ophthalmology, gastroenterology, or pain management.
- Outpatient Facilities:Freestanding emergency and diagnostic centers require hybrid storage for sterile and clean supplies.
- Long-Term Care Centers:Wound care and minor procedure suites specify basic case cart functionality at reduced capital outlay.
Revenue concentration remains with Hospitals; expansion velocity favors Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for surgical case carts concentrates in health systems completing infrastructure renewal and ambulatory expansion, with procurement patterns diverging sharply between established hospital networks and outpatient-focused facilities.
United States
Texas and Florida health systems are standardizing modular case cart specifications across greenfield ASC buildouts to simplify central supply training. FDA quality system regulation elevates supplier qualification barriers for sterilization validation documentation. Integrated delivery networks in the Southeast are consolidating purchasing across 15-plus surgical sites.
Germany
German cardiac centers prioritize traceability documentation for high-value consumables in catheter and stent inventory management. ECHA enforcement of REACH chemical restrictions on hexavalent chromium plating is reshaping surface treatment specifications in procurement tenders. Bavarian medical device fabricators are accelerating migration to citric acid passivation alternatives.
India
Urban ASC buildouts under Ayushman Bharat are generating demand for compact, lightweight case cart configurations suited to space-constrained facilities. CDSCO medical device registration requirements are extending supplier qualification timelines for imported equipment. Maharashtra's hospital infrastructure clusters are prioritizing mobile storage over fixed cabinetry.
Japan
Japanese orthopedic centers specify vibration-dampening inserts for microinstrument sets in neurosurgery applications. METI sustainability guidelines are influencing material specifications in public hospital procurement. The Kansai region's surgical device distributors are bundling case carts with terminal cleaning workflows.
United Kingdom
UK integrated care systems are consolidating surgical supply specifications across merged hospital trusts to leverage volume pricing. MHRA post-Brexit medical device regulations are creating parallel compliance pathways to CE marking. London's private ASC chains are piloting RFID-integrated polymer composite configurations.
Global Surgical Case Carts Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with sterilization equipment providers bundling hardware alongside standalone fabricators competing on lead times. The vendor base organizes around three archetypes: sterilization ecosystem integrators, configurable platform specialists, and domestic-scale fabricators. M&A activity targets ISO 13485-certified shops to accelerate regulatory qualification, while geographic expansion into Indian ASC markets represents a second competitive vector.
Among Ireland-based sterilization specialists, STERIS plc exemplifies the ecosystem-integrator archetype through bundled terminal cleaning workflows. Capsa Healthcare and Pedigo Products represent contrasting strategic positions within North American fabrication—one anchoring configurable modular platforms, the other competing on domestic manufacturing scale and shortened lead times for hospital capital committees.
| Leading Market Players |
|---|
| STERIS plc |
| Capsa Healthcare |
| Pedigo Products |
| Lakeside Manufacturing |
| MAC Medical |
| Bailida Medical |
| InterMetro Industries Corporation |
| Getinge |
| Future Health Concepts |
| Others |
Supply & Pricing Matrix
Certified welder concentrations in Ohio and Pennsylvania sustain North American fabrication capacity, with labor-cost differentials between union metalworking shops and non-union southern facilities widening pricing-tier spreads for stainless steel case carts versus hybrid aluminum configurations.
Pricing Analysis
Volume concentrates in standard stainless steel configurations while margins accrue to modular platforms with RFID integration. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified fabricators with full bioburden documentation from commodity metalworkers lacking sterilization validation. Pricing pressure stems from nickel and chromium commodity volatility compressing margins on legacy all-steel product lines. Ambulatory surgical centers exhibit highest price sensitivity, prioritizing lightweight aluminum alternatives over premium electropolished finishes.
Supply Chain Analysis
Medical-grade stainless steel supply rests on German, Japanese, and South Korean specialty alloy producers with AS9100 aerospace-medical dual certification. Nickel and chromium feedstocks draw from Indonesian mining operations and Russian refining capacity subject to trade restriction exposure. Electropolishing chemicals and HEPA filtration components hinge on single-source Swiss and German suppliers. Distribution runs through GPO contracts and integrated delivery network central procurement offices rather than facility-level purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. FDA quality system regulation and ISO 13485 certification requirements create a barrier-to-entry moat that protects qualified fabricators from commodity metalworking competition.
For Market Incumbents: Anticipate polymer composite and RFID-integrated configurations displacing stainless steel-centric product lines in ambulatory surgical center procurement. Defend position by accelerating backward integration into polymer compounding capabilities and expanding ISO 13485-certified weld shops in Texas to serve Southeast health system expansions. Prioritize terminal cleaning workflow bundling to capture recurring service revenue beyond hardware sales.
For New Entrants and Emerging Players: Indian ambulatory surgical centers under Ayushman Bharat represent an underserved buyer archetype with compressed qualification timelines versus European market entry. Penetrate this white-space through compact aluminum configurations designed for space-constrained urban facilities. Pursue CDSCO registration partnerships with established distributors to navigate extended supplier qualification timelines for imported equipment.
For Investors and Strategic Acquirers: Re-rating potential sits with ISO 13485-certified regional fabricators given consolidation pressure from integrated delivery networks centralizing specifications across multi-site health systems. Long-term viability favors suppliers with documented bioburden control capabilities and modular platform engineering competencies. Watch ECHA enforcement patterns on REACH chemical restrictions as an inflection indicator for surface treatment technology shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Certification arbitrage creates preferred vendor status with GPO contracts and integrated health systems. |
| Backward Integration into Polymer Compounding | In-house production of glass-reinforced composites reduces RFID signal interference and material cost volatility. |
| Terminal Cleaning Workflow Bundling | Automated washer-disinfector integration with case cart hardware captures recurring service revenue streams. |
| Indian ASC Market Entry Partnership | CDSCO registration alliances with Maharashtra distributors accelerate access to Ayushman Bharat facility buildouts. |
| Citric Acid Passivation Migration | ECHA-compliant surface treatment alternatives replace hexavalent chromium plating for European market access. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with central supply directors, biomedical engineers, GPO contracts managers, and sterilization equipment specialists combined with FDA 510(k) databases, ISO certification registries, and hospital procurement databases. Bottom-up facility-level demand modeling triangulated against top-down health system capital expenditure tracking.
Granularity-level modeling addressed product type, material substrate, procedure application, and end-user facility scale across the projection horizon. CAGRs derived from weighted average of historical replacement cycle analysis and greenfield expansion pipeline tracking. Sterilization validation documentation requirements and REACH chemical restriction enforcement patterns informed regional adoption curve assumptions.
Revisions become necessary when ECHA enforcement intensity on hexavalent chromium plating shifts, FDA quality system regulation guidance updates materialize, or integrated delivery network consolidation accelerates beyond modeled centralization rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Global Surgical Suction Instruments Market