
 Iraq Healthcare (Surgical Procedures) Market | 2026-2036
Iraq Healthcare (Surgical Procedures) Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Healthcare (Surgical Procedures) Market Foresight
Project finance tied to hospital infrastructure rebuilds is reconfiguring competitive entry for surgical equipment vendors. Siemens Healthineers leverages its imaging-surgery integration portfolio to anchor large public hospital tenders in Baghdad. Medtronic specializes in cardiac and minimally invasive device lines that sustain premium positioning among Iraqi specialty hospitals. Albanna Group competes through local distribution control and service networks that dominate aftermarket support across southern governorates.
Iraq Healthcare (Surgical Procedures) encompasses operative interventions performed in clinical settings using instrument sets, anesthesia systems, and patient monitoring equipment with sterility assurance levels matching ISO operating theatre standards. The category serves trauma stabilization, chronic disease correction, and congenital defect repair across Iraq's recovering health infrastructure. General surgery and orthopedic surgery segments lead current procedure volumes, reflecting conflict-legacy trauma burdens and rising road injury incidence. Robotic-assisted technology occupies the fastest-expanding margin pool, though laparoscopic platforms still control the majority of installed bases in Iraqi hospitals. Ambulatory surgical centers represent the emerging channel, with specialty hospitals capturing higher-acuity reconstructive and cardiothoracic cases.
Iraq's Ministry of Health procurement directives and the national pharmaceutical regulator shape import licensing timelines for surgical devices, while WHO prequalification standards increasingly filter eligible suppliers for donor-funded hospital upgrades. The country's central bank foreign exchange procedures affect payment terms for capital-intensive robotic and laparoscopic platforms, compressing margins for distributors without local currency hedging. Stakeholders must monitor how procurement decentralization to governorate health departments alters vendor selection criteria and service contract structures.
Market Dynamics
Iraq's surgical equipment market is restructuring around procurement decentralization to governorate health departments, which fragments vendor selection criteria and compresses payment cycles for capital-intensive platforms.
Growth Catalysts
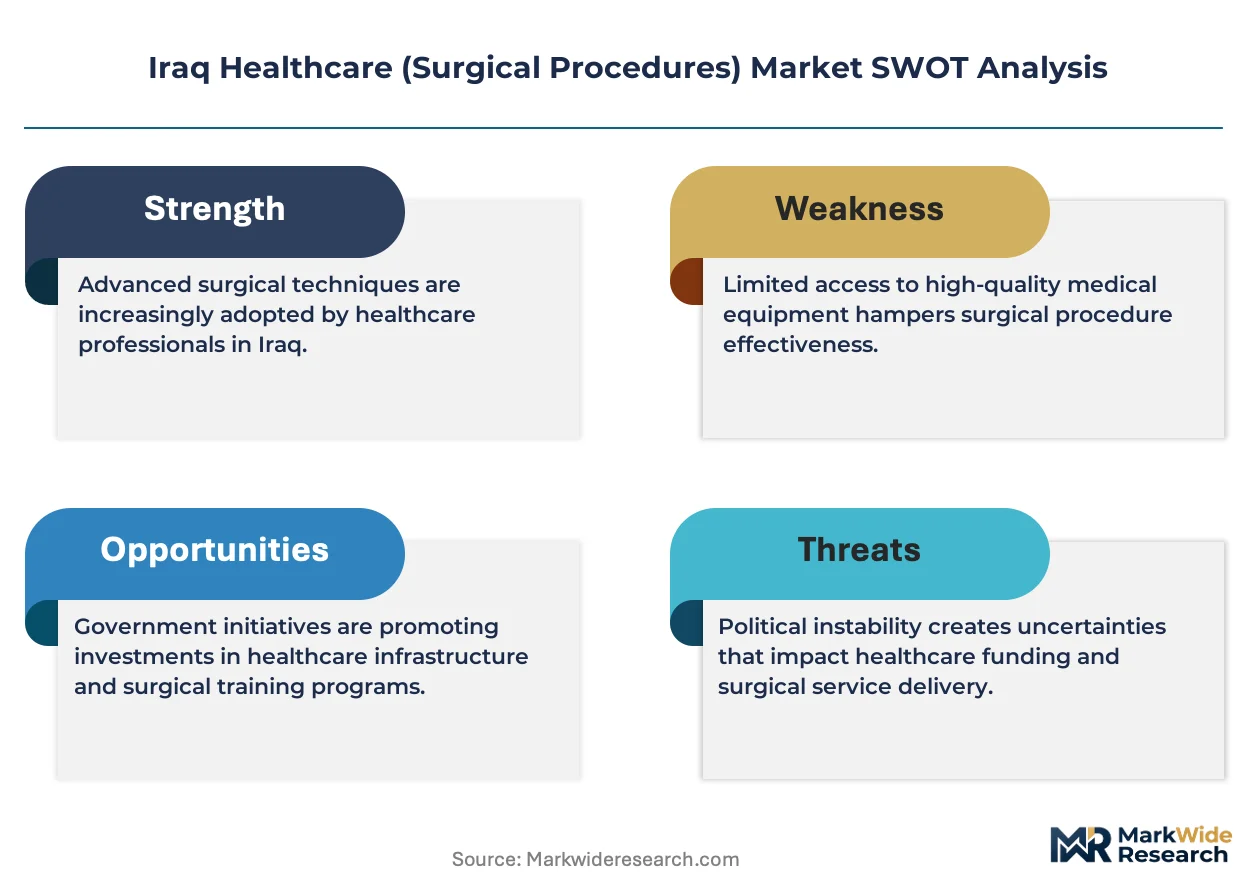
- Ministry of Health Reconstruction Mandates:Baghdad's hospital infrastructure rebuilds prioritize operating theatre modernization, creating sustained demand for integrated surgical suites across public networks.
- Trauma Burden Concentration:Conflict-legacy injuries and rising road accident incidence in southern governorates drive orthopedic and reconstructive procedure volumes.
- Robotic-Assisted Platforms:Da Vinci and comparable systems are penetrating specialty hospitals in Erbil and Basra, expanding margins in cardiothoracic interventions.
Market Restraints
- Foreign Exchange Illiquidity:Central Bank of Iraq procedures delay dollar settlements for robotic and laparoscopic equipment, squeezing distributor margins without local currency hedging.
- Import Licensing Friction:National pharmaceutical regulator timelines extend device approval cycles, particularly for non-WHO-prequalified manufacturers.
- Aftermarket Service Gaps:Technical specialist scarcity outside Baghdad and Basra limits equipment utilization rates in peripheral governorates.
Strategic Opportunities
- Kurdistan Region Specialty Hospitals:Erbil and Sulaymaniyah medical clusters show underpenetrated demand for minimally invasive cardiac platforms.
- Ambulatory Surgical Center Channel:Day-case procedure expansion in Najaf and Karbala creates new volume pools outside traditional hospital procurement.
- Donor-Funded WHO Prequalification:Compliance with international standards unlocks multilateral bank financing for governorate hospital upgrades.
Industry Challenges
- Anesthesiologist and Perioperative Nurse Scarcity:Training pipeline gaps limit surgical throughput expansion despite equipment availability.
- Legacy Imaging-Surgery Integration:PACS and surgical navigation system interoperability failures disrupt workflow efficiency in upgraded Baghdad facilities.
- Sterility Assurance Certification:ISO 14644 cleanroom compliance timelines delay new theatre commissioning in public hospital tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Healthcare (Surgical Procedures) Market |
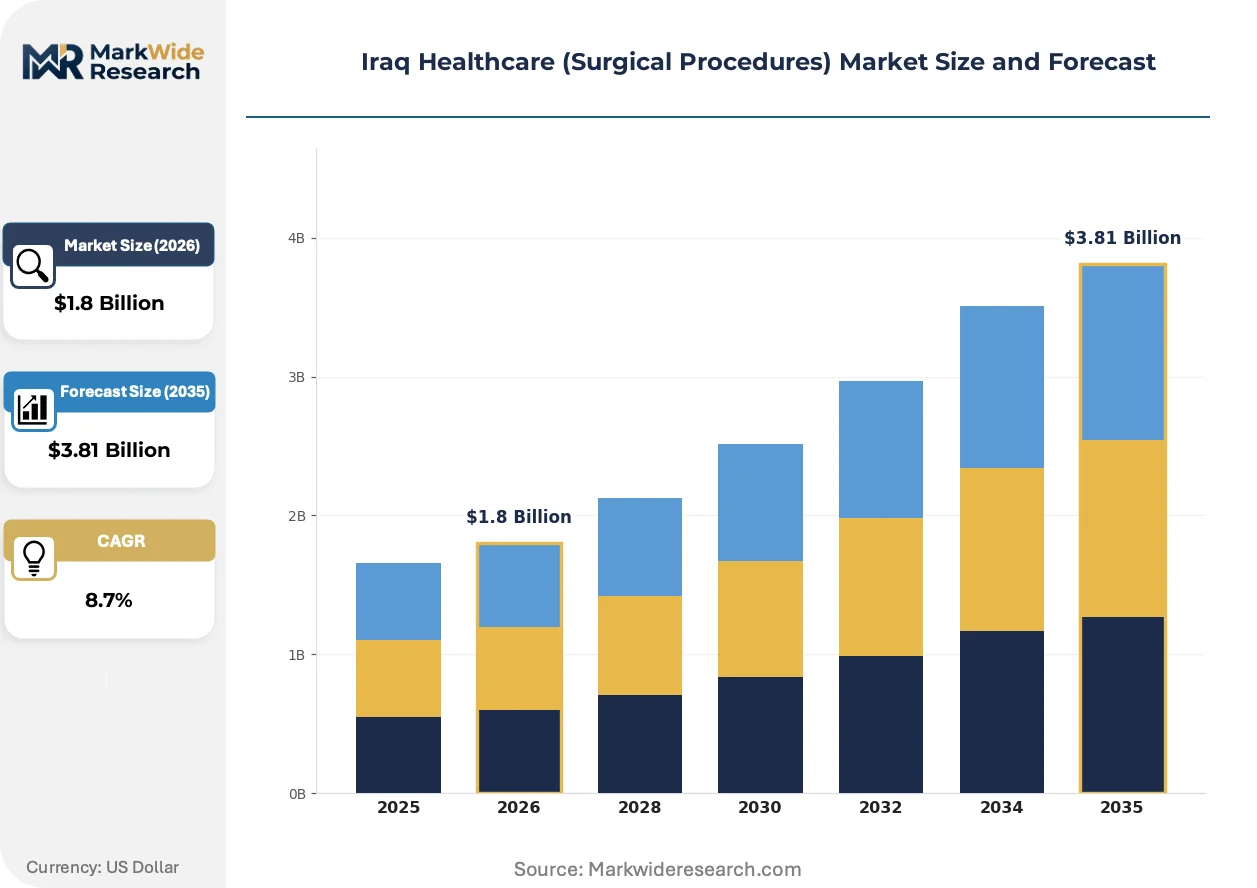
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Neurosurgery Technology: Laparoscopic, Robotic-Assisted, Open Surgery, Endoscopic End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Hospitals Procedure Type: Elective Surgery, Emergency Surgery, Minimally Invasive Surgery, Reconstructive Surgery |
| Companies Covered | Siemens Healthineers, Philips Healthcare, GE Healthcare, Medtronic, Stryker Corporation, Johnson & Johnson, Minas Company, Albanna Group, Baxter, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Healthcare (Surgical Procedures) Market Shifts & Advancements
Digital surgical planning and intraoperative navigation systems are compressing procedure variability while reconfiguring how Iraqi hospitals evaluate capital equipment procurement. Three forces are actively reshaping competitive positioning.
Telemedicine-enabled surgical consultation is virtualizing preoperative assessment workflows in Baghdad teaching hospitals. Rural governorate clinics now connect patients to specialist surgeons for case review without physical transfer. This is virtualizing geographic access barriers that previously concentrated surgical demand in capital city corridors.
Iraq's national pharmaceutical regulator is tightening import licensing requirements for Class III surgical devices, aligning with WHO prequalification standards. Foreign manufacturers face extended documentation demands for biocompatibility and sterilization validation. Specialty hospitals in Basra and Erbil are responding by consolidating procurement through established distributors with regulatory compliance track records.
Service contract unbundling is separating equipment purchase from maintenance obligations in governorate health department tenders. Public hospitals in southern Iraq now negotiate aftermarket support independently of capital acquisition, fragmenting vendor revenue streams. This pattern is most visible in Dhi Qar and Maysan governorates where budget execution pressures force granular cost allocation.
Iraq Healthcare (Surgical Procedures) Market Segmentation
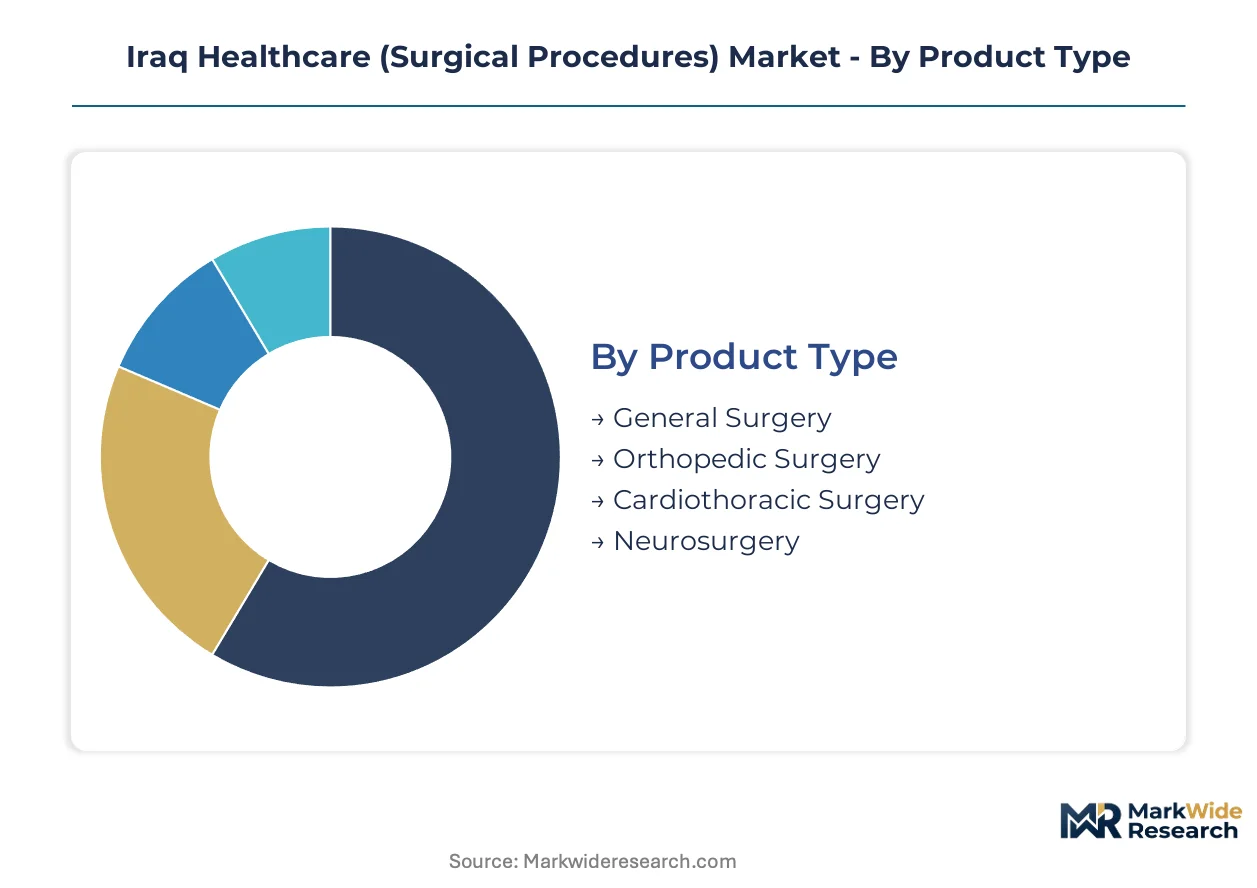
Surgical procedure segmentation in Iraq reveals how trauma burden, technology access, and facility tier interact to shape demand patterns across the recovering health infrastructure. Distinct procurement logics operate in Baghdad's public hospital networks versus Erbil's private specialty clusters.
Product Type:
Use-case spectrum spans trauma stabilization through elective intervention, with conflict-legacy injury patterns concentrating demand in specific surgical disciplines.
- General Surgery:Encompasses abdominal, soft tissue, and wound management procedures using standardized instrument sets and electrocautery platforms. Baghdad public hospitals and Basra trauma centers drive volume through emergency appendectomy, hernia repair, and conflict-legacy wound debridement caseloads.
- Orthopedic Surgery:Fracture fixation, joint replacement, and limb reconstruction procedures deploy trauma implants and arthroscopy systems. Southern governorates—Maysan, Dhi Qar, and Basra—concentrate demand where road injury incidence intersects with limited rehabilitation infrastructure.
- Cardiothoracic Surgery:Valve replacement, coronary bypass, and thoracic tumor resection requiring cardiopulmonary bypass machines. Erbil and Sulaymaniyah specialty hospitals capture higher-acuity cases from across the Kurdistan Region.
- Neurosurgery:Cranial trauma, tumor resection, and spinal stabilization procedures. Limited to Baghdad teaching hospitals and select Erbil facilities due to intraoperative navigation and ICU dependency requirements.
The dominant share belongs to General Surgery, while Orthopedic Surgery is closing the gap fastest.
Technology:
Equipment sophistication tiers map directly to facility capital access and surgeon training density across Iraqi governorates.
- Laparoscopic:Minimally invasive abdominal procedures through trocar access and camera-guided visualization. Controls the majority of installed bases in Iraqi hospitals, with cholecystectomy and diagnostic laparoscopy standard in Baghdad and Basra public networks.
- Robotic-Assisted:Da Vinci and comparable platforms enabling precision suturing in confined anatomical spaces. Specialty hospitals in Erbil and Basra deploy these for prostatectomy and cardiac valve repair where margin structures justify capital intensity.
- Open Surgery:Traditional incision-based approaches for trauma, emergency, and resource-constrained settings. Dominates emergency departments across southern governorates where equipment failure tolerance and speed prioritize reliability.
- Endoscopic:Diagnostic and interventional procedures via natural orifices or small ports. Gastroenterology and ENT applications concentrate in Baghdad's teaching hospital complex.
Robotic-Assisted platforms command premium positioning, though Laparoscopic systems retain volume leadership across governorate health department procurement.
End User:
Facility tier determines reimbursement pathways, equipment financing mechanisms, and case complexity thresholds in Iraq's fragmented health system.
- Hospitals:Ministry of Health public networks and private institutions with full surgical suites and overnight capacity. Baghdad's Kadhimiya and Yarmouk complexes anchor national procedure volume through trauma and emergency mandates.
- Clinics:Outpatient-focused facilities handling minor procedures and preoperative assessment. Urban clusters in Najaf and Karbala concentrate demand for day-case interventions.
- Ambulatory Surgical Centers:Dedicated same-day discharge facilities with streamlined anesthesia protocols. Emerging channel in Najaf and Karbala pilgrimage corridor where elective volume supports standalone economics.
- Specialty Hospitals:Cardiac, orthopedic, or oncology-focused institutions with concentrated expertise. Erbil's private cardiac centers and Basra's trauma specialty units capture complex referrals.
Hospitals retain the dominant procurement footprint, while Ambulatory Surgical Centers are expanding most quickly outside traditional capital city corridors.
Procedure Type:
Clinical urgency and invasiveness dimensions structure staffing requirements, equipment utilization patterns, and payment timelines.
- Elective Surgery:Scheduled interventions for non-life-threatening conditions with predictable resource planning. Hernia repair and joint replacement concentrate in Baghdad and Erbil where diagnostic imaging and specialist availability align.
- Emergency Surgery:Time-critical trauma, hemorrhage control, and acute abdomen procedures. Southern governorate public hospitals absorb conflict-legacy and road trauma caseloads with compressed preparation windows.
- Minimally Invasive Surgery:Reduced-incision techniques prioritizing recovery speed and complication reduction. Laparoscopic and robotic platforms enable this approach in facilities with sterilization assurance and technical specialist coverage.
- Reconstructive Surgery:Defect repair, burn reconstruction, and congenital correction procedures. Baghdad's specialized burn centers and Basra's conflict-legacy trauma units drive demand for microsurgical and grafting capabilities.
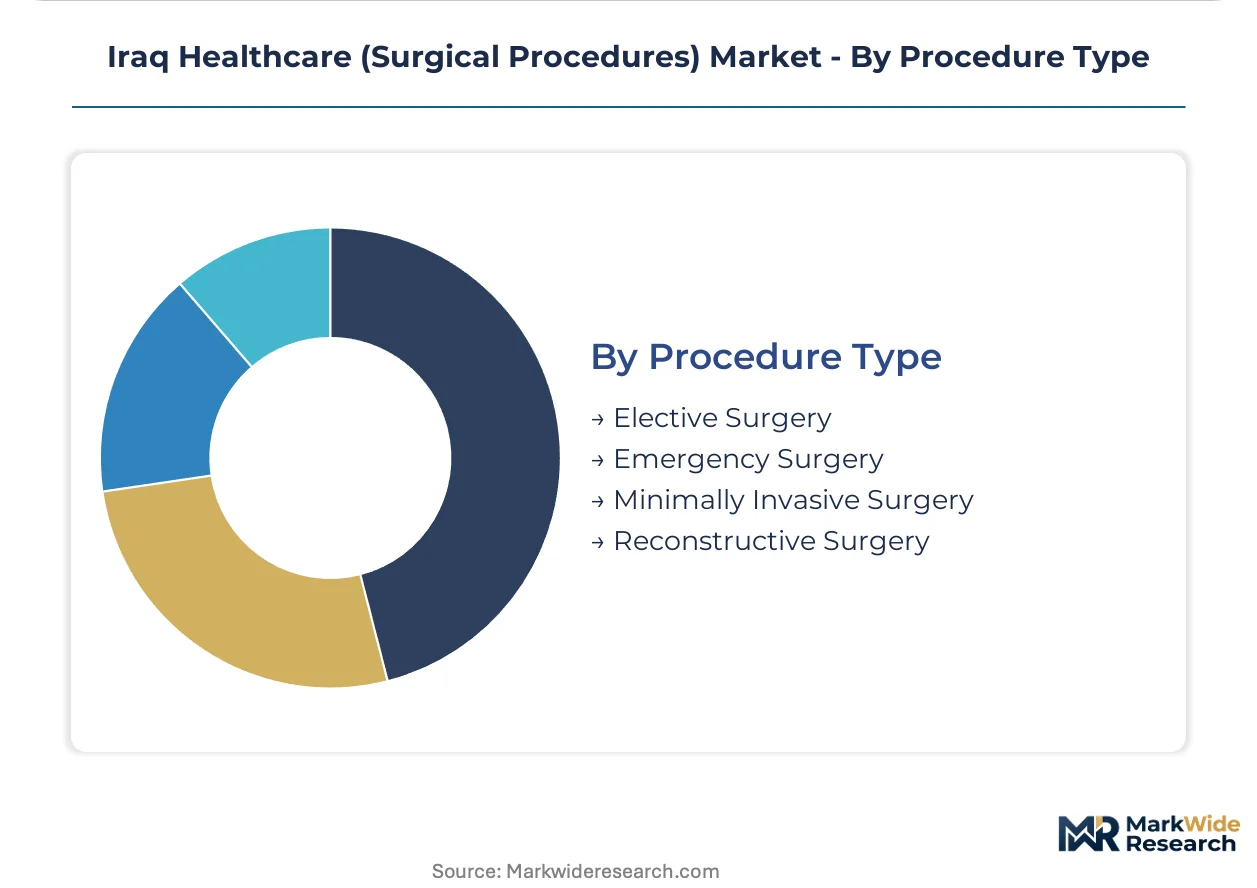
Emergency Surgery dominates public hospital throughput, while Minimally Invasive Surgery is gaining share fastest among private specialty facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Baghdad and Erbil surgical equipment procurement, while southern governorates face compressed margins from foreign exchange illiquidity and extended payment cycles. This asymmetry reshapes vendor geographic prioritization across Iraq's recovering health infrastructure.
Baghdad Governorate
Baghdad's Kadhimiya and Yarmouk hospital complexes anchor national surgical throughput through trauma stabilization and emergency mandates. The Ministry of Health reconstruction directives prioritize operating theatre modernization, channeling capital toward integrated surgical suites. Siemens Healthineers leverages imaging-surgery integration portfolios to anchor large public tenders in these facilities.
Basra Governorate
Road injury incidence and conflict-legacy trauma burdens concentrate orthopedic and reconstructive demand in Basra's public hospital network. The central bank's foreign exchange procedures delay dollar settlements for robotic and laparoscopic equipment, squeezing distributor margins. Albanna Group dominates aftermarket support through local service networks across this southern cluster.
Erbil and Sulaymaniyah
Specialty hospitals in the Kurdistan Region capture higher-acuity cardiothoracic referrals from across northern Iraq. WHO prequalification standards increasingly filter eligible suppliers for donor-funded upgrades in these private medical clusters. Medtronic sustains premium positioning among cardiac and minimally invasive device lines in Erbil's emerging robotic-assisted surgery centers.
Dhi Qar and Maysan Governorates
Budget execution pressures in these southern provinces force service contract unbundling, separating equipment purchase from maintenance obligations. Procurement decentralization to governorate health departments fragments vendor selection criteria. Technical specialist scarcity limits equipment utilization rates, creating aftermarket service gaps that local distributors struggle to fill.
Najaf and Karbala Corridor
Pilgrimage-driven elective volume supports standalone ambulatory surgical center economics in these shrine cities. Day-case procedure expansion creates new volume pools outside traditional hospital procurement channels. Sterility assurance certification delays from ISO 14644 cleanroom compliance timelines slow new theatre commissioning in this emerging channel.
Iraq Healthcare (Surgical Procedures) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper margin capture in specific procedure categories. The vendor base organizes around three strategic archetypes: multinational imaging-surgery integrators anchoring Baghdad public tenders, cardiac and minimally invasive device specialists commanding premium positioning in Erbil specialty hospitals, and local distribution networks dominating aftermarket support across southern governorates. Competitive moves concentrate on procurement compliance track records with Iraq's national pharmaceutical regulator and service network geographic density outside capital city corridors.
Within the multinational integrator tier, Siemens Healthineers, Philips Healthcare, and GE Healthcare occupy positions shaped by imaging-surgery convergence and large public hospital tender participation. Siemens Healthineers exemplifies the imaging-surgery integration archetype through its portfolio breadth in Baghdad reconstruction mandates. Philips Healthcare and GE Healthcare represent parallel positioning in diagnostic-to-therapeutic workflow capture. Among device specialists, Medtronic and Stryker Corporation sit within premium-tier minimally invasive and orthopedic segments. Medtronic anchors cardiac device positioning in Kurdistan Region specialty hospitals. Local distribution control concentrates with Albanna Group across southern governorates, where service network density determines competitive viability.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Philips Healthcare |
| GE Healthcare |
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson |
| Minas Company |
| Albanna Group |
| Baxter |
| Others |
Supply & Pricing Matrix
Undercapacity in robotic-assisted surgical platforms across Dhi Qar and Maysan governorates drives supplier prioritization toward Baghdad and Erbil, concentrating pricing power in facilities with foreign exchange liquidity while peripheral markets absorb extended payment cycles and compressed margins.
Pricing Analysis
Configured-to-order pricing for integrated surgical suites commands substantial premiums over standard laparoscopic instrument sets in Iraqi public hospital tenders. Three-tier pricing structure across premium, standard, and economy levels reflects WHO prequalification status, aftermarket service bundling, and local currency settlement terms. Pricing pressure stems from Central Bank of Iraq foreign exchange illiquidity delaying dollar settlements, which squeezes distributor margins without hedging mechanisms. Ministry of Health public networks exhibit highest price sensitivity due to budget execution pressures, while Erbil specialty hospitals accept premium positioning for robotic-assisted cardiac platforms.
Supply Chain Analysis
Tariff exposure between manufacturing hubs in Germany, the United States, and China dominates supply chain risk calculus for Iraqi surgical equipment procurement. Component sourcing draws from precision instrumentation clusters in Germany, electromechanical assemblies in China, and specialized polymers in the United States. Single-source vulnerability concentrates in intraoperative navigation software and robotic arm actuators where patent-protected designs limit supplier alternatives. Distribution runs through Dubai-based regional hubs into Baghdad and Basra, with local distributors like Albanna Group controlling last-mile service networks across southern governorates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iraq's surgical equipment market rewards vendors who bridge technical specialist scarcity with regulatory compliance track records, as anesthesiologist and perioperative nurse gaps constrain throughput expansion despite capital equipment availability.
For Market Incumbents: Insulate service revenue streams from equipment purchase unbundling by securing multi-year aftermarket contracts with governorate health departments before tender fragmentation accelerates. Deepen backward integration into sterilization assurance certification to compress ISO 14644 cleanroom commissioning delays that disrupt theatre activation timelines. Anchor imaging-surgery integration portfolios in Baghdad reconstruction mandates to defend against Philips Healthcare and GE Healthcare tender participation. For New Entrants and Emerging Players: Ambulatory surgical centers in Najaf and Karbala represent the most penetrable entry point, as pilgrimage-driven elective volume supports standalone economics outside entrenched hospital procurement channels. WHO prequalification compliance unlocks donor-funded governorate upgrades in Dhi Qar and Maysan where incumbent service gaps persist. Partner with established local distributors possessing central bank foreign exchange facilitation capabilities rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic-assisted surgery platforms as software-defined functionality and disposable instrument recurring revenue reshape unit economics. Acquisition targets should emphasize distributors with governorate-level service network density and regulatory compliance track records rather than pure equipment traders. Monitor Central Bank of Iraq foreign exchange auction volumes as the critical signal for distributor working capital stress and margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Compliance unlocks multilateral bank financing for governorate hospital reconstruction mandates. |
| Hospital System Partnership | Integration with Baghdad's Kadhimiya and Yarmouk complexes secures trauma procedure volume anchors. |
| Service Network Expansion | Technical specialist deployment in Basra and Erbil addresses aftermarket gaps limiting equipment utilization. |
| Software Companion Development | Telemedicine-enabled surgical consultation virtualizes preoperative assessment workflows in rural clinics. |
| Reimbursement Strategy | Alignment with Ministry of Health procurement directives shapes import licensing timeline competitiveness. |
Research Methodology
Desk research of hospital procurement databases, GPO contracts, and WHO prequalification registries preceded structured interviews with biomedical engineers, hospital purchasing committee members, and governorate health department procurement officers. Primary fieldwork with surgical equipment distributors in Baghdad, Basra, and Erbil validated secondary estimates of installed base counts and utilization rates. Bottom-up procedure volume modeling triangulated against top-down Ministry of Health budget allocation data.
Assumptions regarding Ministry of Health reconstruction mandate continuity, central bank foreign exchange regime stability, and WHO prequalification standard adoption trajectory were held fixed across the projection horizon. Segmentation dimensions modeled include procedure type, technology tier, end-user facility category, and regional governorate cluster. CAGRs were derived from equipment replacement cycles, procedure volume elasticity to capacity expansion, and technology substitution patterns in cardiac and orthopedic interventions.
Macroeconomic conditions sit as an overlay; deviation in oil revenue flows, dinar-dollar exchange rate volatility, or multilateral donor funding commitments would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline standardization and technical training pipeline expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Laparoscopic Sutures Market