
 Ocular Pain Market | 2026-2036
Ocular Pain Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Pain Market Outlook
Preservative-free formulations are shifting cost structures across the ocular pain landscape, compelling manufacturers to reformulate legacy portfolios. Alcon Vision LLC leverages its manufacturing scale to sustain supply chain control over multi-dose preservative-free eye drops. Bausch + Lomb Corporation anchors its competitive stance through geographic dominance in North American retail pharmacy channels. Sun Pharmaceutical Industries Ltd. differentiates via R&D intensity in generic ophthalmic injectables.
Ocular pain encompasses acute and chronic discomfort arising from corneal, conjunctival, uveal, or orbital tissue injury, inflammation, or surgical intervention, typically measured on validated scales such as the Ocular Surface Disease Index or visual analog scores. The condition drives therapeutic development targeting nociceptor modulation, anti-inflammatory pathways, and barrier restoration to preserve visual function and patient compliance. Eye drops command the largest volume share within product type segments due to immediate topical access and established reimbursement, while intravitreal delivery mode segments capture disproportionate margin pools owing to specialist administration requirements and biologic payload complexity. Post-surgical pain therapy areas are expanding fastest as cataract and refractive procedure volumes rise across aging populations.
FDA ophthalmic guidance and USP sterility standards govern formulation purity, container closure integrity, and endotoxin limits for all products entering the United States market. The EPA regulates active pharmaceutical ingredient discharge from manufacturing facilities, adding environmental compliance costs that filter into pricing structures. Stakeholders must monitor evolving preservative-free mandates and biologic delivery innovations to calibrate portfolio priorities against shifting clinical and regulatory benchmarks.
Market Dynamics
Preservative-free formulation mandates from the FDA are forcing manufacturers to rebuild legacy portfolios around single-use and multi-dose barrier technologies, compressing margins while elevating sterility assurance requirements across ophthalmic supply chains.
Growth Catalysts
- Post-surgical procedure volumes:Cataract and refractive surgery expansion across aging populations in the United States, Germany, and Japan generates sustained demand for acute ocular pain management protocols.
- EMA MDR compliance deadlines:European medical device regulation timelines are accelerating CE-marked ophthalmic device submissions, pulling forward investment in validated pain delivery systems.
- Nociceptor-targeting biologics:Anti-nerve growth factor and TRPV1 modulator pipelines are advancing through Phase II trials, offering mechanism-specific alternatives to corticosteroid drops.
Market Restraints
- API manufacturing concentration:Active pharmaceutical ingredient production for ophthalmic anesthetics concentrates in Indian and Chinese chemical hubs, exposing formulators to export licensing volatility and geopolitical friction.
- Preservative-free packaging costs:Blow-fill-seal and COMOD pump technologies require specialized barrier materials that raise per-unit costs versus traditional benzalkonium chloride formulations.
- Intravitreal administration bottlenecks:Retinal specialist availability limits patient throughput for depot corticosteroid and anti-VEGF pain adjuncts in rural and secondary hospital settings.
Strategic Opportunities
- Brazilian regulatory acceleration:ANVISA's streamlined ophthalmic generic approval pathways enable faster market entry for preservative-free drop portfolios previously validated under FDA or EMA standards.
- Home-based monitoring convergence:Smartphone-enabled visual analog scale apps paired with connected drop dispensers create adherence data streams for chronic dry eye pain management.
- Veterinary ophthalmology extension:Companion animal cataract surgery growth in the United States and United Kingdom opens adjacent revenue pools for reformulated human-grade analgesics.
Industry Challenges
- Aseptic manufacturing workforce scarcity:Qualified personnel for isolator-based filling lines and environmental monitoring remain concentrated in established pharmaceutical clusters, constraining capacity expansion timelines.
- Container closure integrity validation:USP 1207 sterility test method transitions from probabilistic to deterministic leak detection require capital-intensive equipment upgrades and protocol redevelopment.
- Biologic-cold chain integration:Temperature-sensitive protein payloads for intravitreal pain modulation demand parallel distribution infrastructure that conflicts with standard ambient ophthalmic logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Pain Market |
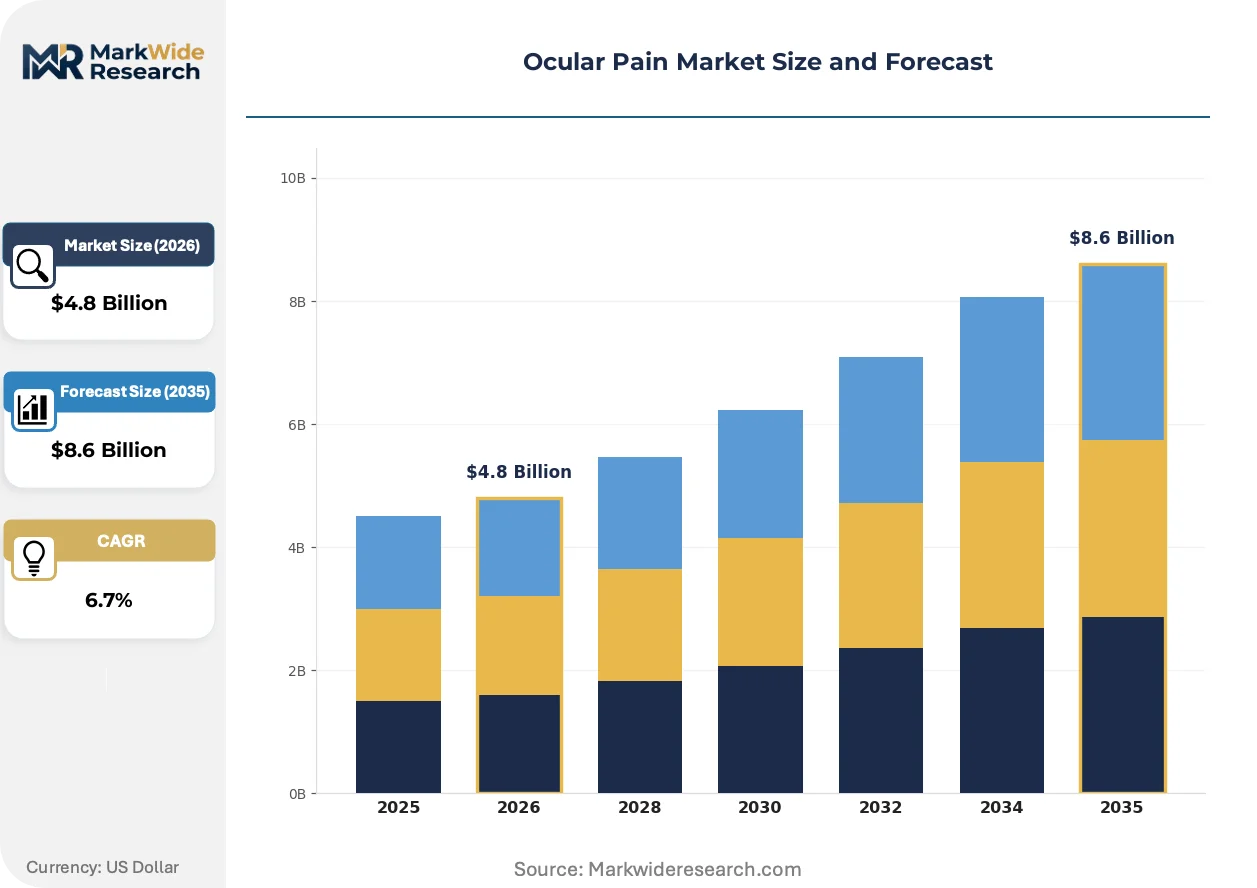
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eye Drops, Ointments, Oral Medications, Injections Therapy Area: Dry Eye Syndrome, Glaucoma, Allergic Conjunctivitis, Post-Surgical Pain End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Delivery Mode: Topical, Systemic, Intravitreal, Periocular |
| Companies Covered | Alcon Vision LLC, Bausch + Lomb Corporation, Sun Pharmaceutical Industries Ltd., AbbVie Inc., Ocular Therapeutix, Inc., KALA BIO, Inc., Formosa Pharmaceuticals, Aldeyra Therapeutics, Inc., Sylentis S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Pain Market Strategic Shifts
Formulation science and delivery mechanism engineering are converging to redefine therapeutic index expectations, with manufacturers competing on residence time extension and patient-administration ergonomics rather than molecule novelty alone.
Preservative-free multi-dose systems employing silver-ion or polyquaternium-1 antimicrobial barriers are overtaking single-use vials in chronic pain indications where daily dosing frequency would otherwise generate prohibitive plastic waste and pharmacy fulfillment costs. Academic medical centers in the United States and university hospitals in Germany are standardizing these platforms for post-keratoplasty regimens. The shift is compressing demand for traditional unit-dose production lines while expanding contract manufacturing organization capacity for barrier technology assembly.
FDA guidance on ophthalmic drug product quality, issued in draft form and now under finalization review, elevates extractables and leachables testing for plastic primary packaging components. The industrial consequence is a 12-18 month extension in ANDA submission preparation timelines as legacy stability data requires supplementation. Generic manufacturers with pre-validated polymer qualification protocols are capturing disproportionate regulatory approval velocity versus competitors initiating extractables studies de novo.
Direct-to-patient subscription models for chronic dry eye therapies are disrupting traditional retail pharmacy fulfillment in the United States, with tele-ophthalmology platforms bundling diagnostic screening, prescription authorization, and 90-day supply auto-refill. The model displaces wholesaler margins and shifts inventory risk to vertically integrated service providers. Concentration is highest in Sun Belt states where dry eye prevalence and telehealth penetration rates intersect most favorably.
Ocular Pain Market Segmentation
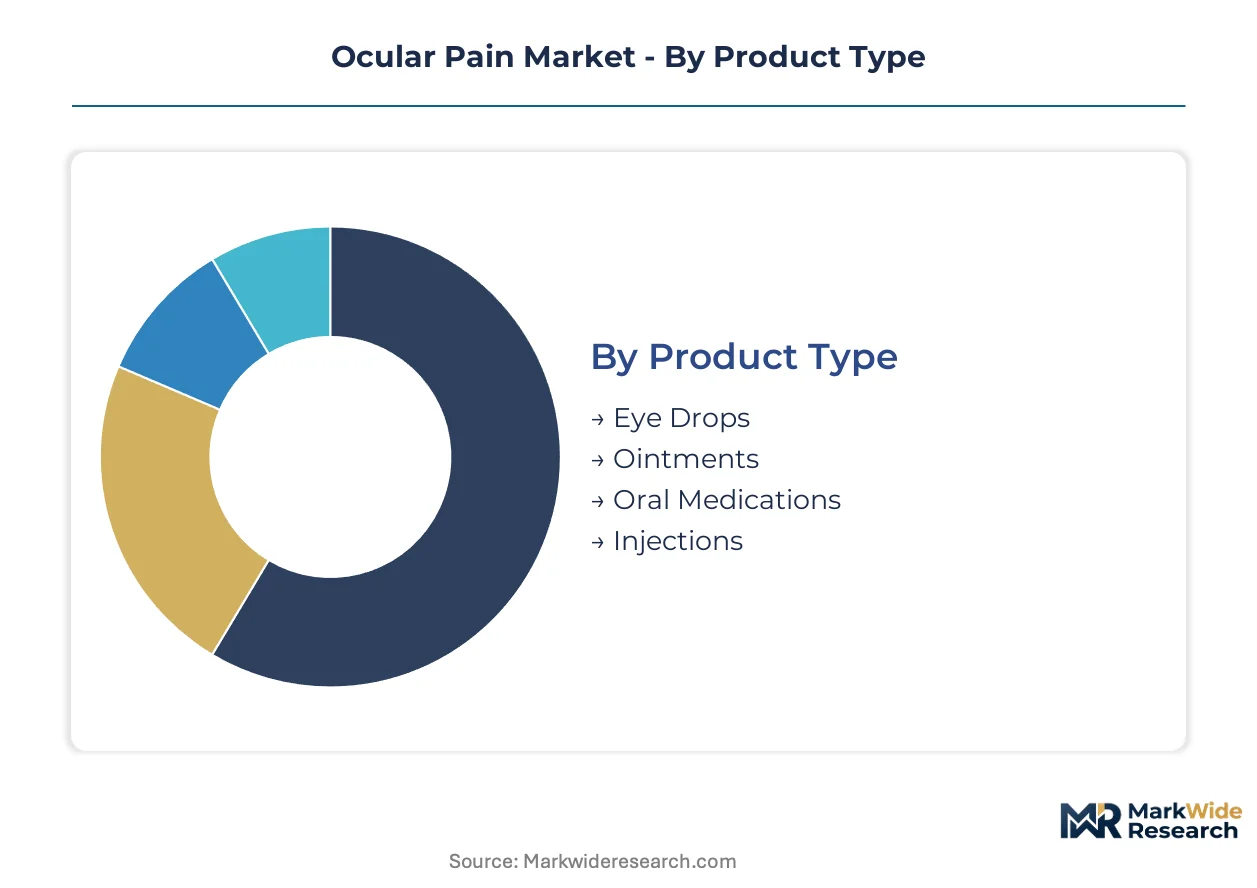
Ocular pain therapeutics fragment across four critical dimensions that determine reimbursement pathways, manufacturing complexity, and patient access. Each category reflects distinct technical barriers and commercial concentration patterns that shape portfolio strategy.
Product Type:
Customization versus standardization tensions surface most acutely in formulation engineering, where preservative-free mandates force capital-intensive retooling of legacy production lines.
- Eye Drops:Aqueous and emulsion-based solutions delivering immediate topical relief through corneal penetration. Demand concentrates in United States retail pharmacy channels where preservative-free multi-dose systems displace benzalkonium chloride formulations under FDA guidance. Reformulation costs and blow-fill-seal technology investments compress margins for generic manufacturers lacking pre-validated polymer protocols.
- Injections:Intravitreal and periocular depot formulations including corticosteroids and anti-VEGF adjuncts administered by retinal specialists. Patient throughput limits in rural hospital settings constrain volume expansion despite superior efficacy for chronic uveitic pain. Cold chain requirements for biologic payloads conflict with ambient ophthalmic distribution infrastructure.
- Ointments:Semi-solid petrolatum or mineral oil bases extending residence time on nocturnal ocular surfaces.
- Oral Medications:Systemic NSAIDs and neuropathic agents prescribed for orbital pain refractory to topical therapy.
Leading the category by volume: Eye Drops. Growing fastest: Injections.
Therapy Area:
Procedure volume trajectories and chronic disease prevalence split investment priorities across acute intervention and long-term maintenance indications.
- Post-Surgical Pain:Acute nociceptive management following cataract extraction, keratoplasty, and refractive procedures. Cataract surgery expansion across aging United States, German, and Japanese populations generates sustained protocol demand. Academic medical centers standardize multimodal regimens combining topical NSAIDs with intravitreal depot corticosteroids.
- Dry Eye Syndrome:Chronic neuropathic and inflammatory discomfort addressed through tear film stabilization and nociceptor modulation. Sun Belt states in the United States show highest tele-ophthalmology subscription penetration where smartphone-enabled visual analog scale apps pair with connected dispensers.
- Glaucoma:Pain secondary to elevated intraocular pressure or surgical intervention.
- Allergic Conjunctivitis:Seasonal and perennial mast cell-mediated pruritus and discomfort.
Post-Surgical Pain commands the largest revenue pool. Dry Eye Syndrome shows the steepest expansion trajectory.
End User:
Site-of-care economics and reimbursement differentials concentrate margin capture in institutional settings while home-based models disrupt traditional fulfillment.
- Hospitals:Inpatient and ambulatory surgical centers performing cataract, corneal transplant, and retinal procedures. Ophthalmology departments expand dedicated pain management protocols with specialist-administered intravitreal injections capturing disproportionate margin pools.
- Specialty Pharmacies:Vertically integrated distributors managing prior authorization, cold chain logistics, and patient adherence programs for biologic and depot formulations.
- Clinics:Office-based ophthalmology and optometry practices.
- Home Care:Self-administered chronic therapies with telehealth oversight.
Hospitals dominate value capture. Specialty Pharmacies are gaining share fastest through biologic distribution integration.
Delivery Mode:
Administration expertise requirements and anatomical targeting precision create tiered barriers to competitive entry.
- Topical:Patient or caregiver-administered drops and ointments accessing anterior segment structures. Immediate accessibility and established reimbursement sustain volume leadership despite residence time limitations.
- Intravitreal:Specialist-administered injections delivering payloads to posterior segment and vitreous cavity. Retinal specialist availability bottlenecks in secondary hospital settings constrain throughput expansion.
- Systemic:Oral or parenteral routes for orbital and neuropathic pain.
- Periocular:Sub-Tenon's and retrobulbar injections offering intermediate anatomical targeting.
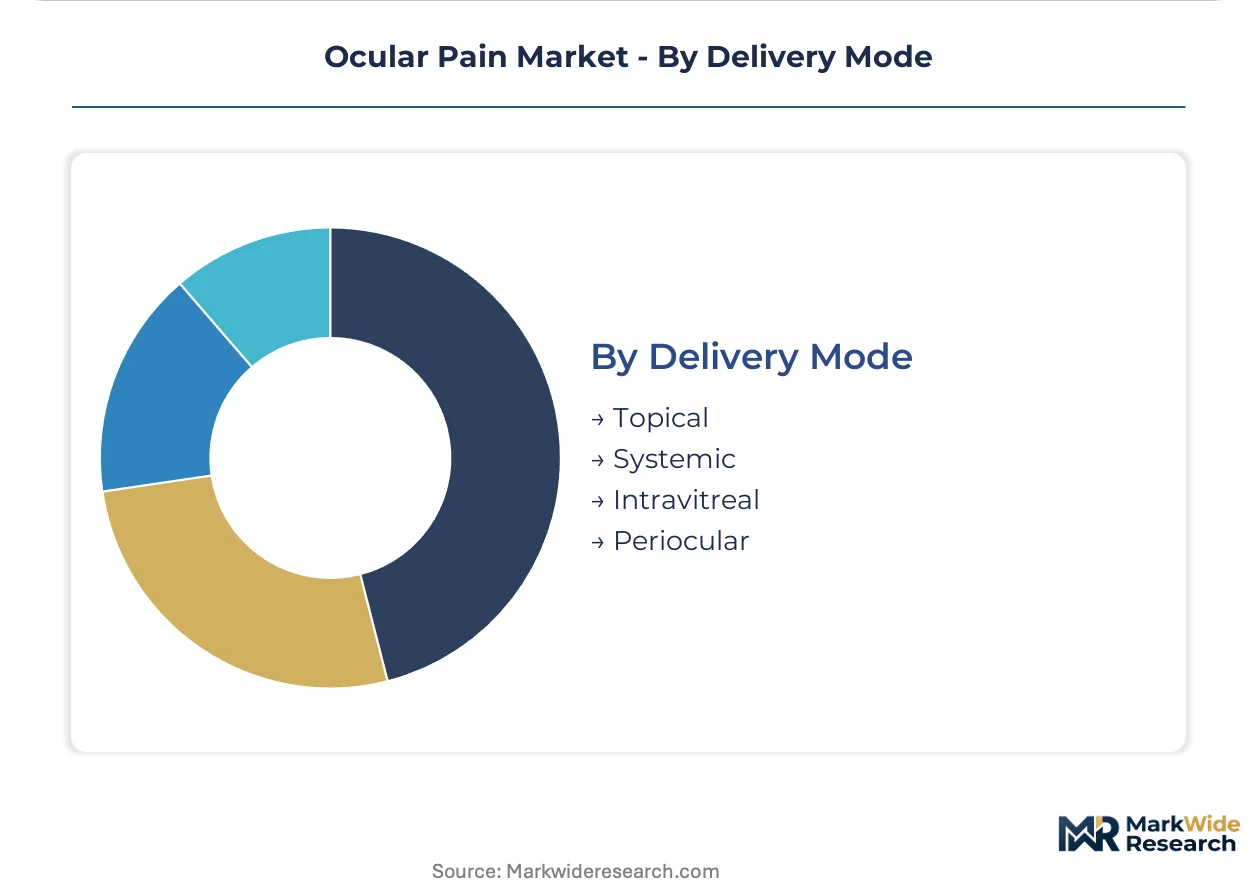
Topical delivery maintains volume supremacy. Intravitreal administration climbs fastest on biologic pipeline advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers concentrate the highest procedure volumes for post-surgical ocular pain management, with demand clustering around cataract and refractive surgery corridors. FDA preservative-free formulation mandates are redirecting manufacturing investment toward specialized barrier technologies.
United States
Cataract surgery expansion across aging populations drives sustained demand for acute pain protocols in Sun Belt states. FDA ophthalmic guidance elevates extractables and leachables testing requirements for plastic primary packaging. Academic medical centers in Boston and Baltimore standardize multimodal regimens combining topical NSAIDs with intravitreal depot corticosteroids.
Germany
University hospitals advance nociceptor-targeting biologic pipelines through Phase II trials. EMA MDR compliance deadlines accelerate CE-marked ophthalmic device submissions. The Rhine-Ruhr and Baden-Württemberg clusters host specialized contract manufacturing organizations for barrier technology assembly.
Japan
Aging demographics sustain refractive procedure volumes requiring post-surgical pain management. PMDA sterility standards govern formulation purity and container closure integrity for domestic market entry. The Kanto region around Tokyo concentrates retinal specialist practices administering intravitreal depot formulations.
Brazil
Companion animal cataract surgery growth opens adjacent revenue pools for reformulated human-grade analgesics. ANVISA streamlined ophthalmic generic approval pathways enable faster market entry for preservative-free portfolios. São Paulo state anchors veterinary ophthalmology extension strategies for multinational formulators.
India
Active pharmaceutical ingredient production for ophthalmic anesthetics concentrates in chemical hubs around Gujarat and Maharashtra. CDSCO export licensing requirements expose formulators to geopolitical friction in API supply chains. Hyderabad and Mumbai manufacturing clusters supply generic injectables to regulated markets.
Ocular Pain Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers rebuild legacy formulations around preservative-free mandates. The vendor base separates into three tiers: multinational ophthalmic specialists with integrated manufacturing, generic pharmaceutical houses with R&D intensity in injectables, and biologic developers advancing mechanism-specific pipelines. Strategic archetypes include scale-driven barrier technology suppliers, geography-anchored retail pharmacy channel controllers, and nociceptor-targeting pipeline specialists. M&A activity and capacity expansion for blow-fill-seal lines represent the dominant competitive moves.
Within the multinational specialist tier, Alcon Vision LLC and Bausch + Lomb Corporation occupy positions reflecting manufacturing scale and North American channel control respectively. Sun Pharmaceutical Industries Ltd. sits within the generic-intensive archetype, while Ocular Therapeutix, Inc. and KALA BIO, Inc. exemplify biologic pipeline developers. These five entities represent the competitive spectrum from legacy formulation reformulation to novel delivery mechanism engineering.
| Leading Market Players |
|---|
| Alcon Vision LLC |
| Bausch + Lomb Corporation |
| Sun Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Ocular Therapeutix, Inc. |
| KALA BIO, Inc. |
| Formosa Pharmaceuticals |
| Aldeyra Therapeutics, Inc. |
| Sylentis S.A. |
| Others |
Value Chain & Pricing Dynamics
Academic medical centers in the United States and university hospitals in Germany concentrate procurement volumes for preservative-free ocular pain formulations, anchoring contract-based long-term offtake agreements that compress margins for generic manufacturers lacking pre-validated polymer protocols. Pricing stratifies across premium barrier technology tiers, standard benzalkonium chloride legacy formulations, and economy generic drops, with cost compression in the standard tier intensifying due to FDA extractables testing mandates.
Pricing Analysis
Volume leadership in topical drops generates thin margins per unit while intravitreal injections capture premium pricing through specialist administration requirements and biologic payload complexity. Price differentiation hinges on certification grade—FDA-validated preservative-free barrier systems command substantial premiums over legacy formulations—and geographic delivery cost differentials between domestic blow-fill-seal capacity and imported unit-dose alternatives. Pricing pressure stems from EMA MDR compliance deadlines accelerating European device submissions. Retail pharmacy channels show highest price sensitivity; hospital ophthalmology departments demonstrate lowest sensitivity due to bundled reimbursement protocols.
Supply Chain Analysis
Qualified personnel for isolator-based filling lines and environmental monitoring concentrate in established pharmaceutical clusters around Hyderabad and Mumbai in India, the Rhine-Ruhr region in Germany, and the Boston-Baltimore corridor in the United States. Raw material dependencies include specialized barrier polymers for COMOD pump systems, silver-ion antimicrobial additives, and active pharmaceutical ingredients for ophthalmic anesthetics. Supply chain risk centers on single-source vulnerability for blow-fill-seal equipment manufacturers. Distribution runs through vertically integrated specialty pharmacies managing cold chain logistics for biologic payloads alongside traditional wholesale channels for ambient-stable formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ocular pain market has become a vertical-integration race as manufacturers pursue captive supply of preservative-free barrier polymers to escape margin compression from specialized material suppliers.
For Market Incumbents: Deploy backward integration into polymer qualification protocols to defend against generic entrants with pre-validated extractables data. Alcon Vision LLC and Bausch + Lomb Corporation should expand blow-fill-seal capacity in FDA-registered facilities while accelerating ANDA submission timelines through legacy stability data supplementation. Channel control through specialty pharmacy partnerships offers additional defensive positioning against direct-to-patient subscription disruptors. For New Entrants and Emerging Players: Tele-ophthalmology platforms represent the most penetrable route for chronic dry eye pain management in Sun Belt states where smartphone-enabled adherence apps intersect with high prevalence rates. Veterinary ophthalmology extension in São Paulo state and companion animal corridors in the United Kingdom offers white-space revenue with lower regulatory barriers than human-grade reformulations. ANVISA's streamlined generic approval pathways enable faster Brazilian market entry for portfolios previously validated under FDA standards. For Investors and Strategic Acquirers: The window for entry favors contract manufacturing organizations with pre-installed barrier technology assembly lines and validated isolator-based filling capacity. Long-term viability hinges on sterility assurance capabilities rather than molecule novelty alone. Acquisition targets should demonstrate established polymer qualification protocols and environmental monitoring workforce depth. The signal to watch is FDA finalization of ophthalmic drug product quality guidance, which will accelerate consolidation among generic manufacturers lacking supplemental extractables data.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Technology Manufacturing Scale-Up | Blow-fill-seal capacity expansion in FDA-registered facilities captures preservative-free mandate tailwinds. |
| Polymer Qualification Protocol Investment | Pre-validated extractables and leachables data accelerates ANDA approval velocity against de novo competitors. |
| Specialty Pharmacy Distribution Partnership | Cold chain integration for biologic payloads displaces traditional wholesale margin capture. |
| Veterinary Ophthalmology Extension | Companion animal surgery growth in São Paulo and UK corridors opens adjacent revenue pools. |
| Tele-ophthalmology Platform Integration | Direct-to-patient subscription models disrupt retail pharmacy fulfillment in high-prevalence Sun Belt states. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors supplied qualitative calibration. FDA 510(k) submissions, EMA CE marking databases, ClinicalTrials.gov entries, and ANVISA approval registries provided validation checkpoints. Bottom-up patient population modeling and top-down pharmaceutical spending allocation were reconciled through iterative triangulation across stakeholder perspectives.
Data-stream reconciliation across procedure volume projections, pricing surveys, and supply chain capacity assessments shaped the analytical framework. Segmentation dimensions included product type, therapy area, delivery mode, and regional regulatory cluster. CAGRs were derived from log-linear trend fitting across the projection horizon, with cross-validation against hospital admission data for cataract and refractive procedures. Forecast inputs incorporated PMDA sterility standard evolution and EMA MDR compliance timeline acceleration.
The model holds under stable FDA preservative-free guidance implementation and continued retinal specialist availability; deviation in API export licensing volatility or geopolitical friction in Indian and Chinese chemical hubs would shift volume and value trajectories. Forecasts reflect documented assumptions regarding procedure volume expansion and barrier technology adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Uveal Melanoma Treatment Market
Ophthalmology
Retina Health Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Age-Related Macular Degeneration Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market