
 Global Pain Management and Surgical Devices Market | 2026-2036
Global Pain Management and Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pain Management and Surgical Devices Market Foresight
Buyer concentration among hospital systems and ambulatory networks is shifting procurement leverage toward larger integrated delivery organizations across North America and Europe. Medtronic leverages its neurostimulation portfolio to anchor premium positioning in spinal cord stimulation, while Boston Scientific Corporation competes through differentiated waveforms and MRI-conditional device architectures. Abbott sustains technology leadership in dorsal root ganglion therapy, extending its footprint in targeted pain modulation.
Pain management and surgical devices encompass pharmaceutical analgesics, implantable neurostimulators, cannabinoid formulations, and precision surgical instruments engineered for tissue sparing and reduced postoperative trauma. Neurostimulation devices incorporate rechargeable pulse generators with multi-programmable parameters, serving patients with neuropathic conditions unresponsive to conventional pharmacotherapy. Analgesics and neurostimulation devices occupy the largest revenue pools, reflecting established reimbursement pathways, while bioelectronic medicine represents the fastest-expanding technology segment as developers pioneer closed-loop autonomic nerve modulation. Minimally invasive surgery instruments command premium pricing through reduced recovery metrics and lower complication profiles.
FDA premarket approval pathways for Class III neurostimulation devices impose extensive clinical evidence requirements that filter market entrants and elevate compliance costs. CE marking under the EU MDR demands renewed technical documentation and post-market surveillance, reshaping competitive access across European member states. ISO 13485 quality management standards govern manufacturing consistency for surgical instrument producers supplying regulated markets. Stakeholders must monitor evolving reimbursement criteria for outpatient pain procedures and anticipate how bioelectronic platforms will challenge conventional pharmaceutical and interventional paradigms.
Market Dynamics
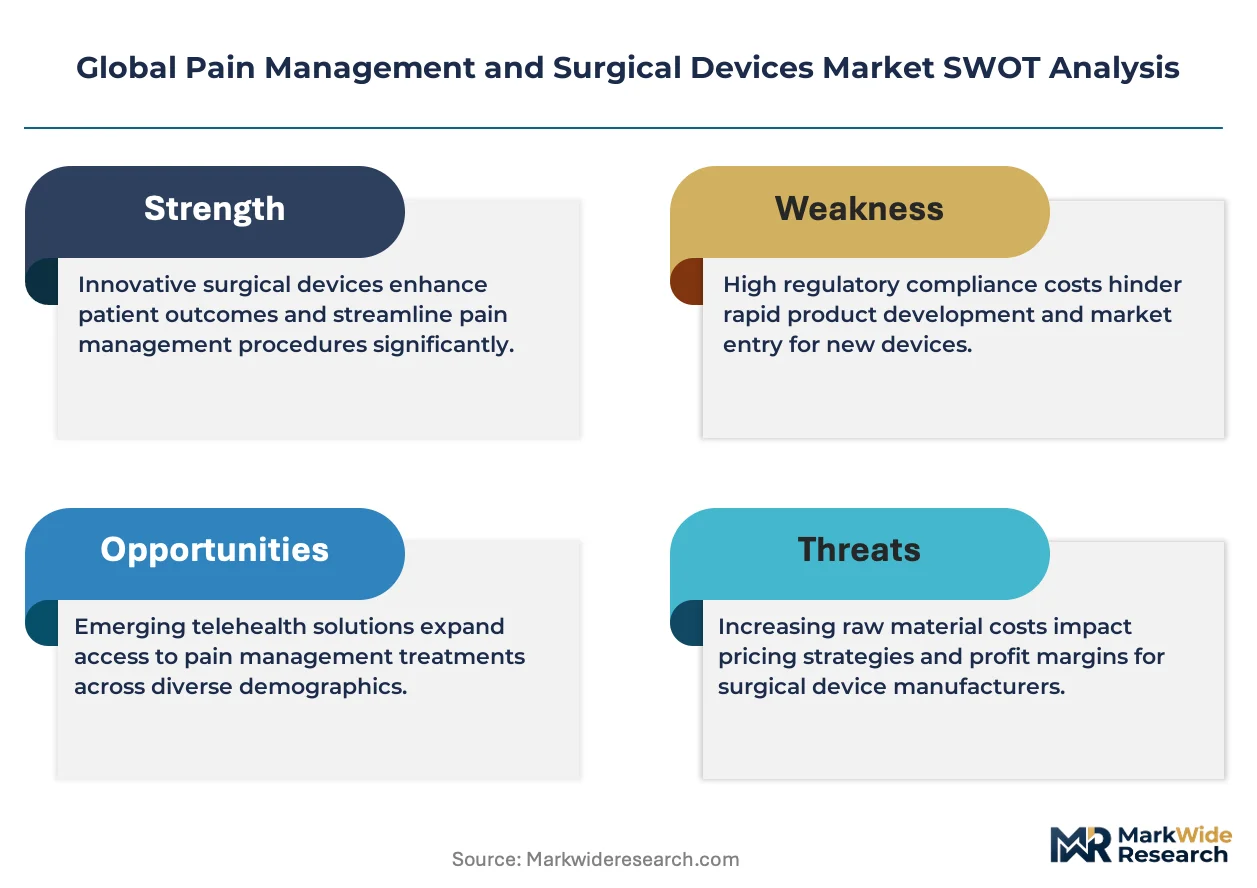
Hospital procurement consolidation is compressing vendor margins and forcing device manufacturers to restructure their commercial organizations around integrated delivery networks rather than individual hospital accounts.
Growth Catalysts
- Ambulatory surgical center expansion:Payer mandates for same-day discharge are routing chronic pain procedures to outpatient settings, expanding addressable volume for portable neurostimulation systems and minimally invasive instruments.
- FDA breakthrough device designation:Accelerated review pathways for closed-loop bioelectronic platforms are compressing time-to-market for novel autonomic nerve modulation therapies targeting treatment-resistant neuropathic pain.
- EU MDR implementation:Stricter post-market surveillance requirements are filtering marginal competitors and creating market share vacuums for manufacturers with robust clinical evidence portfolios.
Market Restraints
- Platinum-iridium electrode supply concentration:Refining capacity for neurostimulation electrode materials clusters in South Africa and Russia, exposing manufacturers to geopolitical input cost volatility.
- Reimbursement pathway fragmentation:CMS national coverage determinations for spinal cord stimulation lag behind FDA approvals, creating multi-year commercialization gaps between regulatory clearance and payer adoption.
- Pharmacological substitution:Long-acting local anesthetic formulations and sustained-release opioid alternatives retain entrenched formulary positions in postoperative pain management.
Strategic Opportunities
- Home healthcare channel penetration:Remote patient monitoring integration with implantable pulse generators enables decentralized chronic pain management outside traditional clinical settings.
- Japan's aging demographic:PMDA fast-track reviews for geriatric-focused neurostimulation indications are opening priority access for dorsal root ganglion therapy in lumbar radiculopathy.
- Closed-loop AI convergence:Machine learning algorithms paired with autonomic nerve recording electrodes enable real-time therapeutic adjustment, differentiating next-generation platforms from open-loop predecessors.
Industry Challenges
- Bioelectronic medicine talent scarcity:Cross-functional expertise spanning neural engineering, embedded systems, and clinical neuroscience concentrates in Boston and San Francisco clusters, constraining R&D scaling.
- ISO 14155 clinical trial complexity:Multinational investigational device exemption studies for Class III neurostimulators require harmonized ethics approvals across divergent national competent authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pain Management and Surgical Devices Market |
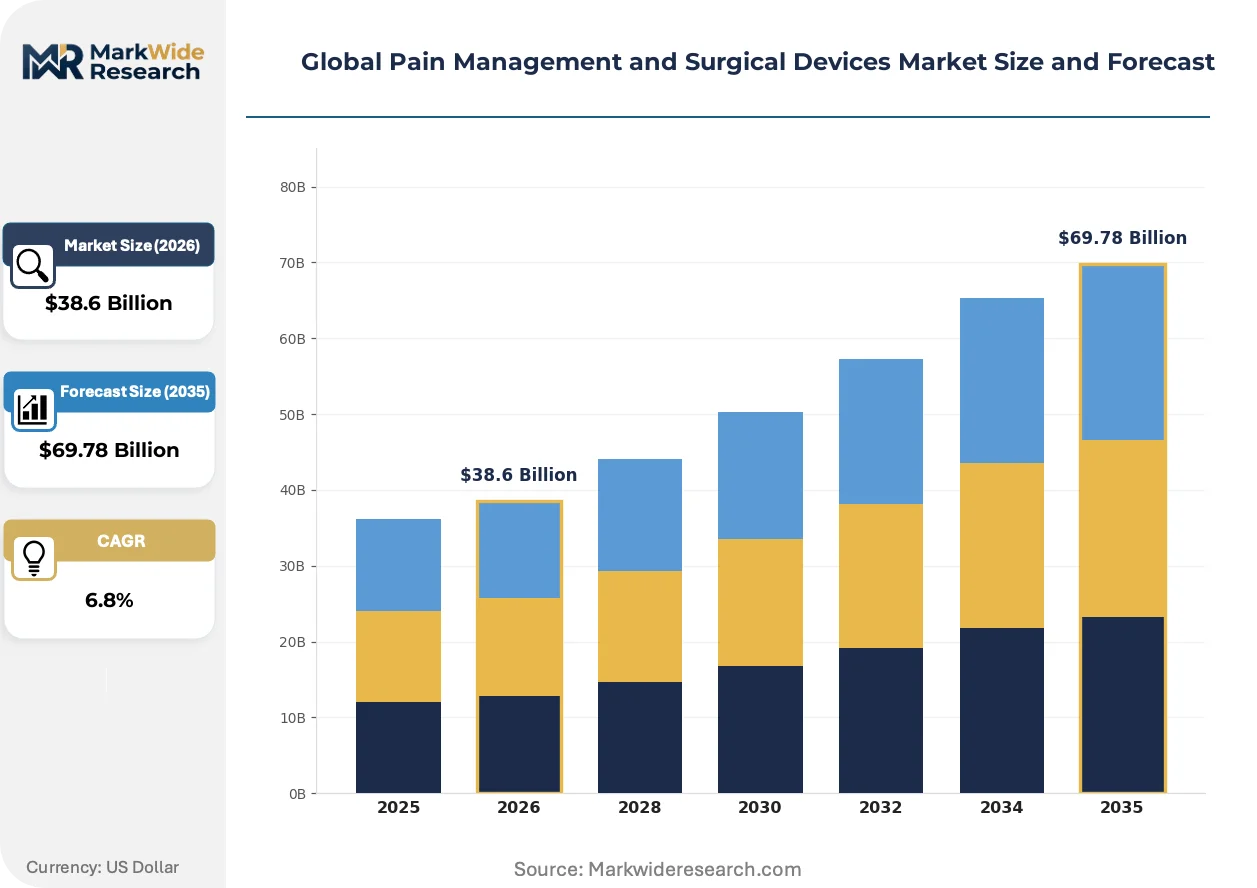
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Cannabinoids, Neurostimulation Devices, Surgical Instruments Technology: Transcutaneous Electrical Nerve Stimulation, Pulsed Radiofrequency, Bioelectronic Medicine, Minimally Invasive Surgery Application: Chronic Pain Management, Postoperative Pain Relief, Cancer Pain Control, Pediatric Pain Treatment End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Clinics, Home Healthcare |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Stryker, Baxter, B Braun Melsungen AG, Nevro Corp, ICU Medical, Enovis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pain Management and Surgical Devices Market Shifts & Advancements
Digital health integration is collapsing the boundary between implantable hardware and software-driven therapeutic optimization, forcing traditional device manufacturers to build data science capabilities.
Closed-loop neurostimulation architectures are modularizing previously monolithic pulse generator designs. Academic medical centers in Germany and the Netherlands are piloting detachable sensing modules that upgrade existing implants without generator replacement. This modularity is compressing replacement cycle revenue while expanding upgrade attach rates.
EU MDR technical documentation requirements are reshaping European market access economics. Manufacturers must renew clinical evidence for legacy devices or withdraw from member state markets, accelerating portfolio rationalization. Small-cap neurostimulation specialists without MDR transition resources are exiting the region, consolidating share among larger competitors.
Integrated delivery networks are unbundling device procurement from procedural service contracts. Hospital systems in Texas, Florida, and Ohio are negotiating direct manufacturer agreements that bypass traditional distributor markups. This disintermediation is most visible in high-volume spinal cord stimulation programs where standardization across system-owned facilities generates procurement leverage.
Global Pain Management and Surgical Devices Market Segmentation
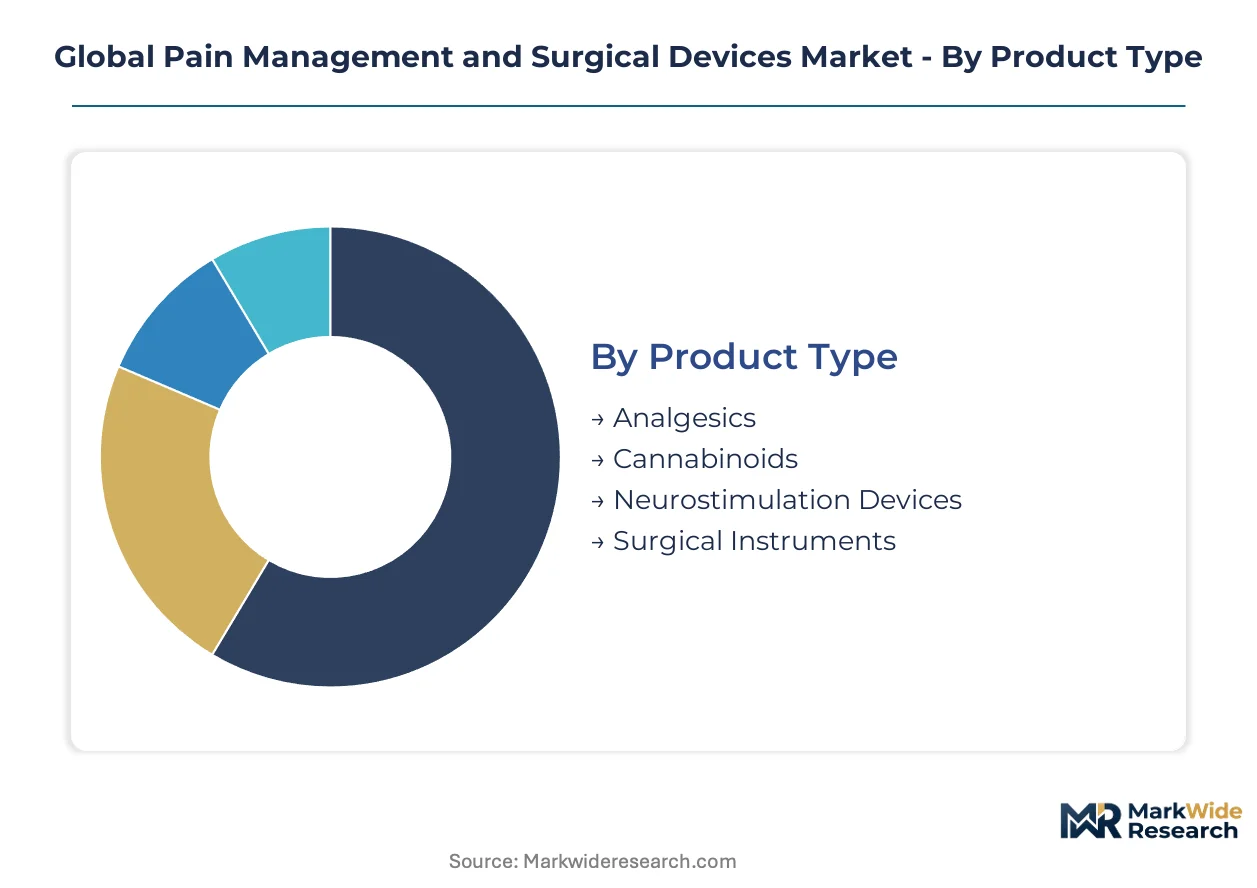
Pain management and surgical devices fragment across therapeutic modality, intervention invasiveness, and care setting. Each segmentation axis reveals distinct procurement patterns, reimbursement pathways, and technology maturity curves that shape vendor strategy.
Product Type:
Composition and mechanism of action differentiate therapeutic platforms, with delivery systems ranging from systemic pharmacology to implanted electrotherapy hardware.
- Analgesics:Small-molecule formulations span non-opioid NSAIDs, acetaminophen derivatives, and controlled opioid agonists. Hospital formularies in Germany and Japan retain entrenched positions for intravenous multimodal protocols despite payer pressure to reduce opioid exposure.
- Neurostimulation Devices:Implantable pulse generators with multi-contact electrode arrays deliver targeted electrical modulation to spinal cord or peripheral nerve targets. Ambulatory surgical centers in Texas and Florida are routing implant procedures to outpatient settings, compressing recovery metrics and expanding same-day discharge eligibility.
- Cannabinoids:Plant-derived and synthetic cannabinoid formulations target neuropathic pain pathways through CB1/CB2 receptor modulation. Regulatory frameworks in Canada and select US states create fragmented commercial access despite expanding clinical evidence portfolios.
- Surgical Instruments:Precision-engineered tools for tissue-sparing dissection, nerve decompression, and lesioning procedures. Japanese manufacturers dominate high-volume production of disposable radiofrequency cannulae and specialized access needles.
Mature deployment sits with analgesics. Newer deployment is concentrated in neurostimulation devices.
Technology:
Energy delivery modality and intervention invasiveness stratify platforms across risk-reward profiles and reimbursement tiers.
- Minimally Invasive Surgery:Percutaneous and endoscopic approaches reduce tissue trauma through specialized access systems and image-guided navigation. German academic medical centers are pioneering augmented reality overlay integration for precision lesion targeting.
- Bioelectronic Medicine:Closed-loop autonomic nerve modulation platforms combine sensing electrodes with adaptive algorithms for real-time therapeutic adjustment. PMDA fast-track designation in Japan is accelerating clinical validation for gastric and vagus nerve applications.
- Transcutaneous Electrical Nerve Stimulation:Surface-applied electrical modulation devices for non-invasive pain management. Home healthcare channels in the United Kingdom and Australia are expanding direct-to-patient distribution for chronic low back pain protocols.
- Pulsed Radiofrequency:Non-thermal electromagnetic energy delivery for nerve modulation without neuronal damage. Outpatient pain clinics in South Korea are adopting cooled RF platforms for sacroiliac joint denervation procedures.
Established clinical acceptance centers on minimally invasive surgery. Steepest expansion trajectory belongs to bioelectronic medicine.
Application:
Pain etiology and patient population define therapeutic intensity, duration, and regulatory scrutiny requirements.
- Chronic Pain Management:Long-term intervention for neuropathic, nociceptive, and mixed pain syndromes exceeding three months duration. Integrated delivery networks in Ohio are consolidating spinal cord stimulation procurement across multi-facility systems.
- Postoperative Pain Relief:Acute intervention protocols spanning multimodal analgesia, regional anesthesia, and non-pharmacological adjuncts. Enhanced recovery after surgery programs in France are standardizing non-opioid-first pathways for orthopedic procedures.
- Cancer Pain Control:Palliative and disease-modifying interventions addressing tumor-related nociception and treatment-associated neuropathy. Hospice networks in Italy are expanding neurolytic block procedures for refractory visceral pain.
- Pediatric Pain Treatment:Age-appropriate dosing, device sizing, and developmental considerations for neonatal through adolescent populations. Regulatory requirements from FDA and EMA impose additional safety and efficacy evidence thresholds.
Volume concentration rests with chronic pain management. Regulatory complexity peaks in pediatric pain treatment.
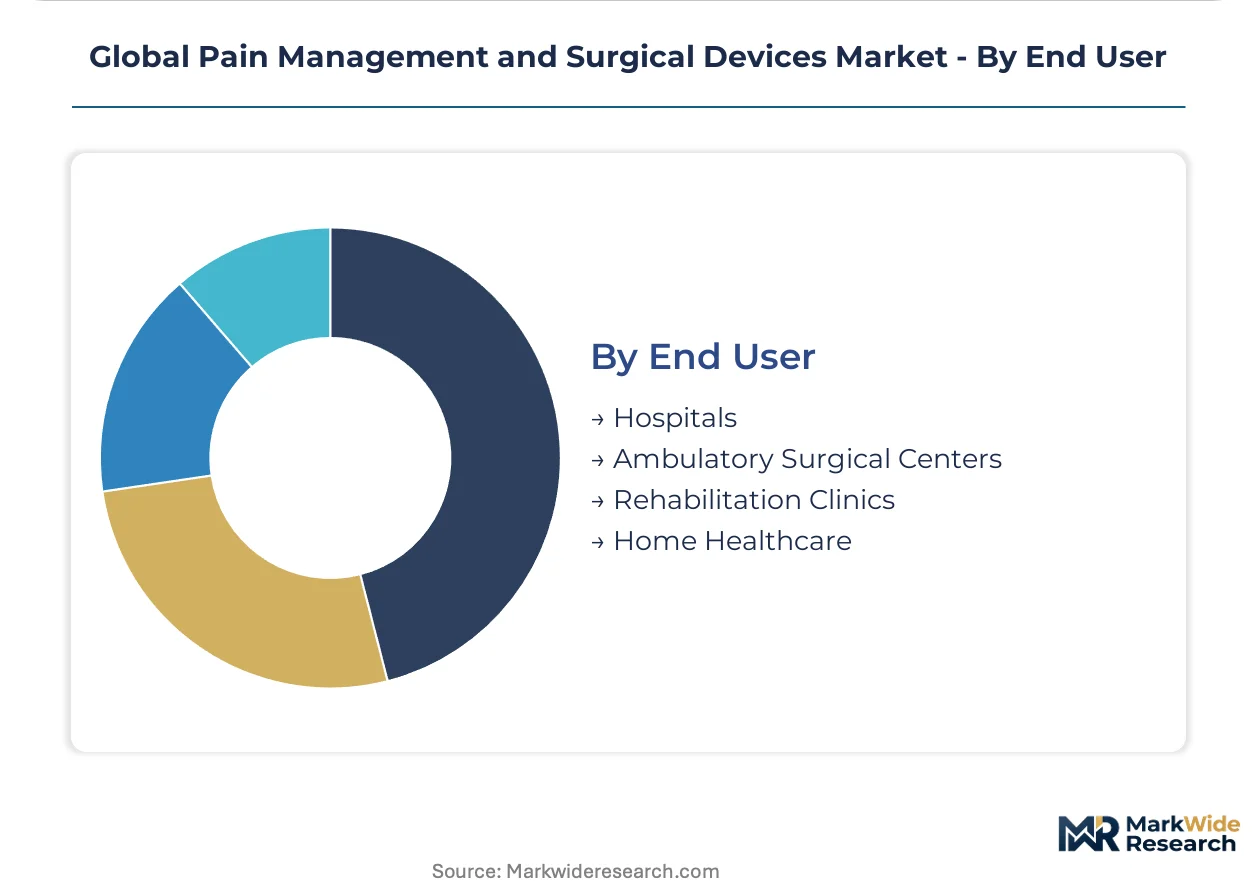
End User:
Care setting determines capital equipment requirements, staffing models, and reimbursement mechanism structures.
- Hospitals:Comprehensive inpatient and outpatient capabilities spanning acute intervention, complex implantation, and multidisciplinary pain programs. Tertiary centers in Switzerland and the Netherlands maintain referral networks for revision neurostimulation procedures.
- Ambulatory Surgical Centers:Focused outpatient facilities optimized for same-day procedures with reduced overhead structures. CMS reimbursement shifts in the United States are accelerating case migration from hospital outpatient departments.
- Rehabilitation Clinics:Post-acute and chronic management settings emphasizing functional restoration and non-interventional modalities. Physical therapy networks in Spain are integrating TENS and therapeutic ultrasound into standardized protocols.
- Home Healthcare:Decentralized delivery of portable devices, remote monitoring, and patient-administered therapies. Telehealth integration platforms in Denmark are enabling remote programming of implantable pulse generators.
Procurement leverage aggregates with hospitals. Fastest channel expansion is occurring in ambulatory surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems concentrate procurement leverage for implantable neurostimulation systems, while Germany and Japan anchor European and Asian demand for precision surgical instruments. Regulatory fragmentation across FDA, EMA, and PMDA jurisdictions shapes divergent commercialization timelines for bioelectronic platforms.
United States
Integrated delivery networks in Texas and Florida are consolidating spinal cord stimulation procurement across multi-facility systems. FDA breakthrough device designation for closed-loop autonomic nerve modulation compresses premarket review timelines. Minneapolis and Boston clusters concentrate neurostimulation R&D talent and pulse generator manufacturing.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia are expanding minimally invasive pain procedures under statutory health insurance reimbursement. EU MDR implementation demands renewed technical documentation for legacy implantable devices. Tübingen and Heidelberg academic medical centers pilot detachable sensing modules for neurostimulator upgrades.
Japan
PMDA fast-track reviews for geriatric-focused dorsal root ganglion therapy accelerate market access for lumbar radiculopathy indications. METI funding programs support domestic bioelectronic medicine startups in Kansai and Chubu regions. Osaka-based manufacturers dominate high-volume production of disposable radiofrequency cannulae.
Switzerland
Tertiary centers in Zurich and Geneva maintain referral networks for revision neurostimulation procedures across Alpine Europe. Swissmedic maintains alignment with EU MDR standards while preserving independent market authorization pathways. Basel and Zug clusters concentrate precision surgical instrument engineering for tissue-sparing dissection tools.
Australia
Home healthcare channels in New South Wales and Victoria are expanding direct-to-patient distribution for transcutaneous electrical nerve stimulation devices. TGA parallel review pathways with FDA accelerate regulatory convergence for implantable pulse generators. Sydney medical device distributors are disintermediating traditional procurement channels for ambulatory pain clinics.
Global Pain Management and Surgical Devices Market Competitive Landscape
United States producers anchor the premium neurostimulation tier; German and Swiss specialists hold precision surgical instrument positioning. The vendor base concentrates around three strategic archetypes: diversified conglomerates with full pain management portfolios, pure-play neurostimulation innovators, and regional surgical instrument fabricators. M&A activity targets bioelectronic medicine capabilities, while geographic expansion into Japanese and Australian markets accelerates through distributor acquisition.
Within the diversified conglomerate tier, Medtronic and Boston Scientific Corporation exemplify scale-driven positioning across implantable pulse generators and spinal cord stimulation systems. Abbott occupies a position within targeted neuromodulation therapy, representing the specialized innovation archetype focused on dorsal root ganglion applications.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Stryker |
| Baxter |
| B Braun Melsungen AG |
| Nevro Corp |
| ICU Medical |
| Enovis |
| Others |
Supply & Pricing Matrix
Captive electrode refining in South Africa and Russia anchors neurostimulation manufacturers to concentrated upstream positions, amplifying pricing power for platinum-iridium suppliers while compressing margins for device producers serving integrated delivery networks.
Pricing Analysis
Volume-midscale splits separate high-throughput spinal cord stimulation systems from premium closed-loop bioelectronic platforms. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status, MRI-conditional certification tiers, and rechargeable versus primary battery architectures. Cost compression in standard-tier pulse generators is intensifying because hospital procurement consolidation demands multi-year contract discounts. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while tertiary academic centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with South African platinum-iridium electrode suppliers and Russian refining capacity for neurostimulation contact materials. Component sourcing draws from Japan for precision-machined pulse generator housings, Germany for biocompatible polymer insulation, and Switzerland for microelectronic assemblies. Geopolitical input cost volatility represents the dominant structural risk as sanctions and export controls disrupt electrode material flows. Distribution runs through integrated delivery network direct agreements that disintermediate traditional medical device distributors in Texas, Florida, and Ohio hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over electrode material supply and closed-loop algorithm development determines sustainable margin capture across the forecast window.
For Market Incumbents: Hedge against platinum-iridium supply disruption through backward integration into alternative electrode alloys or long-term offtake agreements with Australian and Canadian refining projects. Fortify positions in dorsal root ganglion therapy against Abbott's technology leadership by accelerating FDA submissions for expanded indications. Prioritize GPO contract penetration to defend share against ambulatory surgical center procurement consolidation. For New Entrants and Emerging Players: AI-driven closed-loop waveform optimization offers a technology-first wedge into the bioelectronic medicine segment where incumbent platforms remain open-loop. Target Japan's PMDA fast-track pathway for geriatric neurostimulation indications as the most penetrable regulatory entry point. Pursue hospital system pilot programs with detachable sensing module architectures that reduce capital barriers to adoption. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap neurostimulation specialists with MDR-compliant technical documentation and Japanese market access. Five-to-ten year viability hinges on reimbursement pathway clarity for outpatient bioelectronic procedures. Monitor CMS national coverage determination timelines for closed-loop autonomic nerve modulation as the critical inflection signal for platform commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review compresses time-to-market for closed-loop bioelectronic platforms targeting treatment-resistant neuropathic pain. |
| EU MDR Technical Documentation Renewal | Robust clinical evidence portfolios filter marginal competitors and consolidate European market share among compliant manufacturers. |
| Integrated Delivery Network Partnership | Direct procurement agreements bypass distributor markups and secure multi-facility standardization for spinal cord stimulation programs. |
| Software Companion Development | Remote patient monitoring integration enables decentralized chronic pain management outside traditional clinical settings. |
| Reimbursement Strategy Investment | Early engagement with CMS and commercial payers closes commercialization gaps between FDA clearance and coverage adoption. |
Research Methodology
Multi-period observation of neurostimulation implant volumes, ambulatory procedure migration rates, and reimbursement pathway evolution anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at device manufacturers. Secondary validation incorporated FDA 510(k) and PMA filings, EMA MDR technical documentation submissions, CMS national coverage determinations, and hospital procurement database extracts. Bottom-up demand modeling triangulated against top-down market sizing across therapeutic modality, intervention invasiveness, and care setting dimensions.
Segment-weighting approaches distributed value projections across analgesic formulations, implantable pulse generator architectures, cannabinoid delivery systems, and precision surgical instruments. CAGRs derived from procedure volume elasticity to aging demographic shifts, payer pressure metrics, and technology substitution curves. Forecast inputs incorporated PMDA fast-track review timelines, EU MDR transition compliance rates, and integrated delivery network procurement consolidation velocity.
Several conditions sit outside the modeled scope, including unforeseen regulatory classification changes for bioelectronic platforms, geopolitical disruptions to platinum-iridium supply chains, and paradigm shifts in chronic pain pharmacology. Forecasts reflect documented assumptions regarding reimbursement pathway convergence and hospital consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Robotic Surgery Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Global Biopsy Needles Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Neurosurgical Drills Market