
 Global Retinal Detachment Treatment Market | 2026-2036
Global Retinal Detachment Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retinal Detachment Treatment Market Foresight
Germany is narrowing its surgical device supply gap through expanded production of precision ophthalmic instruments. Alcon Inc. leverages its integrated vitrectomy platform to sustain dominance in advanced visualization systems. Carl Zeiss Meditec AG anchors European demand through its surgical microscope and intraoperative imaging portfolio. Bausch & Lomb Incorporated competes across the full retinal surgery workflow, from buckles to laser probes.
Retinal detachment treatment encompasses surgical and laser interventions to reattach separated neurosensory retina from underlying retinal pigment epithelium, utilizing vitrectomy cutters, tamponade agents such as perfluoropropane or silicone oil, and scleral buckling elements to restore anatomical integrity and visual function. Vitrectomy dominates procedural volume due to its versatility in addressing complex detachments with concurrent vitreous pathology, while pneumatic retinopexy occupies a selective outpatient niche for superior rhegmatogenous cases with accessible breaks. Laser photocoagulation and cryopexy function as adjunctive sealing modalities, with margin pools concentrating in single-use disposable instrument kits that reduce cross-contamination risk.
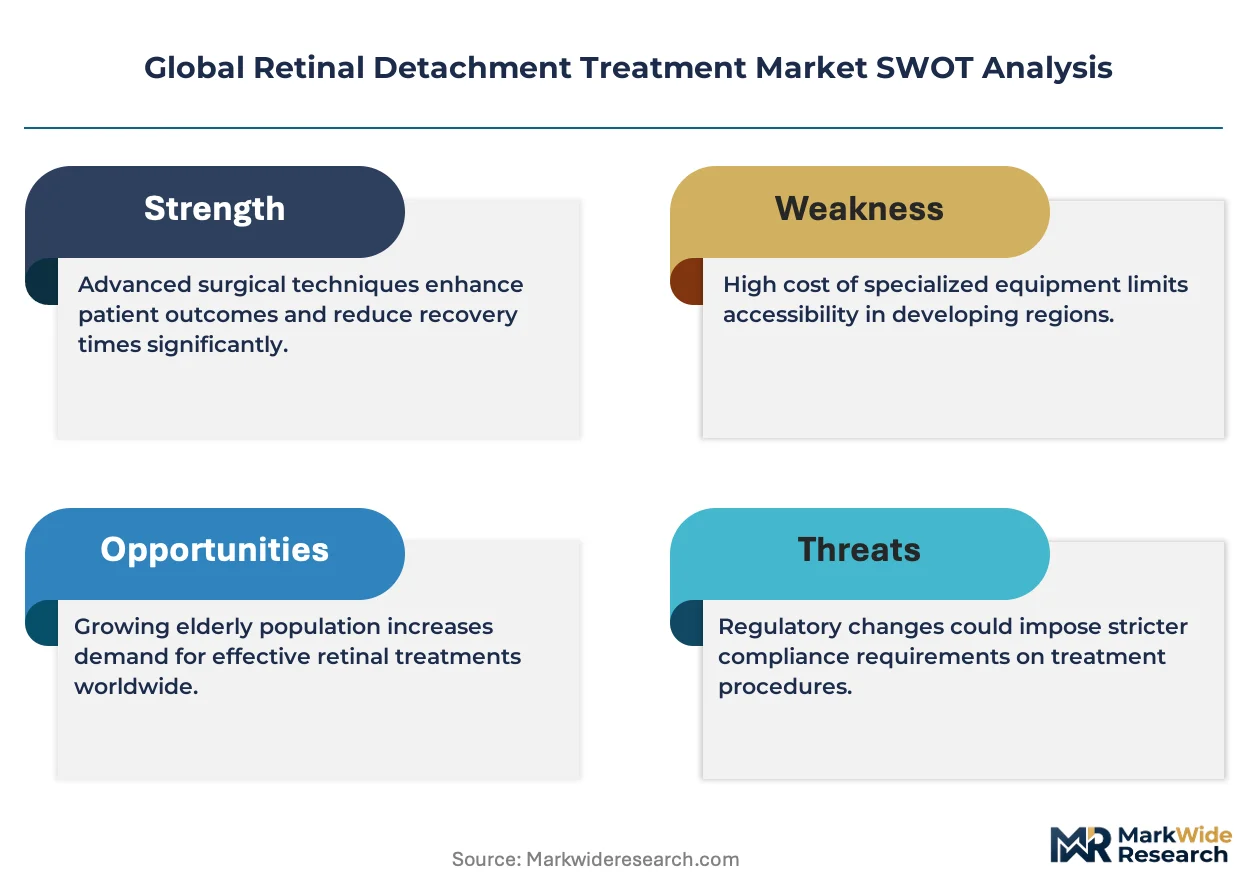
FDA 510(k) clearance pathways govern device commercialization in the United States, while the EU MDR and CE marking requirements reshape market access timelines for European manufacturers. Japan's PMDA and METI oversight of ophthalmic laser systems creates additional regulatory segmentation between surgical and therapeutic device classifications. Stakeholders must monitor evolving reimbursement thresholds for outpatient versus inpatient retinal procedures as payment reform reshapes site-of-service economics.
Market Dynamics
The EU MDR's tightened conformity requirements for ophthalmic surgical devices are compressing market access timelines and elevating compliance costs across European supply chains, forcing manufacturers to restructure quality management systems and clinical evidence portfolios.
Growth Catalysts
- EU MDR framework:The Medical Device Regulation's stricter post-market surveillance mandates are accelerating consolidation among compliant manufacturers, creating competitive moats for firms with robust quality infrastructure.
- Vitrectomy system adoption:Ophthalmic clinics are expanding investment in integrated vitrectomy platforms to handle complex retinal detachments with concurrent vitreous pathology, driving procedural volume concentration.
- United States academic medical centers:Complex case referral networks are concentrating demand at tertiary institutions with advanced visualization capabilities and fellowship-trained retinal specialists.
Market Restraints
- Silicone oil and gas tamponade input costs:Volatility in fluorinated compound feedstock pricing is compressing margins for tamponade agent manufacturers dependent on petrochemical supply chains.
- German precision instrument supply concentration:Retinal surgery instrument production clusters heavily in Baden-Württemberg and Bavaria, creating geographic vulnerability to regional logistics disruptions.
- Technical limitation of pneumatic retinopexy:The procedure's narrow indication window for superior breaks with minimal vitreous traction restricts addressable patient populations.
Strategic Opportunities
- Japan's PMDA pathway optimization:Streamlined review processes for ophthalmic laser systems are shortening time-to-market for novel photocoagulation devices.
- Single-use disposable instrument kits:Cross-contamination risk mitigation is driving conversion from reusable to disposable vitrectomy cutters and laser probes in ambulatory surgery centers.
- Outpatient procedure site migration:Payment reform is shifting retinal detachment repair from inpatient to ambulatory settings, creating channel expansion potential for office-based surgical suites.
Industry Challenges
- Vitreoretinal surgeon training pipeline:Fellowship program capacity constraints are limiting specialist supply growth relative to aging population demand.
- EU MDR technical documentation burden:Clinical evaluation report requirements and notified body backlogs are extending certification timelines for device modifications.
- Visualization system integration complexity:Operating room retrofitting for 3D heads-up display systems requires substantial capital coordination with hospital infrastructure teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retinal Detachment Treatment Market |
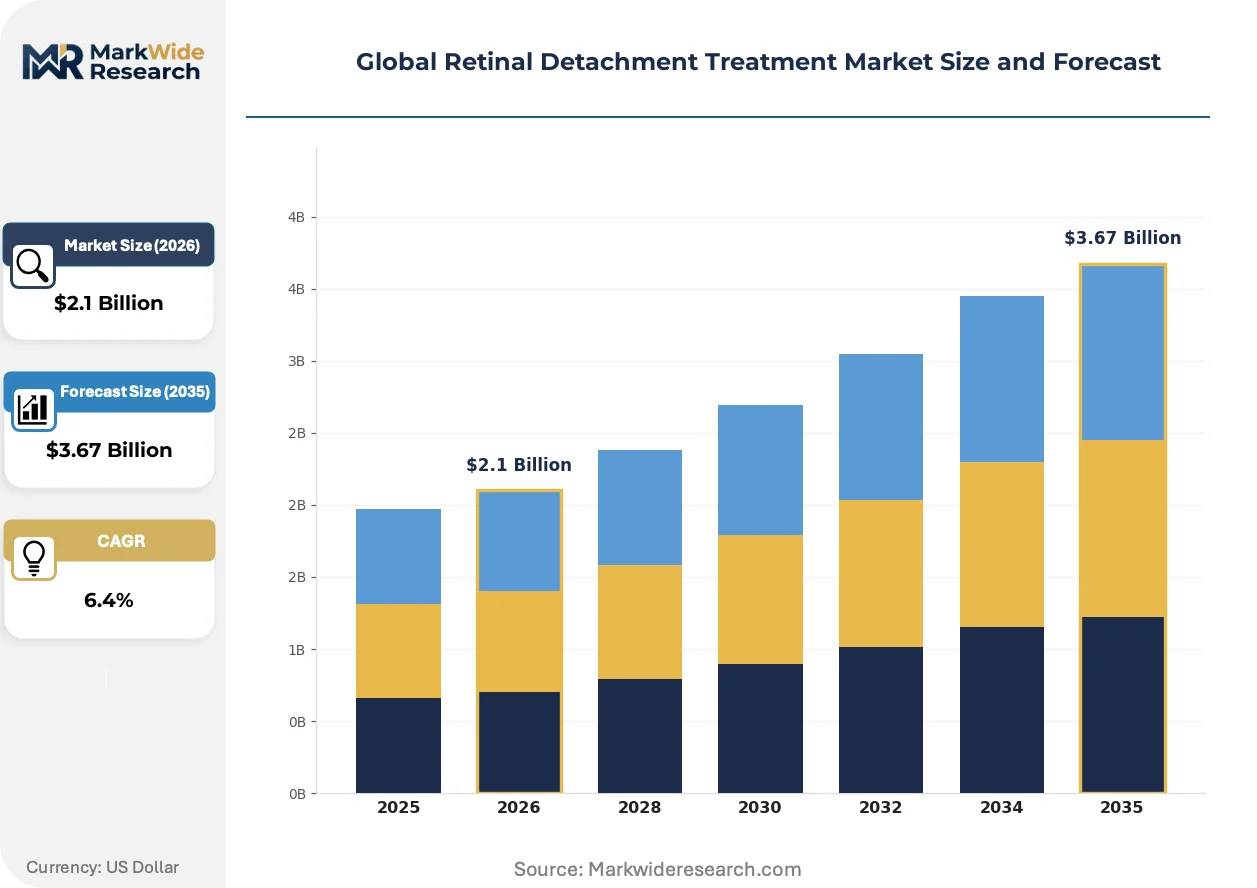
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Vitrectomy, Pneumatic Retinopexy, Scleral Buckling, Laser Photocoagulation, Cryopexy Application: Macula-Off Detachment, Macula-On Detachment, Tractional Retinal Detachment, Rhegmatogenous Retinal Detachment, Exudative Retinal Detachment End User: Ophthalmic Clinics, Eye Hospitals, Ambulatory Surgical Centers, Specialty Eye Care Facilities Delivery Mode: Inpatient Surgery, Outpatient Surgery, Laser Therapy, Minimally Invasive Procedures |
| Companies Covered | Inami & Co., Ltd., FCI Ophthalmics, IRIDEX Corporation, Carl Zeiss Meditec AG, Bausch & Lomb Incorporated, Alcon Inc., Geuder AG, Meridian AG, Ellex Medical Lasers Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retinal Detachment Treatment Market Shifts & Advancements
Digital surgical visualization and heads-up display systems are collapsing the physical boundary between surgeon and microscope, enabling ergonomic repositioning and assistant engagement that conventional ocular interfaces cannot accommodate.
3D stereoscopic visualization technology is collapsing the dominance of traditional binocular indirect ophthalmoscopy in complex retinal surgery. Academic medical centers in the United States are adopting these platforms at accelerating cadence to reduce surgeon fatigue during lengthy vitrectomy procedures. The structural consequence is collapsing reliance on assistant-held indirect viewing systems, compressing the traditional surgical team configuration into a more compact, technology-mediated workflow.
The EU MDR's enhanced clinical evidence requirements are extending premarket approval timelines for novel ophthalmic surgical devices. Manufacturers must now generate prospective clinical data or systematic literature reviews that meet stricter equivalence thresholds than under the prior Medical Device Directive. Retinal laser systems and intraocular tamponade agents face particular scrutiny, with notified bodies demanding expanded post-market clinical follow-up protocols.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases for vitrectomy systems. The traditional bundled model of device-plus-maintenance is giving way to competitive tendering for multi-vendor service agreements. This behavioral shift is most pronounced in German university hospitals and United States integrated delivery networks, where centralized procurement functions are extracting service cost transparency from manufacturers.
Global Retinal Detachment Treatment Market Segmentation
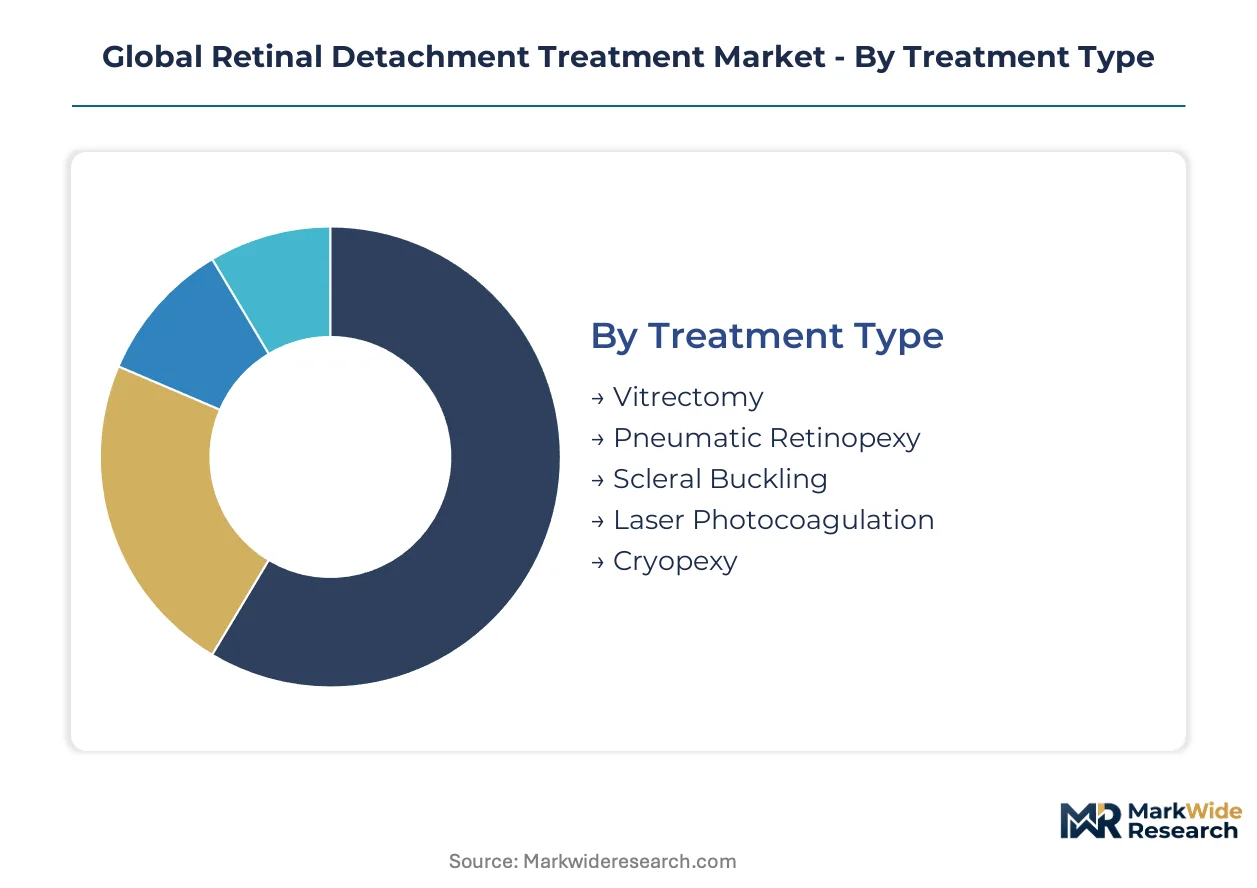
Retinal detachment treatment markets fragment across surgical modality, anatomical presentation, and care delivery setting. Each dimension shapes procurement patterns, reimbursement pathways, and technology investment priorities for manufacturers and providers.
Treatment Type:
Cost tier determines equipment intensity and consumable throughput across surgical approaches.
- Vitrectomy:Pars plana vitrectomy employs cutter instruments, infusion cannulas, and tamponade agents to remove vitreous and relieve traction. Academic medical centers in the United States concentrate demand for 25-gauge and 27-gauge systems that reduce surgical time and patient discomfort.
- Pneumatic Retinopexy:Gas bubble injection with cryopexy or laser retinopexy seals retinal breaks without incision. Ambulatory surgery centers in Germany favor this approach for selective superior breaks with minimal vitreous traction, compressing procedure time and facility costs.
- Scleral Buckling:Silicone band placement indents the sclera to approximate retinal layers.
- Laser Photocoagulation:Thermal coagulation creates chorioretinal adhesion around breaks.
- Cryopexy:Trans-scleral freezing achieves retinopexy in peripheral pathology.
Vitrectomy holds installed capacity. Pneumatic retinopexy is rotating up the share rankings.
Application:
Anatomical classification of detachment severity and etiology drives surgical urgency and technique selection.
- Rhegmatogenous Retinal Detachment:Full-thickness retinal break permits fluid accumulation in subretinal space. Tertiary eye hospitals in Japan handle complex cases with proliferative vitreoretinopathy, where combined scleral buckling and vitrectomy improves anatomical success rates.
- Macula-Off Detachment:Foveal involvement threatens central visual acuity and demands emergent intervention. United States academic centers prioritize same-day surgical scheduling for these presentations, with visual outcomes highly dependent on symptom-to-surgery interval.
- Macula-On Detachment:Peripheral detachment spares central vision but risks progression.
- Tractional Retinal Detachment:Fibrovascular membrane contraction pulls retina from pigment epithelium.
- Exudative Retinal Detachment:Serous fluid accumulation without retinal break requires medical management.
Rhegmatogenous presentations dominate procedural volume. Macula-off cases command premium reimbursement weighting.
End User:
Customer type determines capital equipment scale, surgeon specialization depth, and regulatory exposure.
- Ophthalmic Clinics:Office-based settings perform diagnostic laser and selective pneumatic retinopexy. German multi-site clinic chains invest in portable laser systems to capture outpatient retinopexy volume outside hospital contracts.
- Eye Hospitals:Dedicated ophthalmic facilities maintain 24-hour surgical capacity for emergent detachments. Japan's national university hospitals concentrate fellowship-trained vitreoretinal specialists and advanced visualization platforms.
- Ambulatory Surgical Centers:Same-day discharge settings favor efficient vitrectomy protocols.
- Specialty Eye Care Facilities:Retina-only practices combine medical and surgical retina services.
Eye hospitals anchor complex case referral networks. Ambulatory surgical centers are expanding fastest into routine vitrectomy.
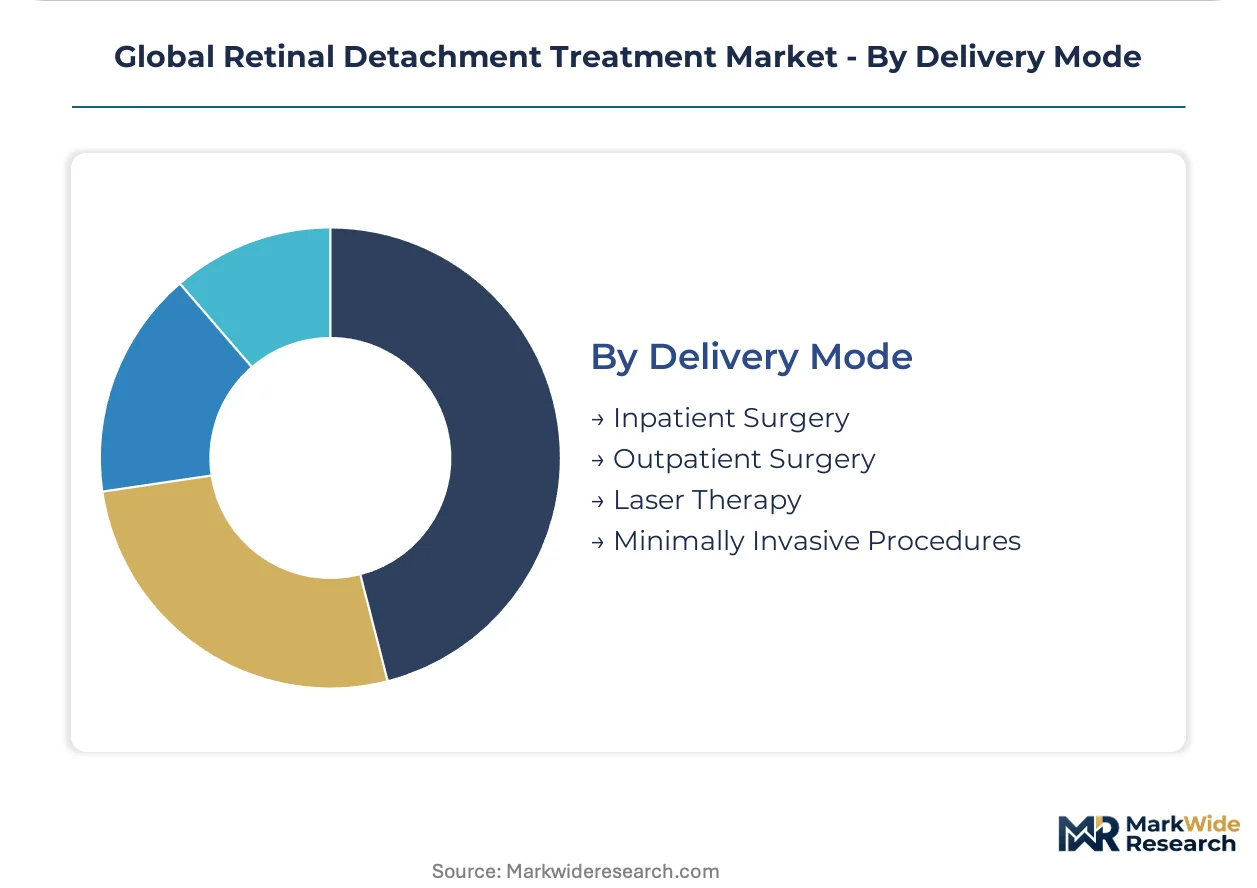
Delivery Mode:
Site-of-service economics and recovery trajectory segment intervention approaches.
- Outpatient Surgery:Same-day discharge after vitrectomy or pneumatic retinopexy dominates United States payment reform incentives. Integrated delivery networks negotiate bundled rates that shift volume from inpatient to ambulatory settings, compressing length-of-stay metrics.
- Minimally Invasive Procedures:Sutureless vitrectomy and small-gauge instrumentation reduce operative trauma. Japanese manufacturers lead 27-gauge cutter development, enabling transconjunctival entry without wound closure.
- Inpatient Surgery:Reserved for complex trauma or concurrent ocular pathology.
- Laser Therapy:Office-based photocoagulation for prophylaxis or limited breaks.
Outpatient surgery captures volume share. Minimally invasive approaches are climbing fastest in adoption metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways govern device commercialization in the United States, while Japan's PMDA and Germany's EU MDR compliance reshape market access timelines across their respective jurisdictions. Academic medical centers and ophthalmic clinic chains concentrate procedural volume in distinct national patterns.
United States
Tertiary academic medical centers in Boston, Baltimore, and San Francisco drive complex retinal detachment referrals with 24-hour surgical capacity. FDA 510(k) pathways for vitrectomy systems and tamponade agents maintain predictable review timelines. The Midwest surgical corridor spanning Cleveland Clinic and Mayo Clinic anchors fellowship-trained specialist density.
Germany
Baden-Württemberg and Bavaria host precision ophthalmic instrument manufacturing clusters for vitrectomy cutters and laser probes. EU MDR notified body backlogs extend certification timelines for device modifications. University hospital procurement in Heidelberg and Tübingen unbundles service contracts from capital equipment purchases.
Japan
National university hospitals in Tokyo and Osaka concentrate fellowship-trained vitreoretinal specialists and advanced visualization platforms. METI and PMDA oversight of ophthalmic laser systems creates regulatory segmentation between surgical and therapeutic classifications. Yokohama-based manufacturers lead 27-gauge cutter development for sutureless transconjunctival entry.
India
Maharashtra and Tamil Nadu eye hospital chains expand vitrectomy capacity to address aging population demand. CDSCO medical device rules classify retinal lasers and intraocular tamponades under distinct registration pathways. Chennai and Mumbai multi-site clinic networks invest in portable laser systems for outpatient retinopexy.
Switzerland
Swissmedic certification requirements for ophthalmic surgical devices align with EU MDR standards while maintaining independent review protocols. Basel and Zurich academic centers integrate 3D heads-up display systems for complex vitreoretinal procedures. Precision instrument fabrication in the Jura region supplies German and French hospital networks.
Global Retinal Detachment Treatment Market Competitive Landscape
Capability concentration sits with integrated visualization platform developers; scale advantage sits with diversified ophthalmic surgical portfolios. The market structures around three tiers: full-workflow providers spanning buckles to laser probes, specialized vitrectomy system manufacturers, and regional precision instrument fabricators. Dominant competitive moves include hospital procurement unbundling of service contracts and multi-vendor maintenance agreement consolidation.
Within the full-workflow tier, Alcon Inc. and Bausch & Lomb Incorporated occupy positions spanning diagnostic through surgical intervention. Carl Zeiss Meditec AG anchors European demand through its surgical microscope and intraoperative imaging portfolio. These three represent distinct archetypes: the diversified multinational, the integrated platform developer, and the precision optics specialist.
| Leading Market Players |
|---|
| Inami & Co., Ltd. |
| FCI Ophthalmics |
| IRIDEX Corporation |
| Carl Zeiss Meditec AG |
| Bausch & Lomb Incorporated |
| Alcon Inc. |
| Geuder AG |
| Meridian AG |
| Ellex Medical Lasers Ltd |
| Others |
Supply & Pricing Matrix
Fluorinated compound feedstock volatility determines both tiered pricing spreads across tamponade agents and the geographic shape of ophthalmic chemical supply chains. EU MDR compliance costs compress margins for mid-tier instrument manufacturers while elevating premium positioning for certified full-workflow providers.
Pricing Analysis
German university hospitals negotiate lower per-procedure costs for vitrectomy systems than United States academic medical centers due to centralized procurement scale. Three-tier pricing structure across premium visualization-integrated platforms, standard cutter-instrument bundles, and economy-grade disposable kits reflects certification grade and after-sales service bundling. Pricing pressure stems from hospital procurement departments unbundling maintenance contracts from capital equipment purchases. Ambulatory surgery centers exhibit highest price sensitivity, while tertiary eye hospitals prioritize visualization capability over unit economics.
Supply Chain Analysis
Extended payment terms from German university hospital networks strain working capital for precision instrument fabricators in Baden-Württemberg. Manufacturing concentrates in Germany, Japan, and Switzerland for vitrectomy cutters, laser probes, and surgical microscopes. Supply chains draw from fluorinated chemical feedstocks, optical-grade glass, and medical-grade silicone for tamponade agents. Single-source vulnerability concentrates in 27-gauge cutter production from Yokohama-based manufacturers. Distribution runs through specialized ophthalmic device distributors and direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from multi-vendor maintenance agreements and disposable instrument kit subscriptions expands faster than capital equipment sales, creating recurring revenue pools for platform-integrated manufacturers.
For Market Incumbents: Pre-empt procurement unbundling by offering transparent service-cost modularization before hospital systems demand it. Lock in ambulatory surgery center chains with consumable subscription models that raise switching costs for competitors. Vertical integration into precision cutter manufacturing in Baden-Württemberg reduces exposure to German supply concentration risk. For New Entrants and Emerging Players: Portable laser systems for outpatient retinopexy in Indian multi-site clinic chains represent the most penetrable entry point, as these facilities seek to capture volume outside hospital contracts. Single-use disposable instrument kits for German ambulatory surgery centers offer second-mover advantage through cross-contamination risk messaging. Partner with established ophthalmic distributors rather than building direct sales infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-workflow platform developers with EU MDR certification infrastructure already deployed. Long-term viability over a multi-year window hinges on capturing service-contract revenue streams rather than hardware placement volume. Monitor notified body backlog resolution timelines as the inflection signal for certification-constrained supply recovery.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Accelerated notified body engagement compresses time-to-market for device modifications. |
| Hospital System Partnership | Integrated delivery network contracts secure procedural volume commitments across multiple sites. |
| Software Companion Development | 3D heads-up display integration creates platform stickiness with visualization-dependent surgeons. |
| Reimbursement Strategy | Outpatient procedure coding alignment captures payment reform-driven site migration. |
| CE Marking Pathway | Streamlined technical documentation meets enhanced clinical evidence requirements for laser systems. |
Research Methodology
Operator-level perspectives from vitreoretinal surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. These primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, PMDA submission records, and hospital procurement databases. Bottom-up procedural volume estimates and top-down equipment replacement cycles were triangulated to establish market sizing.
Scenario-bracketing around regulatory approval timelines and reimbursement pathway shifts informed the analytical framework across the projection horizon. Segmentation dimensions modeled include treatment modality, anatomical presentation severity, care delivery setting, and gauge specification for instrumentation. CAGRs were derived from installed base expansion rates and consumable throughput per procedure. Forecast inputs incorporated fellowship-trained specialist pipeline constraints and EU MDR certification backlog resolution trajectories.
Practitioners should monitor notified body capacity expansion, fluorinated compound pricing volatility, and outpatient reimbursement threshold adjustments for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Usher Syndrome Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
United States Dry Eye Syndrome Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Superficial Punctate Keratitis Treatment Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Synoptophore Market
Ophthalmology
Ptosis Treatment Market