
 Surgical Blades Market | 2026-2036
Surgical Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Blades Market Intelligence
Outpatient facilities are unwinding the historical procurement dominance of hospitals across the surgical blades value chain. B. Braun Melsungen AG anchors its position through captive sterilization and distribution infrastructure in European markets. Swann-Morton Limited specializes in carbon steel blade formulations for dermatology and histology applications where edge retention commands premium positioning. Hu-Friedy Mfg. Co., LLC competes on instrument-system bundling that locks dental and surgical suites into recurring blade replenishment contracts.
Surgical blades are precision cutting instruments manufactured from hardened stainless steel, carbon steel, or polymer composites through grinding, honing, and coating processes to achieve sub-millimeter edge geometries for tissue incision. The primary commercial purpose centers on enabling controlled anatomical dissection across operative, diagnostic, and dermatological procedures with minimal collateral tissue trauma. Safety blades lead volume growth as sharps injury regulations harden liability exposure for healthcare employers, while stainless steel formulations sustain the dominant material share due to corrosion resistance and autoclave compatibility. Disposable blades capture margin pools through single-use economics that eliminate reprocessing labor and cross-contamination risk in high-throughput settings.
FDA 510(k) clearance pathways and EU MDR Class I classification govern blade material biocompatibility, edge integrity testing, and sterilization validation before market authorization. ISO 7740 standards specify dimensional tolerances for blade-to-handle fit that manufacturers must certify to maintain interoperability across instrument platforms. Stakeholders must monitor how FDA's evolving single-use device reprocessing guidance and EU F-Gas restrictions on sterilization agents reshape cost structures and supply qualification timelines.
Market Dynamics
Outpatient procedural volume expansion is dismantling the hospital-centric procurement architecture that has governed surgical blade distribution for decades, forcing manufacturers to reconfigure sterilization logistics and inventory systems around ambulatory surgical centers.
Growth Catalysts
- EU MDR material traceability mandates:Sterilization validation requirements under the Medical Device Regulation are accelerating replacement cycles as facilities retire non-compliant blade inventories ahead of certification deadlines.
- Carbon steel edge retention:Dermatology and histology applications favor high-carbon formulations that maintain sub-millimeter geometries through repeated tissue sectioning, sustaining premium pricing tiers.
- Germany precision manufacturing clusters:Tuttlingen and Solingen production ecosystems supply export markets with ISO 7740-certified blade-to-handle interoperability that locks in recurring procurement contracts.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input costs fluctuate with commodity exchange pricing, compressing margin predictability for high-volume disposable blade manufacturers.
- EU F-Gas sterilization restrictions:Phasedown of hydrofluorocarbon propellants under the Fluorinated Greenhouse Gases Regulation forces capital retooling toward plasma or ethylene oxide alternatives.
- Polymer composite substitution ceiling:Ceramic and zirconia blade materials fail autoclave compatibility testing, limiting penetration into reusable instrument workflows.
Strategic Opportunities
- India outpatient surgical expansion:CDSCO streamlined 510(k)-equivalent pathways for Class I devices enable faster market entry as hospital chains build ambulatory capacity in tier-2 cities.
- Safety-engineered blade systems:OSHA Bloodborne Pathogens Standard compliance creates pull for retractable and shielded designs that reduce sharps injury liability exposure.
- Direct-to-facility distribution:E-commerce procurement platforms bypass traditional surgical supply distributors, capturing margin from consolidated ambulatory surgery center networks.
Industry Challenges
- ISO 7740 dimensional certification backlog:Third-party testing laboratory capacity constraints delay blade-to-handle fit validation, extending product launch timelines.
- Autoclave sterilization protocol fragmentation:Facility-specific steam and temperature parameters force blade manufacturers to maintain multiple coating formulations, complicating production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Blades Market |
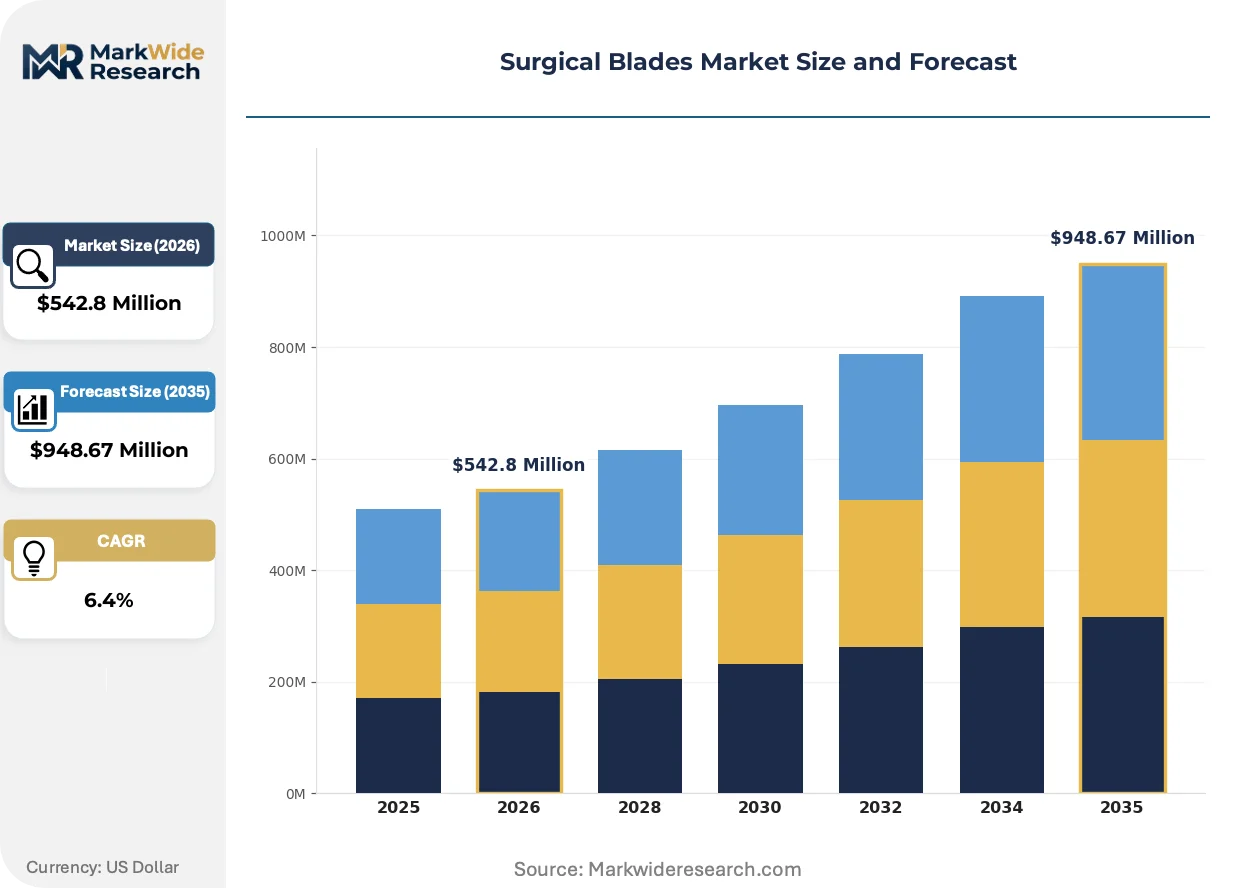
| Market Size in 2026 | $542.8 Million |
| Market Size in 2035 | $948.67 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpel Blades, Safety Blades, Disposable Blades, Reusable Blades Material: Stainless Steel, Carbon Steel, Plastic, Coated Blades Application: Surgery, Biopsy, Dermatology, General Medicine End User: Hospitals, Clinics, Research Labs, Outpatient Facilities |
| Companies Covered | Swann-Morton Limited, Hu-Friedy Mfg. Co., LLC, B. Braun Melsungen AG, PL Medical Co., Hill-Rom Holdings Inc., VOGT Medical, KAI Industries Co., Ltd., Aspen Surgical, Beaver-Visitec International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Blades Market Strategic Shifts & Innovations
Precision coating technologies and single-use safety systems are compressing the traditional trade-off between edge durability and disposability economics that has structured surgical blade procurement for decades.
Diamond-like carbon coatings deposited through plasma-enhanced chemical vapor deposition are miniaturizing edge radius tolerances below 50 nanometers while maintaining fracture resistance. Microsurgical suites in ophthalmology and neurosurgery are adopting these formulations for retinal and neural tissue dissection where collateral damage thresholds approach cellular scale. The technology is miniaturizing the addressable procedure set, enabling blade manufacturers to capture premium positioning in previously inaccessible anatomical interventions.
FDA's evolving single-use device reprocessing guidance is tightening validation documentation requirements for blades marketed as disposable. Manufacturers must now submit sterility assurance level testing and endotoxin screening protocols that previously applied only to reusable instrument reprocessors. Dental and surgical suites are responding by consolidating procurement around original equipment manufacturer blade lines that bundle compliance documentation with replenishment contracts.
Consolidated buying groups are displacing individual facility purchasing autonomy across ambulatory surgery center networks. Group purchasing organizations aggregate volume across dozens of sites, extracting price concessions that independent distributors cannot match. The United States exhibits the most pronounced concentration, where ten national GPOs control procurement for over half of outpatient surgical volume.
Surgical Blades Market Segmentation
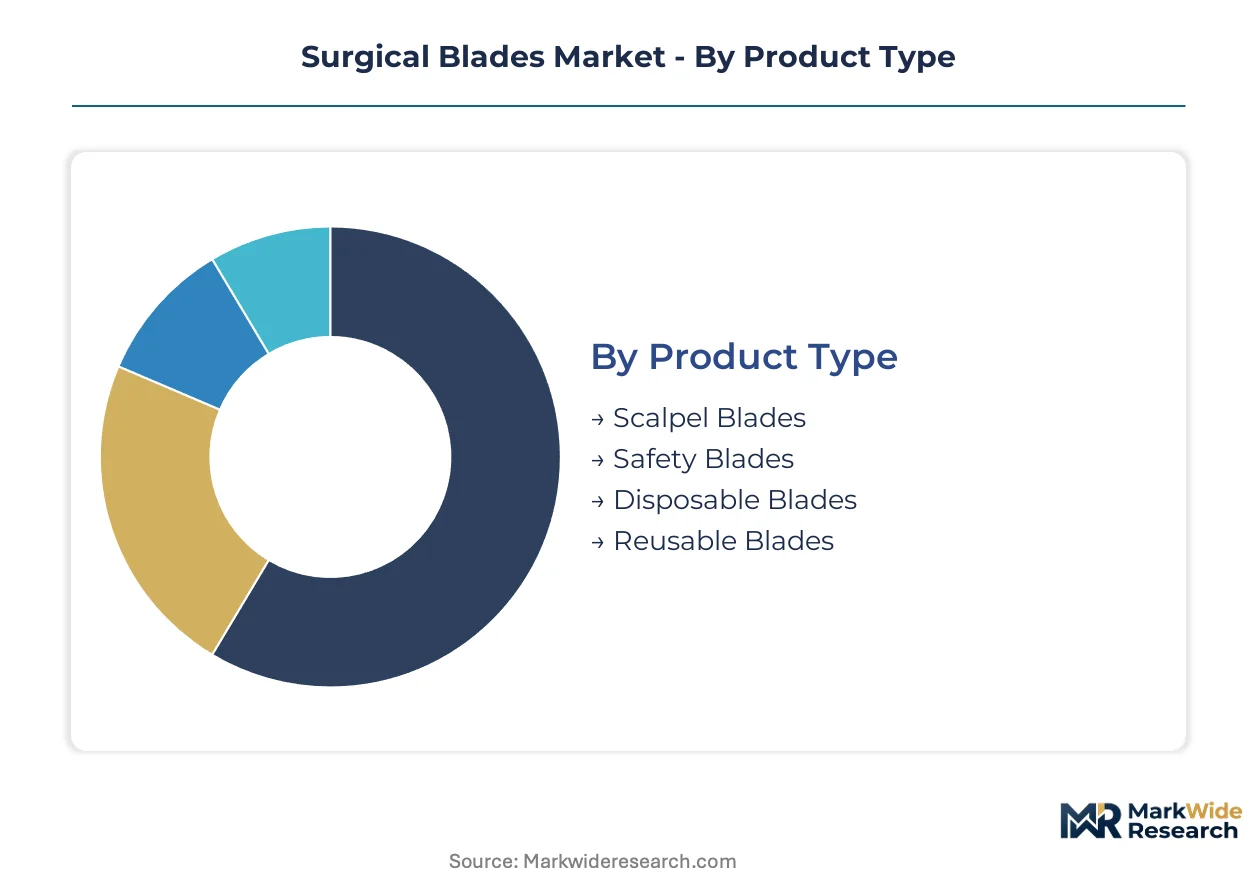
Surgical blade procurement channels diverge sharply by segment—hospitals bulk-purchase through group purchasing organizations while outpatient facilities favor direct e-commerce replenishment. Material composition and sterility requirements further partition distribution logistics, with carbon steel formulations demanding climate-controlled warehousing absent for polymer disposables.
Product Type:
Channel-mix varies dramatically: scalpel blades flow through traditional surgical distributors to hospital sterile processing departments, while safety-engineered disposables bypass intermediaries via direct-to-facility platforms serving ambulatory networks.
- Scalpel Blades:Standard carbon and stainless steel formulations ground to ISO 7740 dimensional tolerances for universal handle compatibility. Demand concentrates in Germany's Tuttlingen manufacturing cluster, where precision grinding infrastructure serves export markets with certified edge geometries. Autoclave reprocessing protocols sustain recurring procurement from hospital sterile supply departments.
- Safety Blades:Retractable and shielded designs engineered for OSHA Bloodborne Pathogens Standard compliance, incorporating passive or active injury-prevention mechanisms. Outpatient surgical centers in the United States drive procurement expansion as sharps injury liability exposure hardens employer risk management priorities. Single-use economics eliminate reprocessing labor costs in high-throughput settings.
- Disposable Blades:Pre-sterilized single-use instruments eliminating cross-contamination risk through gamma irradiation or ethylene oxide validation. Preferred by ambulatory surgery centers seeking inventory simplification.
- Reusable Blades:Hardened stainless steel formulations designed for repeated autoclave cycles with diamond-like carbon coatings extending edge retention. Concentrated in cost-sensitive hospital systems with captive sterilization infrastructure.
By volume, scalpel blades lead procurement across all channels. By growth pace, safety blades are expanding most quickly as regulatory compliance mandates harden.
Material:
Cost tier stratification separates premium formulations from commodity inputs—nickel price volatility compresses margins on standard stainless steel while carbon steel and advanced coatings sustain pricing power in specialized applications.
- Stainless Steel:Austenitic and martensitic grades offering corrosion resistance and autoclave compatibility across hundreds of sterilization cycles. Nickel and chromium input cost exposure from commodity exchange pricing creates margin unpredictability for high-volume manufacturers supplying hospital group purchasing organizations.
- Carbon Steel:High-carbon formulations achieving Rockwell hardness above 60 HRC for superior edge retention in dermatology and histology applications requiring repeated tissue sectioning. Premium positioning commands price multiples over stainless alternatives in pathology and microsurgical suites.
- Plastic:Polymer composite blades for low-risk procedures and training applications where metal detection and disposal costs outweigh performance requirements. Limited by autoclave incompatibility.
- Coated Blades:Diamond-like carbon and titanium nitride surface treatments deposited via plasma-enhanced chemical vapor deposition reducing friction coefficients below 0.1. Ophthalmology and neurosurgery adoption for cellular-scale precision.
Stainless steel dominates procurement tonnage. Carbon steel coatings gain share fastest in premium surgical segments.
Application:
Volume concentration in general surgery contrasts with margin concentration in specialized interventions—procedure reimbursement rates and instrument precision requirements reshape material selection and pricing architecture.
- Surgery:General operative procedures spanning orthopedic, cardiovascular, and abdominal interventions requiring standardized blade geometries for tissue dissection and hemostasis. Hospital operating rooms sustain bulk procurement through consolidated supply agreements.
- Biopsy:Tissue sampling procedures demanding ultra-sharp edges for clean specimen extraction without crush artifact. Histopathology laboratories in research institutions favor carbon steel formulations for microtome compatibility.
- Dermatology:Mohs surgery and cosmetic procedures requiring sub-millimeter precision for layered excision. Premium blade coatings reduce collateral thermal damage.
- General Medicine:Primary care and emergency department applications including wound debridement and suturing where cost minimization supersedes precision requirements.
Surgery generates the highest absolute volume. Biopsy applications climb fastest as early cancer screening protocols expand.
End User:
Customer-type fragmentation is accelerating—consolidated buying groups displace individual facility autonomy while research laboratories sustain specialized procurement outside distributor networks.
- Hospitals:Integrated delivery networks and academic medical centers with captive sterile processing departments and group purchasing organization contracts. EU MDR material traceability mandates are accelerating inventory replacement cycles ahead of certification deadlines.
- Clinics:Physician office laboratories and urgent care centers with limited sterilization infrastructure favoring pre-sterilized disposable configurations. Direct-to-facility e-commerce platforms are capturing procurement share from traditional distributors.
- Research Labs:Academic and pharmaceutical histology facilities requiring carbon steel microtome blades with certified edge geometries for tissue sectioning. Procurement outside standard medical supply channels through scientific distributors.
- Outpatient Facilities:Ambulatory surgery centers and endoscopy suites driving volume growth through procedural migration from inpatient settings. Safety-engineered designs preferred for OSHA compliance in lean staffing environments.
Hospitals retain the largest procurement volume. Outpatient facilities are gaining share fastest as procedural economics shift toward lower-acuity settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturers export ISO 7740-certified blades to hospital systems across North America and Asia-Pacific, while domestic demand concentrates in outpatient surgical networks seeking safety-engineered disposables.
United States
Ambulatory surgery centers now account for the fastest-growing procurement channel as procedural volume migrates from inpatient settings. OSHA Bloodborne Pathogens Standard enforcement hardens liability exposure, accelerating safety blade adoption. The Southeast corridor from Florida through Georgia hosts concentrated ASC network expansion.
Germany
Tuttlingen and Solingen manufacturing clusters supply export markets with certified blade-to-handle interoperability that locks in recurring contracts. EU MDR material traceability mandates accelerate inventory replacement cycles ahead of certification deadlines. Baden-Württemberg precision instrument producers dominate high-carbon formulations for histology applications.
India
Hospital chains build ambulatory capacity in tier-2 cities, expanding addressable surgical volume. CDSCO streamlined 510(k)-equivalent pathways for Class I devices enable faster market entry. Maharashtra and Karnataka medical device manufacturing zones attract sterilization infrastructure investment.
China
Domestic blade producers scale output for hospital system consolidation programs. NMPA biocompatibility testing requirements for imported devices create procurement preference for locally manufactured alternatives. Yangtze River Delta medical device clusters integrate coating and sterilization capabilities.
Japan
Aging demographic profiles sustain demand for ophthalmic and microsurgical precision instruments. PMDA sterility assurance documentation requirements favor established suppliers with validated endotoxin screening protocols. Kansai region manufacturers specialize in diamond-like carbon coatings for cellular-scale interventions.
Surgical Blades Market Key Industry Players
Listed leaders compete with private specialists across sterilization infrastructure and distribution reach. The vendor base spans three tiers: diversified medical device conglomerates with captive sterilization networks, mid-scale precision instrument specialists anchored in regional manufacturing clusters, and niche carbon steel formulators serving pathology and dermatology segments. Consolidation pressure intensifies as group purchasing organizations aggregate procurement volume across ambulatory networks. Two dominant competitive moves reshape positioning: backward integration into sterilization validation services and direct-to-facility e-commerce platforms that bypass traditional surgical supply distributors.
Among German-based diversified manufacturers, B. Braun Melsungen AG exemplifies the conglomerate archetype with integrated sterilization and distribution infrastructure across European markets. Swann-Morton Limited and Hu-Friedy Mfg. Co., LLC represent contrasting specialist positions—Sheffield-based carbon steel formulators and instrument-system bundlers respectively—each anchoring distinct procurement channels through material expertise or recurring replenishment contracts.
| Leading Market Players |
|---|
| Swann-Morton Limited |
| Hu-Friedy Mfg. Co., LLC |
| B. Braun Melsungen AG |
| PL Medical Co. |
| Hill-Rom Holdings Inc. |
| VOGT Medical |
| KAI Industries Co., Ltd. |
| Aspen Surgical |
| Beaver-Visitec International |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day sterilization validation lead times for EU MDR compliance create inventory buffers that concentrate pricing power with German and Japanese manufacturers possessing captive autoclave infrastructure, while buyers without backward integration into sterilization services face cost pass-through vulnerability.
Pricing Analysis
Diamond-like carbon coated blades command three-to-four-fold premiums over standard stainless steel formulations, while safety-engineered disposables price at mid-tier levels between commodity scalpels and premium coated alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and edge retention performance, with ISO 7740 dimensional tolerances separating tiers. Cost compression in standard stainless steel is intensifying because nickel and chromium commodity volatility erodes margin predictability for high-volume disposable manufacturers. Ambulatory surgery centers exhibit highest price sensitivity due to lean staffing economics, while academic medical centers with captive sterile processing departments show lowest sensitivity to per-unit differentials.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for sterilization equipment and coating precursor chemicals, compressing margins for manufacturers without regional warehousing in target markets. Production gravity centers on Germany, Japan, and China, with Tuttlingen and Solingen clusters supplying export markets while Yangtze River Delta producers serve domestic hospital consolidation programs. Raw material dependencies span nickel and chromium for stainless steel formulations, high-carbon steel feedstock from European mills, and plasma-enhanced chemical vapor deposition gases subject to EU F-Gas phasedown restrictions. Single-source vulnerability concentrates in sterilization validation services, where third-party laboratory capacity constraints extend qualification timelines. Distribution runs through group purchasing organizations for hospital networks and direct-to-facility e-commerce platforms for ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against polymer composite and ceramic blade technologies that threaten to displace metal formulations if autoclave compatibility barriers fall.
For Market Incumbents: Shield market position by deepening backward integration into sterilization validation services that lock hospital systems into recurring blade replenishment contracts, and by accelerating diamond-like carbon coating capacity additions in Baden-Württemberg to outpace Japanese competitors in ophthalmology and neurosurgery segments. Electrosurgical and ultrasonic scalpel substitution threats demand coating performance investment as the primary defensive lever.
For New Entrants and Emerging Players: Compliance documentation bundling represents the most pronounced service-layer gap where established suppliers under-serve small ambulatory surgery centers lacking regulatory affairs staff. Target tier-2 Indian cities where CDSCO streamlined pathways enable faster market entry than saturated Western markets, and penetrate safety-engineered disposable segments through direct e-commerce procurement platforms that bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because group purchasing organization procurement concentration across United States ambulatory networks will compress independent distributor margins and force asset sales. Acquisition targets should display sterilization infrastructure ownership or carbon steel formulation expertise for histology applications. The signal to watch is EU MDR certification deadline acceleration, which will strand non-compliant inventories and create distressed asset opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR material traceability mandates accelerate inventory replacement cycles ahead of certification deadlines. |
| Backward Integration into Sterilization | Captive ethylene oxide and plasma sterilization capacity locks hospital systems into recurring blade replenishment contracts. |
| Hospital System Partnership | Group purchasing organization contracts aggregate ambulatory surgery center volume and extract price concessions from distributors. |
| Safety-Engineered Product Launch | OSHA Bloodborne Pathogens Standard compliance creates procurement pull for retractable and shielded blade designs. |
| Geographic Manufacturing Footprint | Tuttlingen and Solingen precision clusters supply export markets with ISO 7740-certified blade-to-handle interoperability. |
Research Approach
A standing panel of sterile processing department managers, group purchasing organization contracts directors, biomedical engineers, and dermatology clinic procurement officers provided ongoing calibration across primary interviews, supplemented by secondary validation from FDA 510(k) filings, EU MDR certification databases, hospital procurement records, and nickel exchange pricing data. Bottom-up demand modeling across ambulatory surgery center networks and top-down supply assessment from German and Japanese manufacturing clusters enabled triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework segmented by product type, material composition, application, and end-user channel, with CAGRs derived from procedure volume migration trends and inventory replacement cycle acceleration under regulatory deadlines. Forecast inputs incorporated outpatient surgical expansion rates and sterilization validation laboratory capacity constraints.
Underlying assumptions cover EU MDR compliance timeline adherence and nickel price band stability, with deviation risk concentrated in F-Gas regulation acceleration and autoclave protocol fragmentation across facility networks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
Global Bone Wax Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market