
 US Medical Device Outsourcing Market | 2026-2036
US Medical Device Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Device Outsourcing Market Intelligence
Additive manufacturing is fragmenting traditional production workflows across the US medical device supply base, forcing OEMs to reevaluate in-house versus outsourced fabrication of patient-specific implants and surgical instruments. Integer Holdings Corporation leverages deep catheter and cardiac rhythm management expertise to anchor high-mix, low-volume production for cardiovascular innovators. Jabil Inc. sustains massive electronics manufacturing scale across multiple US locations, competing for diagnostic and monitoring device programs requiring complex printed circuit board assemblies. West Pharmaceutical Services Inc. dominates injectable drug delivery and containment systems, extending its footprint into combination product partnerships that blur the boundary between pharma and device outsourcing.
US medical device outsourcing encompasses the transfer of design, engineering, manufacturing, sterilization, packaging, and logistics functions from original equipment manufacturers to third-party specialists operating under FDA-regulated quality systems, typically governed by 21 CFR Part 820 and ISO 13485 standards with validated processes for traceability and risk management. Contract manufacturing of implantable devices generates premium margins due to stringent biocompatibility testing and long qualification cycles that lock in multi-year supply agreements. Diagnostic devices represent the highest-volume segment, where electronics integration and software validation demands are accelerating outsourcing to partners with dedicated health technology competencies. Sterilization services remain a bottleneck capacity with ethylene oxide and radiation modalities concentrated among a handful of regional providers.
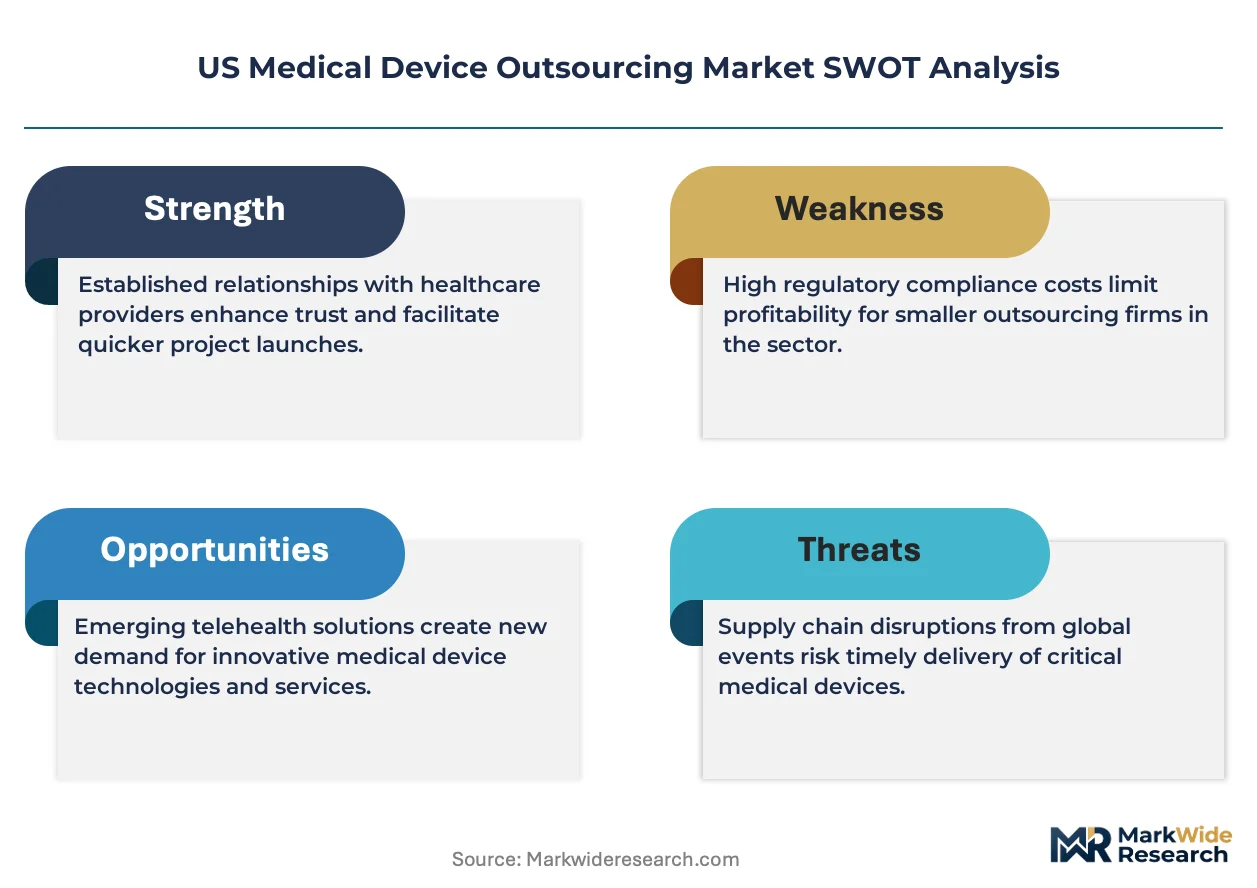
FDA enforcement of the Quality System Regulation and impending transition to harmonized ISO 13485:2016 requirements are elevating compliance costs for smaller contract manufacturers, driving consolidation toward established players with dedicated regulatory affairs teams. The Medical Device Single Audit Program streamlines third-party inspections but demands substantial documentation infrastructure that favors outsourced partners with mature quality management systems. Stakeholders must monitor how FDA's digital health pre-certification pathway reshapes software-intensive outsourcing contracts and liability allocation between OEMs and their development partners.
Market Dynamics
FDA's pending harmonization with ISO 13485:2016 is forcing contract manufacturers to rebuild quality management infrastructure, accelerating consolidation toward specialists with dedicated regulatory affairs teams and validated traceability systems.
Growth Catalysts
- Cardiovascular OEM expansion:Implantable device innovators are transferring high-mix, low-volume catheter and cardiac rhythm management production to contract partners with established biocompatibility testing capabilities.
- 21 CFR Part 820 compliance infrastructure:Sponsors lacking validated sterilization and packaging workflows are outsourcing to specialists with pre-audited quality systems, locking in multi-year supply agreements.
- Twin Cities corridor density:Minnesota's concentrated supplier networks and clinical research institutions surrounding major device headquarters reduce logistics friction and accelerate prototype-to-production cycles.
Market Restraints
- Sterilization capacity concentration:Ethylene oxide and gamma radiation modalities cluster among a handful of regional providers, creating bottlenecks for implantable device launches.
- Biocompatibility testing costs:Extended qualification cycles for implant-grade materials lock working capital into inventory and delay revenue recognition for contract manufacturers.
- Electronics integration complexity:Diagnostic devices with embedded software and wireless connectivity require FCC certification alongside FDA clearance, extending development timelines.
Strategic Opportunities
- Combination product partnerships:Injectable drug delivery systems that merge device mechanics with pharmaceutical containment are opening contracts that blur traditional outsourcing boundaries.
- Additive manufacturing adoption:Patient-specific implants and surgical instruments produced through metal 3D printing enable premium pricing for contract manufacturers with in-house powder bed fusion capabilities.
- Digital health pre-certification pathway:FDA's streamlined software validation framework permits faster market entry for AI-enabled diagnostic devices, rewarding partners with health technology competencies.
Industry Challenges
- Regulatory affairs talent scarcity:Contract manufacturers struggle to recruit specialists capable of navigating FDA's Medical Device Reporting framework and ISO 13485:2016 transition simultaneously.
- Legacy system integration:Electronic batch records and automated inspection equipment must interface with decades-old MES platforms at OEM facilities, complicating data integrity validation.
- Supply chain reconfiguration:Reshoring printed circuit board assembly from Asia-Pacific requires qualifying domestic electronics subcontractors under FDA quality system regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Device Outsourcing Market |
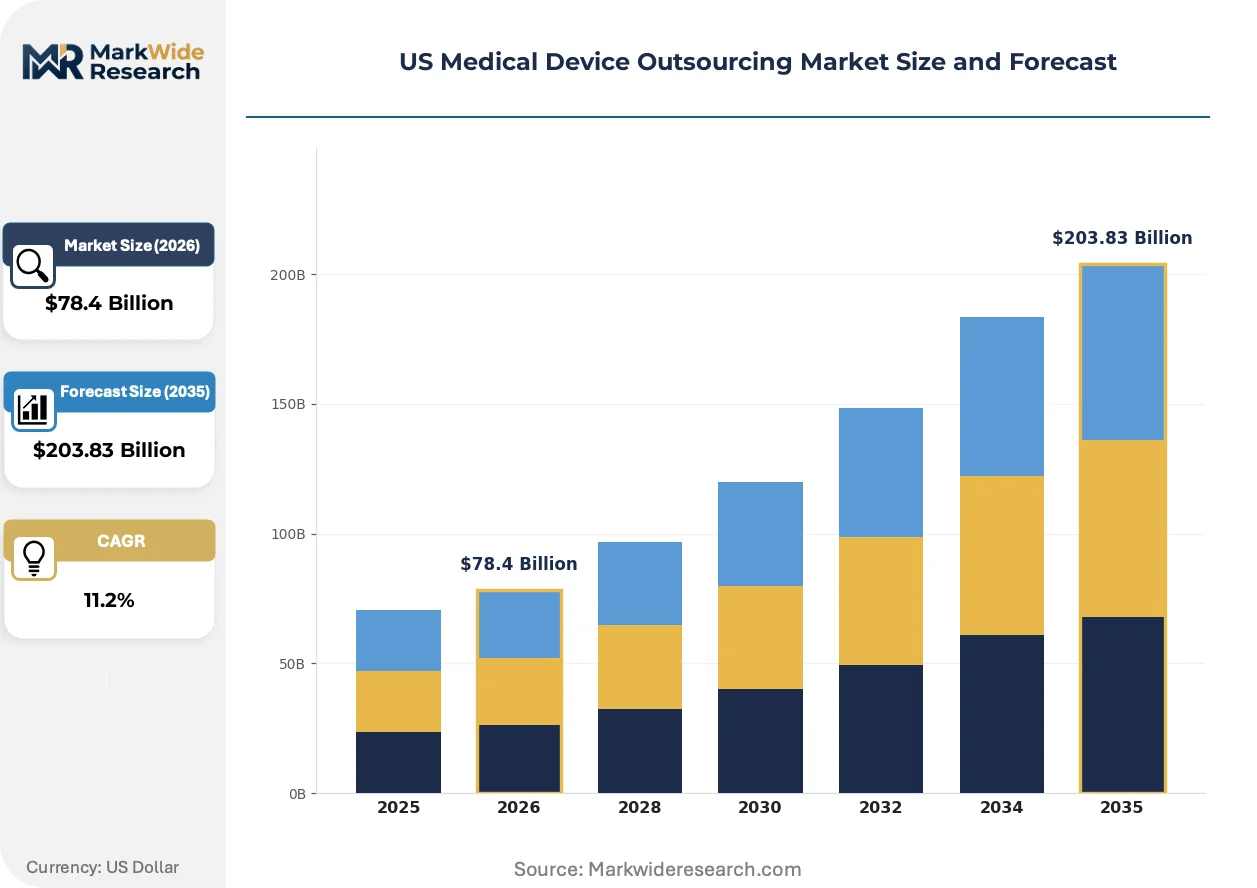
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $203.83 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Manufacturing, Packaging, Sterilization, Distribution Product Type: Diagnostic Devices, Surgical Instruments, Imaging Equipment, Implantable Devices End User: Hospitals, Clinics, OEMs, Contract Manufacturers Technology: Electronics, Robotics, Biocompatible Materials, Software |
| Companies Covered | Integer Holdings Corporation, West Pharmaceutical Services Inc., Jabil Inc., Labcorp Holdings Inc., Charles River Laboratories International Inc., Flex Ltd., Plexus Corp., Celestica Inc., Sanmina Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Device Outsourcing Market Strategic Shifts & Innovations
Additive manufacturing workflows are fragmenting traditional production economics across implantable device categories, compressing lot sizes and forcing contract manufacturers to reconfigure floor layouts around powder bed fusion cells rather than machining centers.
Metal 3D printing with titanium and cobalt-chrome alloys enables lattice-structured orthopedic implants with bone-matching mechanical properties. Spinal fusion and cranial plate OEMs are qualifying these builds for patient-matched production runs as small as single units. Conventional five-axis machining for complex implant geometries is rendering obsolete for geometries exceeding certain complexity thresholds.
FDA's Medical Device Single Audit Program streamlines third-party inspections but demands documentation infrastructure that smaller contract manufacturers cannot sustain. The agency's enforcement of Quality System Regulation violations has intensified, elevating compliance costs and driving sponsor preference toward established players with mature quality management systems. Diagnostic device segments with software-intensive designs are most affected, as sponsors seek partners with pre-validated cybersecurity frameworks.
Cardiovascular OEM procurement teams are unbundling sterilization and packaging from manufacturing contracts to optimize working capital. This behavior concentrates purchasing power among sterilization specialists with ethylene oxide alternatives and accelerates demand for turnkey logistics providers capable of managing temperature-controlled distribution. Minnesota's Twin Cities corridor exhibits this pattern most visibly, where dense supplier networks enable rapid vendor switching.
US Medical Device Outsourcing Market Segmentation
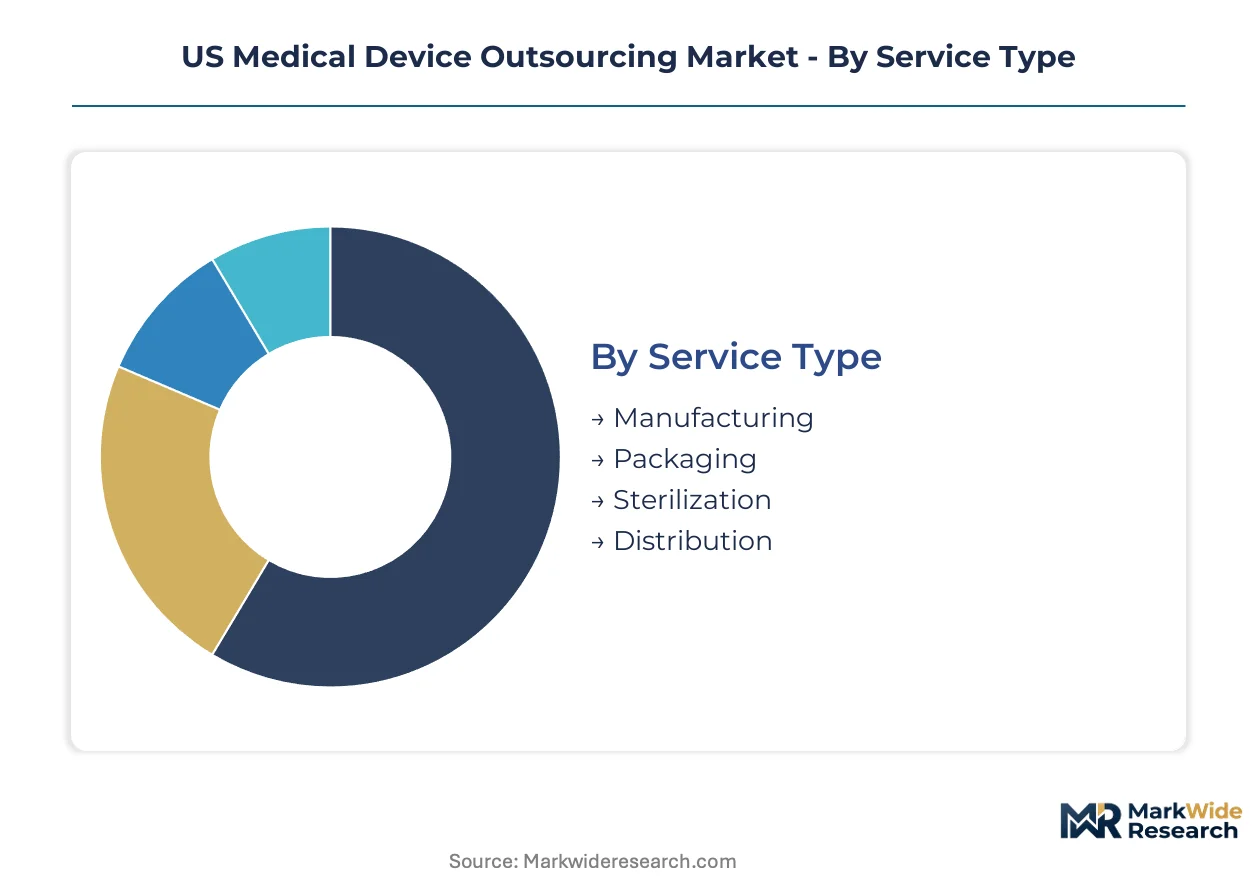
Medical device outsourcing segments reflect divergent regulatory burdens, capital intensity, and qualification timelines. Understanding these divisions reveals where contract manufacturers extract premium margins versus competing on throughput.
Service Type:
Mature sterilization and packaging operations coexist with emerging additive manufacturing services, creating a bifurcated competitive landscape.
- Manufacturing:Contract fabrication spans metal machining, plastic injection molding, and metal 3D printing for patient-specific implants. Minnesota's Twin Cities corridor concentrates demand for cardiovascular catheter production, where Integer Holdings and similar specialists maintain validated cleanroom suites under FDA 21 CFR Part 820.
- Sterilization:Ethylene oxide and gamma radiation modalities face capacity constraints concentrated among regional providers. FDA environmental scrutiny of ethylene oxide emissions is accelerating adoption of electron beam and vaporized hydrogen peroxide alternatives, though validation timelines extend qualification cycles.
- Packaging:Barrier systems for sterile devices combine Tyvek and medical-grade films with validated seal integrity testing. Demand clusters around implantable device launches requiring accelerated aging studies.
- Distribution:Temperature-controlled logistics for biologics and combination products extend contract manufacturer responsibilities through last-mile delivery. Cold chain validation under FDA distribution regulations elevates compliance costs for this segment.
Manufacturing retains volume leadership; sterilization holds the steepest expansion curve as capacity bottlenecks command pricing power.
Product Type:
Product categories stratify by biocompatibility testing burden and electronics integration complexity, with diagnostic and implantable segments diverging sharply in outsourcing economics.
- Diagnostic Devices:Blood glucose monitors, point-of-care testing platforms, and imaging peripherals require FCC certification alongside FDA clearance. Jabil Inc. and electronics-focused contract manufacturers capture programs demanding complex printed circuit board assemblies and wireless connectivity validation.
- Implantable Devices:Cardiac rhythm management systems, spinal fusion hardware, and cranial plates demand multi-year biocompatibility studies under ISO 10993. Extended qualification cycles lock OEMs into multi-year supply agreements with specialized partners.
- Surgical Instruments:Reusable and single-use instruments span electrosurgical devices to robotic surgery attachments. Minnesota-based suppliers leverage dense machining networks for rapid prototype-to-production transitions.
- Imaging Equipment:MRI coils, CT detector assemblies, and ultrasound transducers outsource component fabrication while OEMs retain system integration. Electronics-heavy subassemblies concentrate with partners possessing health technology competencies.
Diagnostic devices dominate transaction volume; implantable devices generate the highest contract values per program.
End User:
Customer type determines contract structure, with OEM procurement teams unbundling services while hospital systems demand turnkey solutions.
- OEMs:Original equipment manufacturers represent the core outsourcing demand, transferring design, engineering, and production to specialists with established FDA quality systems. Cardiovascular innovators increasingly unbundle sterilization and packaging to optimize working capital deployment.
- Contract Manufacturers:Tier-2 and tier-3 subcontractors handle specialized processes—nitinol shape setting, laser welding, or Parylene coating—beneath prime contract manufacturers. This tier concentrates in Massachusetts and California medical technology corridors.
- Hospitals:Health systems outsource device refurbishment, preventive maintenance, and sterilization validation for reusable surgical instruments. Group purchasing organizations consolidate demand for third-party reprocessing services.
- Clinics:Ambulatory surgery centers and specialty clinics represent emerging demand for single-use instrument kits and point-of-care diagnostic consumables, though direct outsourcing relationships remain limited.
OEMs anchor contract value; contract manufacturers represent the most fragmented procurement tier with consolidation pressure.
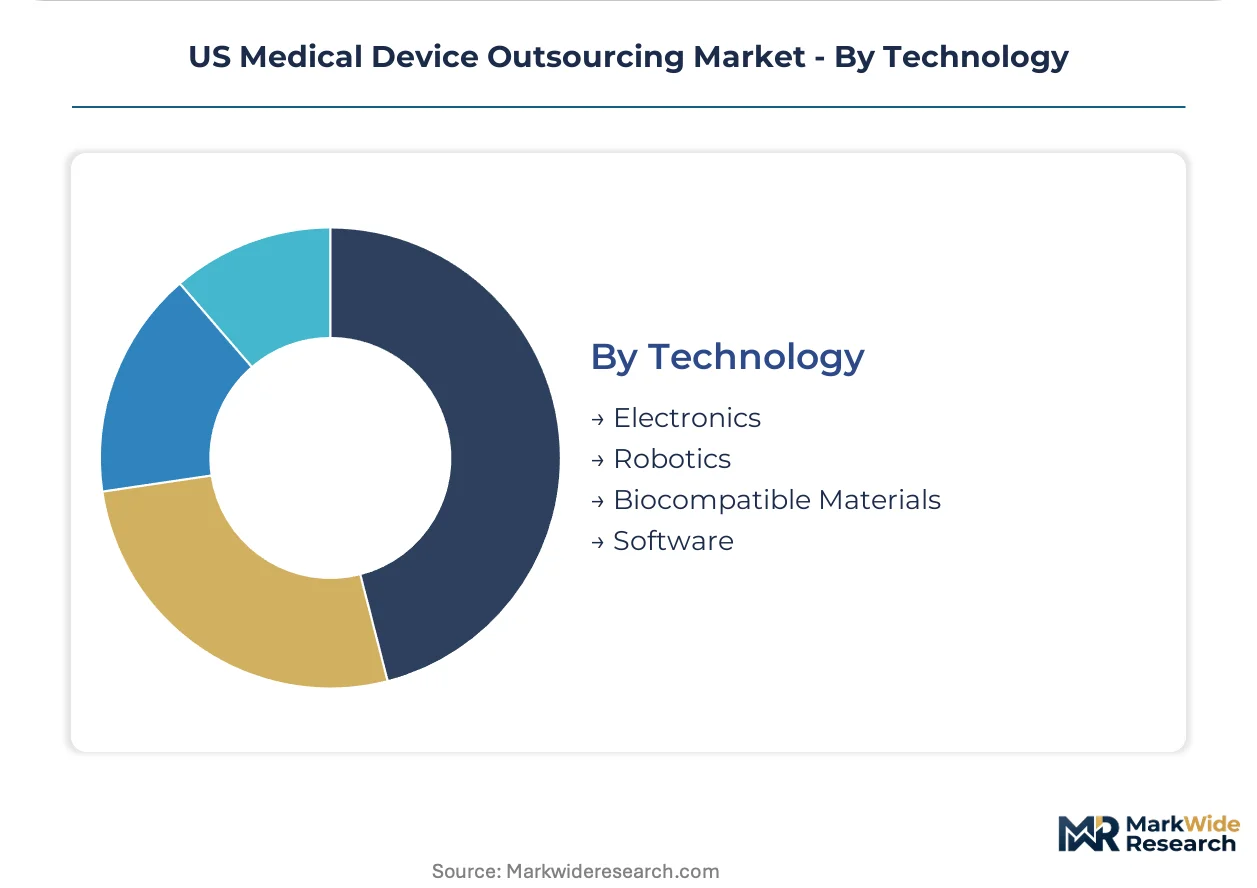
Technology:
Technology segments reflect the convergence of mechanical engineering, electronics, and biological materials under FDA's evolving regulatory frameworks.
- Biocompatible Materials:Titanium, cobalt-chrome, PEEK, and nitinol alloys require extensive cytotoxicity and sensitization testing. Powder bed fusion additive manufacturing is displacing conventional machining for lattice-structured orthopedic implants with bone-matching mechanical properties.
- Electronics:Embedded sensors, wireless telemetry, and battery systems power diagnostic and monitoring devices. FCC Part 15 and Part 18 compliance for electromagnetic compatibility runs parallel to FDA software validation requirements.
- Software:AI-enabled diagnostic algorithms and cybersecurity-hardened device firmware fall under FDA's digital health pre-certification pathway. Sponsors seek partners with pre-validated quality management systems for software as a medical device.
- Robotics:Surgical robot subassemblies—end effectors, force sensors, and haptic feedback systems—demand precision machining and cleanroom assembly. Da Vinci system suppliers anchor demand in California and Connecticut manufacturing clusters.
Biocompatible materials command the steepest qualification barriers; software is gaining share fastest as AI diagnostics proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US medical device outsourcing sector maintains a net export position in sterilization services and precision catheter manufacturing, though domestic OEMs import specialized electronics subassemblies from Asia-Pacific contract manufacturers. Trade flows concentrate through coastal logistics hubs serving FDA-regulated distribution networks.
Minnesota
The Twin Cities corridor anchors cardiovascular catheter production, with Minneapolis-St. Paul hosting dense clusters of contract manufacturers validated under FDA 21 CFR Part 820. Integer Holdings Corporation maintains cleanroom suites for cardiac rhythm management devices. Mayo Clinic's proximity accelerates clinical validation cycles for implantable prototypes.
Massachusetts
Greater Boston's medical technology corridor specializes in diagnostic device electronics and combination product development. Massachusetts-based subcontractors handle nitinol shape setting and laser welding for tier-2 manufacturing. FDA's Boston district office maintains active inspection schedules for local sterilization facilities.
California
The San Francisco Bay Area and Orange County concentrate surgical robotics subassembly and imaging equipment component fabrication. Da Vinci system suppliers cluster around precision machining networks in San Jose and Irvine. FCC Part 15 compliance for wireless-enabled devices runs parallel to FDA software validation requirements.
Pennsylvania
Southeastern Pennsylvania's pharmaceutical-device convergence zone supports injectable drug delivery system manufacturing. West Pharmaceutical Services anchors containment and closure system production near Philadelphia. The region's combination product partnerships blur traditional boundaries between pharma and device outsourcing.
Texas
The Dallas-Fort Worth metroplex hosts electronics manufacturing services for diagnostic devices requiring complex printed circuit board assemblies. Jabil Inc. sustains massive production scale across multiple Texas locations. Reshoring initiatives from Asia-Pacific are qualifying domestic subcontractors under FDA quality system regulations.
US Medical Device Outsourcing Market Key Industry Players
On the supply side, the industry is consolidating toward established players with dedicated regulatory affairs infrastructure capable of navigating FDA's ISO 13485:2016 transition. Three archetypes dominate: cardiovascular specialists with validated cleanroom capabilities, electronics-scale manufacturers serving diagnostic OEMs, and sterilization-focused regional providers. Competitive moves center on M&A to acquire FDA-audited facilities and strategic partnerships for combination product development.
Among the named specialists, Integer Holdings Corporation exemplifies the cardiovascular-focused archetype with deep catheter manufacturing expertise. West Pharmaceutical Services Inc. occupies a distinct position at the pharma-device boundary for injectable delivery systems. Jabil Inc. represents the scale-driven electronics tier competing for diagnostic device programs with complex PCB assembly requirements.
| Leading Market Players |
|---|
| Integer Holdings Corporation |
| West Pharmaceutical Services Inc. |
| Jabil Inc. |
| Labcorp Holdings Inc. |
| Charles River Laboratories International Inc. |
| Flex Ltd. |
| Plexus Corp. |
| Celestica Inc. |
| Sanmina Corporation |
| Others |
Cost & Logistics Intelligence
I-35 freight corridors connecting Texas electronics manufacturing to Minnesota medical device clusters impose fuel surcharges that amplify cost differentials between domestic PCB assembly and offshore alternatives, concentrating pricing power among sterilization specialists with ethylene oxide alternatives while squeezing margins for high-volume diagnostic contract manufacturers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based pricing structure where multi-year supply agreements lock in implantable device premiums. Pricing stratifies across FDA-validated cleanroom tiers, ISO 13485 certification levels, and volume scale commitments. Cost compression in diagnostic electronics manufacturing is intensifying because reshoring initiatives from Asia-Pacific force qualification of domestic subcontractors under 21 CFR Part 820. Hospital procurement teams exhibit the highest price sensitivity, while cardiovascular innovators prioritize biocompatibility assurance over unit economics.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment limit flows of critical chip fabrication tools to China, constraining domestic availability of specialized sensors for diagnostic devices. The US medical device supply chain draws from Mexico for precision machining, Malaysia for electronics assembly, and Germany for laser welding equipment. Raw material dependencies center on titanium powder for additive manufacturing, medical-grade silicone for catheters, and FR-4 substrate laminates for PCB assemblies. Single-source vulnerability concentrates in ethylene oxide sterilization capacity. Distribution runs through FDA-regulated cold chain networks with validated temperature monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's harmonization with ISO 13485:2016 constitutes a regulatory inflection that accelerates market disruption, elevating compliance costs and consolidating competitive position toward established players with mature quality management systems.
For Market Incumbents: Insulate sterilization and packaging revenue streams by acquiring electron beam and vaporized hydrogen peroxide alternatives ahead of EPA ethylene oxide emission restrictions. Backward integration into nitinol shape setting and laser welding capabilities secures tier-2 supply chain control against emerging precision machining specialists in Massachusetts and California corridors. For New Entrants and Emerging Players: Mid-market combination product partnerships for injectable drug delivery systems represent the most penetrable entry point, blurring traditional boundaries between pharmaceutical containment and device mechanics. Additive manufacturing cells for patient-specific orthopedic implants enable premium pricing without competing against Integer Holdings' catheter scale. Target hospital system direct contracts for reusable surgical instrument reprocessing services as group purchasing organizations consolidate third-party demand. For Investors and Strategic Acquirers: FDA's Medical Device Single Audit Program reshapes the acquisition landscape toward contract manufacturers with pre-validated documentation infrastructure capable of sustaining third-party inspection schedules. Five-to-ten year viability favors targets possessing dedicated regulatory affairs teams and established 21 CFR Part 820 compliance records. Monitor EPA enforcement actions on ethylene oxide emissions as the signal indicating sterilization capacity repricing and regional provider consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Pre-validated quality systems reduce clearance timelines for cardiovascular catheter innovators. |
| CE Marking Pathway Expansion | Dual regulatory positioning opens European diagnostic device procurement for US-based electronics manufacturers. |
| Hospital System Partnership | Direct GPO contracts for sterilization services bypass OEM unbundling and capture working capital optimization demand. |
| Software Companion Development | AI-enabled diagnostic algorithms qualify under FDA's digital health pre-certification pathway for faster market entry. |
| Reimbursement Strategy Alignment | CPT code validation for patient-specific 3D-printed implants secures favorable coverage decisions from CMS. |
Research Approach
A spread of perspectives from cardiovascular OEM procurement directors, FDA regulatory affairs consultants, sterilization facility operations managers, and hospital GPO contracts managers converged on the working assumptions. Primary interview insights combined with secondary validation from FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and EPA ethylene oxide emission reports. Bottom-up segment sizing and top-down market triangulation cross-checked contract manufacturer capacity announcements against OEM outsourcing disclosure patterns.
Demand-supply balance modeling across the projection horizon incorporated service type segmentation by manufacturing, sterilization, packaging, and distribution functions alongside product type stratification across diagnostic, implantable, surgical instrument, and imaging equipment categories. CAGRs derived from weighted average growth contributions across technology segments including biocompatible materials, electronics, software, and robotics. Forecast inputs included additive manufacturing adoption curves and FDA inspection backlog trends.
Practitioners should monitor EPA ethylene oxide regulation enforcement intensity and FDA digital health pre-certification pathway expansion for early signals of supply chain reconfiguration. Forecasts reflect documented assumptions regarding reshoring velocity and ISO 13485:2016 transition timelines. Material shifts in FDA quality system harmonization schedules or sterilization modality approval pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Lyophilized Injectable Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Corneal Implants Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Laryngeal Masks Market
Medical Devices
Aortic Cannula Systems Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
PET Injectors Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Electric Massage Equipment Market