
 Chile Ultrasound Devices Market | 2026-2036
Chile Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Ultrasound Devices Market Intelligence
Public hospital procurement is collapsing toward portable and point-of-care ultrasound systems as Chile's healthcare network decentralizes diagnostic capacity. GE Healthcare leverages its established service infrastructure to sustain long-term contracts with major public health institutions. Mindray Medical International Limited competes aggressively on total cost of ownership, while Samsung Medison differentiates through compact system design tailored for ambulatory settings.
Chile ultrasound devices are electronic imaging systems that generate real-time anatomical visualizations through piezoelectric transducers operating at frequencies between 2 and 18 megahertz, primarily serving diagnostic visualization and interventional guidance across clinical environments. Diagnostic ultrasound systems anchor the product mix through established radiology department workflows, while portable ultrasound represents the fastest-expanding category as emergency departments and rural clinics prioritize mobility over premium cart-based specifications. Doppler technology commands attention in cardiology applications where hemodynamic assessment determines clinical utility.
Chile's Ministry of Health and the national health technology regulator shape market access through mandatory technical conformity assessments and import registration requirements for electro-medical equipment. These frameworks elevate compliance costs for new entrants while reinforcing incumbent positions among suppliers with established regulatory dossiers. Stakeholders must monitor pending updates to electrical safety standards and radiological protection protocols that will determine which product generations qualify for public tender participation.
Market Dynamics
Chile's public health decentralization is collapsing diagnostic capacity toward point-of-care deployment, forcing equipment specifications toward portability and wireless connectivity while Santiago's tertiary centers drive replacement demand for premium cart-based systems.
Growth Catalysts
- Ministry of Health technical standards:Updated national health technology regulations mandate equipment conformity assessments that favor incumbent suppliers with established regulatory dossiers and service networks.
- Emergency department workflow redesign:Public hospitals prioritize portable ultrasound for triage acceleration and bedside hemodynamic assessment, expanding addressable clinical settings beyond radiology.
- Santiago Metropolitan Region concentration:Tertiary care facility density in Chile's capital generates replacement cycles and new installation demand that outpaces other regional health networks.
Market Restraints
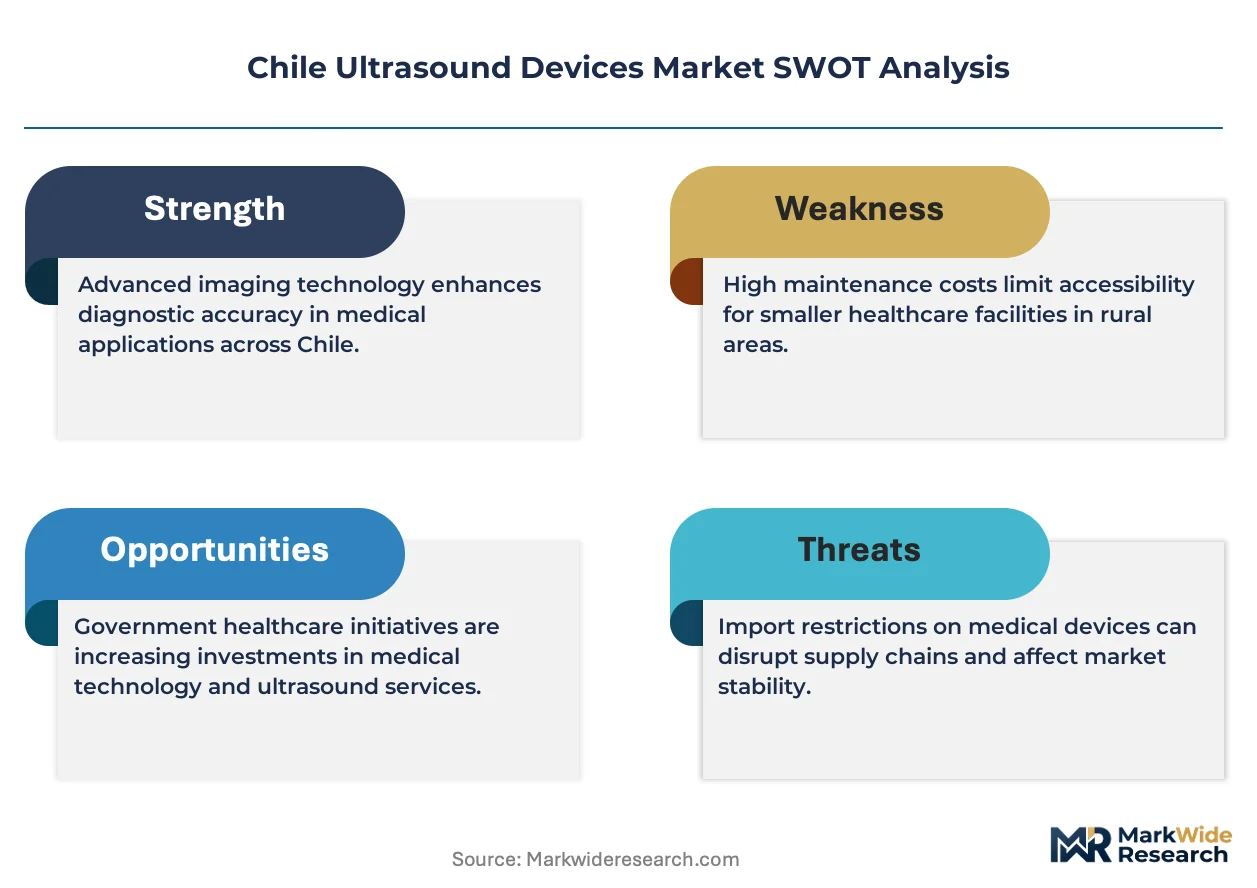
- Import registration requirements:Chile's national health technology regulator imposes mandatory electro-medical equipment registration that elevates compliance costs and extends market entry timelines for new suppliers.
- Service infrastructure concentration:Technical support and preventive maintenance capabilities concentrate among established multinational suppliers, creating switching costs for public institutions.
- Biomedical engineering talent scarcity:Specialized ultrasound technician training programs remain concentrated in Santiago, limiting deployment scalability to rural and remote clinic networks.
Strategic Opportunities
- Rural clinic network expansion:Chile's decentralized primary care infrastructure creates white space for battery-powered compact systems with simplified user interfaces and reduced training requirements.
- Interventional guidance applications:Convergence of ultrasound visualization with needle navigation and procedure planning software opens vascular access and regional anesthesia segments.
- Telemedicine integration:Cloud-connected portable systems enable remote specialist consultation for cardiac and obstetric screening in underserved provincial health districts.
Industry Challenges
- Biomedical equipment certification timelines:Electrical safety standard updates and radiological protection protocol revisions pending at the Ministry of Health create product qualification uncertainty for tender participation.
- Legacy system integration complexity:Hospital information system interoperability requirements and DICOM compliance variations across public health networks complicate enterprise-wide deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Ultrasound Devices Market |
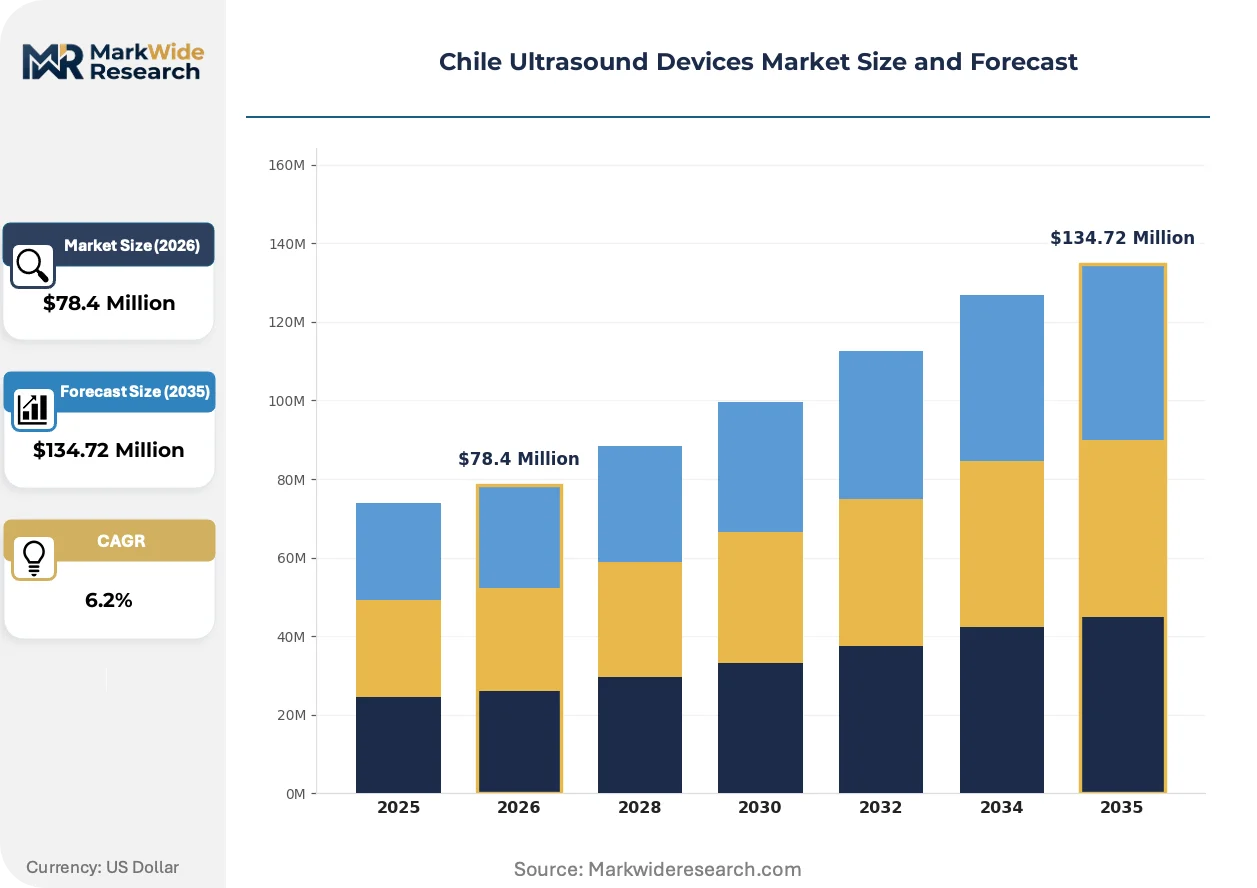
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $134.72 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, 3D Ultrasound, Portable Ultrasound End User: Hospitals, Clinics, Diagnostic Centers, Home Care Technology: Analog, Digital, Doppler, 3D/4D Application: Obstetrics, Cardiology, Urology, Emergency Care |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, Samsung Medison, Mindray Medical International Limited, Fujifilm Holdings Corporation, Hitachi Medical Corporation, Esaote S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Ultrasound Devices Market Strategic Shifts & Innovations
Portable ultrasound architecture is bifurcating from premium cart-based platforms, creating parallel equipment categories with distinct specification hierarchies, pricing bands, and service models that reshape competitive positioning across Chile's stratified health network.
Handheld wireless transducer technology is bifurcating diagnostic ultrasound into smartphone-connected probes and tablet-based systems. Emergency departments and ambulatory clinics adopt these devices for rapid anatomical screening and procedural guidance. The technology is bifurcating procurement decisions between centralized radiology capital budgets and decentralized department-level equipment purchases.
Chile's Ministry of Health has strengthened technical conformity assessments for electro-medical equipment under updated national health technology regulations. These frameworks elevate documentation requirements for electrical safety and electromagnetic compatibility testing. Public tender participation now depends on validated regulatory dossiers that incumbent suppliers maintain more readily than new market entrants.
Public hospital procurement patterns are fragmenting across centralized ministry tenders, regional health service direct purchases, and individual facility emergency acquisitions. Traditional distributor-led sales cycles face displacement from manufacturer-direct service contracts and equipment-as-a-service arrangements. Santiago's largest tertiary centers exhibit the most pronounced procurement autonomy, while provincial networks retain centralized purchasing discipline.
Chile Ultrasound Devices Market Segmentation
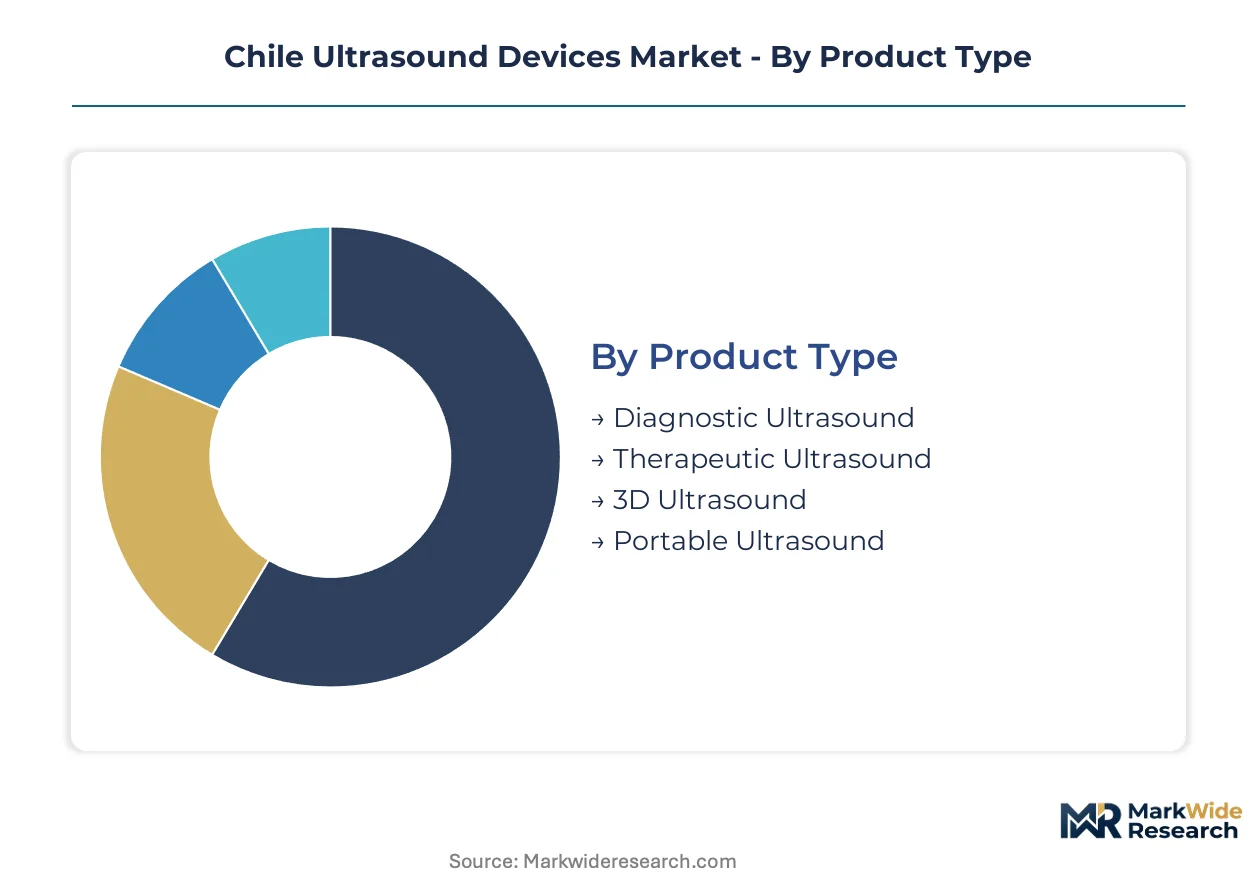
Chile's ultrasound device segmentation reveals divergent margin structures across product architectures and care settings. Portable and 3D systems command premium pricing in decentralized deployment, while hospital-based diagnostic platforms anchor volume throughput in Santiago's consolidated tertiary network.
Product Type:
Margin pools concentrate in portable ultrasound systems where decentralized procurement and premium mobility specifications generate superior unit economics against commoditized cart-based alternatives.
- Diagnostic Ultrasound:Conventional cart-based systems with multi-transducer configurations serve radiology departments and specialized imaging suites. Santiago Metropolitan Region's tertiary hospitals drive replacement cycles as legacy platforms age out of service contracts.
- Portable Ultrasound:Battery-powered compact systems with wireless connectivity are expanding most quickly across emergency departments and rural clinic networks. Chile's Ministry of Health technical standards favor established suppliers with validated service infrastructure for these decentralized deployments.
- Therapeutic Ultrasound:Focused acoustic energy systems for physiotherapy and tissue ablation applications serve rehabilitation centers and interventional suites.
- 3D Ultrasound:Volumetric reconstruction platforms with real-time rendering capabilities target obstetric and cardiac imaging workflows in premium hospital settings.
Diagnostic ultrasound holds installed capacity. Portable ultrasound is rotating up the share rankings.
End User:
Customer-type segmentation shows volume concentration in hospital procurement, though margin expansion tracks toward ambulatory and point-of-care settings where equipment specifications command mobility premiums.
- Hospitals:Public tertiary centers in Santiago Metropolitan Region anchor capital expenditure for premium cart-based systems with advanced Doppler and 3D capabilities. Ministry of Health tender processes consolidate purchasing power across the largest facilities.
- Clinics:Primary care networks and specialty outpatient facilities prioritize compact systems with simplified user interfaces. Chile's decentralized health infrastructure creates procurement fragmentation across regional health service jurisdictions.
- Diagnostic Centers:Dedicated imaging facilities concentrate high-throughput screening workflows for obstetric and cardiac applications.
- Home Care:Emerging deployment of handheld wireless probes for remote patient monitoring and telemedicine consultation in underserved provincial districts.
Hospitals retain volume dominance. Clinics are climbing the fastest in procurement priority.
Technology:
Technology tiering separates legacy analog platforms from digital architectures, with Doppler and 3D/4D modalities capturing margin premiums in specialized clinical applications.
- Digital:Fully digitized beamforming and image processing architectures enable software-defined feature expansion and cloud connectivity. Public hospital procurement specifications increasingly mandate digital platforms for interoperability with hospital information systems.
- Doppler:Frequency-shift detection systems for hemodynamic assessment anchor cardiology and vascular imaging workflows. Santiago's largest cardiac centers specify Doppler capability as mandatory for echocardiography platforms.
- Analog:Legacy analog signal processing platforms remain in limited service for basic screening applications in resource-constrained settings.
- 3D/4D:Volumetric acquisition with temporal resolution for real-time fetal and cardiac imaging commands premium positioning in obstetric and pediatric cardiology departments.
Digital platforms hold installed capacity. Doppler is rotating up the share rankings.
Application:
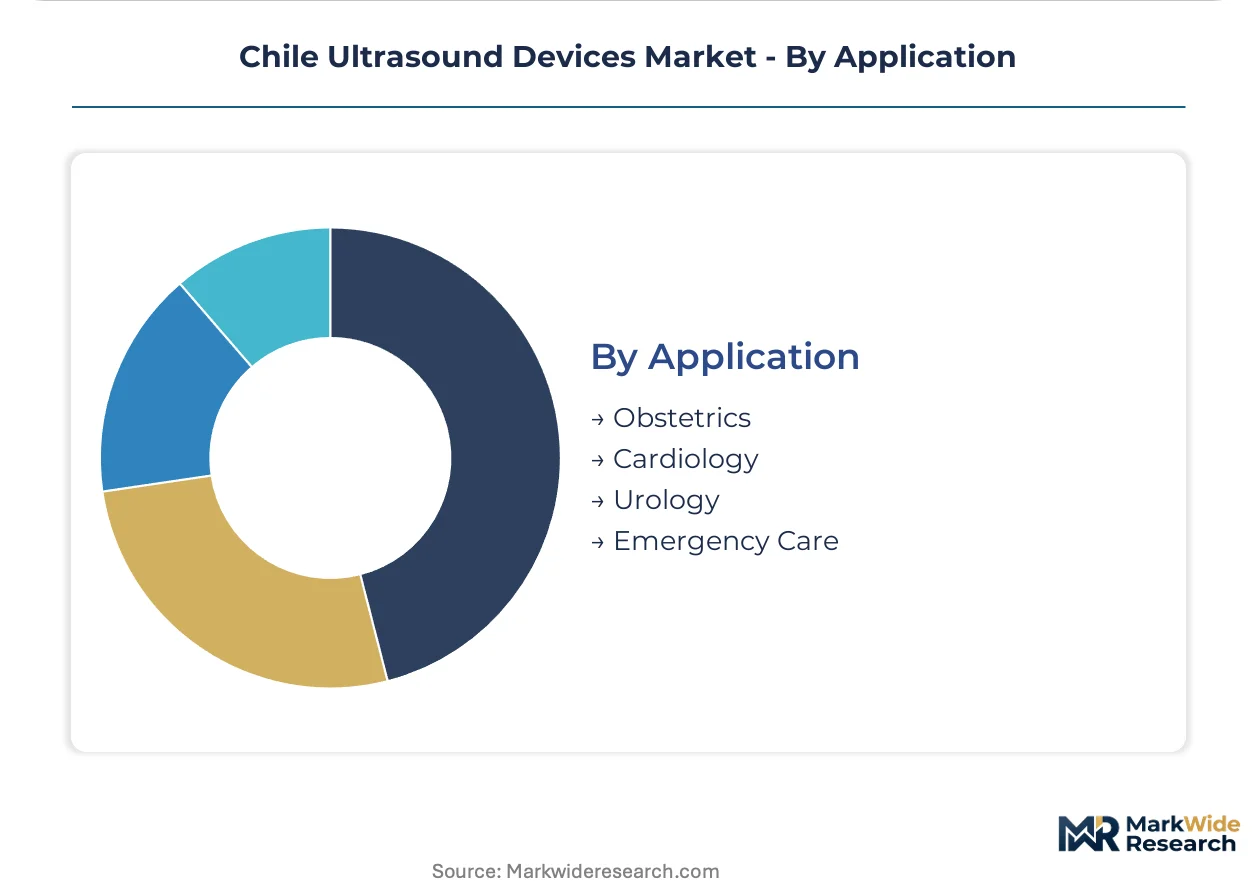
Application segmentation tracks clinical workflow specialization, with obstetrics and cardiology commanding dedicated platform configurations while emergency care drives portable adoption.
- Obstetrics:Fetal imaging platforms with biometric measurement packages and 3D/4D rendering serve maternity wards and dedicated women's health centers. Chile's public health network prioritizes obstetric screening capacity expansion in primary care settings.
- Emergency Care:Rapid triage and bedside hemodynamic assessment applications prioritize portable and handheld systems with simplified protocols. Chile's emergency department workflow redesign mandates ultrasound accessibility for trauma and critical care teams.
- Cardiology:Echocardiography platforms with phased-array transducers and advanced Doppler modes serve dedicated cardiac imaging suites.
- Urology:Transabdominal and transrectal imaging configurations target prostate and renal assessment in urology departments and diagnostic centers.
Obstetrics holds installed capacity. Emergency care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile exports ultrasound devices primarily to neighboring South American markets while importing advanced imaging systems from Germany, Japan, and the United States. Trade flows concentrate through the Valparaíso port corridor, connecting Santiago's procurement hubs to Pacific shipping lanes serving regional health networks.
Santiago Metropolitan Region
Chile's capital anchors national demand through tertiary care density and replacement cycles for aging radiology platforms. The Ministry of Health's technical conformity assessments for electro-medical equipment apply most stringently here, where public hospital tenders consolidate purchasing power. Clínica Las Condes and Hospital Clínico Universidad de Chile drive premium system installations.
Valparaíso Region
Port logistics and maritime health services generate specialized demand for portable diagnostic systems serving coastal populations. The regional health service (Servicio de Salud Valparaíso-San Antonio) prioritizes point-of-care deployment under decentralized procurement authority. Viña del Mar's private clinic cluster sustains mid-tier equipment turnover.
Bío Bío Region
Industrial workforce health screening and regional hospital networks sustain steady diagnostic imaging demand. Concepción's Universidad de Concepción teaching hospital anchors academic medical imaging workflows. The regional health service expands primary care ultrasound access under national decentralization mandates.
Araucanía Region
Rural indigenous health networks and dispersed geography drive battery-powered portable system priorities. The Ministry of Health's Mapuche health initiative channels equipment toward Temuco-based regional facilities. Villarrica's tourist corridor generates seasonal demand for emergency diagnostic capacity.
Antofagasta Region
Mining sector occupational health programs and remote desert communities create dual demand streams for ruggedized portable systems. The regional health service manages equipment distribution across vast distances under constrained biomedical engineering coverage. Calama's mining health clinics represent specialized end-user concentration.
Chile Ultrasound Devices Market Key Industry Players
Player mix skews toward multinational health technology conglomerates with established regulatory dossiers and service infrastructure. Market structure concentrates around three to four dominant suppliers capturing public tender participation through pre-qualified equipment portfolios. Strategic archetypes separate premium cart-based platform specialists, portable system innovators, and total-cost-of-ownership competitors. Capacity expansion through localized service depot investment and strategic partnerships with regional distributors represent the dominant competitive moves.
Within the premium-tier vector, GE Healthcare and Koninklijke Philips N.V. occupy positions anchored by long-term service contracts with major public health institutions. Siemens Healthineers exemplifies the technology-integrated archetype, while Mindray Medical International Limited represents aggressive total-cost-of-ownership positioning. Samsung Medison sits within the compact design specialization, and Canon Medical Systems Corporation anchors the diversified imaging portfolio tier.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Samsung Medison |
| Mindray Medical International Limited |
| Fujifilm Holdings Corporation |
| Hitachi Medical Corporation |
| Esaote S.p.A. |
| Others |
Cost & Logistics Intelligence
Ninety-day import registration timelines for electro-medical equipment in Chile compress distributor inventory cycles and concentrate pricing power among incumbent suppliers with pre-validated regulatory dossiers. Santiago's tertiary hospitals leverage consolidated tender volumes to extract service bundling concessions, while provincial networks absorb portability premiums for decentralized deployment.
Pricing Analysis
Current-generation digital beamforming platforms command substantial premiums over prior-generation analog systems and emerging next-generation AI-augmented architectures. Pricing stratifies across premium cart-based systems with 3D/4D capabilities, standard portable configurations for departmental deployment, and economy-tier handheld probes for primary care screening. Price differentiation centers on Doppler sophistication and wireless connectivity specifications. Cost compression in the economy tier intensifies as Chinese manufacturers expand CE-marked product availability. Public hospital procurement committees exhibit highest price sensitivity, while private cardiac centers prioritize performance specifications over acquisition cost.
Supply Chain Analysis
Just-in-time inventory preferences dominate among established distributors serving Santiago's consolidated hospital networks, while strategic stockpiling characterizes regional health service procurement for remote clinic deployment. Manufacturing concentration rests on Germany, Japan, and the United States for premium imaging platforms, with China and South Korea supplying mid-tier portable systems. Piezoelectric crystal arrays, application-specific integrated circuits, and lithium-ion battery packs constitute critical component dependencies. Single-source vulnerability concentrates in specialized transducer manufacturing. Distribution runs through authorized dealer networks with mandatory Chilean Ministry of Health registration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's ultrasound device market fragments across three procurement channels—centralized ministry tenders, regional health service direct purchases, and facility-level emergency acquisitions—creating niche entry points for specialized competitors. Public hospital decentralization redistributes demand toward point-of-care specifications that incumbent cart-based portfolios underserve.
For Market Incumbents: Secure long-term service contracts with Santiago's largest tertiary centers to anchor replacement cycle participation against emerging portable specialists. Invest in localized biomedical engineering training programs to address technician scarcity that limits competitor scalability to provincial networks. Vertical integration into cloud-connected software platforms defends margin position as hardware commoditization accelerates in the handheld segment. For New Entrants and Emerging Players: Differentiate on total cost of ownership for regional health service procurement outside Santiago Metropolitan Region, where budget constraints outweigh brand preference. Target Araucanía and Antofagasta regions for battery-powered portable deployment, as geographic dispersion and indigenous health initiatives create procurement autonomy from centralized tenders. Pursue direct manufacturer-to-facility service contracts that bypass established distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because Chile's regulatory barrier elevation and service infrastructure concentration favor scaled incumbents with validated dossiers. Acquisition candidates include regional distributors with established Ministry of Health relationships and portable system specialists with proven rural deployment track records. Monitor pending electrical safety standard revisions as inflection indicator for product qualification disruption.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Validates conformity with EU medical device regulations for Chilean public tender eligibility. |
| Hospital System Partnership | Locks in multi-year equipment replacement schedules with Santiago's tertiary care networks. |
| Software Companion Development | Enables AI-augmented image analysis and telemedicine integration for rural clinic networks. |
| Reimbursement Strategy | Aligns portable ultrasound deployment with Chile's decentralized primary care financing mechanisms. |
| Biomedical Engineering Training Program | Addresses technician scarcity that constrains competitor expansion to provincial health districts. |
Research Approach
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, regional health service procurement officers, and ultrasound equipment distributors, and refined through secondary validation. Primary fieldwork combined structured interviews with Chilean Ministry of Health technology assessment officials and private clinic administrators. Secondary sources encompassed ANMAT-equivalent regulatory filings, public hospital tender documentation, GPO contract databases, and electro-medical equipment import records. Bottom-up installed base estimates triangulated against top-down healthcare expenditure flows.
Variance decomposition across product type, technology tier, end-user setting, and regional health network density structured the analytical framework. Segmentation-level growth trajectories derived from replacement cycle timing, decentralization policy implementation pace, and penetration rate differentials between Santiago and provincial markets. Modeled inputs incorporated Ministry of Health capital budget allocations, regional health service autonomy indices, and transducer technology migration curves.
Material uncertainties—regulatory standard revision timing, public health emergency procurement disruptions, and currency fluctuation impacts on import costs—sit outside the modeled envelope. Forecasts reflect documented assumptions regarding continued decentralization momentum and stable regulatory compliance cost structures. Revision becomes warranted when biomedical engineering training program expansion crosses thresholds that materially alter rural deployment feasibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Composite Market
Medical Devices
Single-Use Assemblies Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Organ Care Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Australia Spinal Surgery Devices Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
IV Poles Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Global Photobiostimulation Market