
 PET Injectors Market | 2026-2036
PET Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
PET Injectors Market Analytics
Modular injector configurations paired with dose-calibration software is broadening procurement options for hospital radiopharmacy departments. GE HealthCare leverages integrated PET-CT workflows to sustain installed-base loyalty across major academic centers. Siemens Healthineers anchors European supply chains through region-specific service contracts and regulatory pre-certification. MEDRAD (Bayer) differentiates via closed-loop vial transfer systems that reduce technologist radiation exposure.
PET injectors are electromechanical or automated precision dispensing systems engineered to administer radiopharmaceutical doses with activity accuracy typically within five percent, designed for integration with cyclotron-produced tracers in nuclear medicine workflows. The multi-dose product category leads current procurement volumes where throughput efficiency governs capital allocation, while disposable syringe formats capture expanding share in infection-control-sensitive environments. Electromechanical technology dominates installed bases due to reproducible calibration protocols, yet automated segments attract replacement demand as labor costs rise and dose traceability mandates tighten across hospital accreditation frameworks.
The FDA governs device clearance through 510(k) pathways while the Nuclear Regulatory Commission enforces dose accountability standards that directly shape injector software validation requirements. In Europe, the MDR and EMA's radiopharmaceutical guidelines are extending conformity assessment burdens onto injector manufacturers seeking CE-marked access. Stakeholders must weigh cyclotron co-location strategies against centralized radiopharmacy distribution when sizing injector capacity and service footprints.
Market Dynamics
The FDA's updated guidance on radiopharmaceutical compounding is tightening quality protocols and forcing manufacturers to revalidate injector software architectures. This regulatory compression is accelerating replacement cycles across installed bases while concentrating procurement authority within hospital radiopharmacy departments.
Growth Catalysts
- Oncology Precision Dosing:Academic medical centers are expanding PET injector fleets to support theranostic protocols requiring activity accuracy within five percent. This clinical pull is reshaping capital allocation priorities.
- Cyclotron Network Expansion:Germany, China, and the United States are constructing regional cyclotron hubs that demand co-located dispensing infrastructure with integrated dose-calibration capabilities.
- Technologist Safety Mandates:Closed-loop vial transfer systems are becoming standard specification as nuclear medicine departments prioritize ALARA compliance and staff retention.
Market Restraints
- Molybdenum-99 Supply Concentration:Generator-dependent sites face vulnerability from the limited number of high-enriched uranium conversion facilities operating in Europe and South Africa.
- MDR Conformity Burden:Europe's Medical Device Regulation is extending assessment timelines for CE-marked injectors, delaying market access for new entrants by twelve to eighteen months.
- Disposable Cost Inflation:Single-use syringe formats carry per-procedure consumable loads that strain outpatient clinic operating budgets relative to multi-dose alternatives.
Strategic Opportunities
- Centralized Radiopharmacy Distribution:Hub-and-spoke models in mid-tier US hospital systems allow injector fleet consolidation across multiple imaging sites.
- AI-Enabled Dose Prediction:Machine learning integration with patient-specific pharmacokinetic modeling is opening premium pricing tiers for software-augmented systems.
- Infection-Control Differentiation:Disposable cartridge formats are capturing share in ambulatory surgical centers where Joint Commission accreditation pressures intensify.
Industry Challenges
- Qualified Technologist Shortage:Nuclear medicine training program enrollment lags behind cyclotron installation rates, constraining operational uptime for sophisticated injector platforms.
- Legacy PACS Integration:DICOM connectivity standards vary across vendor ecosystems, complicating workflow automation in mixed-modality departments.
- Service Footprint Scaling:Preventive maintenance contracts require geographic proximity to cyclotron sites, challenging profitability in dispersed rural markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Injectors Market |
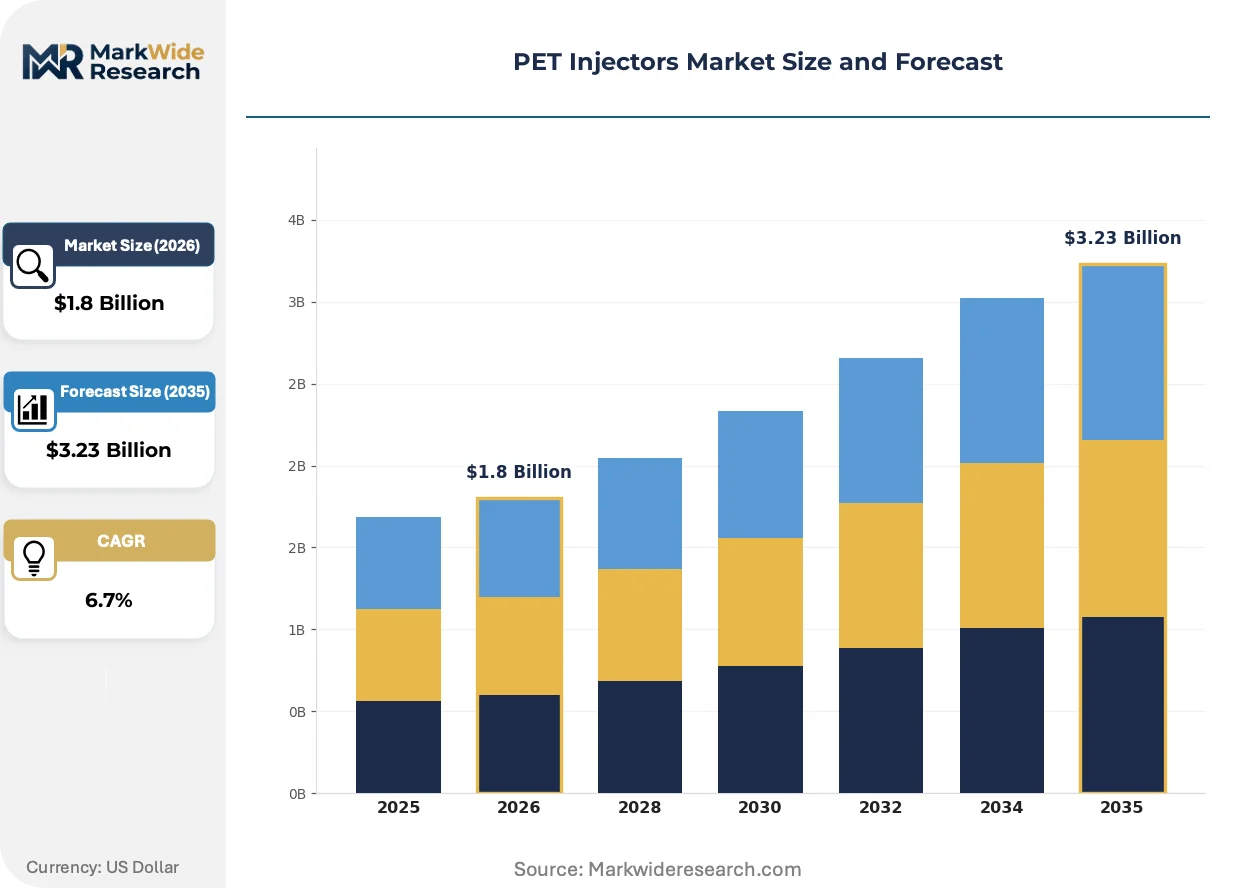
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Dose, Multi-Dose, Prefilled, Disposable End User: Hospitals, Clinics, Research Labs, Pharmaceutical Companies Technology: Electromechanical, Manual, Automated, Hybrid Application: Diagnostic Imaging, Therapeutic Delivery, Research, Clinical Trials |
| Companies Covered | GE HealthCare, Siemens Healthineers, MEDRAD (Bayer), Comecer, DoseTech Systems, Philips Healthcare, Canon Medical Systems, Eckert & Ziegler, IRE EluGa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Injectors Market Evolving Landscape
Automated dispensing architectures are displacing electromechanical platforms as labor costs rise and dose traceability mandates tighten across hospital accreditation frameworks. Three convergent developments are compressing technology refresh cycles.
Closed-loop activity verification systems is electrifying competitive positioning among precision injector manufacturers. These platforms integrate real-time gamma detector feedback with pneumatic dispensing control to eliminate manual assay steps. Community hospital radiopharmacies are adopting this technology fastest where staffing ratios limit technologist availability. The shift is compressing service contract pricing power for legacy electromechanical vendors.
Europe's MDR and EMA radiopharmaceutical guidelines are extending post-market surveillance obligations onto injector software validation. Manufacturers must now submit periodic safety update reports and maintain technical documentation for the full device lifecycle. Mid-cap specialists without dedicated regulatory affairs teams are ceding share to larger competitors with pre-certified quality management systems.
Academic medical centers are consolidating PET injector procurement under centralized radiopharmacy governance rather than decentralized department ownership. This organizational restructuring favors multi-dose platforms with remote monitoring capabilities over single-patient units. The pattern is most pronounced in US integrated delivery networks where capital committees prioritize fleet standardization.
PET Injectors Market Segmentation
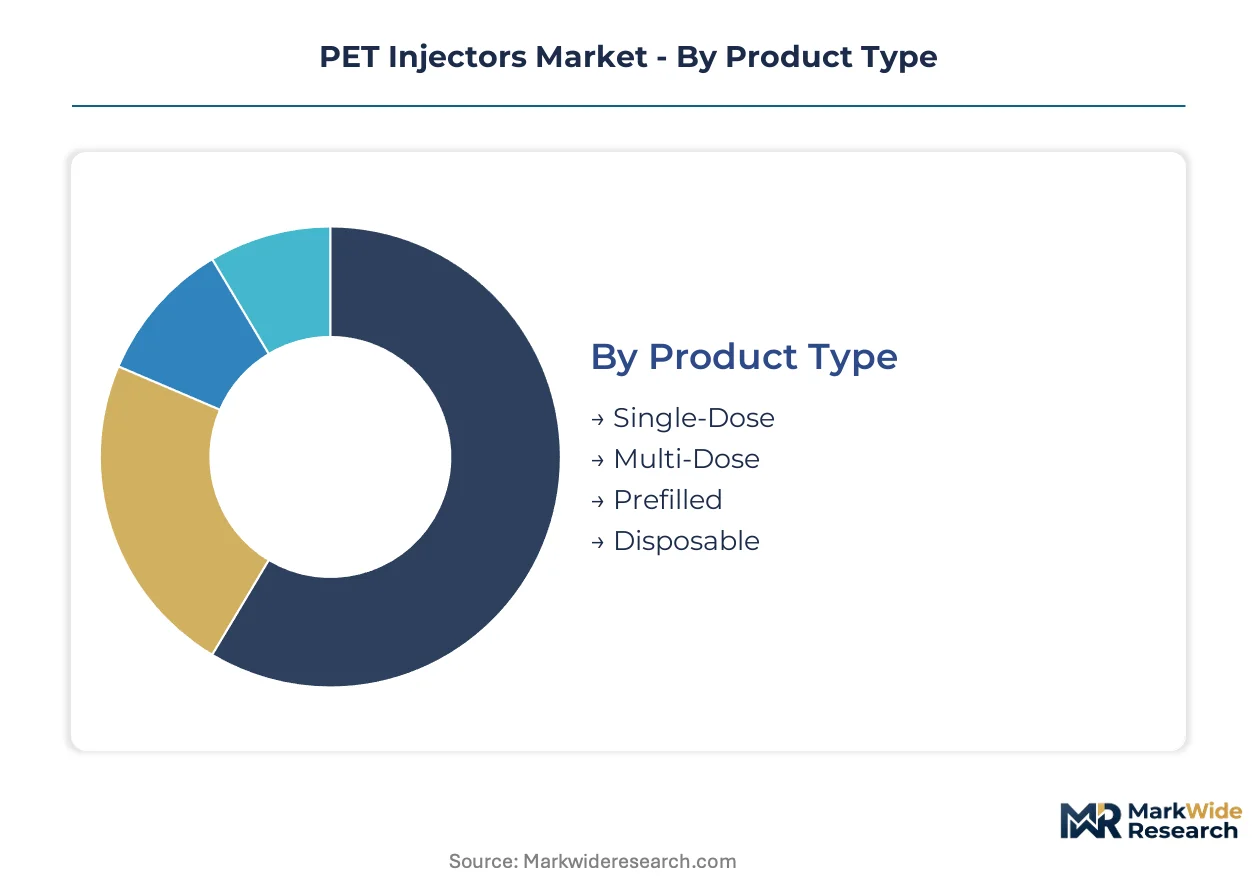
PET injector procurement divides sharply between throughput-optimized hospital radiopharmacies and precision-focused research environments. Understanding these segment boundaries clarifies where capital allocation concentrates and which technical specifications govern purchasing decisions.
Product Type:
Configuration architecture determines capital intensity, consumable burden, and infection control compliance across nuclear medicine workflows.
- Multi-Dose:These systems enable sequential patient dosing from single radiopharmaceutical vials through calibrated activity dispensing. Academic medical centers in the United States deploy multi-dose platforms most heavily where cyclotron co-location supports high-throughput oncology protocols demanding five percent activity accuracy.
- Disposable:Single-patient cartridge formats eliminate cross-contamination risk and reduce technologist radiation exposure through closed-loop transfer. Ambulatory surgical centers in Germany are adopting disposable configurations fastest as Joint Commission accreditation pressures intensify infection control documentation.
- Single-Dose:Dedicated vial-to-patient systems serve low-volume sites with straightforward calibration protocols.
- Prefilled:Factory-sealed unit doses from centralized radiopharmacies streamline workflow for satellite imaging centers without on-site compounding.
Mature deployment sits with Multi-Dose. Newer deployment is concentrated in Disposable.
End User:
Customer organizational structure shapes service contract terms, software integration requirements, and preventive maintenance scheduling.
- Hospitals:Integrated delivery networks consolidate PET injector procurement under centralized radiopharmacy governance with fleet standardization mandates. These institutions prioritize remote monitoring capabilities and DICOM connectivity across mixed-modality departments in China.
- Research Labs:Preclinical and translational facilities require ultra-low-volume precision for tracer development and pharmacokinetic modeling. Lawrence Berkeley National Laboratory and comparable institutions drive demand for automated platforms with programmable infusion profiles.
- Clinics:Outpatient imaging centers balance capital constraints against procedure volume targets.
- Pharmaceutical Companies:Sponsor-funded clinical trials impose audit-ready dose traceability and chain-of-custody documentation.
Capital concentration favors Hospitals. Steepest expansion trajectory belongs to Research Labs.
Technology:
Actuation mechanism governs calibration reproducibility, labor dependency, and regulatory validation burden.
- Electromechanical:Stepper motor-driven syringe actuation delivers reproducible displacement with established service protocols. These platforms dominate installed bases at German university hospitals where preventive maintenance contracts require geographic proximity to cyclotron sites.
- Automated:Pneumatic dispensing with real-time gamma detector feedback eliminates manual assay steps and compresses dose preparation time. Community hospital radiopharmacies in the United States are adopting automated systems fastest where staffing ratios limit technologist availability.
- Manual:Hand-operated systems persist in resource-constrained settings with low procedure volumes.
- Hybrid:Configurations blending electromechanical reliability with automated verification stages serve transitional upgrade paths.
Electromechanical retains the largest installed base. Automated is gaining share fastest.
Application:
Clinical purpose determines tracer selection, dose range requirements, and software validation protocols.
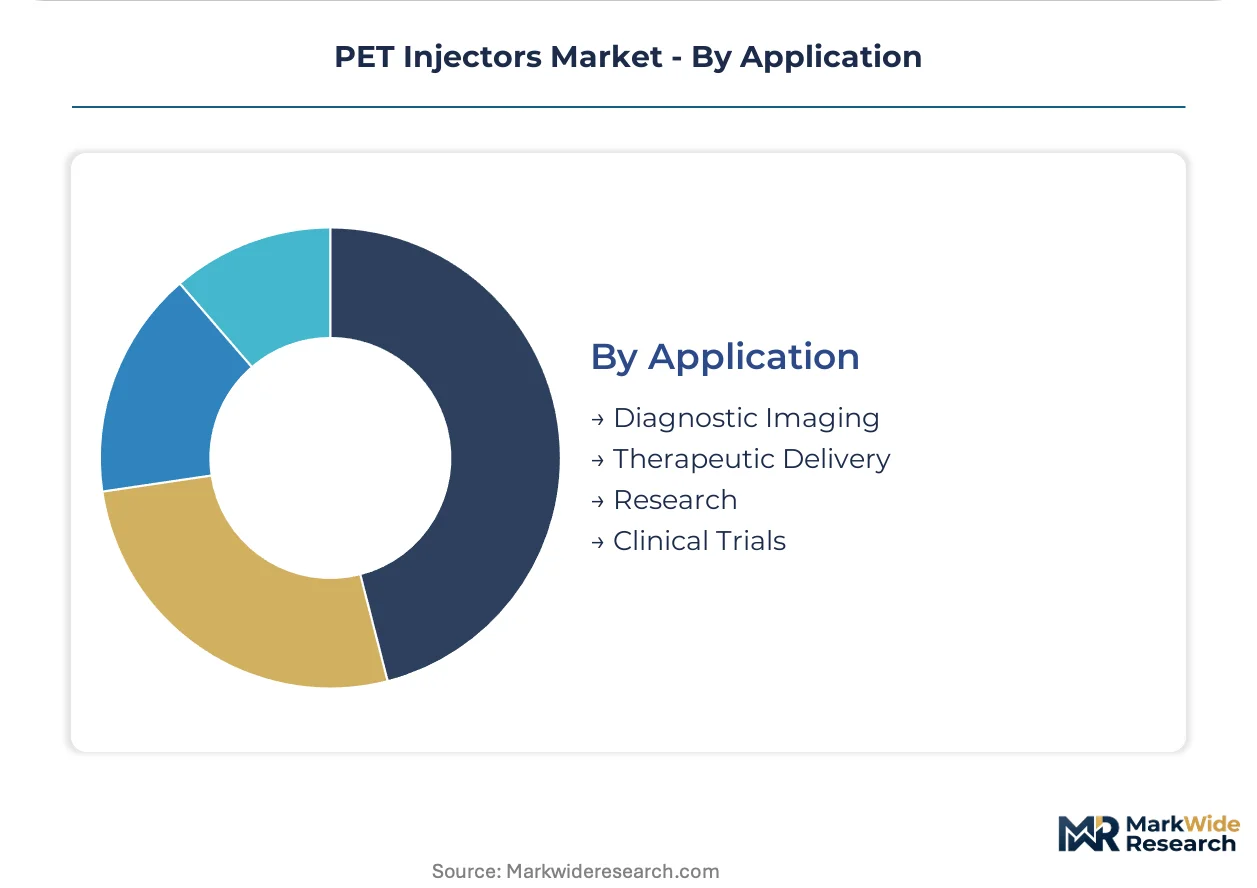
- Diagnostic Imaging:FDG-PET and PSMA-targeted tracers for oncology staging require high-throughput dispensing with integrated PET-CT workflow synchronization. This application consumes the majority of injector capacity at MD Anderson Cancer Center and comparable institutions.
- Therapeutic Delivery:Theranostic protocols combining diagnostic imaging with subsequent radioligand therapy demand precision dosing across wider activity ranges. Sites in Switzerland are pioneering therapeutic injector configurations for lutetium-177 based treatments.
- Research:Novel tracer development involves iterative dosing studies with non-standard radionuclides.
- Clinical Trials:Multi-site studies require harmonized dosing across investigator networks with central monitoring.
Diagnostic Imaging anchors current procurement. Therapeutic Delivery represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of cyclotron-produced tracers concentrates in Germany, China, and the United States, while consumption spreads across hospital radiopharmacy networks in these same markets. The geographic alignment of manufacturing and dispensing infrastructure shapes procurement patterns for precision injector systems.
United States
Academic medical centers at MD Anderson Cancer Center and Mayo Clinic campuses are expanding multi-dose injector fleets to support theranostic protocols. FDA 510(k) clearance pathways govern device software validation requirements. The Midwest cyclotron corridor spanning Illinois, Wisconsin, and Minnesota anchors regional radiopharmacy distribution networks.
Germany
University hospitals in Bavaria and North Rhine-Westphalia deploy electromechanical platforms with preventive maintenance contracts tied to cyclotron proximity. EMA radiopharmaceutical guidelines and MDR conformity assessments extend post-market surveillance obligations. The Dresden-Rostock tracer production cluster supplies dispensing infrastructure across Central European markets.
China
Integrated delivery networks in Beijing and Shanghai consolidate PET injector procurement under centralized radiopharmacy governance. NMPA device registration requirements align with cyclotron network expansion targets in the national nuclear medicine infrastructure plan. The Yangtze River Delta region hosts the fastest-growing installed base of automated dispensing systems.
Switzerland
Theranostic protocols combining diagnostic imaging with lutetium-177 radioligand therapy drive demand for precision dosing across wider activity ranges. Swissmedic regulates radiopharmaceutical compounding quality standards that shape injector specification requirements. The Basel-Zurich corridor leads European adoption of therapeutic delivery configurations.
Japan
PMDA approval timelines for software-validated injector platforms influence replacement cycles at university hospitals in Tokyo and Osaka. METI industrial policy supports domestic cyclotron manufacturing capacity expansion. The Kansai region's preclinical research facilities drive demand for ultra-low-volume precision systems.
PET Injectors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the PET injector market, creating a tiered structure where scale advantages meet customization capabilities. The installed base concentrates among three multinational healthcare technology groups with integrated imaging workflows. Strategic archetypes include full-modality integrators, radiopharmacy-focused specialists, and component subsystem suppliers. Competitive moves center on service contract geographic density and regulatory pre-certification speed.
Within the full-modality integrator tier, GE HealthCare and Siemens Healthineers exemplify archetypes leveraging PET-CT workflow integration to sustain hospital loyalty. MEDRAD, as a Bayer subsidiary, occupies a position representing radiopharmacy-focused specialists emphasizing closed-loop safety systems. These three anchors demonstrate how corporate structure shapes competitive positioning—conglomerate-backed units versus pharmaceutical-captive operations versus independent specialists.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| MEDRAD (Bayer) |
| Comecer |
| DoseTech Systems |
| Philips Healthcare |
| Canon Medical Systems |
| Eckert & Ziegler |
| IRE EluGa |
| Others |
Value Network & Pricing Analysis
Qualified nuclear medicine technologist concentration in Germany's university hospital corridors and the US Midwest cyclotron belt feeds labor-cost differentials into pricing-tier spreads across electromechanical and automated platform categories.
Pricing Analysis
Margin tightening in disposable syringe formats reflects single-use consumable inflation outpacing outpatient clinic reimbursement rates. Three-tier pricing structure across premium automated systems, standard electromechanical platforms, and economy manual configurations governs procurement. Price differentiation rests on FDA 510(k) clearance tier and integrated dose-calibration software depth. Hospital radiopharmacy departments demonstrate highest price sensitivity where capital committees enforce fleet standardization mandates.
Supply Chain Analysis
China's NMPA domestic-content mandates for medical device registration are reshaping sourcing patterns for gamma detector subassemblies and pneumatic valve components. Manufacturing concentrates in Germany, the United States, and China where cyclotron co-location drives regional injector assembly. Component sourcing draws from Swiss precision sensor suppliers and Japanese stepper motor specialists. Single-source vulnerability sits with high-enriched uranium conversion facilities in Europe and South Africa affecting generator-dependent sites. Distribution runs through hospital GPO contracts and direct academic medical center procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET injector market reads as a consolidation play where MDR conformity burdens and qualified technologist shortages force weaker regulatory affairs teams toward exit.
For Market Incumbents: To counter mid-cap specialists ceding share under Europe's extended CE-marking timelines, deepen backward integration into gamma detector manufacturing and anchor service contract density within 200 kilometers of cyclotron sites. Pre-certify quality management systems against EMA periodic safety update obligations to compress competitor market access windows. For New Entrants and Emerging Players: Enter via AI-enabled dose prediction software modules that attach to existing electromechanical installed bases rather than competing head-to-head on hardware. Target community hospital radiopharmacies in the US Southeast where staffing ratios limit technologist availability and automated verification commands premium positioning. Lead with SaaS-tiered pricing to bypass capital committee approval cycles. For Investors and Strategic Acquirers: The window for entry favors radiopharmacy-focused specialists with closed-loop safety IP and pre-certified MDR technical documentation. Long-term viability hinges on therapeutic delivery configuration readiness as lutetium-177 protocols expand. Monitor FDA guidance publication velocity on radiopharmaceutical compounding as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Pre-Certification Investment | Compresses CE-marking timelines against competitors lacking dedicated regulatory affairs infrastructure. |
| Closed-Loop Vial Transfer System Development | Reduces technologist radiation exposure to meet ALARA compliance and staff retention mandates. |
| AI-Enabled Dose Prediction Integration | Opens premium software subscription tiers through patient-specific pharmacokinetic modeling capabilities. |
| Service Footprint Geographic Concentration | Locks in preventive maintenance contract profitability near cyclotron corridor clusters. |
| Therapeutic Delivery Configuration Expansion | Captures lutetium-177 radioligand therapy growth across Swiss and German theranostic pioneers. |
Research Methodology
FDA 510(k) device clearance databases, EMA radiopharmaceutical guideline publications, and hospital GPO contract repositories formed the secondary backbone. Primary interviews with nuclear medicine department heads, hospital biomedical engineers, radiopharmacy managers, and cyclotron facility operators combined with secondary validation. Bottom-up installed base enumeration and top-down healthcare capital expenditure triangulation anchored market sizing.
Historical trendline analysis across multi-dose and disposable product categories established baseline penetration patterns. Segmentation modeling spanned product configuration, end-user organizational structure, actuation technology, and clinical application across the projection horizon. CAGRs derived from cyclotron network expansion trajectories and replacement cycle compression under regulatory guidance updates. Forecast inputs incorporated qualified technologist training program enrollment gaps and theranostic protocol adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MDR assessment timeline extensions or molybdenum-99 supply disruptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Vision Aids Market
Medical Devices
Global Robotic Nurse Assistant Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
LAMEA Breast Pumps Market
Medical Devices
South Africa Ultrasound Devices Market