
 Interatrial Shunt Market | 2026-2036
Interatrial Shunt Market Size, Share, and Industry Trends Forecast 2026-2036
Interatrial Shunt Market Outlook
Market Context
CE-marked interatrial shunt specifications are collapsing into a narrower premium tier as payers demand durable hemodynamic data. Corvia Medical leverages its first-mover transcatheter platform to anchor European reimbursement conversations. Edwards Lifesciences dominates tissue-engineered closure architectures with sustained R&D commitments exceeding industry norms. Abbott Laboratories navigates dual regulatory tracks through its established structural heart portfolio.
Technical Definition and Segment Structure
An interatrial shunt is an implantable orifice placed between the atria to reduce left atrial pressure, typically manufactured from nitinol wireframes with polymer membranes and sized to maintain calibrated flow rates between 5-10 mm diameters. Septal occluders occupy the largest revenue pool among device types, while balloon catheters represent the fastest-growing delivery mechanism as outpatient migration accelerates. Transcatheter methods command premium pricing over surgical alternatives, and heart failure indications now outpace congenital defect volumes in new patient screenings across specialized heart institutions.
Regulatory Framework and Outlook
FDA breakthrough device pathways and EMA conditional approval frameworks shape trial design and market access timelines for interatrial shunt developers. ISO 10993 biocompatibility standards and MDR technical documentation requirements in Europe constrain material selection and manufacturing validation cycles. Stakeholders must monitor evolving CMS national coverage determinations and parallel German G-BA benefit assessments to anticipate reimbursement parity for minimally invasive versus percutaneous delivery classifications.
Market Dynamics
The interatrial shunt market pivots on the tension between transcatheter delivery maturation and payer demands for durable hemodynamic evidence, forcing manufacturers to compress clinical timelines while expanding real-world data collection infrastructure.
Growth Catalysts
- FDA Breakthrough Device Pathway:Accelerated review timelines compress development cycles for novel nitinol-polymer platforms, enabling earlier commercial dialogue with CMS.
- German Structural Heart Programs:Specialized institutions in Munich and Heidelberg are building dedicated catheterization labs, concentrating procedural expertise and referral networks.
- Balloon Catheter Migration:Outpatient delivery mechanisms displace surgical alternatives as ambulatory surgical centers expand cardiac service lines across the United States.
Market Restraints
- Nitinol Price Volatility:Nickel-titanium alloy supply concentrates among a limited supplier base, exposing manufacturers to raw material cost swings.
- MDR Technical Documentation Burden:Europe's Medical Device Regulation imposes extended validation cycles for biocompatibility testing under ISO 10993, delaying CE mark renewals.
- Pharmacological Substitution:SGLT2 inhibitor advances in heart failure management compete for the same patient pool, pressuring device trial enrollment.
Strategic Opportunities
- Japanese Reimbursement Expansion:METI's healthcare technology assessment reforms create pathways for transcatheter devices in aging populations with preserved ejection fraction.
- India's PLI Scheme:Production-linked incentives for medical device manufacturing attract contract manufacturers seeking cost-competitive nitinol fabrication.
- AI-Enabled Patient Selection:Machine learning integration with echocardiographic screening identifies optimal shunt candidates earlier in disease progression.
Industry Challenges
- Interventional Cardiologist Training Bottlenecks:Procedural complexity requires dedicated structural heart fellowships that expand slower than device availability.
- Longitudinal Data Infrastructure:Post-market surveillance demands for hemodynamic monitoring strain existing cardiac registry architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interatrial Shunt Market |
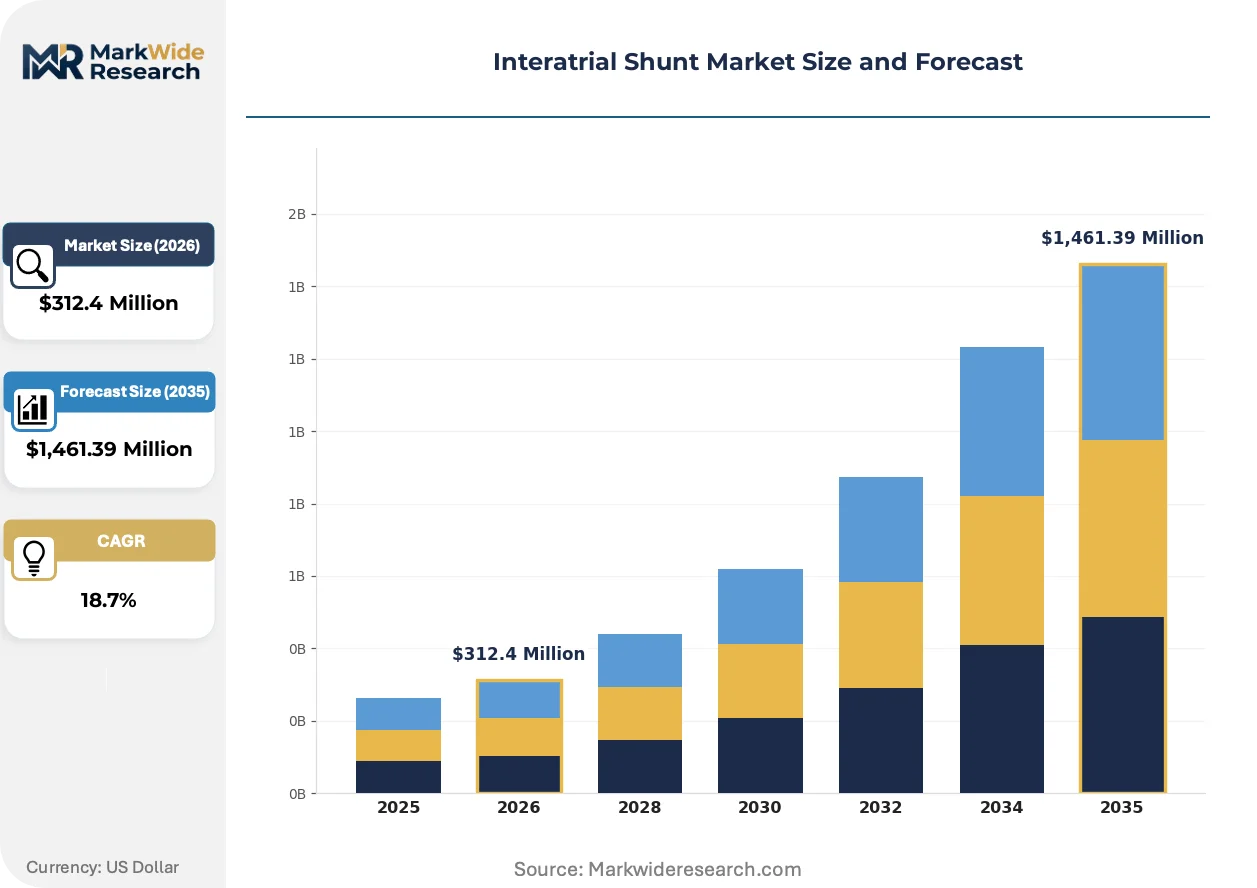
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Septal Occluders, Post-Market Products, Closure Devices, Balloon Catheters End User: Cardiology Clinics, Hospitals, Outpatient Centers, Specialized Heart Institutions Indication: Atrial Septal Defect, Patent Foramen Ovale, Congenital Heart Disease, Heart Failure Delivery Method: Transcatheter, Surgical, Minimally Invasive, Percutaneous |
| Companies Covered | Corvia Medical Inc, Occlutech Holding AG, Edwards Lifesciences Corporation, W. L. Gore & Associates Inc., Lepu Medical Technology Beijing Co. Ltd., Medtronic plc, V-Wave Ltd, Terumo Corporation, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interatrial Shunt Market Strategic Shifts
Transcatheter platform evolution is compressing the boundary between diagnostic and therapeutic intervention, with device miniaturization and real-time hemodynamic feedback integration reshaping how structural heart procedures are planned and reimbursed.
Self-expanding nitinol frames with integrated pressure sensors are miniaturizing delivery profiles below 12 French, enabling femoral access in patients previously requiring surgical cut-down. Community hospitals in the United States are adopting these platforms faster than academic centers anticipated, compressing the traditional referral hierarchy and redistributing procedural volume toward ambulatory settings.
Europe's MDR implementation is forcing manufacturers to rebuild technical documentation for legacy CE-marked devices, with notified bodies in Germany and the Netherlands experiencing 18-month backlogs. Smaller developers without established quality management systems are exiting the European market, consolidating regulatory expertise among mid-cap specialists with dedicated MDR transition teams.
Hospital purchasing committees now bundle device procurement with procedural training and outcomes guarantees, displacing traditional fee-for-service arrangements. This shift is most visible in United States integrated delivery networks, where cath lab directors negotiate multi-year contracts tying shunt device pricing to readmission rate thresholds and operator certification milestones.
Interatrial Shunt Market Segmentation
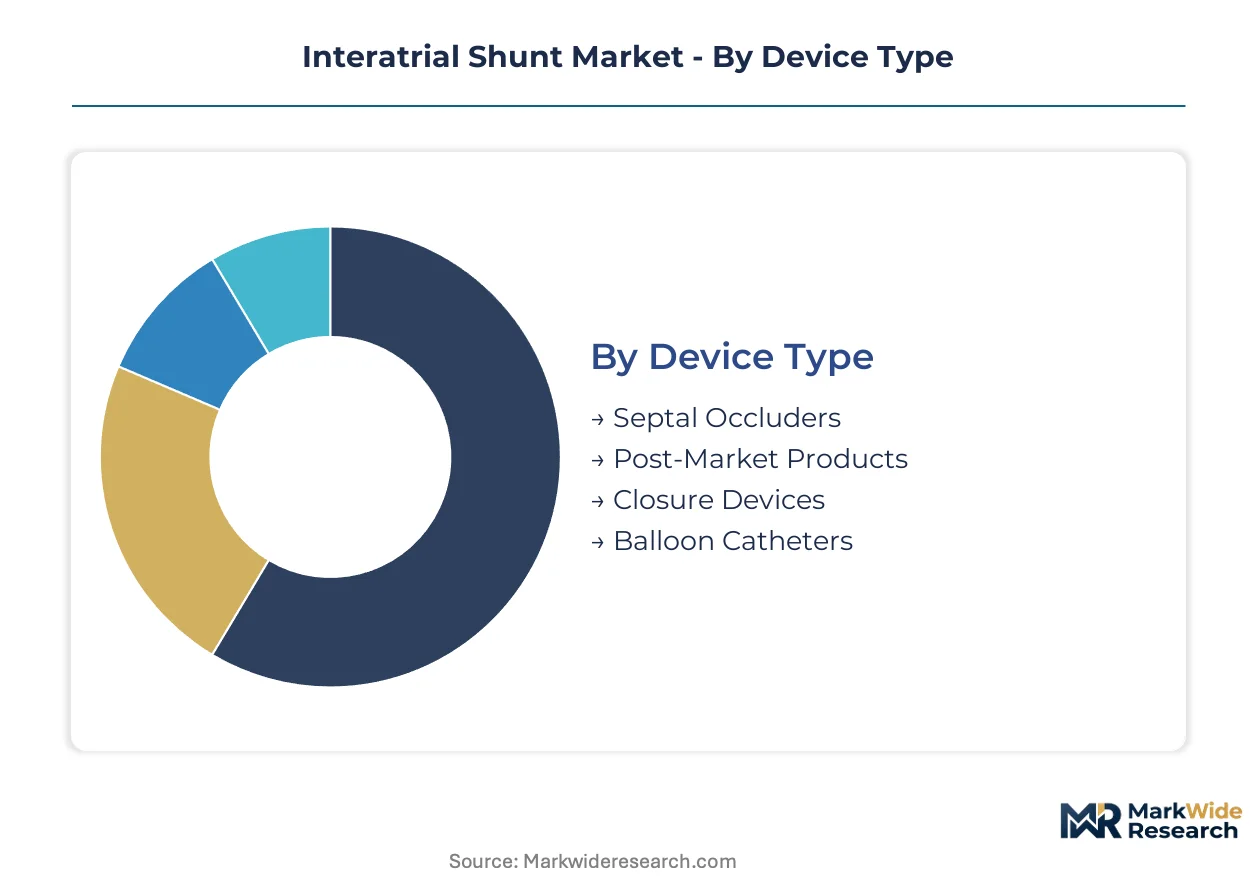
Interatrial shunt procurement patterns diverge sharply across clinical settings, with reimbursement pathways and procedural complexity dictating which device configurations capture volume. Manufacturers must align technical specifications with the specific hemodynamic monitoring capabilities and operator training levels available at each delivery site.
Device Type:
Domestic production concentrates on established nitinol platforms, while export-led growth flows through next-generation sensor-integrated designs targeting premium European and Japanese markets.
- Septal Occluders:Self-expanding nitinol wireframes with polymer membranes dominate installed bases across German and US heart centers. Demand clusters in specialized heart institutions requiring durable left-to-right shunt calibration for heart failure decompensation management.
- Balloon Catheters:Integrated delivery-and-deployment systems enable outpatient migration. US ambulatory surgical centers in Florida and Texas are building dedicated structural heart service lines around these platforms, compressing traditional hospital referral networks.
- Closure Devices:Tissue-engineered architectures with enhanced endothelialization profiles serve congenital defect repairs in pediatric settings.
- Post-Market Products:Legacy CE-marked systems undergoing MDR technical documentation renewal for European market continuity.
Septal occluders command the established base. The steepest expansion runs through balloon catheters.
End User:
Procurement authority shifts toward cath lab directors as integrated delivery networks consolidate cardiovascular service purchasing across multiple sites.
- Hospitals:Academic medical centers with structural heart fellowships anchor complex case volumes and device training certification programs.
- Specialized Heart Institutions:Munich's Deutsches Herzzentrum and Cleveland Clinic anchor referral networks. These centers negotiate outcomes-based procurement contracts tying device pricing to readmission thresholds and longitudinal hemodynamic monitoring compliance.
- Cardiology Clinics:Community-based practices in US sunbelt states are acquiring transcatheter capabilities faster than fellowship expansion permits, creating operator training bottlenecks.
- Outpatient Centers:Ambulatory settings in Germany and the Netherlands pursue MDR-compliant same-day discharge protocols for selected heart failure patients.
Specialized heart institutions anchor premium pricing. Cardiology clinics are gaining share fastest as capability diffusion accelerates.
Indication:
Patient selection algorithms are rebalancing toward hemodynamic phenotypes rather than anatomical defect classifications alone.
- Heart Failure:Elevated left atrial pressure reduction in preserved ejection fraction patients now drives screening volumes across US and German centers. FDA breakthrough pathway designations have compressed trial timelines for this indication.
- Atrial Septal Defect:Pediatric and adult congenital repair programs in Heidelberg and Boston Children's Hospital maintain steady demand for occluder platforms with biocompatible polymer specifications.
- Patent Foramen Ovale:Cryptogenic stroke prevention protocols in European centers sustain secondary prevention volumes.
- Congenital Heart Disease:Complex anatomical variants requiring customized device sizing concentrate in quaternary referral centers.
Heart failure applications are expanding most quickly. Atrial septal defect repairs retain the procedural volume base.
Delivery Method:
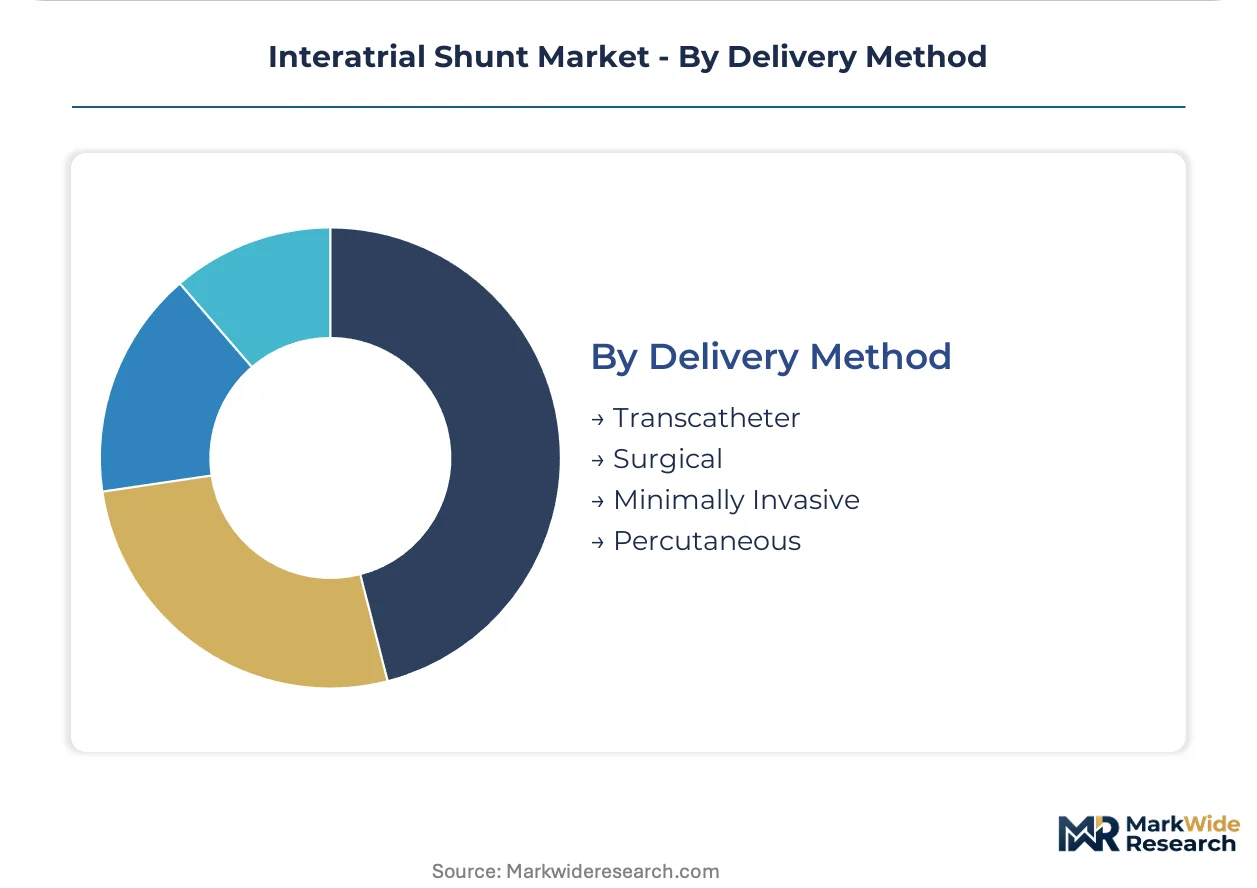
Reimbursement parity debates between minimally invasive and percutaneous classifications are reshaping CMS national coverage determination timelines.
- Transcatheter:Femoral access platforms with sub-12 French delivery profiles enable outpatient migration. German G-BA assessments are evaluating benefit claims for same-day discharge protocols.
- Minimally Invasive:Hybrid operating room configurations combine surgical backup with catheter-based deployment, appealing to community hospitals building structural heart capabilities.
- Percutaneous:Standard femoral venous access with local anesthesia dominates cost-sensitive procurement evaluations.
- Surgical:Sternotomy-based approaches retreat to complex congenital cases requiring concomitant repair or device explantation.
Transcatheter methods anchor the revenue base. Minimally invasive approaches are climbing the fastest as hybrid infrastructure spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized heart institutions in Germany, the United States, and Japan concentrate procedural expertise and anchor premium pricing for nitinol-polymer platforms. Raw material supply chains for nickel-titanium alloys concentrate among a limited supplier base, exposing manufacturers to cost volatility.
United States
FDA breakthrough device pathways accelerate clinical trial timelines for novel shunt technologies. CMS national coverage determinations shape reimbursement parity debates between minimally invasive and percutaneous delivery classifications. Cleveland Clinic anchors referral networks and negotiates outcomes-based procurement contracts tying device pricing to readmission thresholds.
Germany
Specialized heart institutions in Munich and Heidelberg build dedicated structural heart programs and catheterization labs. EMA conditional approval frameworks and MDR technical documentation requirements constrain material selection and manufacturing validation cycles. The G-BA evaluates benefit claims for same-day discharge protocols.
Japan
METI healthcare technology assessment reforms create pathways for transcatheter devices in aging populations with preserved ejection fraction. PMDA regulatory timelines influence market entry sequencing for sensor-integrated designs. Tokyo-based cardiac centers concentrate expertise in hemodynamic phenotyping for patient selection.
India
Production-linked incentives for medical device manufacturing attract contract manufacturers seeking cost-competitive nitinol fabrication. CDSCO regulatory pathways shape import substitution strategies for domestic producers. Manufacturing clusters in Maharashtra and Gujarat expand catheter assembly capacity for export markets.
China
NMPA innovation approval pathways compress development cycles for domestic device developers. MIIT industrial policies support precision manufacturing upgrades for nitinol wireframe production. Shanghai and Beijing cardiac centers anchor clinical trial networks for transcatheter platform validation.
Interatrial Shunt Market Competitive Environment
Concentration sits with diversified cardiovascular device conglomerates and specialized structural heart innovators. The competitive terrain splits between established nitinol platform holders and sensor-integrated technology entrants. Three archetypes dominate: first-mover transcatheter specialists, diversified cardiovascular conglomerates with structural heart portfolios, and contract manufacturers leveraging India's PLI scheme. Capacity expansion and M&A activity represent the dominant competitive moves as players secure nitinol supply commitments and acquire regulatory expertise.
Among diversified cardiovascular conglomerates, Edwards Lifesciences Corporation, Abbott Laboratories, and Medtronic plc exemplify scale-driven archetypes with established structural heart portfolios. These entities occupy positions spanning tissue-engineered architectures and transcatheter delivery platforms. Corvia Medical Inc represents the first-mover specialist archetype, while Occlutech Holding AG anchors European nitinol platform expertise. The competitive dynamic hinges on regulatory navigation capabilities and longitudinal hemodynamic data generation infrastructure.
| Leading Market Players |
|---|
| Corvia Medical Inc |
| Occlutech Holding AG |
| Edwards Lifesciences Corporation |
| W. L. Gore & Associates Inc. |
| Lepu Medical Technology Beijing Co. Ltd. |
| Medtronic plc |
| V-Wave Ltd |
| Terumo Corporation |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for nitinol wireframe supply lock in both raw material access and cost visibility for transcatheter platform manufacturers, insulating European producers from nickel-titanium alloy spot market volatility while constraining pricing flexibility for new entrants seeking German G-BA reimbursement.
Pricing Analysis
FDA breakthrough device designation dictates the pricing tier structure across the interatrial shunt landscape, with CE-marked MDR-compliant platforms commanding premium positioning against legacy systems undergoing technical documentation renewal. Price differentiation separates sensor-integrated designs with real-time hemodynamic feedback from standard nitinol-polymer configurations lacking embedded monitoring. Cost compression in balloon catheter delivery systems is intensifying as US ambulatory surgical centers consolidate procurement volume and negotiate outcomes-based contracts. Cardiology clinics exhibit highest price sensitivity due to capital constraints and slower reimbursement capture, while specialized heart institutions in Munich and Cleveland absorb premium tiers through bundled training and certification programs.
Supply Chain Analysis
Nitinol inventory cycles stretching eighteen months from wireframe specification to validated device release expose manufacturers to nickel price swings before finished goods reach cath lab shelves. Raw material concentration centers on Germany, the United States, and China for nickel-titanium alloy production, with polymer membrane fabrication anchored in established medical device clusters. Supply chain risk manifests through single-source vulnerability for superelastic nitinol wire drawing capacity, where qualified suppliers number fewer than five globally. Distribution runs through GPO contracts with integrated delivery networks and direct hospital system agreements for specialized heart institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procedural expertise scarcity constrains market expansion faster than device availability, with structural heart fellowship slots expanding at one-third the pace of transcatheter platform launches.
For Market Incumbents: Shield installed base revenue through exclusive supply agreements with German catheterization labs and accelerated MDR technical documentation renewal for legacy CE-marked devices. Pharmacological substitution from SGLT2 inhibitor advances threatens device trial enrollment and long-term pricing power, demanding deeper backward integration into nitinol wireframe production to defend margin position against raw material volatility. For New Entrants and Emerging Players: Anchor in Japanese METI reimbursement expansion for preserved ejection fraction populations, where transcatheter device pathways remain underdeveloped relative to US and German markets. India's PLI scheme for medical device manufacturing offers contract manufacturing partnerships as the most penetrable entry vector, bypassing direct regulatory confrontation with established nitinol platform holders. Pursue AI-enabled patient selection software as a companion diagnostic go-to-market angle to differentiate before hardware commercialization. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors mid-cap specialists with dedicated MDR transition teams and established European notified body relationships. Long-term viability across the five-to-ten year window depends on longitudinal hemodynamic data infrastructure rather than single-device approval velocity. Watch FDA CMS national coverage determination timelines as the critical inflection signal for reimbursement parity between minimally invasive and percutaneous delivery classifications.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Renewal | CE-marked device continuity depends on notified body backlog navigation in Germany and the Netherlands. |
| Hospital System Partnership | Cleveland Clinic and Munich's Deutsches Herzzentrum anchor outcomes-based procurement with readmission guarantees. |
| Reimbursement Strategy | German G-BA same-day discharge protocol evaluation shapes transcatheter premium pricing sustainability. |
| Software Companion Development | AI-enabled echocardiographic screening identifies optimal shunt candidates earlier in heart failure progression. |
| CE Marking Pathway | EMA conditional approval frameworks compress trial timelines for novel nitinol-polymer platforms. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with interventional cardiologists, cath lab directors, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EMA public assessment reports, CMS Medicare coverage databases, and hospital procurement contract archives. Bottom-up device shipment estimates from specialized heart institutions and cardiology clinics were triangulated against top-down market sizing from cardiovascular device revenue disclosures.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across device type, delivery method, indication, and end-user setting. CAGRs were derived from procedure volume growth trajectories, reimbursement pathway expansion rates, and technology substitution elasticities. Forecast inputs incorporated nitinol raw material cost indices, MDR transition timelines, and structural heart fellowship graduation rates.
Material uncertainties — regulatory approval delays, nitinol supply disruptions, and pharmacological substitution advances — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement parity achievement and operator training bottleneck resolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Global Venous Stents Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Contact Cast Systems Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Asia-Pacific Vaginal Slings Market