
 Endoscope Reprocessing Device Market | 2026-2036
Endoscope Reprocessing Device Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscope Reprocessing Device Market Analysis
The endoscope reprocessing device market is pivoting between premium automated systems and commodity manual workflows as capital budgets diverge across healthcare tiers. STERIS leverages integrated washer-disinfector platforms to dominate North American hospital procurement. Steelco anchors European demand through modular automated lines that accommodate flexible endoscope volumes. Olympus Corporation competes by extending its scope-to-reprocessing ecosystem across Japanese and Asia-Pacific installations.
Endoscope reprocessing devices clean, disinfect, and sterilize flexible and rigid endoscopes between procedures using thermal, chemical, or combined cycles validated to eliminate microbial contamination including mycobacteria and bacterial spores. Automated product types command the dominant installed base in tertiary hospitals where throughput exceeds fifty scopes daily and labor liability risks intensify. Ultrasonic technology leads growth among specialty reprocessors handling complex duodenoscope and linear echoendoscope geometries where mechanical brushing alone fails to reach elevator channel junctions. Chemical technology sustains margin pools through recurring disinfectant and detergent consumables that lock purchasers into long-term supply contracts.
FDA 510(k) clearance requirements and AAMI ST91 guidelines shape product development timelines and validation costs for manufacturers seeking US market access. EMA's Medical Device Regulation and ISO 15883 washer-disinfector standards impose parallel compliance burdens across European jurisdictions, favoring established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor how FDA's evolving duodenoscope surveillance sampling protocols redirect hospital procurement toward automated systems with validated microbiological performance documentation rather than cost-minimized manual alternatives.
Market Dynamics
Automated reprocessing systems are displacing manual workflows as tertiary hospitals confront throughput pressures exceeding fifty scopes daily and liability exposure from human error in high-level disinfection protocols.
Growth Catalysts
- FDA duodenoscope surveillance sampling:The agency's updated validation protocols redirect hospital procurement toward automated systems with documented microbiological performance, accelerating replacement cycles for legacy manual stations.
- Ambulatory surgical center expansion:Freestanding ASCs in the United States are installing compact automated reprocessors to handle elevated endoscopy volumes without dedicated sterile processing departments.
- Ultrasonic channel cleaning:Specialty reprocessors deploy ultrasonic technology to address elevator mechanism junctions in complex duodenoscope geometries where mechanical brushing fails to reach biofilm accumulation.
Market Restraints
- Peracetic acid supply concentration:Chemical disinfectant manufacturing clusters in German and Belgian industrial corridors expose purchasers to input cost volatility and single-source dependency for validated consumables.
- Capital intensity barriers:Automated washer-disinfector platforms require infrastructure investments in utility connections, ventilation, and physical footprint that exclude smaller community hospitals and rural clinics.
- ISO 15883 validation timelines:Extended certification cycles for washer-disinfector compliance delay product launches and freeze development budgets for manufacturers seeking European market access.
Strategic Opportunities
- Japanese super-aging infrastructure:METI hospital modernization incentives support replacement of obsolete manual reprocessing with automated systems in prefectural medical centers facing severe nursing shortages.
- Rental and subscription models:Equipment-as-a-service arrangements reduce upfront capital barriers for mid-tier hospitals while locking in long-term consumable supply contracts for manufacturers.
- AI-enabled cycle validation:Integration of machine vision and sensor analytics with automated reprocessors enables real-time disinfection assurance documentation that satisfies tightening Joint Commission audit requirements.
Industry Challenges
- Sterile processing technician shortages:Specialized certification requirements for high-level disinfection operators create hiring bottlenecks that constrain throughput expansion even where capital equipment is available.
- Legacy scope incompatibility:Automated reprocessor manufacturers must maintain adapter libraries for obsolete endoscope models still in clinical service, fragmenting engineering resources and complicating validation matrices.
- Cross-border regulatory divergence:Misalignment between FDA 510(k) clearance pathways and EMA Medical Device Regulation technical documentation requirements forces redundant testing expenditures for multi-territory launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscope Reprocessing Device Market |
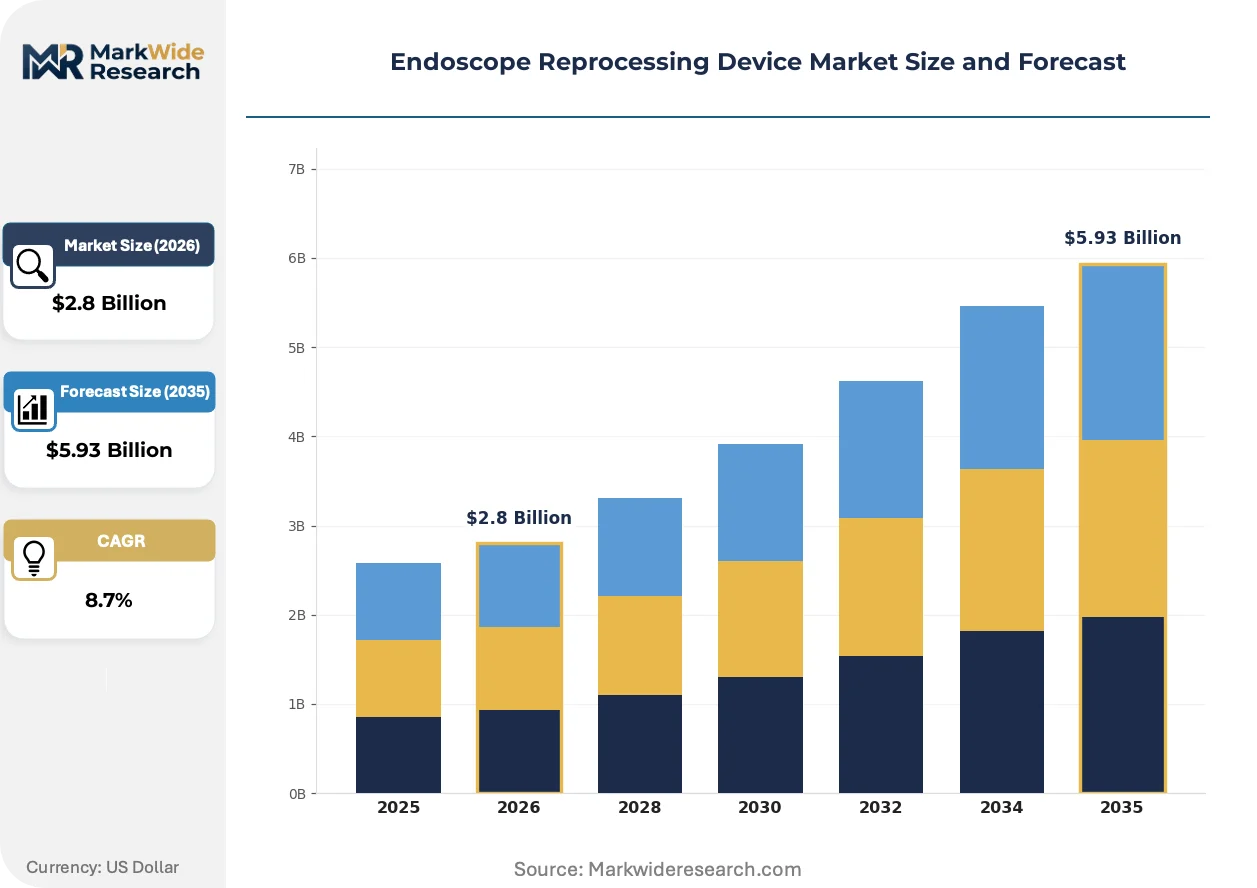
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated, Manual, Hybrid, Portable Technology: Ultrasonic, Chemical, Thermal, Mechanical End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Facilities Delivery Mode: Direct Sales, Distributors, Online, Others |
| Companies Covered | STERIS, ASP, Olympus Corporation, Getinge AB, Ecolab, Steelco, HOYA Corporation, Cantel Medical, Wassenburg Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscope Reprocessing Device Market Emerging Trajectories
Reprocessing technology is converging with digital validation systems and service-based commercial models that transform capital equipment relationships into ongoing compliance partnerships.
Single-use endoscope alternatives are consolidating competitive positioning in high-risk procedural categories. Gastroenterology suites in United States academic medical centers are piloting disposable duodenoscopes for ERCP cases involving resistant organism carriers. This substitution threat is compressing pricing power for reprocessing device manufacturers in premium segments.
EMA's Medical Device Regulation is tightening post-market surveillance obligations for reprocessing equipment placed on European markets. Manufacturers must now maintain clinical follow-up registries and periodic safety update reports that extend regulatory affairs overhead. German and French notified bodies are prioritizing automated systems with embedded electronic record-keeping for streamlined technical file reviews.
Hospital purchasing cooperatives are consolidating vendor selection authority across multi-facility networks. Integrated delivery networks in the United States are mandating standardized reprocessing platforms to simplify training, reduce spare parts inventories, and leverage volume-based consumable pricing. This concentration is squeezing regional distributors and forcing direct manufacturer contracting relationships.
Endoscope Reprocessing Device Market Segmentation
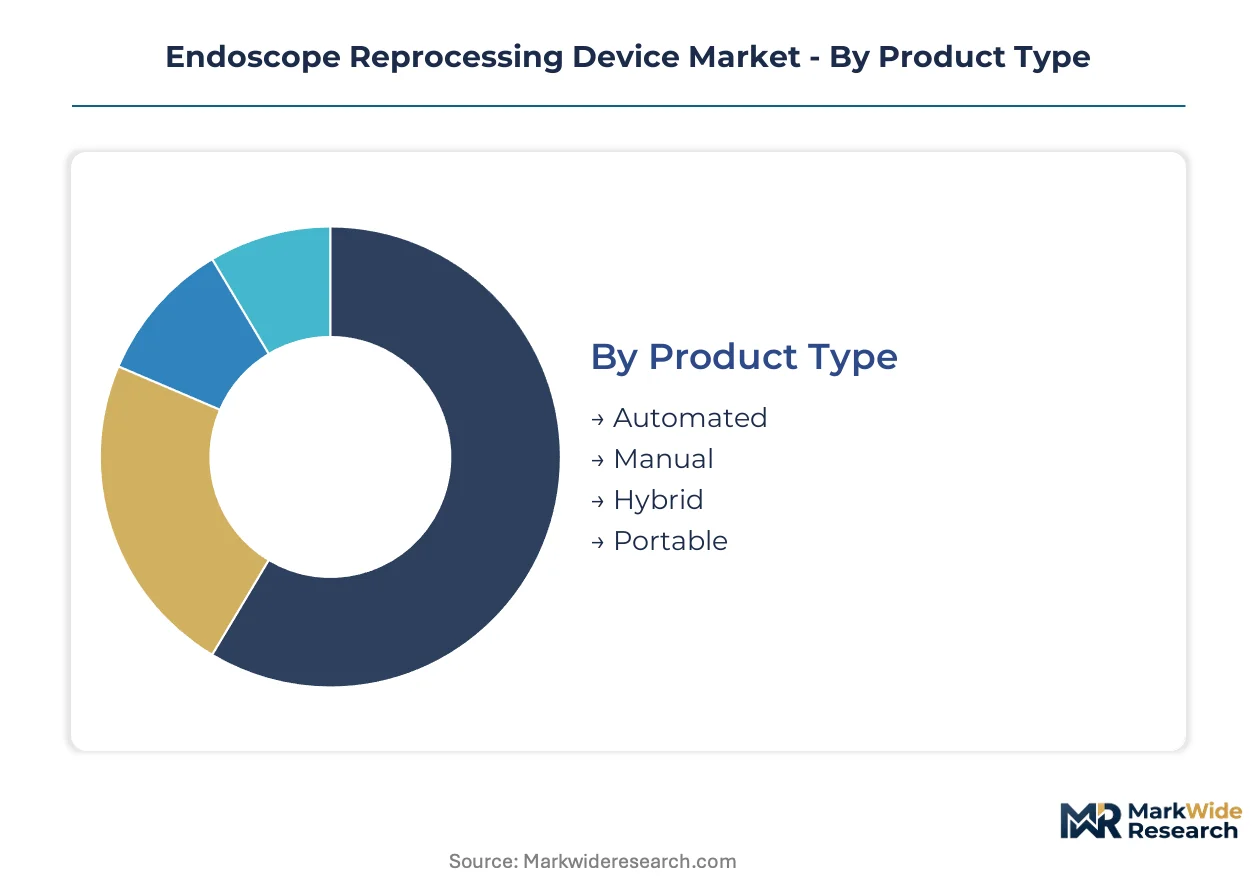
Endoscope reprocessing device segmentation reflects divergent capital availability and throughput requirements across healthcare tiers. Product type and technology choices determine compliance posture and lifecycle economics for purchasers navigating FDA and ISO validation frameworks.
Product Type:
Standardization dominates high-throughput settings while customization persists in constrained footprints.
- Automated:Washer-disinfector platforms execute validated thermal and chemical cycles with minimal operator intervention. Tertiary hospitals in the United States deploy these systems to process fifty-plus scopes daily while mitigating liability from manual disinfection errors.
- Manual:Basin-and-brush workflows require trained technicians to execute immersion, brushing, and rinsing protocols. Rural clinics and resource-constrained facilities retain these stations where capital budgets exclude automated infrastructure and case volumes remain below automation breakeven thresholds.
- Hybrid:Semi-automated units combine mechanical washing with manual chemical immersion steps.
- Portable:Compact battery-powered reprocessors serve field deployment and mobile endoscopy units.
Most installed capacity flows through Automated systems. Expansion is steepest in Hybrid configurations bridging cost and compliance gaps.
Technology:
Cost tier stratification separates premium validated technologies from commodity mechanical methods.
- Ultrasonic:High-frequency cavitation penetrates elevator channel junctions and biofilm accumulation zones that mechanical brushing cannot reach. Specialty reprocessors handling complex duodenoscope geometries in German university hospitals prioritize this technology for ERCP scope reprocessing.
- Chemical:Peracetic acid and glutaraldehyde formulations deliver high-level disinfection validated against mycobacteria and bacterial spores. Recurring consumable purchases lock Japanese medical centers into long-term supply contracts with validated disinfectant manufacturers.
- Thermal:Steam and heat-based sterilization complements chemical methods for heat-tolerant rigid endoscopes.
- Mechanical:Brushing and flushing actions provide baseline cleaning without advanced energy inputs.
Revenue concentrates in Chemical technology through recurring consumable streams. Ultrasonic applications are gaining share fastest in complex flexible scope processing.
End User:
Application intensity varies from high-volume procedural suites to intermittent research use.
- Hospitals:Central sterile processing departments manage diverse scope inventories across gastroenterology, pulmonology, and surgical specialties. German tertiary hospitals anchor European demand for automated washer-disinfector lines with integrated electronic record-keeping for EMA Medical Device Regulation compliance.
- Ambulatory Surgical Centers:Freestanding endoscopy suites in the United States install compact automated reprocessors to handle elevated procedural volumes without dedicated sterile processing departments or specialized technician staffing.
- Clinics:Lower-throughput settings balance capital constraints against regulatory minimums.
- Research Facilities:Preclinical and veterinary applications drive specialized validation requirements.
Procurement volume concentrates in Hospitals. Ambulatory Surgical Centers are climbing the fastest as outpatient endoscopy migration accelerates.
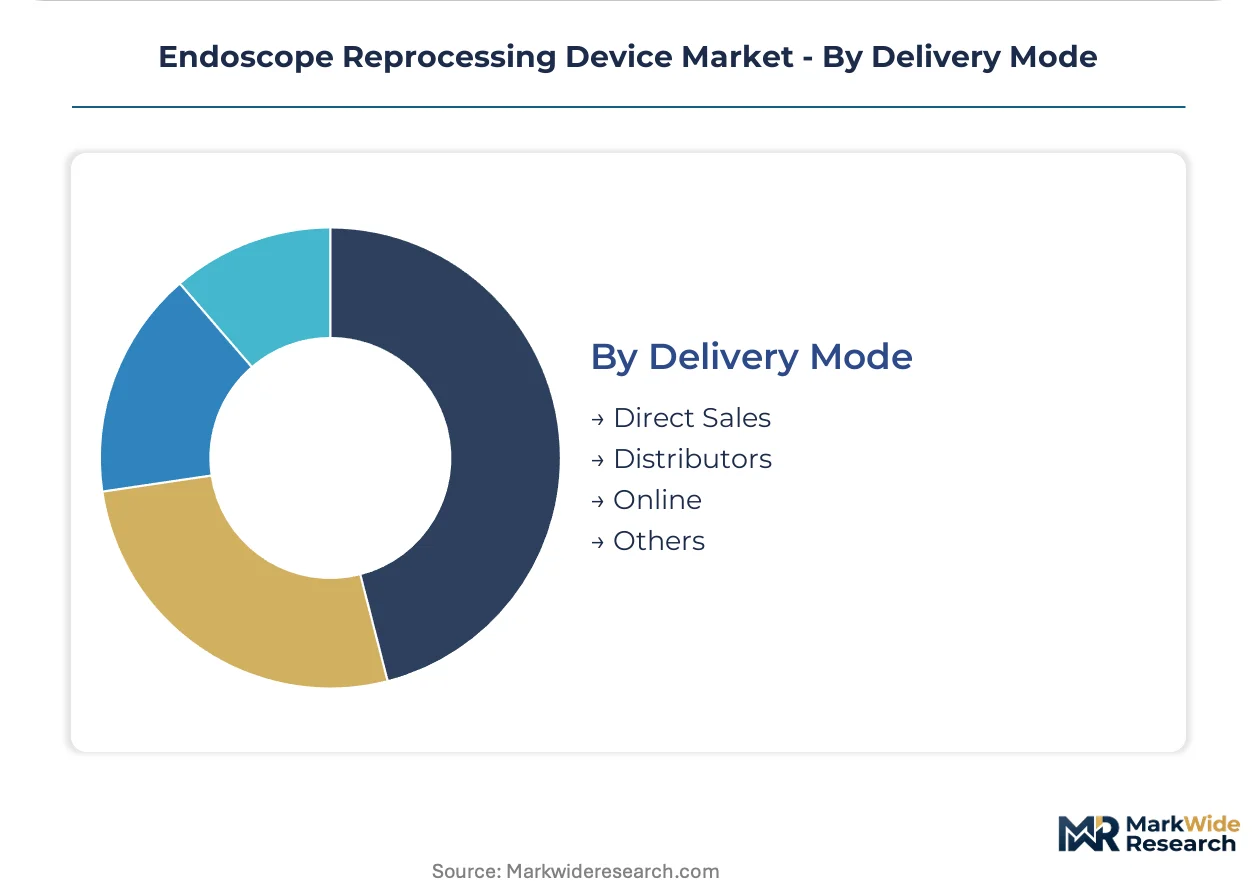
Delivery Mode:
Supply concentration shapes channel economics and manufacturer margin capture.
- Direct Sales:Manufacturer field organizations negotiate enterprise contracts with integrated delivery networks and hospital purchasing cooperatives. United States health systems leverage direct relationships to standardize platforms across multi-facility networks and secure volume-based consumable pricing.
- Distributors:Regional medical device distributors maintain inventory proximity and local service capabilities. Smaller community hospitals and rural clinics in Japan rely on prefectural distributors for installation support and maintenance access.
- Online:E-procurement platforms serve consumable replenishment and accessory purchases.
- Others:Rental and subscription models reduce upfront capital barriers for mid-tier facilities.
Transaction volume concentrates in Direct Sales for capital equipment. Distributor relationships retain importance in service-dependent segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified sterile processing technicians concentrate in German industrial corridors, Japanese metropolitan hospital clusters, and United States tertiary care networks, anchoring regional capacity for high-throughput automated reprocessing operations.
United States
FDA duodenoscope surveillance sampling protocols redirect hospital procurement toward automated systems with validated microbiological documentation. Ambulatory surgical centers in Texas and Florida install compact reprocessors to handle elevated endoscopy volumes without dedicated sterile processing departments. Boston and Cleveland academic medical centers pilot disposable duodenoscope alternatives for ERCP cases involving resistant organism carriers.
Germany
ISO 15883 washer-disinfector standards impose extended certification cycles that delay product launches for manufacturers seeking European market access. EMA Medical Device Regulation post-market surveillance obligations require clinical follow-up registries and periodic safety update reports. Stuttgart and Düsseldorf industrial corridors host peracetic acid disinfectant manufacturing clusters that expose purchasers to input cost volatility.
Japan
METI hospital modernization incentives support replacement of obsolete manual reprocessing with automated systems in prefectural medical centers facing severe nursing shortages. PMDA regulatory frameworks shape validation requirements for reprocessing equipment placed on domestic markets. Tokyo and Osaka metropolitan areas concentrate demand for scope-to-reprocessing ecosystem integration across gastroenterology suites.
United Kingdom
NHS procurement consolidation mandates standardized reprocessing platforms across multi-facility networks to simplify training and reduce spare parts inventories. MHRA guidance on high-level disinfection validation tightens compliance requirements for device manufacturers seeking market access. London and Manchester integrated delivery networks leverage volume-based consumable pricing through direct manufacturer contracting relationships.
Endoscope Reprocessing Device Market Vendor Landscape
Top-tier vendors anchor North American hospital procurement, while European modular specialists and Japanese ecosystem integrators occupy differentiated positions. The vendor base stratifies across three tiers: integrated washer-disinfector platform providers, regional automated line specialists, and consumable-locked chemical disinfectant suppliers. Strategic archetypes include capital equipment manufacturers pursuing rental and subscription models, consumable suppliers securing long-term supply contracts, and technology licensors enabling AI-enabled cycle validation. Dominant competitive moves encompass M&A for regulatory affairs infrastructure and geographic expansion through notified body relationships.
Within the integrated platform tier, STERIS and Olympus Corporation exemplify divergent geographic anchoring strategies. STERIS occupies a position representing North American direct contracting dominance through enterprise relationships with integrated delivery networks. Olympus Corporation sits within the Japanese ecosystem integration archetype, extending scope-to-reprocessing connectivity across Asia-Pacific installations. Steelco anchors the European modular specialist position, accommodating flexible endoscope volumes through configurable automated lines.
| Leading Market Players |
|---|
| STERIS |
| ASP |
| Olympus Corporation |
| Getinge AB |
| Ecolab |
| Steelco |
| HOYA Corporation |
| Cantel Medical |
| Wassenburg Medical |
| Others |
Supply Flow & Price Mechanics
Peracetic acid spot prices in Belgian and German chemical corridors cascade through three distinct pricing tiers for endoscope reprocessing systems, with automated washer-disinfector platforms commanding premium positioning while manual workflows absorb commodity-level cost compression.
Pricing Analysis
Bundled equipment-and-consumable contracts dominate tertiary hospital procurement while unbundled capital-only sales persist in resource-constrained settings. Pricing stratifies across premium automated lines with integrated electronic record-keeping, standard washer-disinfector platforms, and economy manual basin systems differentiated by validation documentation depth and after-sales service bundling. Cost compression in the manual tier is intensifying because ambulatory surgical centers are migrating to compact automated alternatives. Rural clinics and community hospitals exhibit the highest price sensitivity, whereas integrated delivery networks in the United States demonstrate lowest sensitivity due to volume-based consumable lock-in contracts.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from integrated delivery networks while regional distributors serve fragmented rural and clinic segments. Peracetic acid and glutaraldehyde disinfectant manufacturing concentrates in Germany, Belgium, and Japan, with specialty ultrasonic transducer components sourcing from South Korea and Taiwan. The supply chain draws from stainless steel processing equipment fabricated in Italy and Germany, polymer channel adapters molded in China, and control electronics assembled in Malaysia. Single-source vulnerability in validated disinfectant formulations exposes purchasers to input cost volatility when Belgian industrial corridor production encounters regulatory inspections. Distribution runs through manufacturer field organizations for capital equipment and medical device distributors for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endoscope reprocessing device market functions as a regulatory compounder where FDA duodenoscope surveillance sampling protocols are accelerating replacement cycles and locking purchasers into validated automated platforms with documented microbiological performance.
For Market Incumbents: Lock in consumable supply contracts with ten-year pricing mechanisms to defend against single-use endoscope substitution threats in ERCP procedures. Deepen backward integration into peracetic acid manufacturing to neutralize Belgian and German supply concentration risks. Prioritize AI-enabled cycle validation R&D to satisfy tightening Joint Commission audit documentation requirements and differentiate from commodity automated competitors. For New Entrants and Emerging Players: AI-enabled real-time disinfection assurance systems offer a technology-first wedge into mid-tier hospital segments underserved by incumbent field service infrastructure. White-space opportunities concentrate in Japanese prefectural medical centers facing nursing shortages and METI modernization incentives, plus United States ambulatory surgical centers seeking compact automated solutions without dedicated sterile processing departments. Pursue equipment-as-a-service subscription models to bypass capital budget barriers and establish recurring revenue footholds. For Investors and Strategic Acquirers: Asymmetric upside sits with regional automated line specialists possessing notified body relationships and modular platform architectures adaptable to EMA Medical Device Regulation compliance. Long-term viability over the projection horizon favors manufacturers with integrated scope-to-reprocessing ecosystems and captive consumable streams. Monitor FDA duodenoscope surveillance sampling protocol expansion as the inflection signal indicating accelerated replacement demand and pricing power recovery in premium automated segments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Automated Platform | Clearance unlocks United States hospital procurement and duodenoscope surveillance compliance positioning. |
| CE Marking Pathway under MDR | Notified body approval enables European market access and EMA post-market surveillance registry participation. |
| Hospital System Partnership | Integrated delivery network contracts standardize platforms across multi-facility networks and secure volume consumable pricing. |
| Software Companion Development | AI-enabled cycle validation satisfies Joint Commission audit requirements and differentiates from commodity competitors. |
| Reimbursement Strategy | CPT code alignment for automated reprocessing services accelerates ambulatory surgical center adoption and shortens payback periods. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sterile processing department managers, biomedical engineers, hospital purchasing committee members, and GPO contracts managers with secondary validation against FDA 510(k) filings, EMA Medical Device Regulation technical documentation, hospital procurement databases, and ISO 15883 certification records. Bottom-up scope installation counts and top-down equipment spending estimates were triangulated to anchor market sizing.
Segment-weighting approaches distributed total market value across product type, technology, end user, and delivery mode dimensions, with automated washer-disinfector platforms, ultrasonic cleaning systems, and ambulatory surgical center deployments receiving distinct growth coefficients across the analysis window. CAGRs were derived from installed base replacement cycles, regulatory-driven procurement accelerations, and consumable attachment rate projections. Forecast inputs incorporated FDA duodenoscope surveillance protocol adoption curves and METI hospital modernization incentive disbursement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to single-use endoscope substitution rates, peracetic acid supply disruptions, and cross-border regulatory divergence between FDA and EMA validation pathways. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gum Grafting Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Facial Implant Market
Medical Devices
Medical Manifolds Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Silastic Implant Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Global Electroceuticals Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
Hearing Loop Market