
 UAE Artificial Organs and Bionic Implants Market | 2026-2036
UAE Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Artificial Organs and Bionic Implants Market Analytics
MOHAP's updated medical device vigilance framework is broadening procurement criteria for implantable technologies across UAE federal hospitals. Medtronic plc leverages its regional distribution infrastructure to sustain cardiac rhythm device availability throughout Gulf Cooperation Council channels. Edwards Lifesciences Corporation anchors its transcatheter valve portfolio within Dubai's specialized cardiac centers, while Cochlear Ltd differentiates through direct audiologist training programs that reinforce implant fitting capabilities.
Artificial organs and bionic implants encompass electromechanical and biological substitute systems engineered to replicate or augment native physiological functions, typically incorporating biocompatible alloys, polymers, and sensor arrays fabricated through precision machining or additive manufacturing. These technologies restore motor, sensory, or organ-level performance for patients with irreversible tissue damage or congenital deficits. Heart valves and cochlear implants occupy established revenue positions due to mature reimbursement pathways and standardized surgical protocols, whereas neural interfaces and robotics command premium positioning as Abu Dhabi health authorities prioritize advanced rehabilitation infrastructure. Biomaterials development is accelerating as regional research consortia pursue localized supply chain resilience for titanium and ceramic substrates.
MOHAP, the FDA, and ISO 13485 collectively govern UAE market access through pre-market registration, quality system audits, and post-market adverse event reporting obligations that elevate compliance costs for new entrants. The Emirates' mandatory health insurance expansion under the Dubai Health Authority and Abu Dhabi Department of Health frameworks directly expands addressable patient pools for elective implant procedures. Stakeholders must monitor evolving Gulf standardization initiatives and federal procurement localization mandates that will reshape competitive qualification requirements.
Market Dynamics
MOHAP's mandatory post-market surveillance expansion is restructuring procurement pathways across UAE federal hospital networks, compelling suppliers to establish localized adverse-event reporting infrastructure as a prerequisite for contract eligibility.
Growth Catalysts
- Cardiac Device Reimbursement Expansion:Abu Dhabi Department of Health's updated essential benefits package now covers transcatheter valve replacement and pacemaker implantation for expanded age cohorts.
- Neural Interface Rehabilitation Mandates:Federal directives prioritize advanced prosthetic and brain-computer interface deployment within trauma centers serving the Emirate's construction and logistics workforce.
- Titanium Substrate Localization:Emirates Global Aluminium and Khalifa University consortia are developing domestic ceramic and alloy supply chains to reduce import dependency for implant-grade materials.
Market Restraints
- ISO 13485 Certification Burden:Small and mid-sized manufacturers face 18-24 month quality system audit timelines and recurring surveillance costs that block market entry.
- Specialized Surgical Talent Scarcity:Cochlear and neural implant fitting requires certified audiologists and neurophysiologists concentrated in Dubai and Abu Dhabi tertiary centers alone.
- Biological Substitute Competition:Tissue-engineered heart valves and stem-cell derived corneal grafts from European suppliers threaten electromechanical implant volumes in elective procedures.
Strategic Opportunities
- Ras Al Khaimah Medical Tourism Corridor:Lower-cost surgical facilities outside Dubai-Abu Dhabi core are attracting GCC patients seeking cardiac rhythm device implantation packages.
- Sensor-AI Convergence:Integration of real-time biomonitoring chips with predictive analytics platforms enables remote patient monitoring contracts with Dubai Health Authority.
- Direct-to-Hospital Distribution:Bypassing traditional Gulf distributor networks through MOHAP-registered direct sales teams captures margin and accelerates technical training deployment.
Industry Challenges
- Biocompatibility Testing Bottlenecks:Limited UAE-based ISO 10993 testing laboratories force manufacturers to ship samples to Germany or Singapore, extending product launch timelines.
- Legacy Hospital IT Integration:Federal hospital electronic health record systems require custom API development to accommodate implant device telemetry and remote monitoring data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Artificial Organs and Bionic Implants Market |
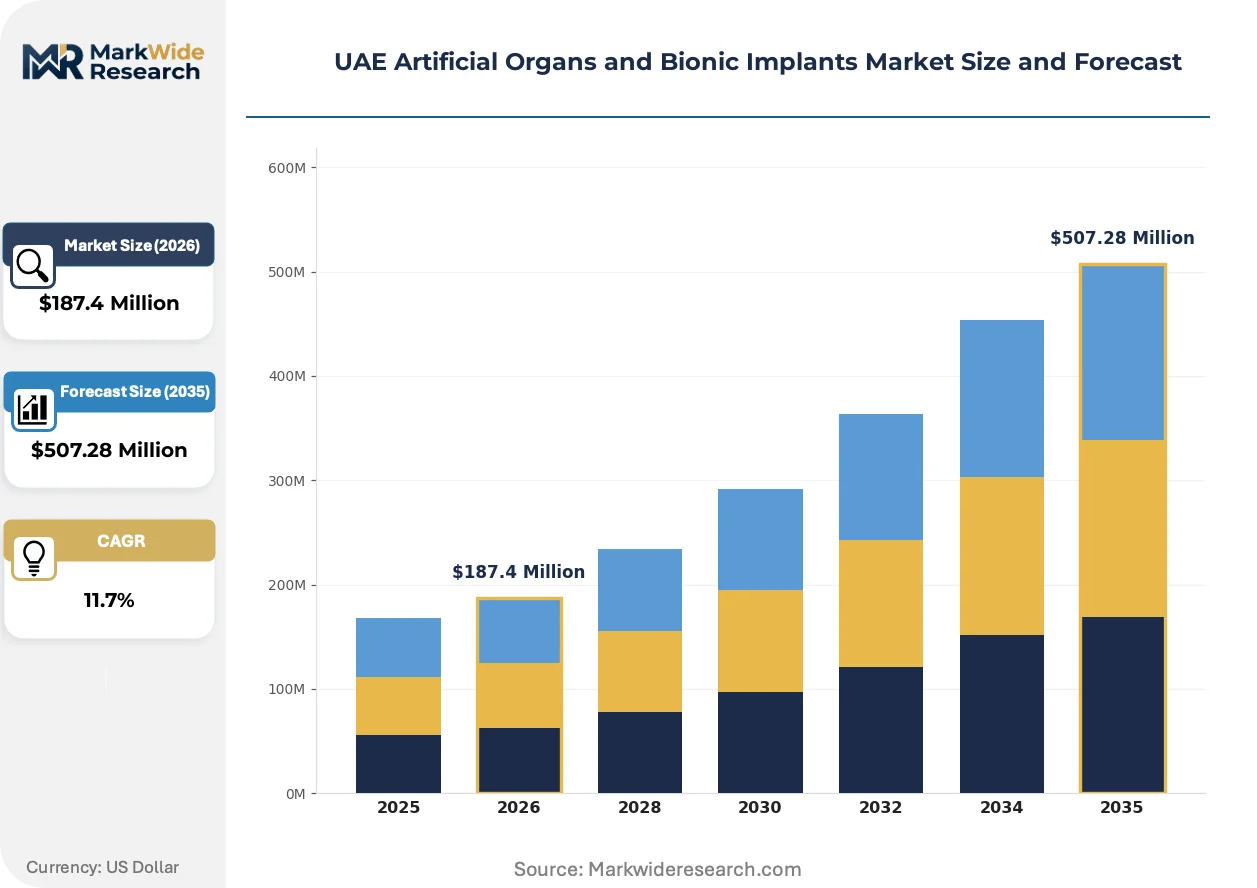
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Valves, Kidney Devices, Cochlear Implants, Artificial Limbs End User: Hospitals, Rehabilitation Centers, Surgical Clinics, Home Healthcare Technology: 3D Printing, Biomaterials, Neural Interfaces, Robotics Application: Transplantation, Surgery, Rehabilitation, Assistive Technology |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Zimmer Biomet Holdings Inc, Edwards Lifesciences Corporation, Otto Bock Holding GmbH & Co. KG, Cochlear Ltd, Ekso Bionics Holdings Inc, Johnson & Johnson, Berlin Heart GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Artificial Organs and Bionic Implants Market Evolving Landscape
Additive manufacturing of patient-specific titanium implants is compressing surgical planning cycles and enabling geometries impossible through conventional machining, with Dubai's specialized cardiac centers now requiring this capability in supplier qualification.
Point-of-care 3D printing of surgical guides and implant fixtures is decentralizing production control from centralized European and North American manufacturing hubs toward hospital-integrated fabrication cells. Cleveland Clinic Abu Dhabi and Burjeel Medical City are installing titanium and polymer printing suites for craniomaxillofacial and orthopedic applications. This geographic redistribution of manufacturing is shortening sterile supply chains and enabling same-day implant customization for trauma cases.
MOHAP's 2024 medical device vigilance framework mandates real-world performance data submission for Class III implantable devices, aligning UAE requirements with EU MDR post-market clinical follow-up obligations. Manufacturers must now maintain UAE-specific patient registries and submit annual safety reports rather than relying on foreign regulatory filings. Cardiac rhythm management and neurostimulation device suppliers face the steepest compliance curve due to longitudinal follow-up requirements.
Health authority procurement panels are consolidating vendor lists through framework agreements that bundle device supply with multi-year technical training and maintenance commitments. Dubai Health Authority's centralized cardiac device tender now specifies direct manufacturer presence for implant support, displacing traditional distributor-only arrangements. This concentration of purchasing power favors suppliers with UAE-based clinical specialist teams and dedicated biomedical engineering support infrastructure.
UAE Artificial Organs and Bionic Implants Market Segmentation
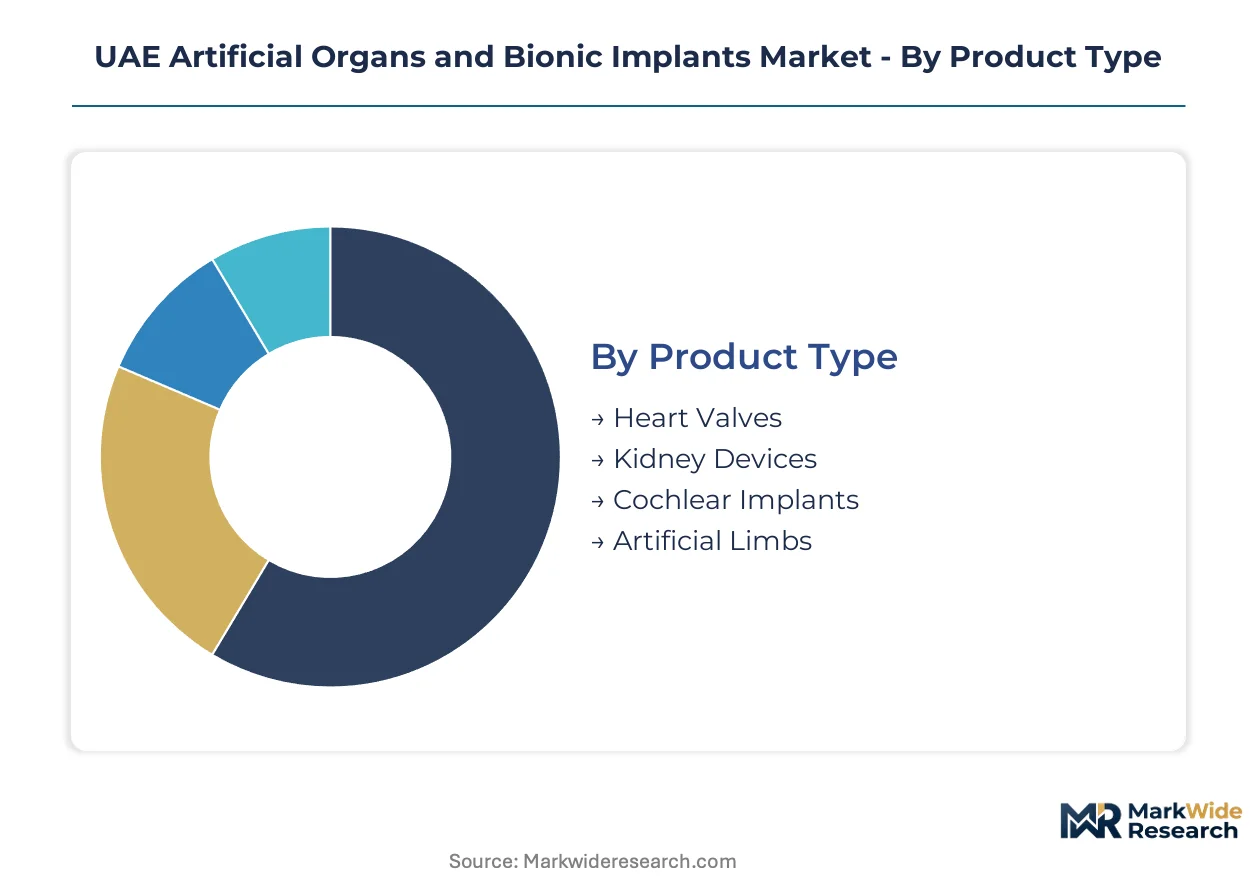
Segmentation in the UAE artificial organs and bionic implants market reveals distinct procurement patterns across federal hospital networks and specialized rehabilitation infrastructure. Understanding these divisions enables suppliers to align technical capabilities with MOHAP's evolving qualification requirements and reimbursement pathways.
Product Type:
Replacement-cycle dynamics vary sharply across implant categories, with cardiac devices requiring earlier revision than neural prosthetics due to battery depletion and tissue integration differences.
- Heart Valves:Transcatheter and surgical valve substitutes fabricated from bovine pericardium or pyrolytic carbon. Demand concentrates in Dubai's specialized cardiac centers where Abu Dhabi Department of Health reimbursement expansion covers expanded age cohorts for transcatheter procedures.
- Kidney Devices:Wearable artificial kidneys and implantable renal assist systems employing hemofiltration membranes and biocompatible tubing. Dialysis-dependent patients in federal hospital networks drive procurement volumes as MOHAP prioritizes reducing transplant waitlist pressure.
- Cochlear Implants:Electrode arrays and speech processors for sensorineural hearing restoration.
- Artificial Limbs:Myoelectric and body-powered prosthetics for upper and lower extremity amputation.
Heart valves sit at the top of the volume ranking, with kidney devices climbing the fastest as wearable dialysis technology matures.
End User:
Procurement authority fragmentation across UAE health authorities creates distinct contracting pathways that favor suppliers with localized technical support teams.
- Hospitals:Tertiary and secondary acute care facilities performing implantation surgeries. Cleveland Clinic Abu Dhabi and Burjeel Medical City anchor demand for cardiac and orthopedic devices requiring same-day customization capabilities.
- Rehabilitation Centers:Post-surgical facilities specializing in prosthetic fitting and neural adaptation training. Federal directives prioritize advanced brain-computer interface deployment within trauma centers serving construction and logistics workforce injuries.
- Surgical Clinics:Ambulatory facilities performing elective implant procedures.
- Home Healthcare:Remote monitoring and maintenance services for implantable cardiac rhythm devices.
Hospitals capture the dominant procurement share, though rehabilitation centers are expanding most quickly under federal trauma infrastructure mandates.
Technology:
Cost tier differentiation separates established manufacturing methods from emerging fabrication platforms commanding premium positioning in supplier qualification.
- 3D Printing:Additive manufacturing of patient-specific titanium implants and surgical guides. Dubai's specialized cardiac centers now require this capability in supplier qualification, compressing planning cycles for craniomaxillofacial applications.
- Biomaterials:Titanium alloys, ceramics, and biocompatible polymers for implant substrates. Emirates Global Aluminium and Khalifa University consortia are developing domestic supply chains to reduce import dependency for implant-grade materials.
- Neural Interfaces:Brain-computer and peripheral nerve electrode systems.
- Robotics:Powered exoskeletons and surgical assistance platforms for implant placement.
Biomaterials anchor current revenue concentration, while 3D printing gains share fastest through hospital-integrated fabrication cell deployment.
Application:
Application scope determines reimbursement tier and regulatory scrutiny intensity under MOHAP's Class III device vigilance framework.
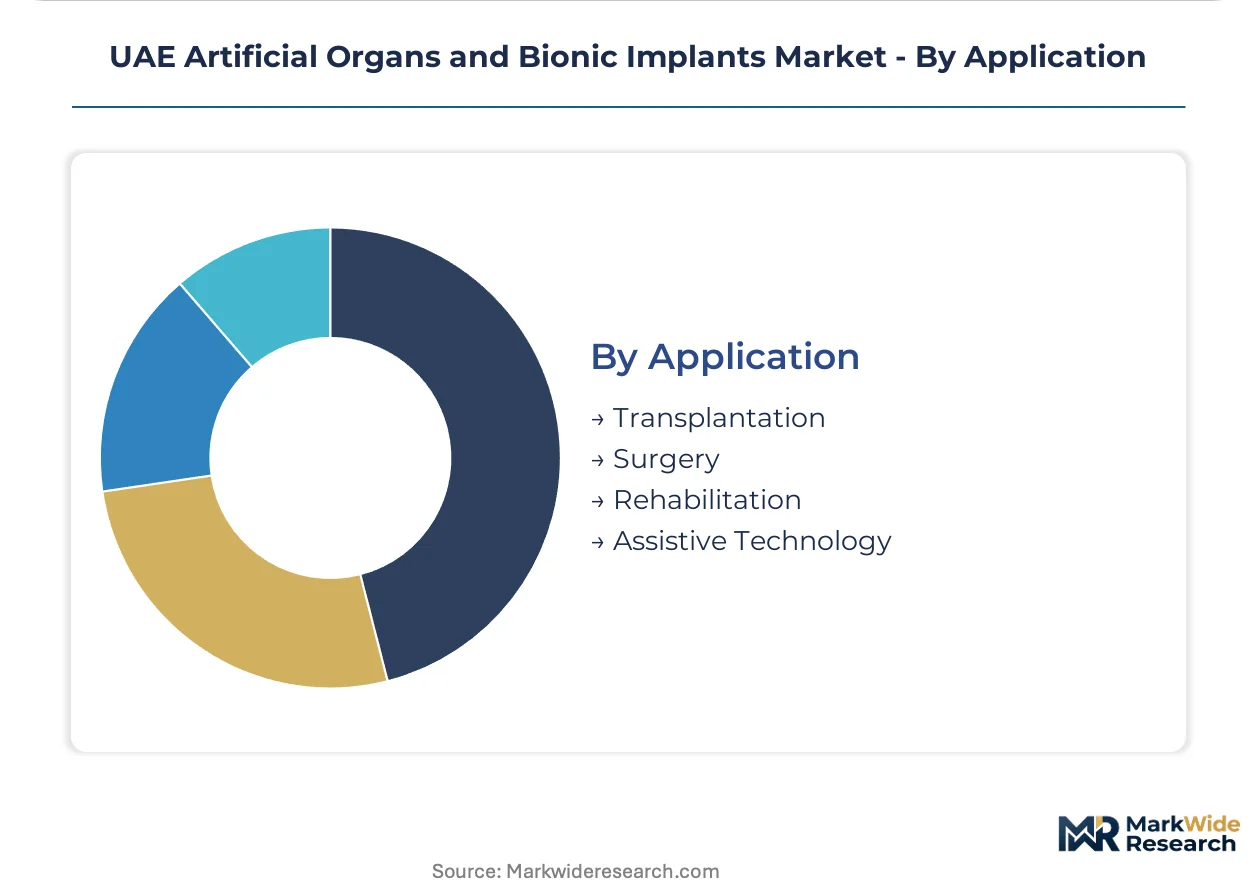
- Transplantation:Bridge-to-transplant and destination therapy devices replacing failed organs. Abu Dhabi Department of Health's essential benefits package expansion directly enlarges addressable patient pools for cardiac replacement candidates.
- Surgery:Intraoperative implantation and revision procedures. Real-world performance data submission requirements now apply, compelling manufacturers to maintain UAE-specific patient registries.
- Rehabilitation:Post-implant adaptation and functional training programs.
- Assistive Technology:External devices augmenting rather than replacing physiological function.
Surgery generates the highest procedure volume, with transplantation showing the steepest expansion trajectory as federal health insurance coverage broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac rhythm management and neural prosthetic industries first achieved commercial scale in Western Europe and the United States during the 1980s, with transcatheter valve innovations later migrating to Gulf Cooperation Council markets through Dubai's medical tourism infrastructure.
United States
FDA pre-market approval pathways for Class III implantable devices establish the regulatory benchmark that MOHAP now emulates through its 2024 vigilance framework. The Centers for Medicare & Medicaid Services reimbursement schedules for transcatheter aortic valve replacement directly influence Abu Dhabi Department of Health essential benefits package design. Boston Scientific Corporation and Medtronic plc anchor their global cardiac device portfolios within Minneapolis and Massachusetts industrial clusters before Gulf distribution.
Germany
Berlin Heart GmbH exemplifies European mechanical circulatory support specialization that UAE federal hospitals now import for bridge-to-transplant protocols. The country's national pharmaceutical regulator enforces MDR post-market clinical follow-up obligations that MOHAP's updated framework explicitly references. Baden-Württemberg's precision machining ecosystem supplies titanium substrate expertise to Emirates Global Aluminium localization consortia.
Switzerland
Swissmedic quality system audits for implantable devices set ISO 13485 certification standards that block small manufacturers from UAE market entry. Edwards Lifesciences Corporation maintains European headquarters near Geneva, leveraging proximity to EU MDR regulatory expertise for Gulf market navigation. The Lake Geneva biotech corridor channels transcatheter valve innovation toward Dubai's specialized cardiac centers.
Australia
TGA adverse event reporting infrastructure provides the template for MOHAP's mandatory UAE-specific patient registry requirements. Cochlear Ltd anchors global hearing implant manufacturing within Sydney, deploying direct audiologist training programs that reinforce fitting capabilities across Abu Dhabi tertiary centers. The country's therapeutic goods regulator coordinates with Gulf standardization initiatives on neural interface safety protocols.
Saudi Arabia
SFDA medical device registration pathways run parallel to MOHAP systems, creating dual compliance burdens for suppliers seeking Gulf-wide coverage. The Kingdom's Health Sector Transformation Program prioritizes domestic cardiac device manufacturing that competes with UAE import channels. Riyadh's King Faisal Specialist Hospital anchors demand for Berlin Heart ventricular assist devices serving the Peninsula's transplant waitlist.
UAE Artificial Organs and Bionic Implants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance capability, with ISO 13485 certification and UAE-based adverse-event reporting infrastructure separating contract-eligible suppliers from distributor-dependent entrants. The vendor base concentrates among multinational device manufacturers with established Gulf logistics networks and localized clinical specialist teams. Three archetypes dominate: integrated cardiac rhythm management suppliers, specialized neural prosthetic developers, and diversified orthopedic reconstructive platforms. Competitive moves center on direct-to-hospital distribution licensing and multi-year technical training bundling within health authority framework agreements.
Among diversified reconstructive specialists, Zimmer Biomet Holdings Inc occupies a position exemplifying orthopedic implant scale advantages. Within the neural interface tier, Ekso Bionics Holdings Inc and Otto Bock Holding GmbH & Co. KG represent contrasting archetypes of powered exoskeleton innovation against traditional prosthetic fabrication. Johnson & Johnson anchors a position spanning multiple implant categories through its broad device portfolio structure. These named entities illustrate how regulatory compliance depth and Gulf distribution control determine contract access across MOHAP-registered procurement channels.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Zimmer Biomet Holdings Inc |
| Edwards Lifesciences Corporation |
| Otto Bock Holding GmbH & Co. KG |
| Cochlear Ltd |
| Ekso Bionics Holdings Inc |
| Johnson & Johnson |
| Berlin Heart GmbH |
| Others |
Value Network & Pricing Analysis
MOHAP's 2024 medical device vigilance framework gates qualified supply access and premium-tier pricing power through mandatory UAE-specific patient registry infrastructure and adverse-event reporting capabilities that smaller manufacturers cannot sustain.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates contract-eligible suppliers with ISO 13485 certification and localized clinical teams from distributor-dependent entrants. Price differentiation rests on certification grade and after-sales service bundling, with premium tiers capturing multi-year technical training commitments. Cost compression in standard tiers intensifies because health authority procurement panels consolidate vendor lists through framework agreements. Government hospital procurement committees exhibit highest price sensitivity, while private cardiac centers in Dubai and Abu Dhabi prioritize performance metrics over unit cost.
Supply Chain Analysis
Freight costs for implant-grade titanium and ceramic substrates from Germany and Switzerland elevate landed costs for UAE federal hospitals, compressing margins on high-volume cardiac rhythm devices. Supply concentration centers on Baden-Württemberg precision machining clusters for titanium alloys, Lake Geneva biotech corridors for transcatheter valve components, and Sydney manufacturing hubs for cochlear electrode arrays. Single-source vulnerability threatens neural interface supply chains where TGA-regulated Australian facilities dominate global hearing implant production. Distribution runs through MOHAP-registered direct sales teams displacing traditional Gulf distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE market functions as a geographic-arbitrage play where European and North American manufacturers exploit regulatory compliance gaps that block emerging-market competitors, leveraging FDA and EU MDR clearance as fast-track credentials for MOHAP registration.
For Market Incumbents: Lock in framework agreement renewals by deploying UAE-based biomedical engineering support infrastructure before procurement panels finalize consolidated vendor lists. Deepen backward integration into titanium substrate supply through Emirates Global Aluminium localization partnerships to defend against domestic manufacturing mandates. Prioritize real-world performance data submission capabilities to satisfy MOHAP's longitudinal follow-up requirements for Class III devices. For New Entrants and Emerging Players: Begin with Ras Al Khaimah medical tourism corridor facilities where lower-cost surgical packages attract GCC patients seeking cardiac rhythm device implantation outside Dubai-Abu Dhabi core markets. Target rehabilitation center procurement for neural interface and prosthetic fitting services where federal trauma infrastructure mandates expand fastest. Pursue direct-to-hospital distribution licensing to bypass margin-stacking Gulf distributor networks. For Investors and Strategic Acquirers: Roll-up economics work for ISO 13485-certified mid-cap specialists because MOHAP's quality system audit timelines and recurring surveillance costs block organic market entry for undeveloped competitors. Target acquisition candidates with UAE-based adverse-event reporting infrastructure and existing health authority framework agreement relationships. Watch for MOHAP procurement localization mandates as inflection indicator for domestic manufacturing joint venture requirements.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Registration Fast-Track | FDA-cleared devices leverage pre-existing dossiers to accelerate UAE market entry timelines. |
| Hospital-Integrated 3D Printing Suite | Cleveland Clinic Abu Dhabi and Burjeel Medical City require additive manufacturing capability in supplier qualification. |
| Direct Audiologist Training Program | Cochlear Ltd's physician education model reinforces implant fitting capabilities across Abu Dhabi tertiary centers. |
| Domestic Titanium Substrate Joint Venture | Emirates Global Aluminium and Khalifa University consortia reduce import dependency for implant-grade materials. |
| Remote Patient Monitoring Contract | Dubai Health Authority contracts for sensor-AI convergence with predictive analytics platforms. |
Research Methodology
Coverage spans UAE federal hospital networks, Dubai specialized cardiac centers, and Abu Dhabi tertiary rehabilitation infrastructure, with primary inputs from each. The analysis combines structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists with secondary validation from MOHAP medical device registration databases, Dubai Health Authority procurement disclosures, and Abu Dhabi Department of Health essential benefits package documentation. Bottom-up procedure volume estimates triangulate against top-down health authority expenditure allocations.
Granularity-level modeling disaggregates the market across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs derive from segmented procedure volume projections and average selling price trajectories, with cardiac rhythm management and neural interface categories receiving discrete modeling treatment. Industry-specific forecast inputs incorporate MOHAP vigilance framework compliance cost curves and federal health insurance coverage expansion schedules.
Several conditions sit outside the modeled scope, including potential harmonization of Gulf Cooperation Council medical device regulations and unannounced shifts in Emirates Global Aluminium substrate pricing. Forecasts reflect assumptions about sustained reimbursement expansion and stable titanium alloy supply from European precision machining clusters. Stakeholders should weight assumptions against their own operating context and monitor evolving procurement localization mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Contraceptive Rings Market
Medical Devices
Smart Syringe Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
Global Positive Airway Pressure Devices Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
United States Respiratory Devices Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Breathing Circuits Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Corneal Implants Market