
 Laryngeal Masks Market | 2026-2036
Laryngeal Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Laryngeal Masks Market Analysis
Ambulatory surgical centers are repositioning their device procurement toward disposable laryngeal masks, shifting volume away from traditional hospital operating theaters. Medtronic Plc leverages its broad anesthesia portfolio to sustain institutional contracts across North American health systems. Teleflex Inc. differentiates through specialized airway management lines that target emergency department workflows. Ambu A/S dominates disposable segment supply with manufacturing scale that anchors its presence in European outpatient clinics.
A laryngeal mask airway is a supraglottic device constructed from medical-grade silicone or PVC that forms a perilaryngeal seal to facilitate controlled ventilation without tracheal intubation, primarily serving anesthesia induction and emergency airway rescue. Disposable masks lead volume due to infection control protocols, while video laryngeal masks represent the fastest-growing product type as visualization technology integrates with standard airway management. Silicone formulations command premium positioning against PVC alternatives because of superior biocompatibility and extended reusability cycles in hospital settings.
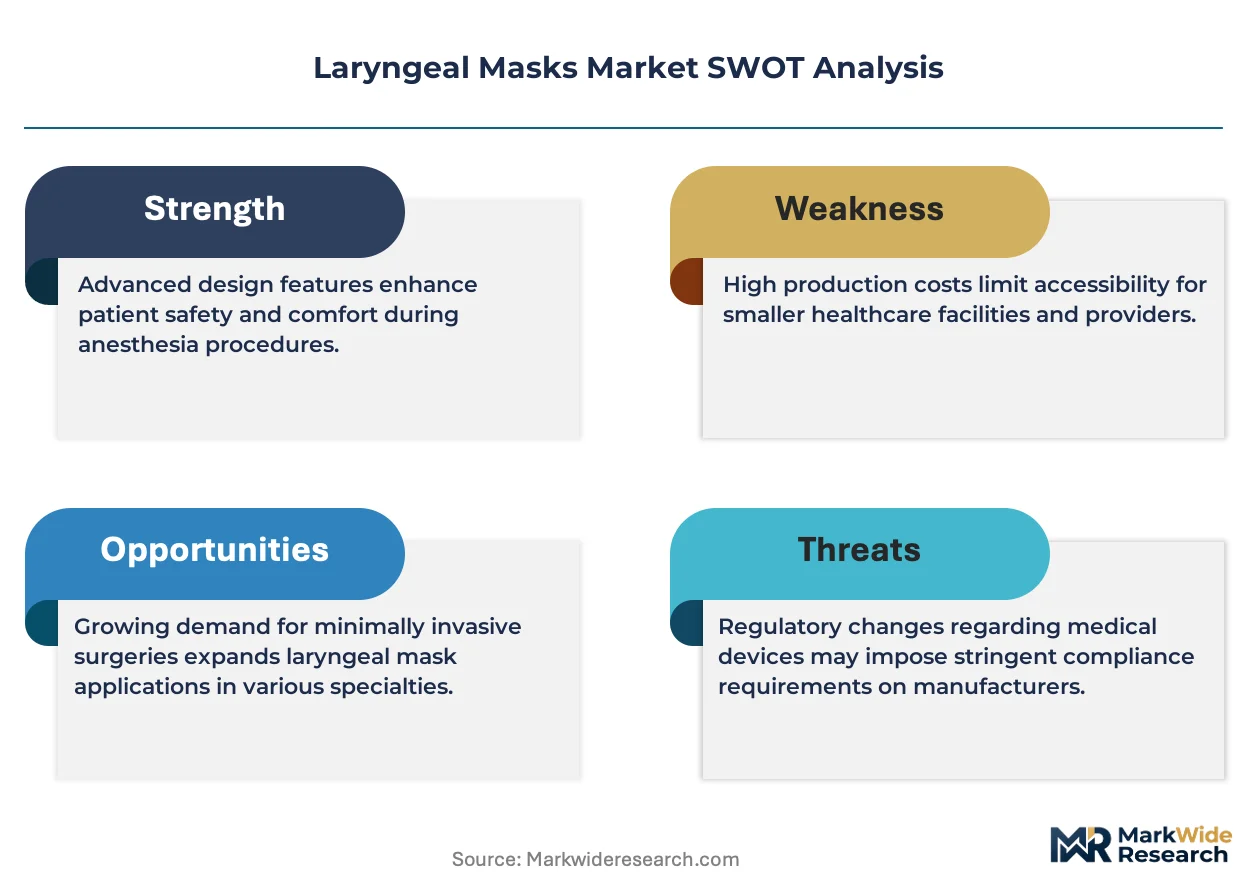
FDA 510(k) premarket notification requirements and EU MDR conformity assessment procedures shape product development timelines and material selection standards for manufacturers seeking dual-market access. ISO 10993 biocompatibility testing protocols further constrain formulation choices, particularly for phthalate-free PVC alternatives and novel foam-cushion designs. Stakeholders must monitor evolving reimbursement thresholds for outpatient airway management procedures as payers recalibrate coverage between disposable and reusable device categories.
Market Dynamics
Ambulatory surgical centers are consolidating purchasing power and mandating single-use device protocols, compressing demand for reusable silicone masks and forcing manufacturers to reconfigure production lines toward disposable output.
Growth Catalysts
- Outpatient anesthesia expansion:United States health systems are redirecting elective procedures to ambulatory settings, generating concentrated demand for disposable airway devices that eliminate reprocessing costs.
- Emergency airway protocol standardization:Germany's updated prehospital care guidelines now specify supraglottic airway devices as first-line rescue tools, expanding institutional procurement volumes across EMS networks.
- Video laryngoscopy convergence:Visualization technology is integrating with standard mask designs, creating premium product categories that command higher reimbursement rates in hospital outpatient departments.
Market Restraints
- Raw material concentration:Medical-grade silicone supply chains concentrate in Southeast Asian chemical processing hubs, exposing manufacturers to input volatility and logistics disruptions.
- Regulatory friction:EU MDR conformity assessment timelines have extended by 12-18 months for PVC-based devices, delaying market entry for reformulated phthalate-free alternatives.
- Reusable device residual demand:Academic medical centers with captive sterilization infrastructure continue specifying silicone reusable masks, fragmenting volume across incompatible procurement categories.
Strategic Opportunities
- Pediatric anesthesia underpenetration:Size-optimized disposable masks for neonatal and pediatric patients remain underserved, particularly in China's expanding tier-2 hospital network.
- Prehospital EMS channel development:Direct distribution to emergency medical services bypasses hospital procurement committees, enabling faster adoption cycles for compact disposable designs.
- Green procurement mandates:EU Green Deal circular economy requirements are creating preferential purchasing frameworks for bio-based polymer alternatives to conventional PVC formulations.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints, extending product validation timelines for novel cushion materials.
- Legacy sterilization infrastructure:Health systems with capital invested in autoclave fleets resist full conversion to disposables, requiring manufacturers to maintain dual-format product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laryngeal Masks Market |
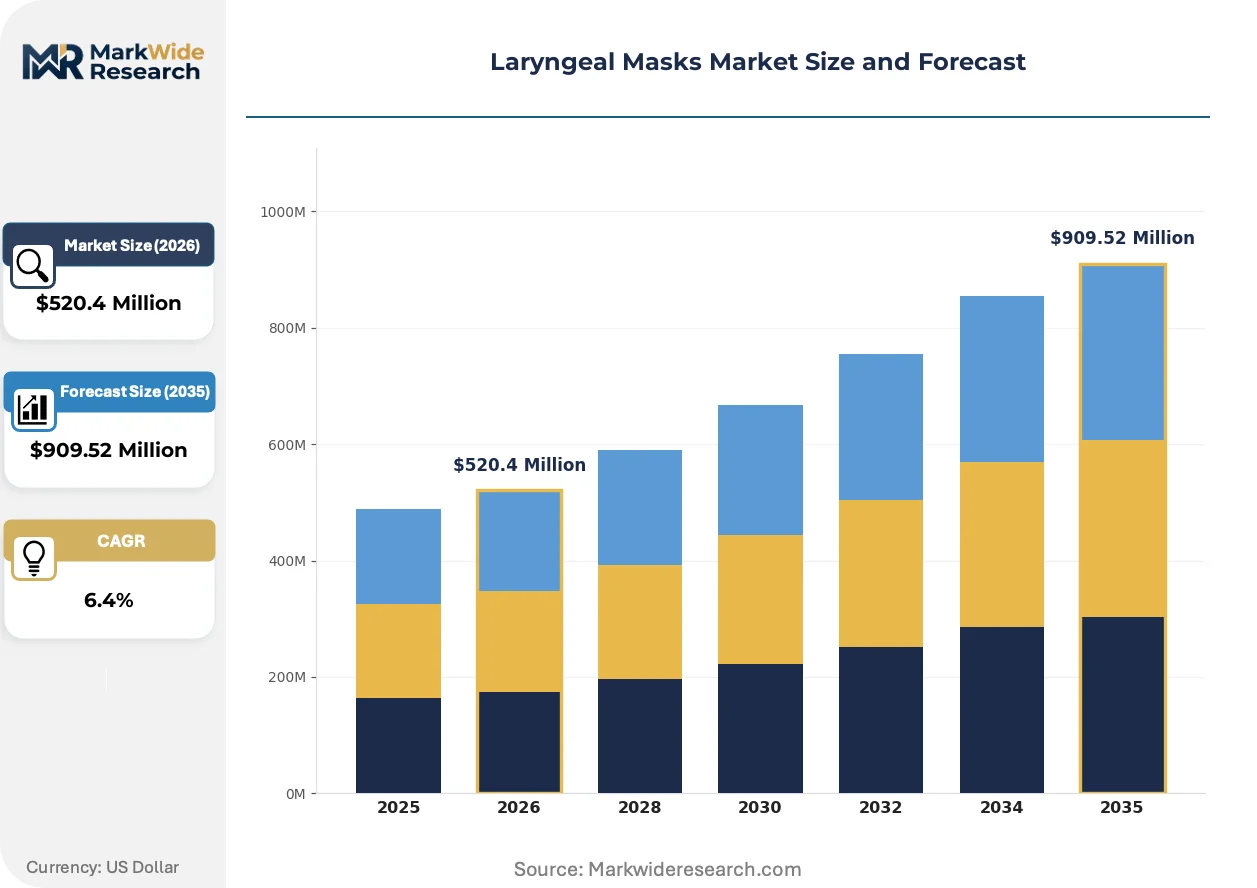
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $909.52 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Masks, Disposable Masks, Video Laryngeal Masks, Pediatric Masks End User: Hospitals, Clinics, Emergency Departments, Home Care Application: Anesthesia, Emergency Resuscitation, Airway Management, Surgery Material: Silicone, PVC, Rubber, Foam |
| Companies Covered | Medtronic Plc, Teleflex Inc., Intersurgical Ltd., Ambu A/S, Smiths Medical, Anandic Medical Systems, Thermo Fisher Scientific Inc., Narang Medical, Besmed Health Business Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laryngeal Masks Market Emerging Trajectories
Visualization technology, regulatory material standards, and procurement centralization are converging to reshape product development priorities and channel economics across the laryngeal mask supply base.
Video laryngeal masks incorporate miniature camera modules and LED illumination into the distal tip, enabling real-time glottic visualization during blind insertion attempts. Anesthesiology departments in tertiary care centers are adopting these devices for difficult airway algorithms, displacing conventional fiberoptic bronchoscopy for select indications. The technology is integrating standard airway management with continuous video documentation, creating new liability and training requirements for institutional users.
EU MDR technical documentation requirements now mandate clinical evidence for all silicone and PVC formulations in prolonged tissue contact applications, elevating post-market surveillance obligations. Manufacturers serving European markets must maintain updated risk management files and periodic safety update reports, increasing regulatory affairs headcount. Reusable mask categories face particular scrutiny due to reprocessing validation requirements, tilting development resources toward single-use designs with simpler conformity pathways.
Hospital purchasing consortia are consolidating anesthesia device contracts into multi-year agreements with sole-source or dual-source provisions, compressing vendor margins and raising qualification barriers. Group purchasing organizations now specify minimum volume commitments and performance guarantees that favor manufacturers with captive injection molding capacity. This concentration is most visible in United States integrated delivery networks, where standardized device form factors reduce clinical training costs across multi-site deployments.
Laryngeal Masks Market Segmentation
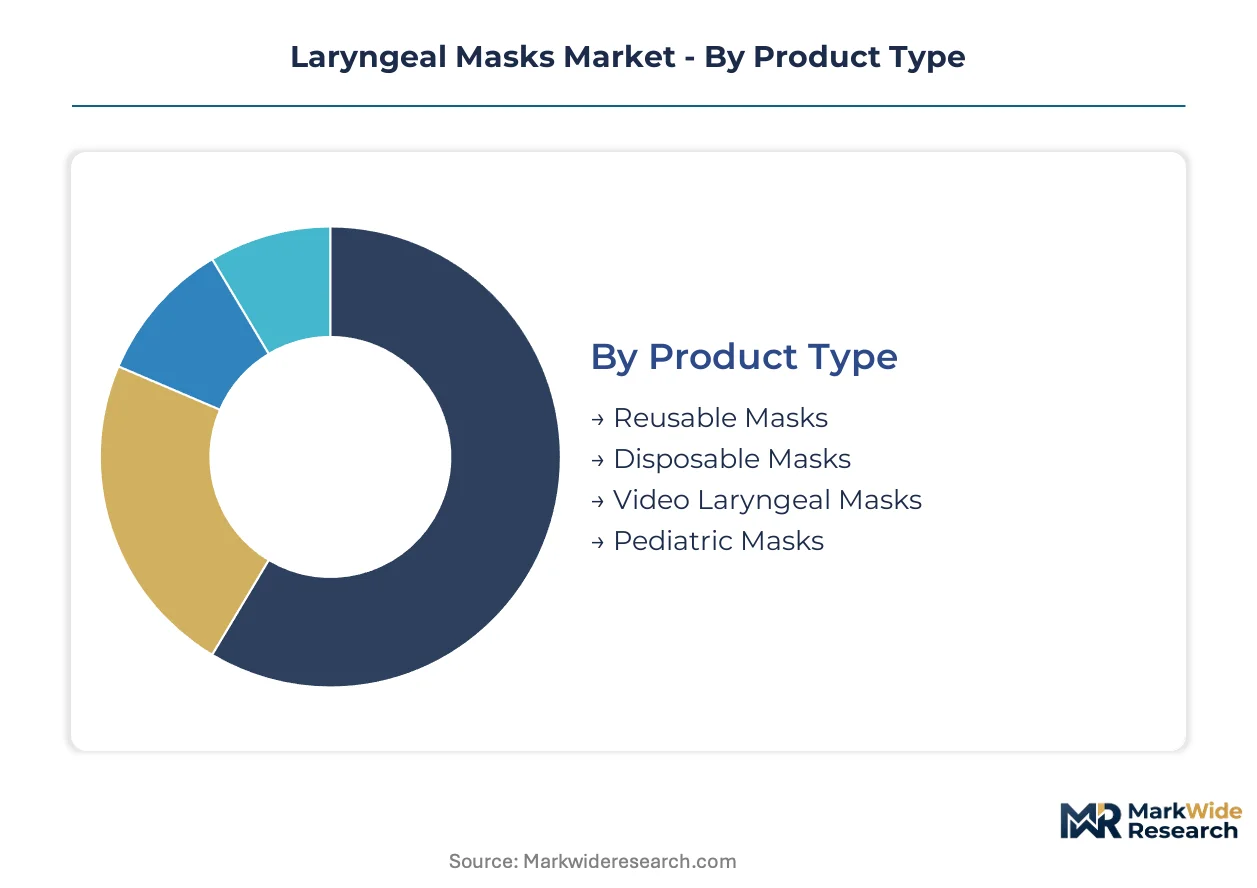
Device configuration across the laryngeal mask market fragments across clinical workflow requirements, sterilization infrastructure, and patient-specific anatomical constraints. Procurement patterns diverge sharply between institutions with captive reprocessing capacity and those mandating single-use protocols.
Product Type:
Volume leadership concentrates in disposable formats, while premium positioning clusters around visualization-enabled designs that command higher reimbursement.
- Reusable Masks:Medical-grade silicone construction supports 40-50 autoclave cycles before material degradation. Academic medical centers in Germany retain procurement preference for these devices due to existing sterilization infrastructure and per-use cost amortization.
- Disposable Masks:PVC and silicone formulations designed for single-use elimination of cross-contamination risk. Ambulatory surgical centers in the United States are redirecting volume toward this category as infection control protocols tighten and reprocessing labor costs escalate.
- Video Laryngeal Masks:Integrated camera modules with LED illumination enabling real-time glottic visualization during insertion. Tertiary care centers are adopting these for difficult airway algorithms.
- Pediatric Masks:Size-optimized designs for neonatal through adolescent anatomical ranges. China's tier-2 hospital network shows underpenetration in this category.
Mature deployment sits with reusable masks. Newer deployment is concentrated in video laryngeal masks.
End User:
Facility type determines procurement authority structure, with hospital committees favoring multi-year contracts and emergency channels requiring rapid-turn inventory.
- Hospitals:Integrated delivery networks consolidate anesthesia device purchasing into sole-source agreements with performance guarantees. These institutions maintain dual-format inventories to serve both inpatient and outpatient surgical volumes.
- Clinics:Outpatient surgical centers mandate single-use protocols to eliminate reprocessing capital expenditure. Procurement decisions concentrate with clinical administrators rather than centralized supply chains.
- Emergency Departments:Rapid-sequence intubation workflows require immediate device availability without sterilization delays. Stocking patterns prioritize disposable formats with compact packaging.
- Home Care:Palliative ventilation support and non-invasive airway management in domestic settings. Regulatory constraints limit penetration due to training requirements for supraglottic device placement.
Volume concentration rests with hospitals. Fastest expansion is occurring in emergency departments.
Application:
Clinical indication drives specification requirements, with elective procedures tolerating standard designs and rescue scenarios demanding enhanced performance margins.
- Anesthesia:Elective surgical induction and maintenance of controlled ventilation. Ambulatory centers in the United States generate concentrated demand for disposable devices that streamline turnover between cases.
- Emergency Resuscitation:Prehospital and in-hospital cardiac arrest scenarios requiring rapid airway establishment. Germany's updated EMS guidelines now specify supraglottic devices as first-line rescue tools.
- Airway Management:Difficult airway algorithms and planned extubation sequences. Video-enabled masks are displacing fiberoptic bronchoscopy for select indications.
- Surgery:Intraoperative ventilation across orthopedic, ophthalmic, and general surgical disciplines. Procedure volume shifts toward outpatient settings are reshaping device format preferences.
Established utilization centers on anesthesia. Emerging utilization is concentrating in emergency resuscitation.
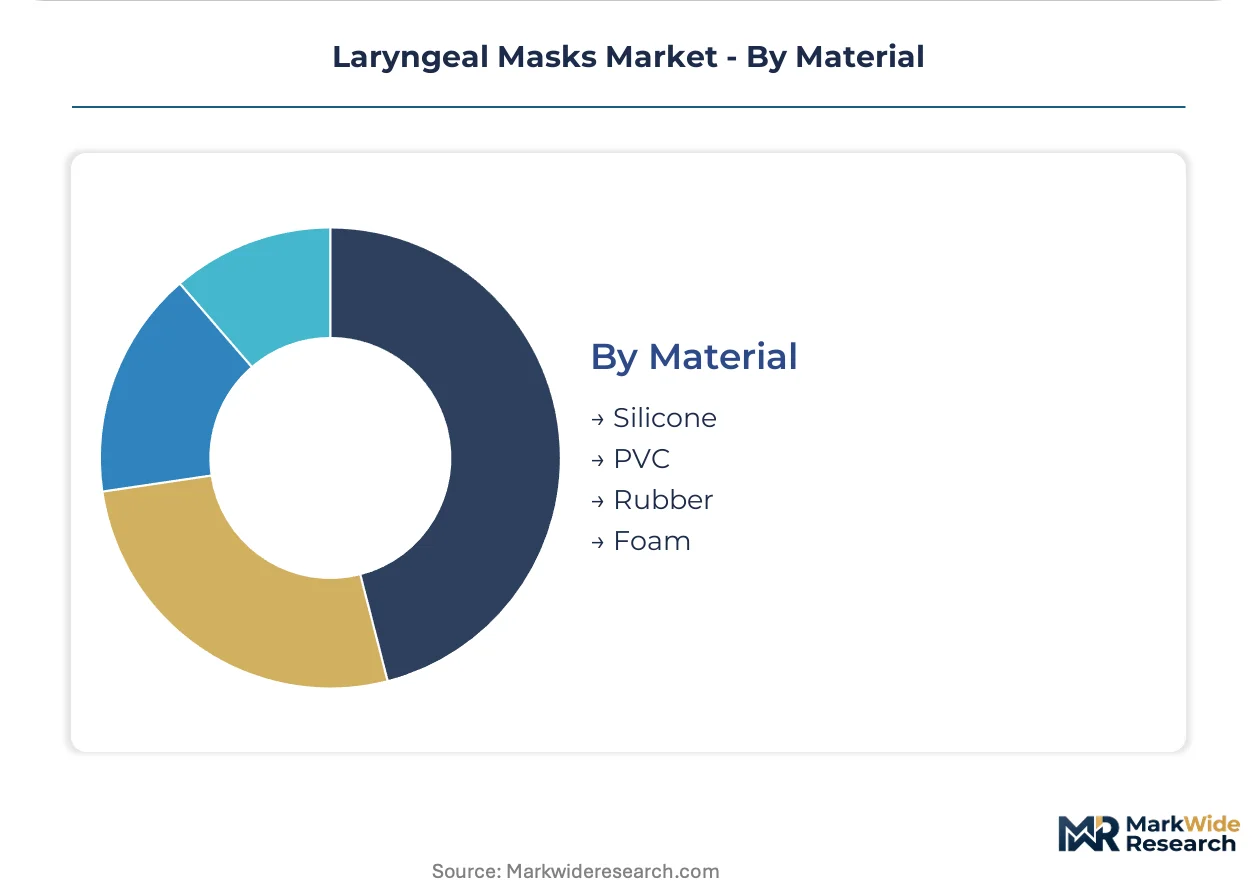
Material:
Biocompatibility certification and reprocessing durability separate premium formulations from commodity alternatives.
- Silicone:Medical-grade elastomer with superior tissue tolerance and extended autoclave resilience. FDA 510(k) pathways and EU MDR conformity assessments impose stringent extraction testing for platinum-cured formulations.
- PVC:Cost-effective polymer requiring phthalate-free reformulation for European market access. ECHA REACH restrictions on plasticizer migration are extending development timelines.
- Rubber:Latex and synthetic elastomer alternatives with limited penetration due to allergen concerns. Niche applications in resource-constrained settings persist.
- Foam:Cushion materials for enhanced perilaryngeal seal compliance. ISO 10993 cytotoxicity testing backlogs constrain novel foam introduction.
Institutional preference clusters with silicone. Reformulation investment is concentrating in PVC alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Jiangsu and Zhejiang provinces concentrate medical-grade silicone processing capacity, drawing laryngeal mask manufacturers seeking integrated supply chains and export logistics advantages.
United States
Ambulatory surgical centers in Texas and Florida are redirecting elective anesthesia volumes away from inpatient facilities, generating concentrated procurement for disposable airway devices. FDA 510(k) premarket notification pathways impose material biocompatibility documentation requirements that extend development timelines for novel cushion formulations. The Research Triangle Park corridor in North Carolina hosts sterilization validation laboratories serving reusable mask reprocessing protocols for academic medical centers.
Germany
Prehospital emergency medical services across Bavaria and North Rhine-Westphalia have adopted updated airway management guidelines specifying supraglottic devices as first-line rescue tools. EU MDR conformity assessment procedures mandate clinical evidence for silicone formulations in prolonged tissue contact applications, elevating post-market surveillance obligations. The Baden-Württemberg medical technology cluster maintains specialized injection molding capacity for precision mask cuff production.
China
Tier-2 hospital networks in Sichuan and Shandong provinces are expanding outpatient anesthesia departments, creating demand for pediatric-optimized disposable masks. NMPA registration requirements for imported medical devices impose localization pressures on foreign manufacturers seeking market access. The Yangtze River Delta manufacturing belt concentrates domestic production of phthalate-free PVC alternatives for European export compliance.
India
Government hospital procurement under the Ayushman Bharat scheme is standardizing airway device specifications across tertiary care facilities in Maharashtra and Karnataka. CDSCO medical device rules classify laryngeal masks as Class C products requiring import license verification and quality testing documentation. The Chennai medical devices park in Tamil Nadu offers production-linked incentive benefits for domestic manufacturing of single-use anesthesia consumables.
Laryngeal Masks Market Vendor Landscape
Top-tier vendors anchor institutional contracting across integrated health systems, while mid-scale specialists occupy regional outpatient channels and emergency medical services distribution. The competitive structure stratifies across three tiers: diversified medical technology conglomerates with broad anesthesia portfolios, focused airway management specialists with video-enabled product lines, and regional disposable device fabricators serving price-sensitive procurement committees. M&A activity concentrates on video laryngoscopy technology acquisitions and captive silicone molding capacity expansion.
Among diversified anesthesia portfolio holders, Medtronic Plc and Teleflex Inc. exemplify the integrated health system contracting archetype, leveraging multi-product agreements to secure sole-source positions across North American hospital networks. Ambu A/S occupies a distinct position within the disposable segment specialist tier, with Danish corporate structure and manufacturing scale anchoring European ambulatory clinic supply. These three entities represent the primary competitive anchors shaping procurement standards and reimbursement negotiation frameworks across their respective geographic strongholds.
| Leading Market Players |
|---|
| Medtronic Plc |
| Teleflex Inc. |
| Intersurgical Ltd. |
| Ambu A/S |
| Smiths Medical |
| Anandic Medical Systems |
| Thermo Fisher Scientific Inc. |
| Narang Medical |
| Besmed Health Business Corp. |
| Others |
Supply Flow & Price Mechanics
Captive silicone molding capacity in Southeast Asian chemical processing hubs anchors both supply security and premium pricing power for manufacturers serving hospital networks with reusable mask requirements. This backward integration into medical-grade elastomer production insulates tier-one vendors from input volatility while compressing margins for competitors dependent on spot-market silicone procurement.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent spot orders from contracted volume commitments, with ambulatory surgical centers paying premiums for compressed delivery schedules. Three-tier pricing structure across premium video-enabled, standard disposable, and economy PVC tiers reflects ISO 10993 certification grades and reprocessing durability. Cost compression in the economy tier is intensifying because Chinese manufacturers are expanding phthalate-free PVC capacity. Academic medical centers with captive sterilization infrastructure show lowest price sensitivity, while independent outpatient clinics negotiate aggressively on per-unit costs.
Supply Chain Analysis
Medical-grade silicone supply rests on chemical processing clusters in China, Germany, and the United States, with platinum-cured formulations requiring specialized catalysis expertise. PVC resin and plasticizer additives draw from petrochemical feedstocks concentrated in the Yangtze River Delta and Gulf Coast corridors. Single-source vulnerability persists for miniature camera modules integrated into video laryngeal masks, as CMOS sensor fabrication concentrates in Taiwanese foundries. Distribution runs through group purchasing organizations in North America and direct hospital contracts in Europe, with emergency medical services channels bypassing traditional procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laryngeal mask market is navigating a technology-transition phase as video-enabled devices displace conventional fiberoptic bronchoscopy in difficult airway algorithms. This substitution pattern favors manufacturers with integrated visualization engineering capabilities over legacy silicone molding specialists.
For Market Incumbents: Cement sole-source positions within integrated delivery networks by embedding performance guarantees into multi-year anesthesia device contracts. Acquire captive injection molding capacity in Baden-Württemberg or the Yangtze River Delta to secure silicone cuff supply against Southeast Asian logistics disruptions. Video laryngoscopy convergence threatens conventional mask margins; prioritize R&D investment in camera module integration to maintain premium tier access.
For New Entrants and Emerging Players: Emergency medical services distributors offer the most penetrable channel for compact disposable designs, bypassing hospital procurement committee delays. Target China's tier-2 hospital network for pediatric-optimized mask formats, where NMPA localization requirements have slowed multinational penetration. Direct-to-EMS go-to-market models accelerate adoption cycles compared to traditional hospital sales processes.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified anesthesia portfolio holders seeking video-enabled product lines. Long-term viability favors manufacturers with dual-format capabilities spanning disposable and reusable categories, as health system infrastructure heterogeneity persists. Watch EU MDR conformity assessment timelines as an inflection indicator; extended delays for PVC-based devices signal regulatory headwinds for commodity-tier competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements elevate post-market surveillance obligations for silicone formulations. |
| Hospital System Partnership | Sole-source agreements with integrated delivery networks in Texas and Florida secure ambulatory anesthesia volume. |
| Software Companion Development | Video laryngeal masks integrate continuous documentation capabilities for liability protection in tertiary care centers. |
| Reimbursement Strategy | Outpatient airway management procedure codes determine coverage thresholds between disposable and reusable categories. |
| Backward Integration into Silicone | Captive molding capacity in Jiangsu province insulates against medical-grade elastomer supply volatility. |
Methodological Framework
Independent corroboration across hospital purchasing committee interviews, emergency medical services procurement directors, and biomedical engineering specialists underwrites the qualitative findings. Primary fieldwork with group purchasing organization contracts managers and anesthesia department heads combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records. Bottom-up volume estimates triangulated against top-down expenditure analysis across ambulatory surgical center networks.
Comparable-period anchoring to historical outpatient anesthesia expansion and emergency airway protocol adoption patterns established the forecast baseline. Segmentation modeling spanned product configuration, end-user facility type, clinical application, and material formulation across the projection horizon. CAGRs derived from regression analysis of procedure volume shifts and device replacement rates, with specific inputs including sterilization infrastructure depreciation schedules and infection control protocol adoption curves.
Caveats apply where EU MDR conformity timeline extensions or raw material logistics disruptions could materially shift the outlook. Forecasts reflect assumptions regarding reimbursement stability and ambulatory surgery migration patterns. A small set of named triggers warrants ongoing watch: NMPA localization mandates in China, phthalate-free PVC reformulation costs, and video module supply concentration in Taiwanese semiconductor foundries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Medical Coatings Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Skin Rejuvenation Devices Market