
 Medical Oxygen Sensors Market | 2026-2036
Medical Oxygen Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Oxygen Sensors Market Insights
Hospital procurement consolidation is repositioning medical oxygen sensor vendors toward long-term service contracts and integrated monitoring suites. Honeywell International Inc. leverages its industrial sensing heritage to compete in high-accuracy critical care applications. Teledyne Analytical Instruments anchors its position through specialized optical sensing platforms for anesthesia monitoring. Hamilton Medical sustains technology leadership by embedding proprietary oxygen measurement into ventilator ecosystems.
Medical oxygen sensors are electrochemical, optical, zirconia, or laser-based transducers that measure partial pressure or concentration of oxygen in gas mixtures or blood, typically operating within clinical temperature ranges and requiring calibration stability for patient safety. Electrochemical variants dominate current hospital installations due to proven reliability and lower unit costs, while optical sensors capture expanding share in home care and remote monitoring deployments where drift tolerance and reduced maintenance cycles justify premium positioning. Zirconia-based designs concentrate in high-throughput laboratory and industrial-medical hybrid settings where rapid response times offset higher capital investment.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and validation costs for manufacturers targeting both markets. ISO 80601-2-55 standards for respiratory gas monitors establish baseline accuracy thresholds that differentiate clinical-grade from consumer-oriented sensor offerings. Stakeholders must monitor evolving home care reimbursement codes and wireless connectivity security mandates as care delivery shifts beyond traditional hospital boundaries.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously elevating performance requirements for oxygen sensing accuracy and wireless integration. This structural force favors suppliers capable of delivering integrated monitoring ecosystems over standalone component manufacturers.
Growth Catalysts
- Critical care infrastructure expansion:The U.S. Department of Health and Human Services is funding ventilator fleet modernization programs that embed multi-parameter gas monitoring, directly expanding addressable sensor demand.
- EU MDR compliance deadlines:Medical device manufacturers face mandatory recertification timelines that accelerate replacement cycles for legacy electrochemical sensors with drift-stabilized optical alternatives.
- Home care reimbursement codes:Germany's statutory health insurance framework now covers remote patient monitoring devices, creating pull-through demand for maintenance-free oxygen sensors in portable concentrators.
Market Restraints
- Precious metal input volatility:Electrochemical sensor production depends on platinum and gold electrode coatings, exposing manufacturers to London Bullion Market Association price swings that compress gross margins unpredictably.
- Optical component supply concentration:High-precision LED and photodiode sources for optical oxygen sensors concentrate in Taiwanese and South Korean semiconductor foundries, creating single-source vulnerability.
- Cross-sensitivity limitations:Electrochemical platforms exhibit interference from anesthetic gases including nitrous oxide and halogenated agents, restricting deployment in hybrid surgical environments.
Strategic Opportunities
- India's medical device PLI scheme:Production-linked incentives for domestic manufacturing of critical care equipment create localized assembly opportunities for sensor-integrated ventilator subsystems.
- Wireless connectivity convergence:Bluetooth Low Energy and NFC protocols are merging with oxygen sensing hardware, enabling smartphone-integrated home diagnostics without dedicated display units.
- Sustainability mandates:The EU Green Deal's circular economy requirements for medical electronics are accelerating demand for solid-state zirconia sensors that eliminate electrolyte replacement and hazardous waste streams.
Industry Challenges
- ISO 80601-2-55 calibration expertise:Respiratory gas monitor certification requires specialized metrology capabilities that concentrate in German and Swiss testing laboratories, creating bottlenecks for new market entrants.
- Legacy system integration friction:Hospital information systems running proprietary communication protocols demand custom middleware development for seamless sensor data ingestion, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Oxygen Sensors Market |
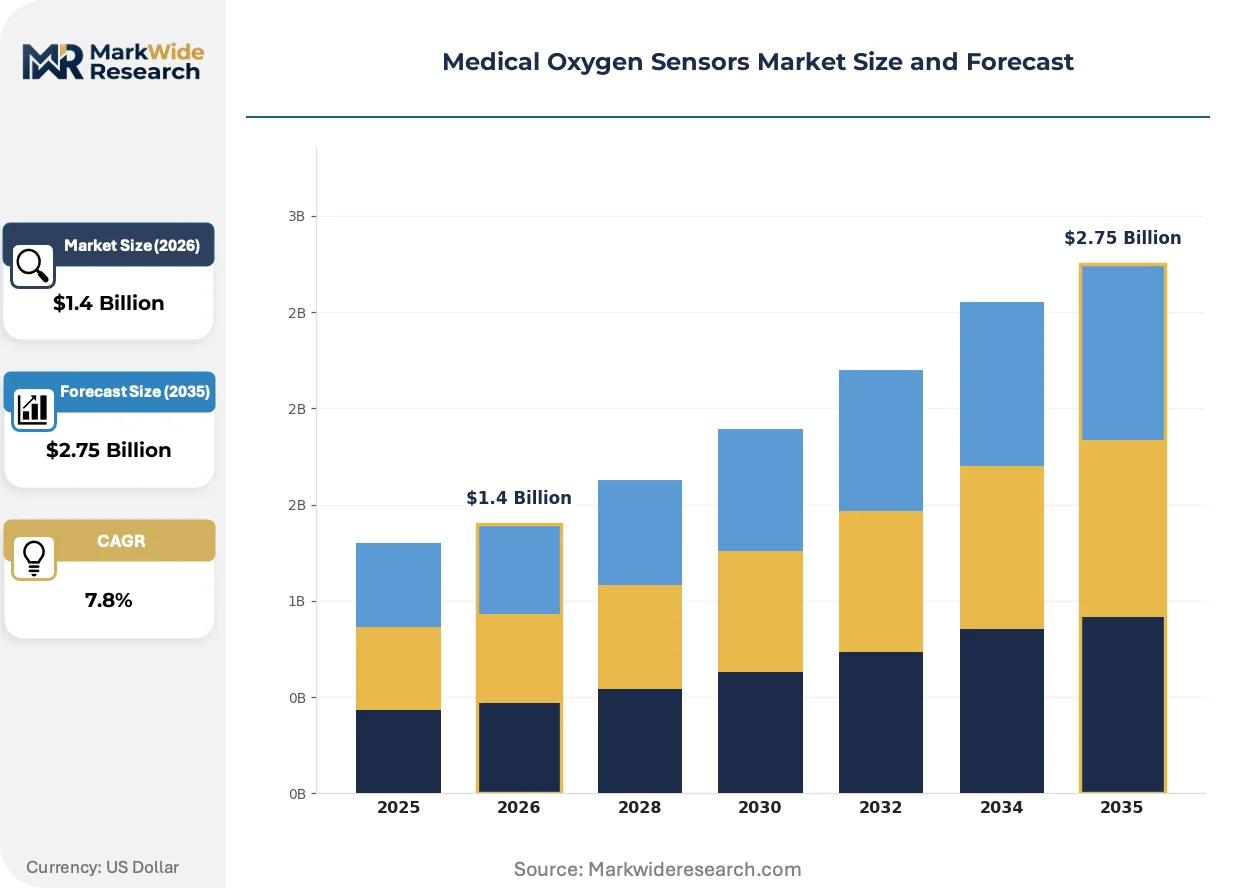
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical, Optical, Zirconia, Laser End User: Hospitals, Home Care, Emergency Services, Laboratories Technology: Wireless, Portable, Fixed, Remote Monitoring Application: Critical Care, Anesthesia Monitoring, Sleep Studies, Respiratory Management |
| Companies Covered | Honeywell International Inc., Teledyne Analytical Instruments, Hamilton Medical, SST Sensing Ltd, PreSens Precision Sensing GmbH, Nuova GmbH, Orantech USA Inc., Fujikura Global, Kranz Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Oxygen Sensors Market Trends and Innovations
Optical sensing platforms are capturing share from electrochemical predecessors through superior drift stability and reduced calibration burden. This transition is compressing development timelines and reshaping supplier qualification criteria across critical care and home monitoring segments.
Fluorescence-quenching optical oxygen sensors measure dissolved and gaseous oxygen through phase-shift detection of ruthenium complex emissions. Intensive care units in tertiary hospitals across Germany and Switzerland are adopting these platforms for continuous arterial blood gas monitoring. The technology is consolidating previously fragmented maintenance schedules into unified device management protocols.
FDA's 510(k) third-party review pilot program is streamlining clearance pathways for predicate-device modifications in respiratory gas monitors. This regulatory efficiency reduces time-to-market for sensor firmware updates and hardware iterations. Anesthesia workstation manufacturers in the United States are leveraging this pathway to accelerate optical sensor integration into existing ventilator architectures.
Hospital purchasing cooperatives are unbundling sensor procurement from original equipment manufacturer service contracts. This disintermediation enables direct sourcing from specialized component vendors and reduces lifetime equipment costs. The pattern is most visible in North American health systems consolidating ventilator fleets under standardized maintenance agreements.
Medical Oxygen Sensors Market Segmentation
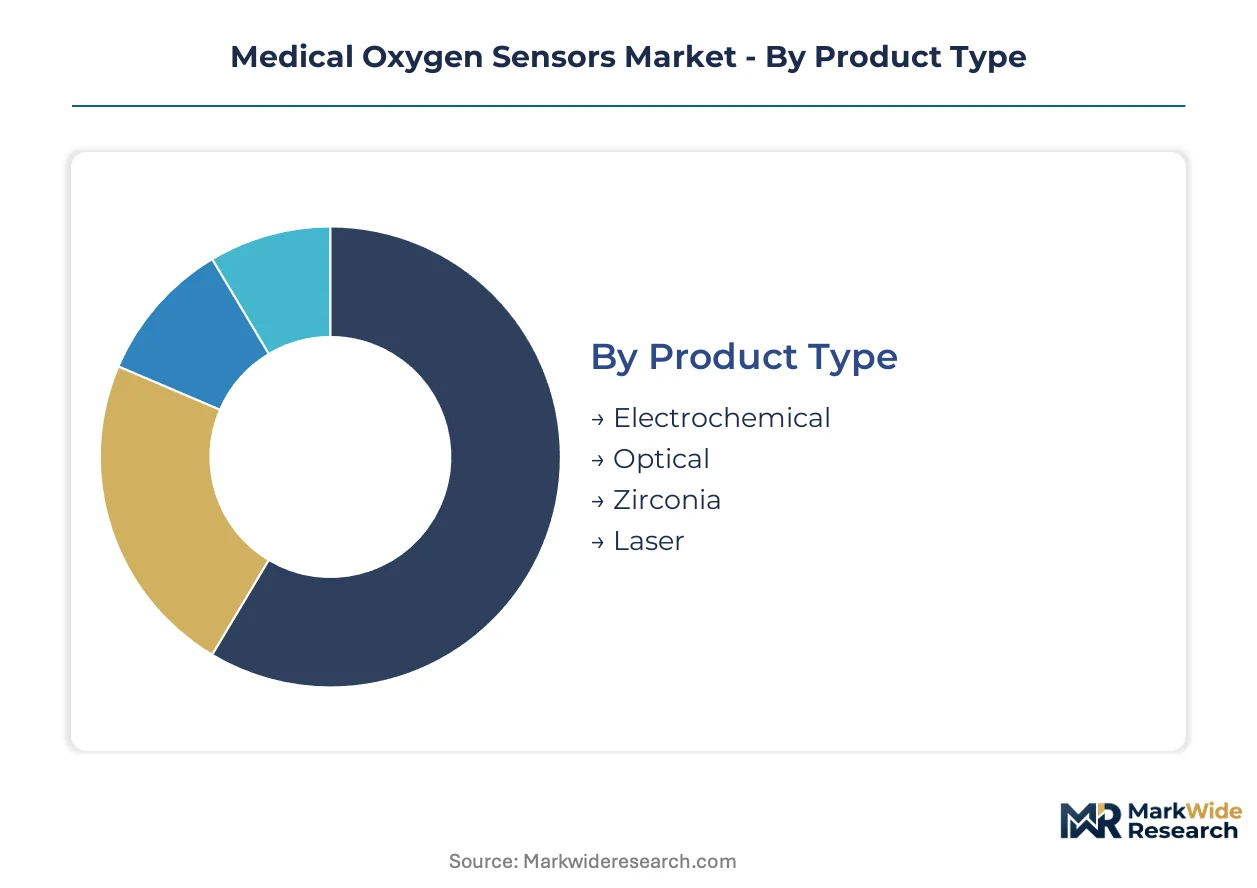
Medical oxygen sensor procurement splits across technical architectures, care settings, connectivity modes, and clinical applications. Each segmentation axis carries distinct regulatory burdens and margin structures that reshape supplier positioning.
Product Type:
FDA 510(k) clearance timelines stretch longest for novel optical platforms, while electrochemical variants leverage predicate device pathways. EU MDR technical documentation demands escalate proportionally with sensor complexity and patient contact duration.
- Electrochemical:Platinum-gold electrode assemblies measure oxygen partial pressure through redox reactions at clinical temperature ranges. Hospital procurement teams in Germany favor these units for anesthesia workstations where proven drift characteristics support predictable calibration cycles.
- Optical:Fluorescence-quenching ruthenium complexes eliminate electrolyte degradation and enable extended maintenance intervals. Swiss tertiary care centers are deploying these sensors for continuous arterial blood gas monitoring in intensive care units.
- Zirconia:Solid-state ceramic designs deliver rapid response times for high-throughput laboratory environments.
- Laser:Tunable diode absorption spectroscopy targets specialized industrial-medical hybrid applications requiring non-contact measurement.
Electrochemical sensors sit at the top of the volume ranking, with optical platforms climbing the fastest.
End User:
Reimbursement coding density varies sharply across care settings, concentrating margin in sites with favorable remote monitoring coverage.
- Hospitals:Tertiary medical centers in the United States operate ventilator fleets with embedded multi-parameter gas monitoring. Consolidated procurement cooperatives are unbundling sensor sourcing from OEM service contracts.
- Home Care:Portable concentrator demand is accelerating in Germany following statutory health insurance coverage expansion for remote patient monitoring devices.
- Emergency Services:Pre-hospital transport ventilators prioritize weight-optimized optical sensors with Bluetooth Low Energy connectivity.
- Laboratories:High-throughput blood gas analyzers specify zirconia-based designs for rapid sample turnaround.
Hospitals command the largest installed base, while home care applications are expanding most quickly.
Technology:
Wireless protocol certification through FCC and CE marking gates creates tiered cost structures across connectivity modes.
- Wireless:Bluetooth Low Energy and NFC integration enables smartphone-integrated diagnostics without dedicated display hardware. FDA's 510(k) third-party review pilot is streamlining clearance for firmware-upgradable wireless respiratory monitors.
- Portable:Battery-optimized optical sensors with reduced calibration burden target ambulatory and transport applications.
- Fixed:Hardwired electrochemical installations dominate anesthesia workstation architectures in Swiss and German hospitals.
- Remote Monitoring:Cloud-connected platforms aggregate sensor data for centralized device management protocols.
Fixed installations retain the highest unit volume, with wireless configurations gaining share fastest.
Application:
ISO 80601-2-55 accuracy thresholds differentiate clinical-grade from consumer-oriented offerings across use cases.
- Critical Care:Continuous arterial blood gas monitoring in intensive care units demands drift-stabilized optical platforms with sub-percent accuracy. German precision medical device manufacturing corridors supply these specialized components.
- Anesthesia Monitoring:Hybrid surgical environments restrict electrochemical deployment due to nitrous oxide and halogenated agent cross-sensitivity, favoring optical alternatives.
- Sleep Studies:Home-based polysomnography drives demand for maintenance-free sensors in portable diagnostic equipment.
- Respiratory Management:Long-term oxygen therapy concentrators specify solid-state designs for reduced service intervals.
Critical Care leads absolute sensor consumption, with Anesthesia Monitoring showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision medical device manufacturing corridor generates higher sensor demand intensity per hospital bed than the United States' fragmented procurement landscape. Switzerland's tertiary care centers pioneer optical platform adoption at faster replacement cycles than neighboring markets.
United States
The Department of Health and Human Services funds ventilator fleet modernization programs that embed multi-parameter gas monitoring. FDA's 510(k) third-party review pilot accelerates clearance pathways for predicate-device modifications. Hospital purchasing cooperatives in the Midwest and Southeast are unbundling sensor procurement from OEM service contracts.
Germany
Statutory health insurance coverage expansion for remote patient monitoring devices creates pull-through demand for maintenance-free oxygen sensors in portable concentrators. EU MDR compliance deadlines accelerate replacement cycles for legacy electrochemical sensors. The precision medical device manufacturing corridor around Tübingen and Freiburg specializes in drift-stabilized optical platforms for continuous arterial blood gas monitoring.
Switzerland
Swissmedic certification requirements for respiratory gas monitors concentrate specialized metrology capabilities in Basel and Zurich testing laboratories. ISO 80601-2-55 calibration expertise creates bottlenecks for new market entrants. Tertiary care centers in Geneva and Lausanne deploy fluorescence-quenching optical sensors for intensive care unit continuous monitoring.
China
NMPA medical device registration reform streamlines approval timelines for electrochemical sensor imports while tightening domestic manufacturing quality standards. The dual carbon goals policy framework accelerates demand for solid-state zirconia designs that eliminate hazardous electrolyte waste streams. Yangtze River Delta medical device clusters in Shanghai and Suzhou assemble sensor-integrated ventilator subsystems for regional hospital networks.
India
The Production-Linked Incentive scheme for domestic manufacturing of critical care equipment creates localized assembly opportunities for sensor-integrated ventilator subsystems. CDSCO medical device rules harmonize with international standards for oxygen sensing accuracy in anesthesia workstations. Maharashtra and Gujarat medical device parks attract component suppliers serving both domestic hospital procurement and export markets.
Medical Oxygen Sensors Market Competitive Landscape
German and Swiss producers anchor the premium-tier sensor segment; United States-based industrial conglomerates hold scale-driven positions in hospital procurement channels. The vendor base splits between integrated ventilator manufacturers and specialized component suppliers. Three archetypes dominate: diversified industrial sensing conglomerates, precision medical device specialists, and anesthesia workstation OEMs with captive sensor production. Competitive moves concentrate on strategic partnerships for wireless connectivity integration and backward integration into optical component supply.
Among diversified industrial technology groups, Honeywell International Inc. occupies a position exemplifying cross-sector sensing capability application. Hamilton Medical and Teledyne Analytical Instruments represent contrasting archetypes—ventilator-integrated versus standalone analytical specialization. SST Sensing Ltd and PreSens Precision Sensing GmbH sit within the precision component supplier tier serving both OEM integration and aftermarket replacement demand. These named entities collectively illustrate the market's structural segmentation across conglomerate, specialist, and captive-production categories.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Teledyne Analytical Instruments |
| Hamilton Medical |
| SST Sensing Ltd |
| PreSens Precision Sensing GmbH |
| Nuova GmbH |
| Orantech USA Inc. |
| Fujikura Global |
| Kranz Equipment |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA 510(k) cleared optical platforms and legacy electrochemical alternatives manifests in divergent pricing power and supply chain sourcing patterns. Premium-tier optical sensors command sustained margins through specialized ruthenium complex sourcing and Swiss-German metrology partnerships, while commodity electrochemical units face margin compression from precious metal electrode cost volatility and hospital procurement consolidation.
Pricing Analysis
Capacity additions in China's Yangtze River Delta sensor assembly corridors are reshaping price floors for electrochemical variants. Three-tier pricing structure across premium optical, standard electrochemical, and economy zirconia levels stratifies by ISO 80601-2-55 calibration grade and wireless connectivity certification. Pricing pressure stems from hospital purchasing cooperatives unbundling sensor procurement from OEM service contracts. Home care concentrator manufacturers exhibit highest price sensitivity; Swiss tertiary care centers demonstrate lowest sensitivity due to drift-stabilized performance requirements.
Supply Chain Analysis
Direct-to-OEM channels handle ventilator manufacturer demand, while specialized distributors serve aftermarket replacement. Supply concentrates in Germany's precision medical device corridor, Taiwan's LED and photodiode foundries, and South Korea's semiconductor packaging facilities. Production draws from platinum and gold electrode coatings, ruthenium complex fluorescence dyes, and zirconia ceramic substrates. Single-source vulnerability in Taiwanese optical component supply creates structural risk. Distribution runs through GPO-integrated procurement cooperatives in North America and statutory health insurance frameworks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU MDR recertification deadlines and FDA 510(k) pathway reforms accelerate replacement cycles and reshape competitive positioning.
For Market Incumbents: Deepen backward integration into ruthenium complex supply and Swiss calibration laboratory partnerships to defend against optical platform commoditization. Invest in Bluetooth Low Energy firmware certification to capture hospital wireless integration mandates. Consolidate service contract bundling before purchasing cooperative unbundling erodes attach rates. For New Entrants and Emerging Players: India's PLI scheme for critical care equipment opens a window for localized ventilator subsystem assembly with reduced import duty exposure. Target Germany's statutory health insurance remote monitoring reimbursement expansion with maintenance-free optical sensors for portable concentrators. Pursue CDSCO harmonization pathways for anesthesia workstation sensor qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 80601-2-55 calibration expertise concentrates in German and Swiss testing laboratories. Long-term viability favors precision component specialists with captive optical chemistry capabilities and hospital GPO contract access. Watch NMPA domestic manufacturing quality standard tightening as inflection signal for China supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates recertification timelines for drift-stabilized optical platforms in German manufacturing corridors. |
| Backward Integration into Ruthenium Complex Supply | Secures fluorescence dye sourcing for premium-tier arterial blood gas monitoring sensors. |
| Bluetooth Low Energy Firmware Certification | Enables smartphone-integrated home diagnostics under FDA 510(k) third-party review pilot. |
| Hospital Purchasing Cooperative Partnership | Locks in sensor procurement volumes before OEM service contract unbundling advances. |
| India PLI Scheme Localized Assembly | Captures ventilator subsystem demand from Maharashtra and Gujarat medical device parks. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers, hospital GPO contracts managers, and anesthesia workstation procurement leads; secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, and CMS Medicare reimbursement codes; plus customs records for platinum and gold electrode coating imports — were reconciled through bottom-up sensor unit deployment estimates and top-down critical care equipment market sizing.
Historical installation base trajectories were cross-referenced against panel input from ventilator OEMs and precision sensor specialists. Segmentation modeling spanned product architecture, care setting, connectivity mode, and clinical application across the projection horizon. CAGRs were derived from replacement cycle analysis calibrated to regulatory deadline impacts and infrastructure funding program disbursements. Forecast inputs incorporated precious metal price volatility indices and wireless protocol certification timelines.
Revisions become necessary when EU MDR enforcement intensity shifts, NMPA domestic manufacturing standards tighten, or hospital procurement consolidation accelerates beyond modeled thresholds. Forecasts reflect documented assumptions regarding optical platform adoption curves and electrochemical sensor obsolescence patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Inversion Table Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
Cranial Clamps Market
Medical Devices
Spinal Implant Market
Medical Devices
Wearable ECG Sensor Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market