
 Aortic Cannula Systems Market | 2026-2036
Aortic Cannula Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aortic Cannula Systems Market Analytics
Multi-source procurement for polymer extrusions and tip-forming components is hardening as device OEMs reduce single-source dependency for critical blood-handling parts. Medtronic leverages backward integration into precision molding to protect proprietary cannula geometries. Edwards Lifesciences Corporation anchors its position through sustained R&D intensity in minimally invasive delivery platforms.
Aortic cannula systems are sterile, single-use or limited-reuse tubular devices constructed from medical-grade PVC, silicone, or thermoplastic elastomers, featuring radio-opaque markers and graduated insertion depths, designed to establish blood flow between the heart and extracorporeal circulation circuits during cardiac procedures. Single-use cannulas dominate hospital procurement due to infection control protocols, while dual-lumen configurations capture expanding margin pools as surgeons adopt streamlined venous-arterial cannulation. Cardiac surgery applications retain the largest volume share, though extracorporeal life support segments are attracting accelerated product development investment.
FDA 510(k) clearance pathways and EU MDR Class III device requirements impose substantial clinical evidence burdens on new entrants, effectively filtering market access to well-capitalized manufacturers with established quality management systems. ISO 10993 biocompatibility testing and ASTM material standards further constrain substrate selection and sterilization validation scope. Stakeholders must monitor evolving notified body capacity constraints in Europe and the trajectory of FDA's Safer Technologies Program for breakthrough device designations.
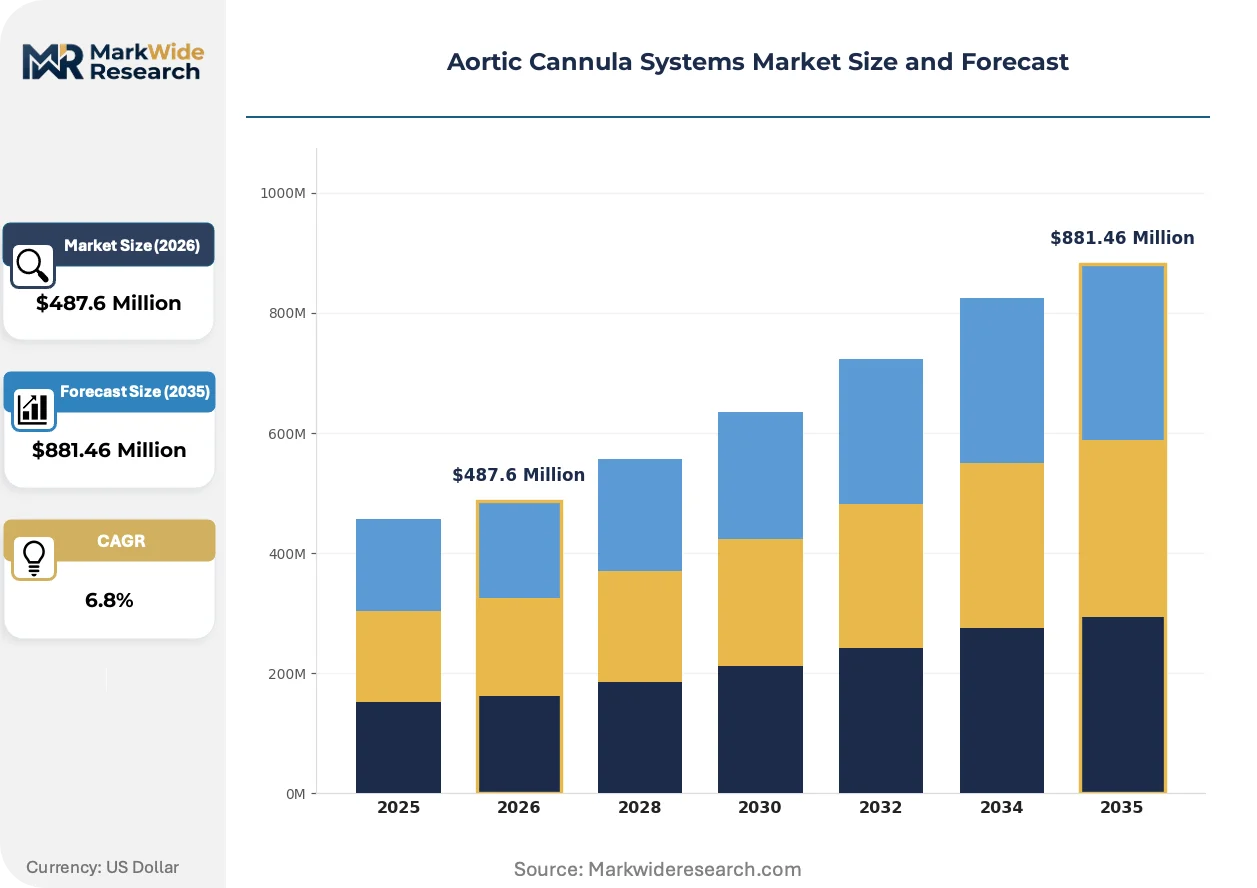
Market Dynamics
Cardiac surgery centers are consolidating vendor relationships as EU MDR compliance costs force smaller manufacturers from the market, concentrating procurement power among hospital systems with dedicated perfusion departments.
Growth Catalysts
- EU MDR Class III pathways:Stricter clinical evidence requirements are filtering out marginal competitors and expanding market share for established quality system holders.
- Extracorporeal membrane oxygenation expansion:ECMO program proliferation in tertiary cardiac centers is creating incremental demand for dual-lumen arterial configurations.
- Japan's aging surgical population:Tokyo and Osaka cardiac institutes are replacing cannula inventories at accelerated cycles due to procedure volume recovery.
Market Restraints
- Medical-grade silicone price volatility:Petrochemical feedstock fluctuations compress margins for manufacturers without long-term polymer supply agreements.
- Notified body capacity constraints:European technical review backlogs extend EU MDR certification timelines by 12-18 months for new device submissions.
- Reusable cannula substitution:Limited-reuse stainless steel tip configurations retain preference in cost-constrained Eastern European hospital systems.
Strategic Opportunities
- India's cardiac infrastructure buildout:Delhi and Mumbai private hospital chains are establishing perfusion departments requiring full cannula system procurement.
- FDA Safer Technologies Program:Breakthrough device designation pathways offer expedited review for antimicrobial-coated cannula innovations.
- Point-of-care sterilization integration:Hybrid single-use/limited-reuse systems are modularizing supply chain flexibility for rural cardiac centers.
Industry Challenges
- Perfusionist workforce scarcity:Specialized training program bottlenecks in Germany and the United States constrain optimal device utilization rates.
- ISO 10993-18 chemical characterization:Extractables and leachables testing protocols add six-figure validation costs per substrate formulation change.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aortic Cannula Systems Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Cannulas, Dual-Lumen Cannulas, Pediatric Cannulas, Hybrid Cannulas End User: Hospitals, Cardiac Surgery Centers, Outpatient Clinics, Research Institutions Delivery Mode: Invasive Procedure, Minimally Invasive Procedure, Open Surgery, Video-Assisted Techniques Application: Cardiac Surgery, Blood Management, Extracorporeal Life Support, Organ Transplantation |
| Companies Covered | Medtronic, Edwards Lifesciences Corporation, LivaNova PLC, BD, Getinge, Terumo Corporation, Nipro Corporation, Surge Cardiovascular, Fresenius Medical Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aortic Cannula Systems Market Evolving Landscape
Device architectures are fragmenting into application-specific configurations as surgeons demand cannula geometries optimized for minimally invasive access ports rather than traditional sternotomy approaches.
Radio-opaque marker integration is modularizing across next-generation thermoplastic elastomer formulations. Cardiac surgery centers in the United States are specifying graduated depth indicators for robotic-assisted procedures. This capability compression is collapsing the distinction between standard and premium cannula tiers.
FDA's intensified scrutiny of sterilization validation data is extending 510(k) review cycles for ethylene oxide-processed devices. Manufacturers are migrating to gamma irradiation protocols or electron beam alternatives to preempt regulatory holds. Small-cap entrants lacking dedicated regulatory affairs functions are withdrawing submissions rather than responding to additional information requests.
Hospital procurement departments are consolidating annual cannula purchasing into multi-year framework agreements with single-source suppliers. German cardiac centers pioneered this model; United States academic medical centers are replicating it to secure volume discounts and dedicated field technical support. The shift is marginalizing independent distributors and compressing available shelf space for secondary brands.
Aortic Cannula Systems Market Segmentation
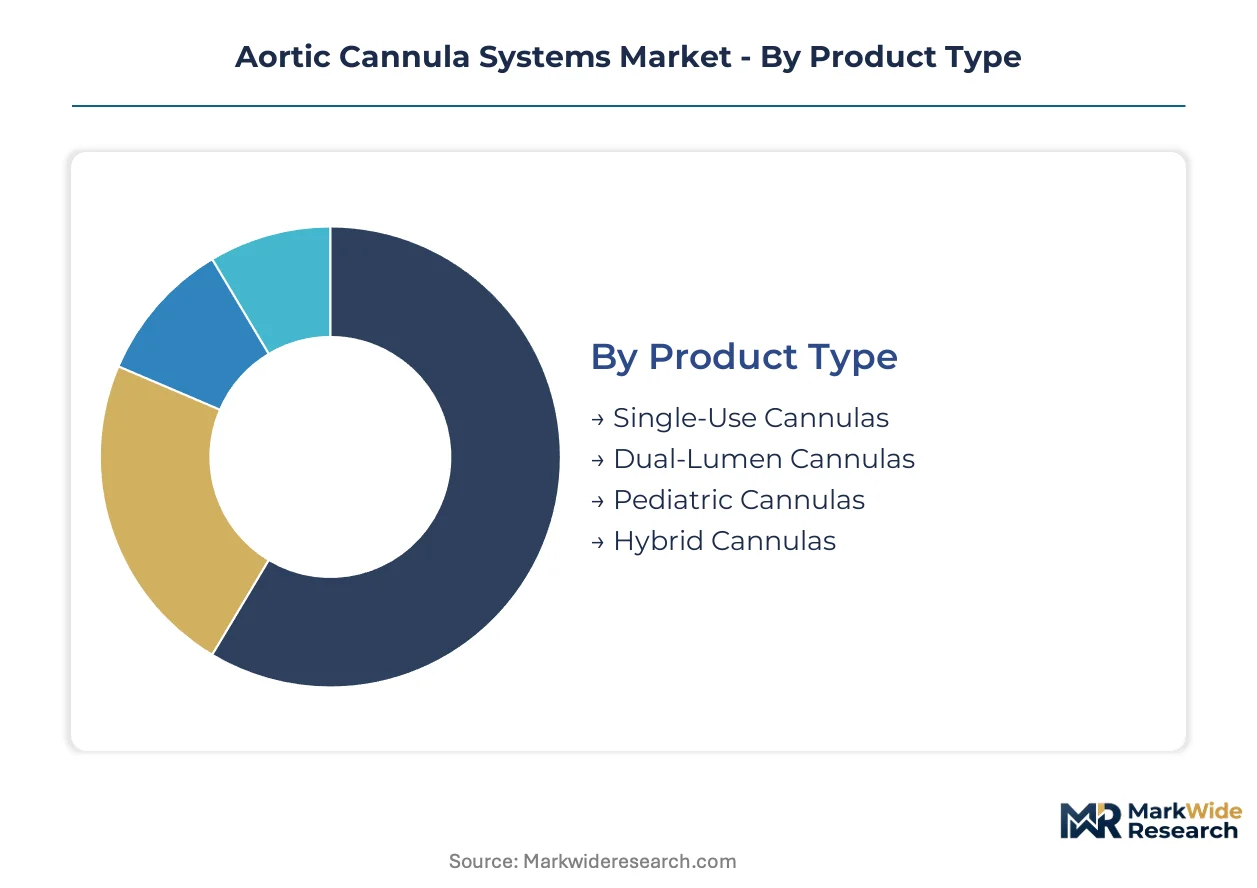
Aortic cannula procurement patterns diverge sharply across product configurations and clinical settings. Hospital systems prioritize infection control protocols and procedural throughput when segmenting vendor portfolios.
Product Type:
Capital requirements concentrate in dual-lumen and hybrid configurations where precision molding and multi-material bonding demand specialized cleanroom infrastructure.
- Single-Use Cannulas:Polymer extrusions in medical-grade PVC or silicone incorporate radio-opaque markers and graduated depth indicators. Demand concentrates in United States academic medical centers enforcing strict infection control protocols against surgical site infections.
- Dual-Lumen Cannulas:Integrated venous-arterial flow channels reduce cannulation sites during cardiopulmonary bypass. German cardiac surgery centers in Berlin and Munich are expanding procurement as minimally invasive procedure volumes recover.
- Pediatric Cannulas:Smaller-diameter configurations with enhanced flexibility for neonatal and infant cardiac procedures.
- Hybrid Cannulas:Modular single-use/limited-reuse systems enabling point-of-care sterilization flexibility.
Single-use cannulas absorb the bulk of installed capacity; dual-lumen cannulas are expanding most quickly.
End User:
Procurement sophistication varies by institutional scale, with tertiary centers commanding dedicated perfusion departments and framework purchasing power.
- Hospitals:General acute-care facilities with mixed surgical portfolios and standardized central supply chains.
- Cardiac Surgery Centers:Dedicated perfusion departments in Cleveland Clinic, Mayo Clinic, and Charité Berlin drive specification of premium configurations with robotic-assisted compatibility.
- Outpatient Clinics:Limited procedural volume restricts cannula inventory to emergency backup stock.
- Research Institutions:Preclinical testing facilities in Japan's National Cerebral and Cardiovascular Center validate next-generation biocompatible coatings.
Cardiac surgery centers command the highest per-procedure spend; hospitals provide the broadest volume base.
Delivery Mode:
Surgeon training pathways and institutional equipment investments lock in delivery mode preferences across geographic markets.
- Invasive Procedure:Traditional sternotomy approaches with direct aortic cannulation retain dominance in Eastern European cost-constrained systems.
- Minimally Invasive Procedure:Port-access configurations demand specialized curved-tip geometries and enhanced flexibility. Tokyo Women's Medical University and Osaka University Hospital are specifying graduated-depth indicators for robotic-assisted deployment.
- Open Surgery:Conventional approaches with full visualization remain standard for complex redo operations.
- Video-Assisted Techniques:Thoracoscopic guidance systems requiring modified cannula lengths and tip angulation.
Open surgery retains the largest installed base; minimally invasive procedures are climbing the fastest.
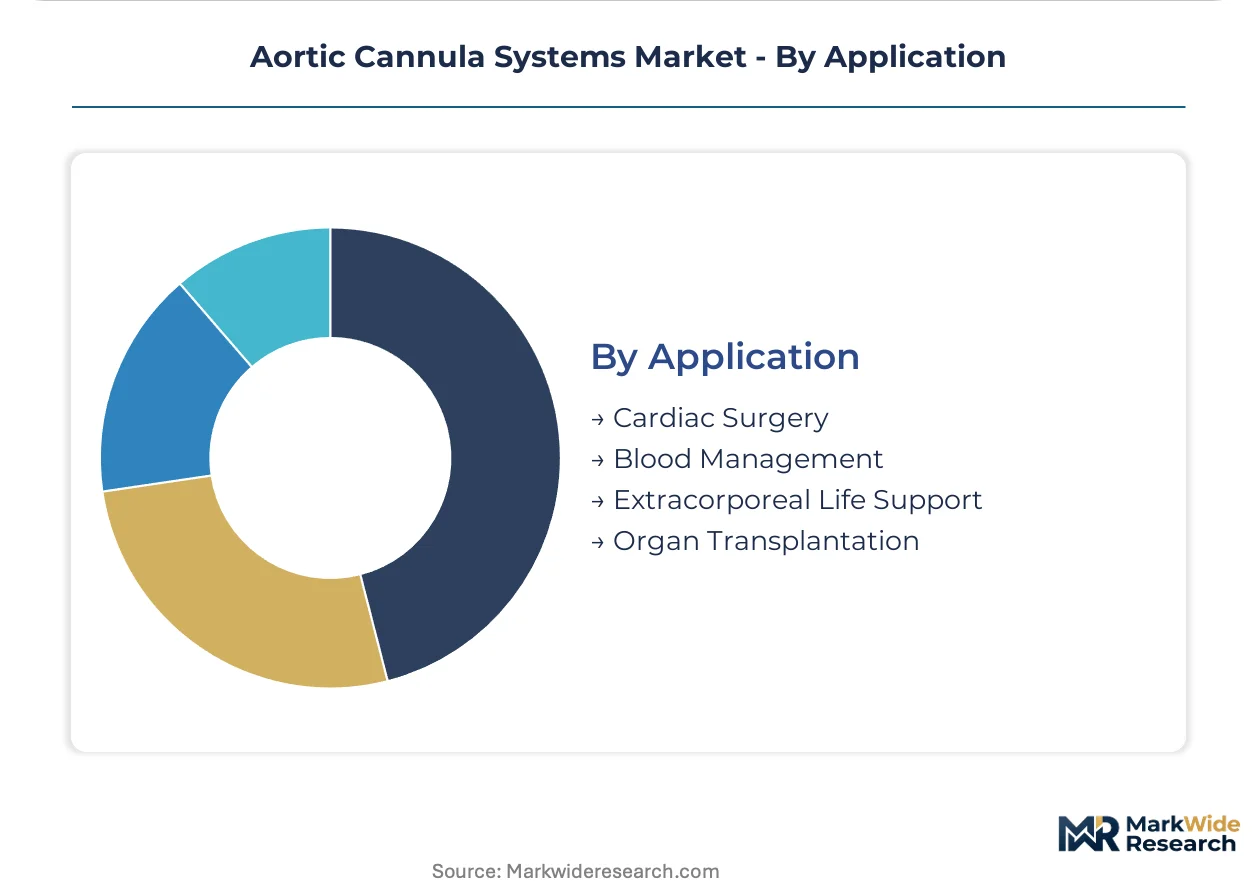
Application:
Clinical indication severity determines cannula specification tier and replacement cycle frequency.
- Cardiac Surgery:Coronary artery bypass and valve replacement procedures sustain baseline demand across all product configurations.
- Blood Management:Intraoperative autotransfusion and cell salvage applications.
- Extracorporeal Life Support:ECMO programs at Massachusetts General Hospital and Heidelberg University Hospital are creating incremental demand for dual-lumen arterial configurations with extended dwell-time biocompatibility.
- Organ Transplantation:Heart and lung procurement protocols requiring rapid aortic cross-clamp and cardioplegia delivery.
Cardiac surgery anchors current revenue; extracorporeal life support shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone feedstock from Wacker Chemie's Burghausen complex anchors European supply security for blood-contacting polymer extrusions. German compounders ship formulated resins to device molders across the continent. Asian petrochemical corridors in South Korea and Japan provide competing thermoplastic elastomer streams.
United States
Cleveland Clinic and Mayo Clinic perfusion departments drive specification of robotic-assisted compatible cannula configurations. FDA 510(k) clearance pathways impose clinical evidence burdens that filter market access to established quality system holders. Boston's medical device corridor concentrates precision molding capacity for radio-opaque marker integration.
Germany
Berlin and Munich cardiac surgery centers expand procurement of dual-lumen configurations as minimally invasive procedure volumes recover. EU MDR Class III device requirements extend certification timelines through notified body capacity constraints. Baden-Württemberg's polymer processing cluster supplies medical-grade PVC extrusions to device OEMs.
Japan
Tokyo Women's Medical University and Osaka University Hospital specify graduated-depth indicators for robotic-assisted deployment. PMDA regulatory pathways align with international ISO 10993 biocompatibility standards. The National Cerebral and Cardiovascular Center validates next-generation coatings for extended dwell-time applications.
India
Delhi and Mumbai private hospital chains establish perfusion departments requiring full cannula system procurement. CDSCO medical device regulations tighten import quality controls for blood-contacting devices. Karnataka's medical technology corridor attracts contract manufacturing investment from multinational device firms.
South Korea
Seoul Capital Area tertiary cardiac centers expand ECMO programs creating incremental demand for dual-lumen arterial configurations. MFDS regulatory pathways emphasize sterilization validation for single-use devices. Busan-Ulsan's polymer processing base supplies medical-grade silicone formulations to regional device manufacturers.
Aortic Cannula Systems Market Competitive Landscape
Backward integration into precision molding dominates the current landscape as manufacturers protect proprietary cannula geometries. The vendor base concentrates around three tiers: multinational device conglomerates with captive polymer supply, mid-cap specialists with cleanroom extrusion capabilities, and regional fabricators serving cost-constrained hospital systems. Strategic archetypes include quality-system holders leveraging EU MDR compliance costs to displace marginal competitors, and technology licensors partnering with Asian contract manufacturers. M&A activity and capacity expansion in dual-lumen configurations represent the dominant competitive moves.
Among diversified medical technology conglomerates, Medtronic exemplifies the backward-integrated archetype through in-house production of precision-molded components. Edwards Lifesciences Corporation occupies a position representing sustained R&D intensity in minimally invasive delivery platforms. Terumo Corporation anchors the Asia-Pacific competitive vector as a Japanese Co., Ltd. with established regulatory affairs infrastructure across multiple geographies.
| Leading Market Players |
|---|
| Medtronic |
| Edwards Lifesciences Corporation |
| LivaNova PLC |
| BD |
| Getinge |
| Terumo Corporation |
| Nipro Corporation |
| Surge Cardiovascular |
| Fresenius Medical Care |
| Others |
Value Network & Pricing Analysis
Hospital systems with dedicated perfusion departments command consolidated procurement power, translating into multi-year framework agreements that compress pricing flexibility for secondary manufacturers. This buyer concentration rewards established quality-system holders with volume premiums while marginalizing independent distributors.
Pricing Analysis
Service bundling separates premium-tier vendors from commodity suppliers, with field technical support and sterilization validation assistance included in framework contracts. Pricing stratifies across premium dual-lumen configurations, standard single-use cannulas, and economy limited-reuse systems, with differentiation driven by ISO 10993 certification tier and after-sales service depth. Cost compression in standard single-use tiers is intensifying because medical-grade silicone feedstock volatility squeezes manufacturers without long-term polymer agreements. Eastern European hospital systems exhibit highest price sensitivity; United States academic medical centers show least.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns serving cardiac surgery clusters. Medical-grade silicone formulations from Wacker Chemie's Burghausen complex and thermoplastic elastomer streams from South Korean petrochemical corridors feed precision molding operations. Single-source dependency for radio-opaque marker compounds constitutes the dominant supply chain risk. Distribution runs through authorized distributors with field technical support capabilities, though hospital procurement consolidation is compressing available shelf space.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU MDR Class III compliance costs filter marginal competitors from certification pathways. Quality-system investment requirements favor well-capitalized incumbents with established notified body relationships.
For Market Incumbents: Anticipate perfusionist workforce scarcity constraining optimal device utilization rates by expanding remote technical support capabilities and automated cannula deployment training modules. Backward integration into precision molding protects proprietary geometries from polymer supply disruption. Capacity addition in India's Karnataka medical technology corridor captures infrastructure buildout demand.
For New Entrants and Emerging Players: Begin with antimicrobial-coated cannula innovations targeting FDA Safer Technologies Program breakthrough designation pathways, where expedited review offsets clinical evidence burdens. India's Delhi and Mumbai private hospital chains offer the most penetrable geography for full system procurement. Partner with Asian contract manufacturers possessing established regulatory affairs infrastructure across multiple geographies.
For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with cleanroom extrusion capabilities and EU MDR quality system holders facing capital constraints for dual-lumen capacity expansion. Long-term viability hinges on capturing ECMO program proliferation in tertiary cardiac centers. Watch notified body capacity normalization in Europe as inflection indicator for certification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class III Certification Investment | Quality-system holders leverage notified body relationships to displace marginal competitors from hospital procurement. |
| Dual-Lumen Configuration Capacity Expansion | German and United States cardiac surgery centers drive specification as minimally invasive procedure volumes recover. |
| Antimicrobial Coating R&D Partnership | FDA Safer Technologies Program offers expedited review pathway for breakthrough device designation candidates. |
| India Distribution Infrastructure Buildout | Delhi and Mumbai private hospital chains establish perfusion departments requiring full cannula system procurement. |
| Gamma Irradiation Sterilization Migration | Manufacturers preempt FDA review cycle extensions for ethylene oxide-processed devices. |
Research Methodology
Independent corroboration across perfusion department heads, hospital purchasing committee members, and biomedical engineers underwrites the qualitative findings in this analysis. Primary interviews with GPO contracts managers and regulatory affairs specialists at device OEMs combined with secondary validation from FDA 510(k) filings, EU MDR notified body submission databases, and hospital procurement contract records. Bottom-up cannula shipment estimates triangulate against top-down cardiac procedure volume projections.
Comparable historical reference periods spanning pre-pandemic baseline, disruption trough, and recovery trajectory anchor the forecast window across the analysis window. Segmentation dimensions modeled include product configuration, delivery mode, application severity, and institutional procurement sophistication. CAGRs derive from procedure volume elasticity to demographic aging patterns and technology substitution rates. ECMO program proliferation and robotic-assisted surgery adoption constitute primary demand-side inputs.
Underlying measurement precision varies by segment; single-use cannula volumes carry tighter precision than hybrid limited-reuse system estimates. Forecasts reflect assumptions regarding EU MDR notified body capacity normalization and medical-grade polymer supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Kirschner Wires Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Pipette Controllers Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Aesthetic Devices Market
Medical Devices
Pen Needles Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Global Stent Graft Balloon Catheter Market