
 Global Stabilometric Platform Market | 2026-2036
Global Stabilometric Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stabilometric Platform Market Intelligence
Sports training is consolidating as the fastest-expanding end-use vertical for stabilometric platforms, displacing slower-growing general physiotherapy segments. Techno Concept leverages its European manufacturing base to dominate force plate exports across rehabilitation centers. Biodex Medical Systems sustains R&D intensity in integrated systems that combine pressure mapping with motion capture. Sensor Medica specializes in portable units that extend channel reach into smaller physiotherapy clinics and elder care facilities.
A stabilometric platform measures postural sway and center-of-pressure displacement using force transducers, load cells, or optical arrays to quantify balance and proprioceptive function. Force plate systems, which detect ground reaction forces across triaxial dimensions, anchor clinical diagnostics through standardized protocols such as the Sensory Organization Test. Pressure mat deployments are accelerating fastest in sports training applications where real-time feedback during dynamic movement is critical. Hybrid systems that fuse inertial sensors with force plates command premium positioning in research institutes due to their superior temporal resolution and multi-parameter output.
The FDA's 510(k) clearance framework and the EU MDR's clinical evidence requirements are elevating barriers for new entrants while reinforcing incumbent quality systems. Japan's PMDA and METI coordinate on harmonized standards for neurological rehabilitation devices that align with ISO 13485 quality management protocols. Stakeholders must monitor evolving reimbursement codes for balance assessment in geriatric care and track how cloud-based platform architectures reshape data ownership models across clinical and sports end users.
Market Dynamics
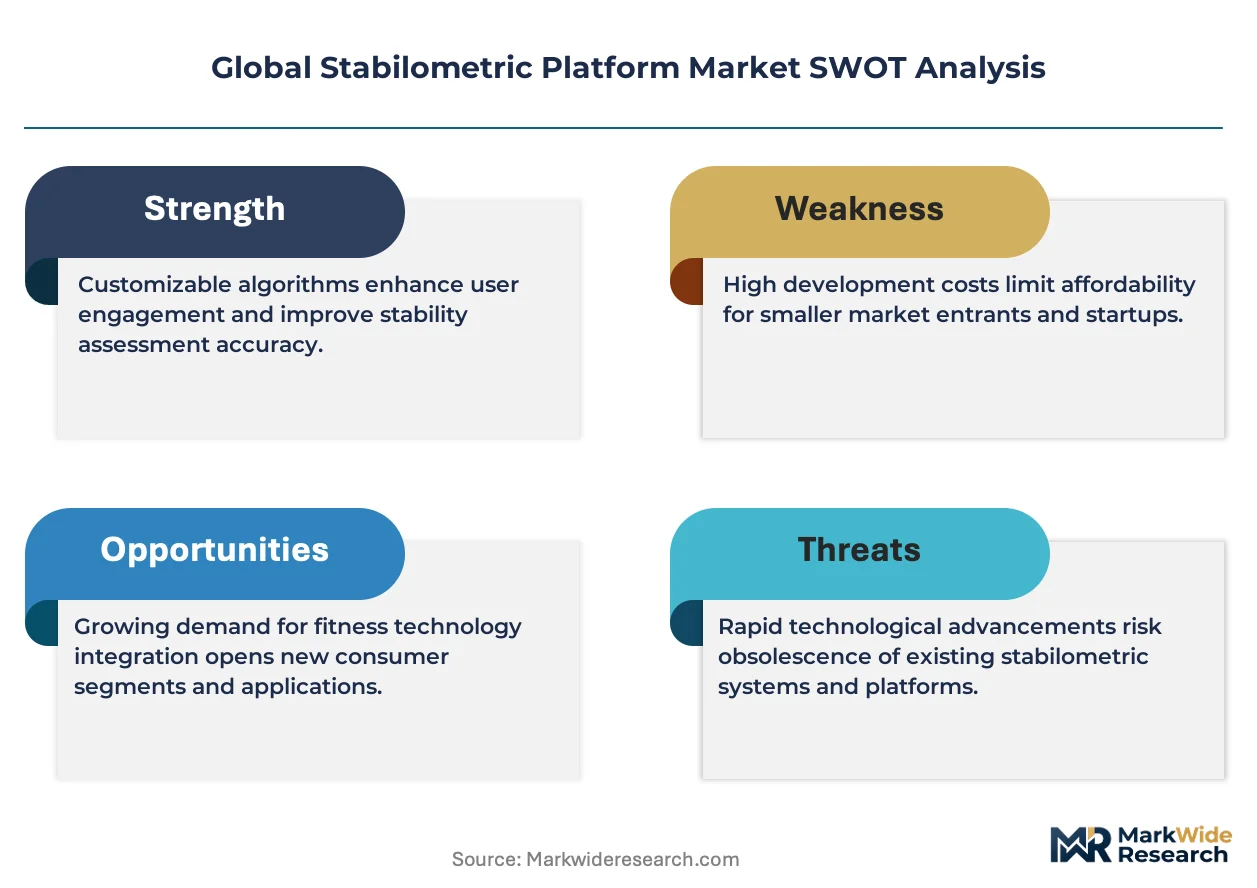
Hybrid sensor architectures are compressing the performance gap between clinical-grade diagnostics and portable training tools, forcing incumbents to recalibrate R&D roadmaps and pricing architectures simultaneously.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's predicate device framework for Class II medical devices accelerates market entry for force plate manufacturers with established clinical validation histories.
- Sports science investment surge:Professional athletic training programs across Germany, Japan, and the United States are consolidating procurement of real-time biomechanical feedback systems.
- EU MDR harmonization:The Medical Device Regulation's unified clinical evidence standards reduce fragmentation across European rehabilitation markets, simplifying multi-country deployment.
Market Restraints
- Load cell supply concentration:Precision strain gauge manufacturing clusters in Germany and Japan, exposing platform assemblers to single-source vulnerability.
- EU MDR clinical evidence costs:The regulation's expanded post-market surveillance requirements impose documentation burdens that disproportionately constrain mid-tier manufacturers.
- Consumer-grade IMU substitution:Low-cost inertial measurement units from smartphone and wearables supply chains threaten entry-level static platform segments.
Strategic Opportunities
- India rehabilitation infrastructure:The country's expanding network of government-funded physiotherapy centers under the National Health Mission creates channel access for cost-optimized pressure mat systems.
- Cloud-native platform architectures:Subscription-based data analytics and remote monitoring capabilities are expanding into elder care facilities seeking reduced capital deployment.
- ISO 13485 convergence:Harmonized quality management standards across Japan's PMDA and METI frameworks reduce compliance duplication for manufacturers targeting neurological rehabilitation segments.
Industry Challenges
- Biomechanical engineering talent scarcity:The intersection of signal processing, sports science, and clinical validation expertise concentrates in academic hubs, constraining product development velocity.
- Legacy EMR integration friction:Hospital procurement committees demand HL7 FHIR compatibility that legacy platform architectures lack, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stabilometric Platform Market |
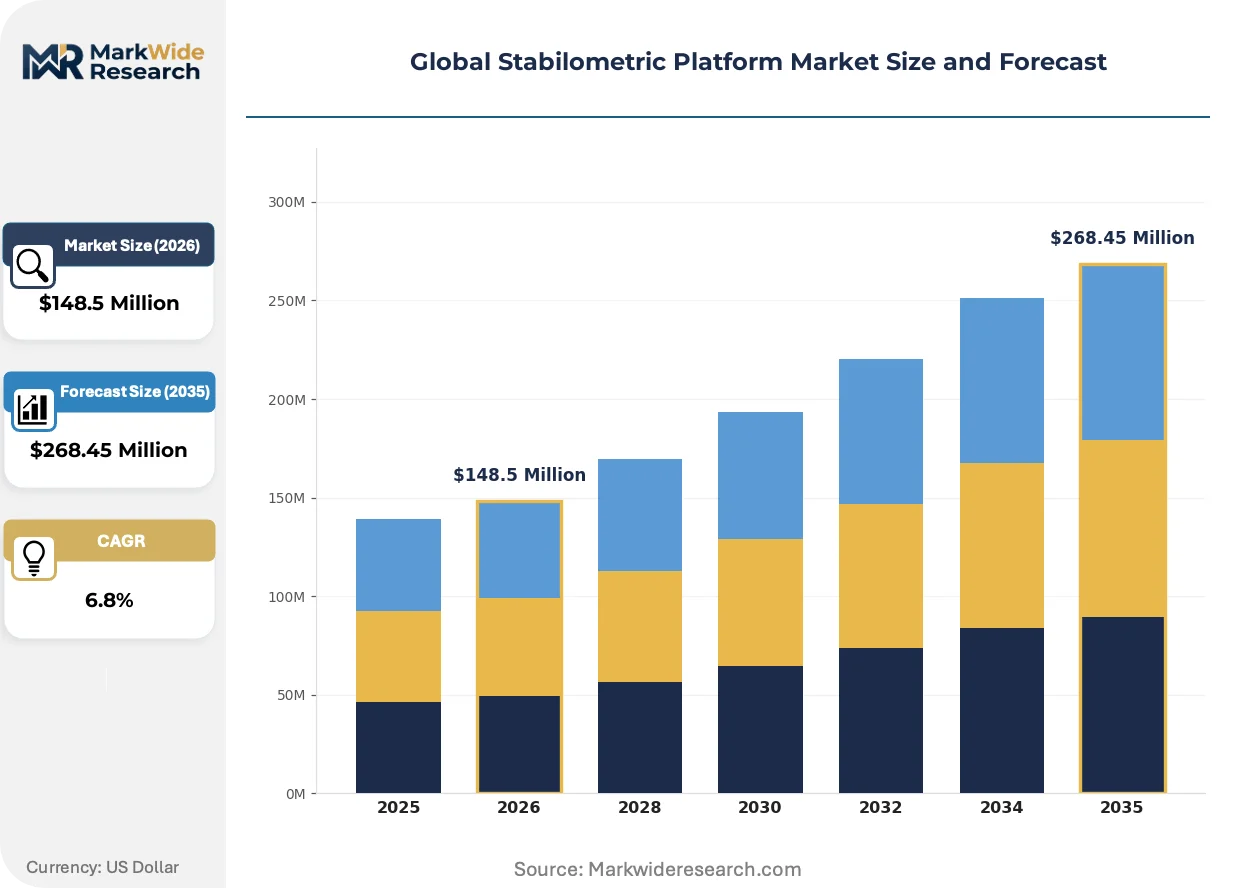
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $268.45 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Force Plate, Pressure Mat, Inertial Sensor, Optical Sensor, Hybrid System Application: Balance Assessment, Neurological Rehabilitation, Sports Training, Fall Risk Analysis, Ergonomic Evaluation End User: Rehabilitation Centers, Sports Academies, Research Institutes, Elder Care Facilities, Physiotherapy Clinics Deployment Mode: Standalone Systems, Portable Units, Integrated Systems, Cloud-Based Platforms |
| Companies Covered | Techno Concept, NeuroCom International (Natus Medical), Biodex Medical Systems, HUR Labs, Balance Systems Srl, Sensor Medica, Medicapteurs, KINESIQ, Zebris Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stabilometric Platform Market Strategic Shifts & Innovations
Real-time kinematic feedback is displacing retrospective diagnostic workflows across both clinical and performance optimization settings, compressing the value chain between data capture and actionable insight delivery.
Portable pressure mat systems are expanding into dynamic movement analysis for athletic training applications. NCAA Division I programs and European football academies are deploying these units for on-field balance assessment during practice sessions. This technology is expanding into segments previously served only by fixed laboratory installations, eroding the installed base advantage of traditional force plate vendors.
The EU MDR's post-market clinical follow-up requirements are elevating real-world evidence collection to a competitive differentiator. Manufacturers must now maintain active surveillance registries that track device performance across diverse patient populations. Rehabilitation centers in France and Italy are prioritizing suppliers with established PMCF infrastructures, shifting procurement criteria toward longitudinal data capabilities.
Direct-to-facility equipment financing is displacing traditional capital purchase models in North American outpatient clinics. Third-party lessors are bundling maintenance, software updates, and calibration services into per-assessment fee structures. This pattern concentrates in the United States where reimbursement code uncertainty for balance testing discourages outright ownership commitments.
Global Stabilometric Platform Market Segmentation
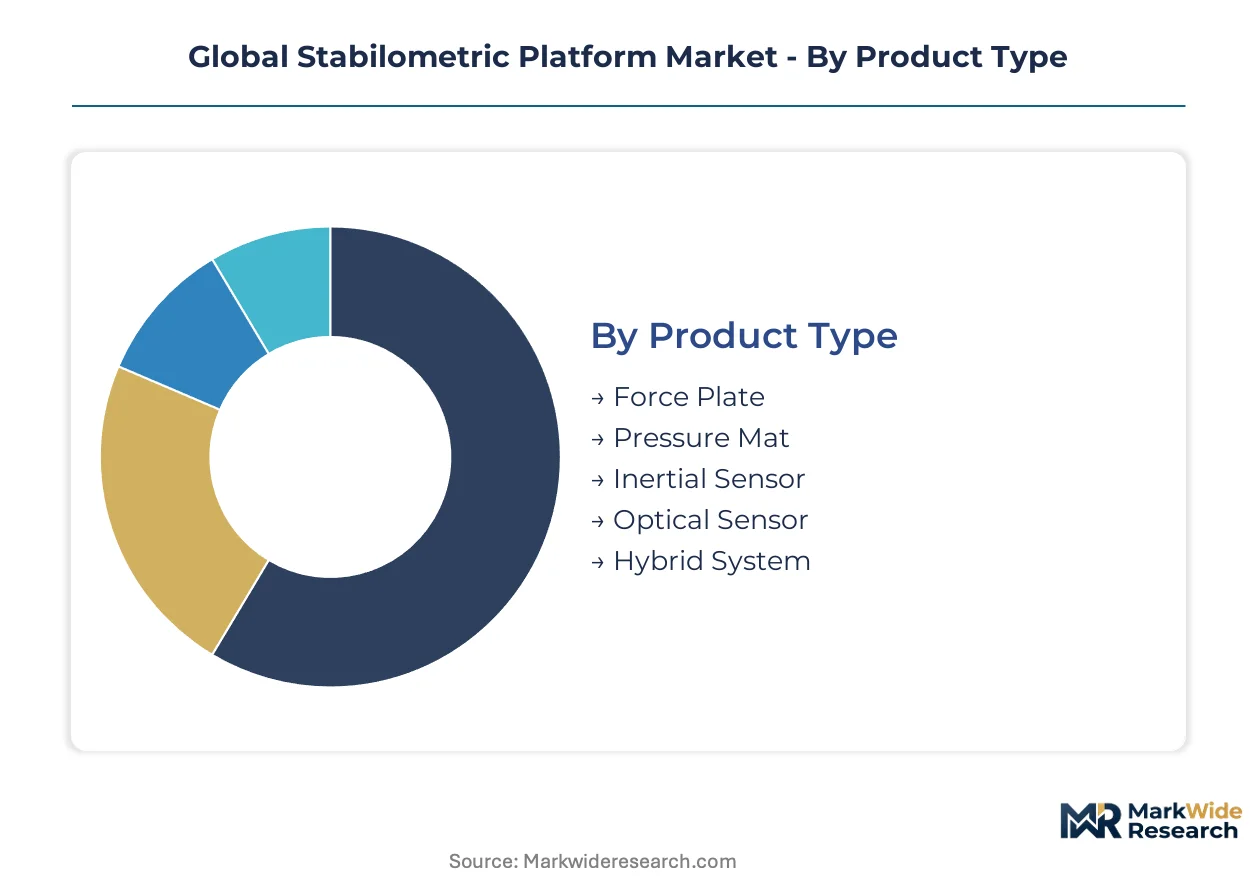
Stabilometric platform segmentation reveals divergent capital requirements across hardware architectures and deployment models. Product type and deployment mode categories exhibit the steepest investment gradients, while application and end-user segments demonstrate how procurement authority migrates between clinical reimbursement and performance optimization budgets.
Product Type:
Force plate systems demand the highest upfront capital deployment due to precision load cell arrays and triaxial calibration infrastructure. Pressure mat and portable sensor categories require substantially lower fixed investment, enabling broader channel penetration.
- Force Plate:Triaxial load cell arrays detect ground reaction forces with laboratory-grade precision. Rehabilitation centers in Germany and the United States concentrate procurement for standardized Sensory Organization Test protocols, though load cell supply concentration in Japan and Germany exposes assemblers to single-source vulnerability.
- Hybrid System:Fused inertial sensors with force plates deliver superior temporal resolution for multi-parameter output. Research institutes across Japan and the United States absorb premium positioning for these units, driven by post-market clinical follow-up requirements under EU MDR that elevate real-world evidence collection capabilities.
- Pressure Mat:Flexible sensor arrays enable dynamic movement analysis with reduced calibration overhead.
- Inertial Sensor:Accelerometer-gyroscope combinations support portable deployments with lower capital barriers.
- Optical Sensor:Marker-based or markerless camera systems capture kinematic data without ground contact.
Force plate systems absorb the bulk of installed capacity; hybrid systems are expanding most quickly.
Application:
Procurement authority concentrates differently across clinical reimbursement codes versus discretionary athletic budgets. Neurological rehabilitation commands the most rigorous documentation standards, while sports training exhibits the fastest procurement cycle acceleration.
- Sports Training:Real-time biomechanical feedback during dynamic movement compresses the value chain between data capture and actionable insight. NCAA Division I programs and European football academies deploy portable pressure mat systems for on-field balance assessment, displacing slower-growing general physiotherapy segments through faster procurement decisions.
- Neurological Rehabilitation:FDA 510(k) clearance pathways and EU MDR clinical evidence requirements impose elevated documentation burdens. Rehabilitation centers in France and Italy prioritize suppliers with established post-market clinical follow-up infrastructures, shifting procurement criteria toward longitudinal data capabilities.
- Balance Assessment:Standardized diagnostic protocols anchor clinical utility across geriatric and vestibular patient populations.
- Fall Risk Analysis:Elder care facilities drive demand for rapid screening tools with minimal operator training.
- Ergonomic Evaluation:Occupational health departments utilize static and dynamic postural analysis for workplace intervention design.
Neurological rehabilitation commands the deepest reimbursement integration; sports training is climbing the fastest.
End User:
Customer type segmentation tracks how procurement authority fragments between institutional capital budgets and third-party financing structures. Research institutes maintain the most stringent technical specifications, while elder care facilities exhibit rising price sensitivity.
- Research Institutes:Multi-parameter output requirements and superior temporal resolution specifications dominate technical evaluation. Japan's PMDA and METI coordination on harmonized standards for neurological rehabilitation devices aligns procurement with ISO 13485 quality management protocols, reducing compliance duplication for manufacturers.
- Elder Care Facilities:Cloud-native platform architectures with subscription-based data analytics expand channel access for reduced capital deployment. Direct-to-facility equipment financing displaces traditional capital purchase models, particularly in the United States where reimbursement code uncertainty discourages outright ownership commitments.
- Rehabilitation Centers:Fixed installations with standardized diagnostic protocols anchor clinical utility.
- Sports Academies:Portable systems for dynamic movement analysis gain share in professional training environments.
- Physiotherapy Clinics:Smaller footprints and lower throughput requirements favor cost-optimized configurations.
Rehabilitation centers absorb the bulk of installed capacity; elder care facilities are gaining share fastest.
Deployment Mode:
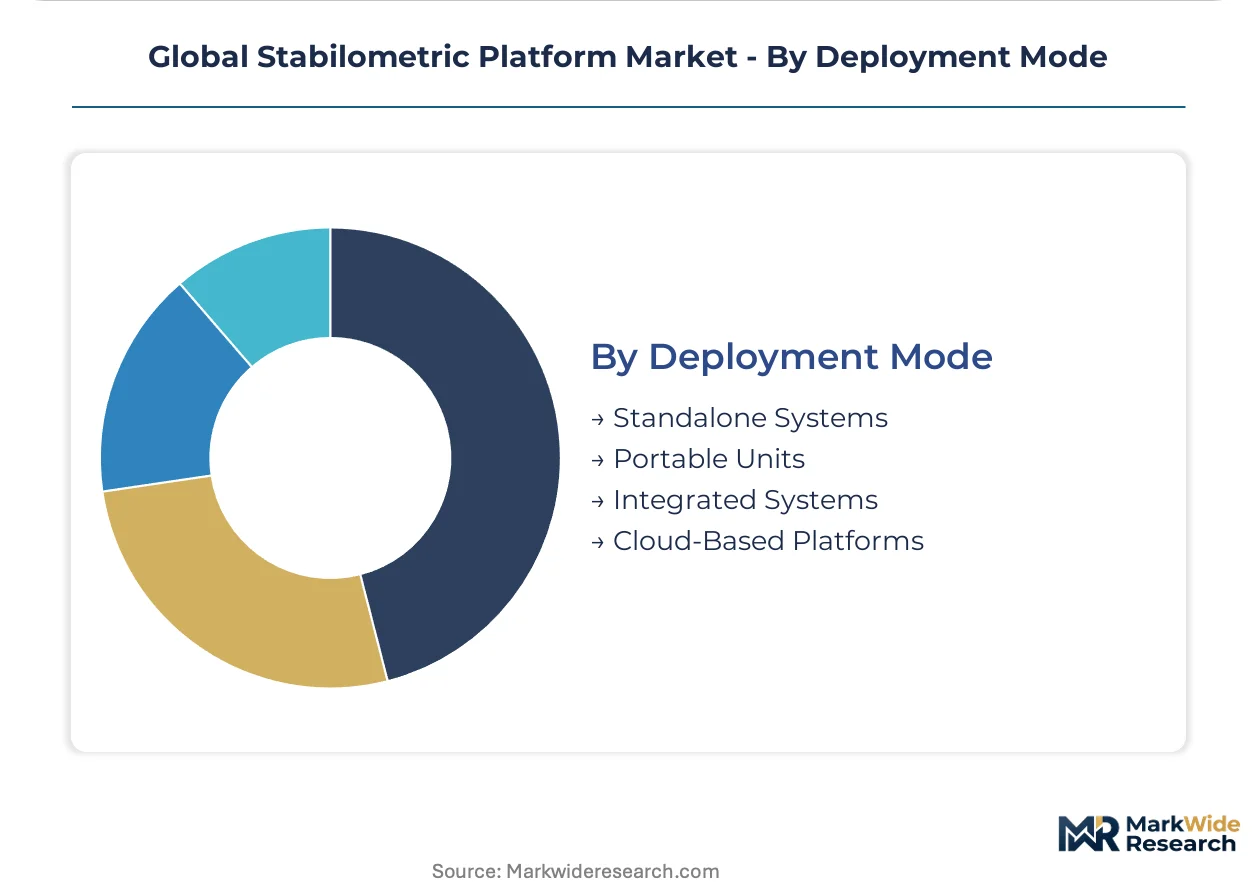
Capital deployment patterns diverge sharply between fixed infrastructure and service-based consumption models. Integrated systems require the most extensive facility modification, while cloud-based platforms shift cost structures from capital to operating expenditure.
- Cloud-Based Platforms:Subscription-based data analytics and remote monitoring capabilities reshape data ownership models across clinical and sports end users. Third-party lessors bundle maintenance, software updates, and calibration services into per-assessment fee structures, concentrating in markets with reimbursement code uncertainty.
- Integrated Systems:HL7 FHIR compatibility demands extend sales cycles as hospital procurement committees require EMR interoperability that legacy platform architectures often lack. Biodex Medical Systems and competitors sustain R&D intensity in these configurations to defend positioning.
- Standalone Systems:Fixed laboratory installations with minimal external connectivity requirements serve established diagnostic workflows.
- Portable Units:Battery-powered configurations enable field deployment with reduced facility infrastructure.
Integrated systems absorb the bulk of installed capacity; cloud-based platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized rehabilitation technology zones in Bavaria and the Kanto region concentrate R&D tax incentives for biomechanical device manufacturers. These incentive structures accelerate prototyping cycles for force plate and hybrid sensor systems. Regulatory harmonization initiatives across Japan's METI and Germany's federal economic zones further deepen manufacturing clusters.
United States
NCAA Division I athletic programs and Veterans Affairs rehabilitation networks drive procurement of portable pressure mat systems. The FDA's 510(k) predicate device framework accelerates clearance timelines for established manufacturers. Boston's medical device corridor hosts concentrated engineering talent for signal processing and cloud-native platform development.
Germany
Professional football academies and statutory health insurance reimbursement for balance assessment sustain demand for laboratory-grade force plates. The EU MDR's unified clinical evidence standards reduce multi-country deployment friction. Precision load cell manufacturing clusters in Baden-Württemberg expose platform assemblers to single-source supply vulnerability.
Japan
PMDA-METI coordination on ISO 13485-aligned standards streamlines neurological rehabilitation device approvals. Aging demographics and government-funded elder care infrastructure expand addressable market for fall risk analysis tools. The Chubu region around Nagoya hosts concentrated biomechanical engineering programs feeding device manufacturers.
France
Post-market clinical follow-up registries mandated by EU MDR elevate procurement criteria toward longitudinal data capabilities. Rehabilitation centers in Lyon and Marseille prioritize suppliers with established PMCF infrastructures. ANSM oversight of Class II medical devices reinforces quality system documentation requirements for balance assessment equipment.
India
National Health Mission funding for government physiotherapy centers creates channel access for cost-optimized pressure mat configurations. CDSCO medical device rules impose registration requirements that favor established quality management systems. Manufacturing zones in Maharashtra and Karnataka attract contract assembly for portable sensor units.
Global Stabilometric Platform Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors defending premium positioning through HL7 FHIR compatibility investments while portable unit assemblers compete on capital efficiency. The vendor base concentrates around three strategic archetypes: European precision manufacturers with captive load cell supply, North American integrated diagnostics platforms, and Italian portable specialists. Dominant competitive moves include backward integration into strain gauge manufacturing and geographic expansion through third-party equipment financing partnerships.
Within the European precision tier, Techno Concept and Zebris Medical occupy positions anchored by regional manufacturing infrastructure. Biodex Medical Systems exemplifies the North American integrated platform archetype, sitting within the diagnostics consolidation orbit of broader medical device portfolios. These three entities represent divergent R&D intensity levels across force plate, hybrid system, and pressure mat configurations.
| Leading Market Players |
|---|
| Techno Concept |
| NeuroCom International (Natus Medical) |
| Biodex Medical Systems |
| HUR Labs |
| Balance Systems Srl |
| Sensor Medica |
| Medicapteurs |
| KINESIQ |
| Zebris Medical |
| Others |
Cost & Logistics Intelligence
EU MDR post-market surveillance mandates and FDA 510(k) documentation requirements are compressing procurement timelines for rehabilitation centers and sports academies, forcing load cell manufacturers in Germany and Japan to prioritize certified suppliers and extend order backlogs for uncertified assemblers.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to force plate systems with ISO 13485-certified load cell arrays, while spot inventory discounts emerge for non-certified pressure mat configurations. Three-tier pricing structure across premium, standard, and economy levels separates hybrid research systems from clinical-grade force plates and portable training units. Cost compression in the entry-level portable segment is intensifying because consumer-grade IMU substitution erodes differentiation. Elder care facilities exhibit the highest price sensitivity due to reimbursement code uncertainty, while research institutes absorb premium positioning for multi-parameter output capabilities.
Supply Chain Analysis
FDA 510(k) and EU MDR quality system certifications gate supplier eligibility for precision strain gauge procurement, concentrating qualified component sources in Germany, Japan, and select Swiss manufacturing zones. Platform assemblers draw from aluminum alloy substrates, silicon strain gauges, and optical encoder arrays as core inputs. Single-source vulnerability in Baden-Württemberg load cell manufacturing exposes assemblers to supply interruption. Distribution runs through authorized medical device distributors with regulatory compliance capabilities, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Stabilometric Platform Market operates as a cost-of-compliance story where EU MDR clinical evidence requirements and FDA 510(k) predicate frameworks erect documentation barriers that reward incumbent manufacturers with established quality infrastructures.
For Market Incumbents: Deepen backward integration into strain gauge manufacturing to mitigate single-source exposure in German and Japanese supply clusters. Fortify post-market clinical follow-up registries to defend positioning against emerging portable specialists lacking longitudinal data capabilities. Expand HL7 FHIR compatibility investments to capture hospital procurement committee requirements that extend sales cycles for legacy architectures.
For New Entrants and Emerging Players: Government-funded physiotherapy centers under India's National Health Mission represent the most penetrable buyer archetype for cost-optimized pressure mat configurations. Cloud-native subscription architectures targeting elder care facilities with per-assessment financing bypass capital purchase barriers in reimbursement-uncertain markets. Prioritize CDSCO registration pathways to establish quality system credibility for contract assembly opportunities in Maharashtra and Karnataka manufacturing zones.
For Investors and Strategic Acquirers: The window for entry favors portable system specialists with cloud-native platform architectures and established third-party equipment financing partnerships. Long-term viability hinges on differentiation through real-time kinematic feedback capabilities rather than retrospective diagnostic positioning. Watch for FDA 510(k) clearance acceleration timelines as an inflection indicator for incumbent margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Quality System Certification | Unlocks supplier eligibility for precision load cell procurement in German and Japanese manufacturing clusters. |
| Cloud-Native Platform Development | Enables subscription-based remote monitoring capabilities for elder care facilities seeking reduced capital deployment. |
| HL7 FHIR EMR Integration | Satisfies hospital procurement committee requirements that legacy platform architectures often lack. |
| Post-Market Clinical Follow-Up Infrastructure | Addresses EU MDR surveillance mandates that rehabilitation centers in France and Italy prioritize in supplier selection. |
| Third-Party Equipment Financing Partnerships | Captures outpatient clinic demand in the United States where reimbursement uncertainty discourages outright ownership. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and rehabilitation center procurement leads. FDA 510(k) clearance databases, EU MDR notified body certificates, CMS Medicare reimbursement code schedules, and Japan PMDA medical device registrations provided structured validation points. Bottom-up unit economics triangulated against top-down market sizing across product type, application, end user, and deployment mode dimensions.
Granularity-level modeling addressed force plate, hybrid system, pressure mat, inertial sensor, and optical sensor configurations at the product level, with parallel segmentation across sports training, neurological rehabilitation, balance assessment, fall risk analysis, and ergonomic evaluation applications. CAGRs were derived from installed base evolution and replacement cycle analysis, incorporating sensor fusion technology adoption curves and cloud platform subscription conversion rates as industry-specific forecast inputs.
Revisions become necessary when FDA 510(k) predicate device frameworks materially shift, EU MDR post-market surveillance requirements expand, or load cell supply concentration in Germany and Japan disrupts component availability. A model refresh is warranted upon material change in reimbursement code coverage for balance assessment in geriatric care.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Foot Suction Unit Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Allografts Market
Medical Devices
Bone Allografts Market