
 India Spinal Fusion Devices Market | 2026-2036
India Spinal Fusion Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Spinal Fusion Devices Market Foresight
Private hospital chains in Tier-II cities are redrawing procurement patterns for spinal fusion hardware. Medtronic PLC leverages its extensive distributor network across India's secondary cities to sustain implant availability where local supply chains remain fragmented. Johnson & Johnson (DePuy Synthes) anchors its position through training partnerships with regional surgical societies, while Zimmer Biomet Holdings Inc competes on modular pedicle screw systems tailored to cost-sensitive institutional buyers. Matrix Meditec Pvt Ltd differentiates through domestically manufactured titanium cages that navigate import duty structures favoring local production.
Spinal fusion devices encompass interbody cages, pedicle screws, plates, and bone graft substitutes engineered to stabilize vertebral segments and promote osseointegration, with titanium and polyetheretherketone dominating material selection due to biocompatibility and radiolucency properties. The devices serve to immobilize motion segments, correct deformity, and decompress neural elements in degenerative, traumatic, and oncologic pathologies. Pedicle screw systems generate the deepest margin pools given their reusable instrumentation and premium pricing, while minimally invasive technology is expanding fastest as surgical training curricula shift toward percutaneous approaches. Robotics-assisted placement, though nascent, concentrates in metro academic centers where capital equipment budgets and surgeon learning curves align.
CDSCO's Medical Device Rules framework mandates registration and quality management system compliance for all spinal implant manufacturers, raising barriers for unnotified foreign suppliers. BIS certification for stainless steel and titanium alloys shapes raw material sourcing decisions, while the PLI scheme for medical devices incentivizes domestic production of high-value orthopedic implants. Stakeholders must monitor how state-level health insurance expansions alter reimbursement-driven site-of-care shifts between public tertiary hospitals and private surgical centers.
Market Dynamics
The CDSCO's tightened Medical Device Rules framework is compressing competitive timelines while the PLI scheme for medical devices pulls manufacturing capacity toward domestic titanium implant production.
Growth Catalysts
- State-level health insurance expansion:Maharashtra, Karnataka, and Tamil Nadu are extending surgical coverage to Tier-II city populations, routing spinal fusion volume toward private surgical centers outside metropolitan cores.
- Patient-specific 3D-printed titanium implants:Additive manufacturing is collapsing lead times for complex deformity cases while matching anatomical geometry that off-the-shelf cages cannot address.
- Minimally invasive percutaneous approaches:Surgical training curricula at regional medical colleges are reorienting toward MIS techniques, expanding addressable patient pools beyond academic hospital catchments.
Market Restraints
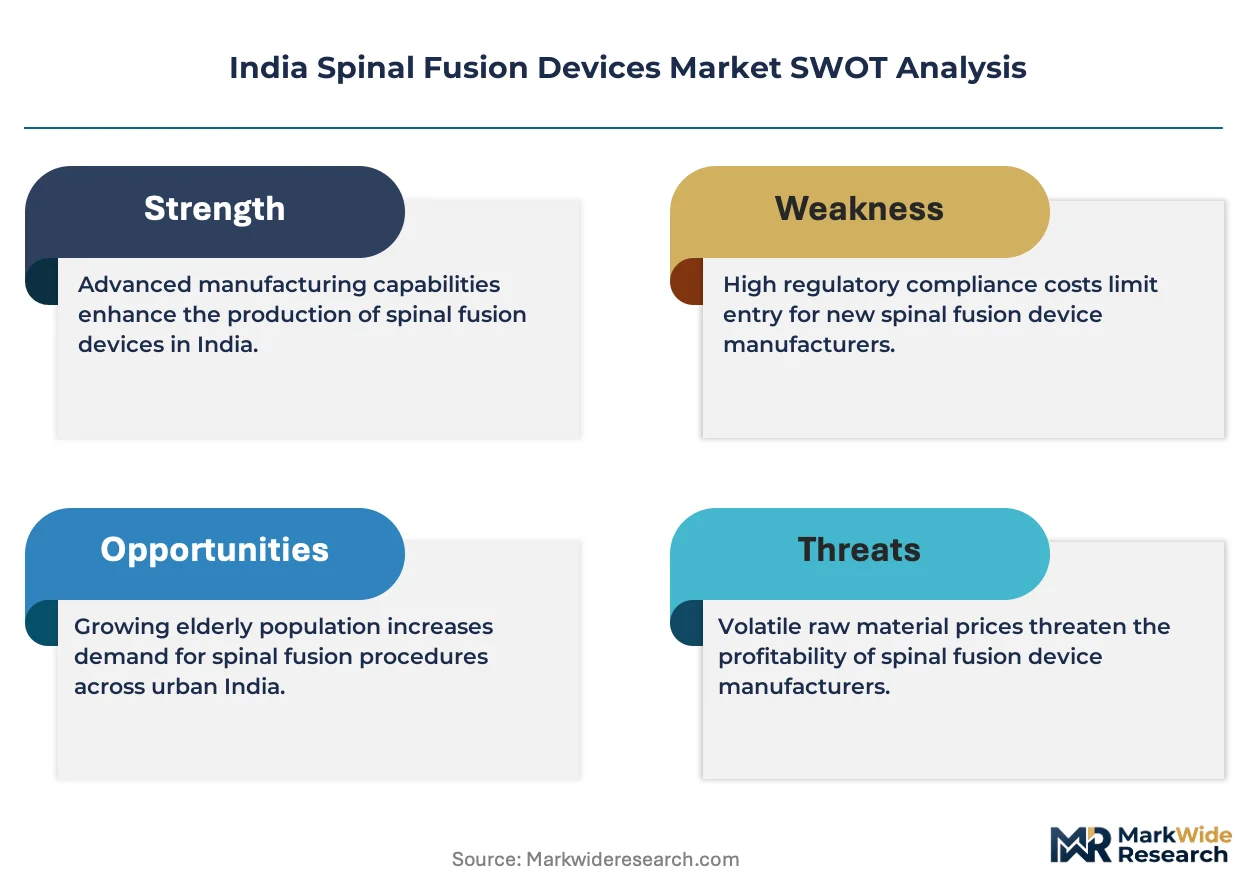
- Import duty structures on polyetheretherketone:PEEK interbody cages face elevated landed costs versus domestically manufactured titanium alternatives, distorting material selection in cost-constrained procurement.
- Capital equipment concentration:Robotics-assisted placement systems remain tethered to metro academic centers where equipment budgets and surgeon learning curves align, capping penetration.
- BIS certification timelines:Stainless steel and titanium alloy raw material approvals stretch 12-18 months, freezing sourcing flexibility for domestic manufacturers.
Strategic Opportunities
- Tier-III city hospital networks:Procedural access gaps in Uttar Pradesh, Rajasthan, and Madhya Pradesh present first-mover terrain for distributor partnerships and mobile C-arm leasing models.
- Modular pedicle screw system standardization:Cost-sensitive institutional buyers are consolidating vendor lists around interoperable instrumentation platforms that reduce inventory carrying costs.
- CDSCO quality management system mandates:Registration requirements for unnotified foreign suppliers are clearing competitive space for compliant domestic manufacturers with established QMS infrastructure.
Industry Challenges
- Surgeon training pipeline gaps:Fellowship-trained spine specialists cluster in Maharashtra and Karnataka, leaving Tier-II city hospitals dependent on visiting surgeon models with inconsistent case volumes.
- Reusable instrumentation sterilization protocols:Pedicle screw system trays require dedicated CSSD infrastructure that many secondary city facilities lack, forcing capital outlays or third-party service contracts.
- Osseointegration evidence generation:Domestic titanium cage manufacturers face compressed timelines to compile clinical data packages that satisfy CDSCO renewal requirements and hospital tender specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Spinal Fusion Devices Market |
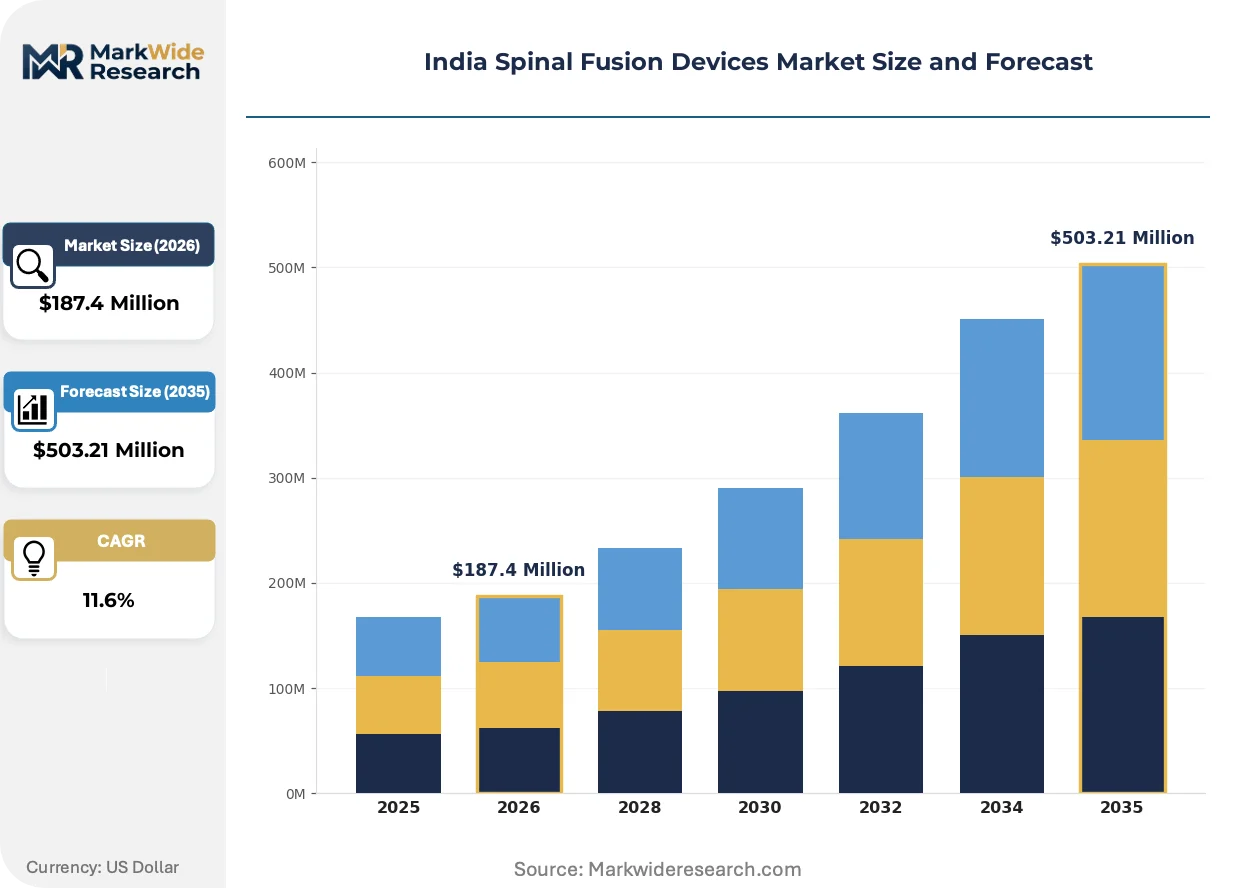
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interbody Cages, Pedicle Screws, Plates, Bone Grafts Material: Titanium, Polyetheretherketone, Stainless Steel, Composite Materials End User: Hospitals, Outpatient Surgical Centers, Specialty Clinics, Rehabilitation Centers Technology: Traditional, Minimally Invasive, Robotics, 3D Printing |
| Companies Covered | Medtronic PLC, Johnson & Johnson (DePuy Synthes), Globus Medical Inc, Stryker Corporation, Zimmer Biomet Holdings Inc, Matrix Meditec Pvt Ltd, Auxein Medical Pvt Ltd, S H Pitkar Orthotools Pvt Ltd, Bonetech Medisys Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Spinal Fusion Devices Market Shifts & Advancements
Spinal fusion hardware is pivoting toward personalization and percutaneous delivery, with regulatory quality mandates and procurement consolidation acting as simultaneous accelerants and filters.
Additive manufacturing of patient-specific titanium interbody cages is decomposing the traditional off-the-shelf inventory model. Tier-II city spine surgery centers are adopting these implants for complex deformity cases where standard geometries fail. The technology is compressing surgical planning cycles while elevating the competitive threshold to include in-house 3D modeling capabilities.
CDSCO's Medical Device Rules framework is mandating registration and quality management system compliance for all spinal implant manufacturers. This regulatory friction is elevating barriers for unnotified foreign suppliers while creating procurement preference for domestic entities with established QMS infrastructure. Maharashtra and Karnataka hospital chains are consolidating vendor lists around compliant manufacturers ahead of enforcement deadlines.
Institutional procurement patterns are rotating toward bundled pricing for pedicle screw systems with reusable instrumentation. Private hospital chains in Tamil Nadu are displacing transactional implant purchasing with multi-year vendor partnerships that include training and inventory management. This consolidation is most visible in dedicated spine surgery centers where case volumes justify standardization around single-platform instrumentation.
India Spinal Fusion Devices Market Segmentation
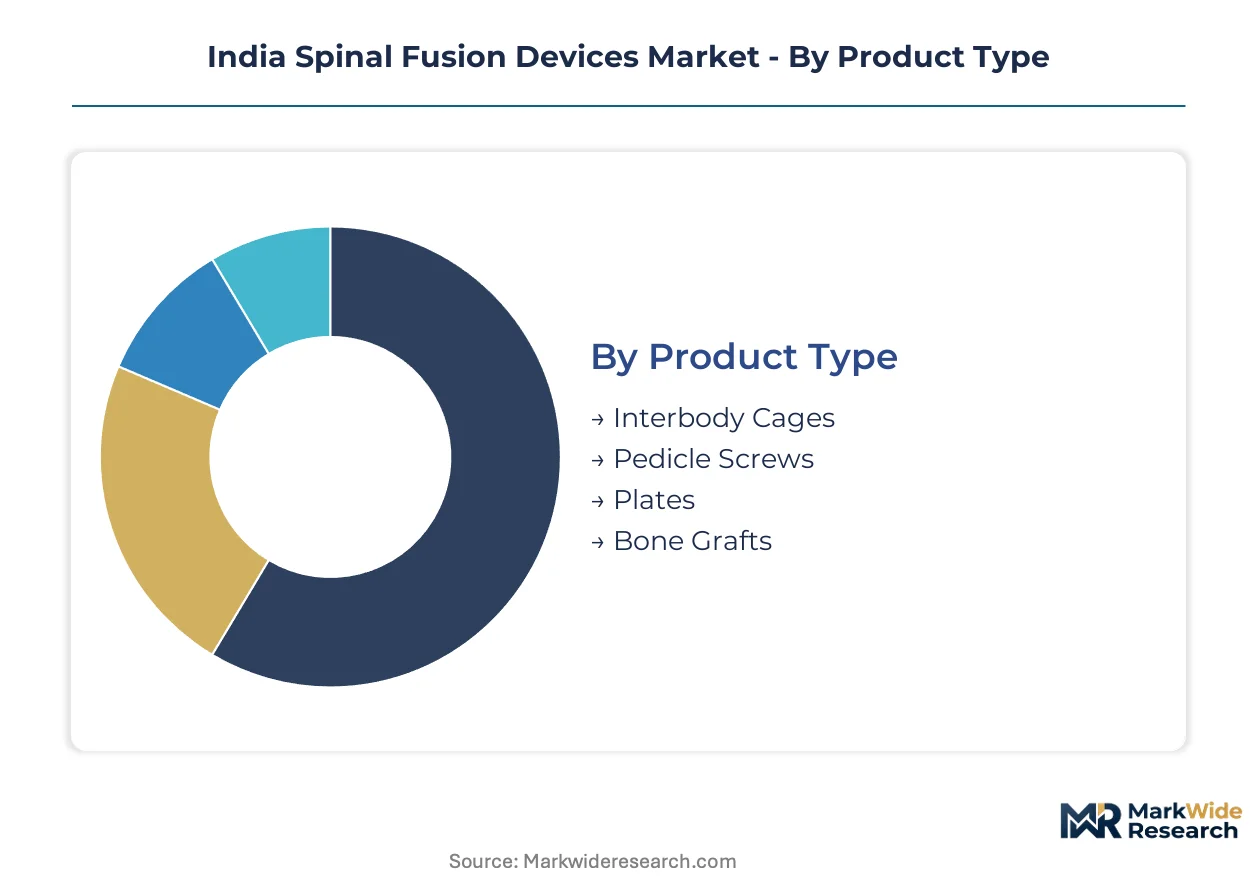
Spinal fusion device procurement in India fragments across material preferences, procedural settings, and technological sophistication tiers. Understanding these divides reveals where domestic manufacturing incentives intersect with import dependency and where minimally invasive adoption outpaces traditional approaches.
Product Type:
Pedicle screw systems and interbody cages dominate domestic production conversations, while plates and bone grafts retain heavier import exposure.
- Pedicle Screws:Modular titanium constructs with polyaxial heads and cannulated designs enable percutaneous placement. Maharashtra and Karnataka hospital chains are consolidating vendor lists around interoperable instrumentation platforms that reduce CSSD overhead and inventory carrying costs.
- Interbody Cages:Titanium and PEEK constructs restore disc height and lordosis while promoting fusion. Tamil Nadu spine surgery centers are driving volume toward patient-specific 3D-printed titanium geometries that match anatomical deformities off-the-shelf cages cannot address.
- Plates:Anterior cervical and thoracolumbar plating systems stabilize anterior column constructs. These devices face concentrated demand in trauma cases at tertiary public hospitals.
- Bone Grafts:Allograft, autograft, and synthetic osteoconductive materials supplement mechanical fixation. Procurement concentrates around demineralized bone matrix and ceramic composites.
Pedicle screws hold the largest share; momentum sits with interbody cages as additive manufacturing collapses lead times for complex deformity cases.
Material:
Cost-tier differentiation separates premium titanium from economy stainless steel alternatives, with PEEK occupying a mid-tier position distorted by import duty structures.
- Titanium:Grade 5 Ti-6Al-4V alloys dominate interbody cages and pedicle screws due to strength-to-weight ratios and osseointegration properties. CDSCO quality management system mandates and PLI scheme incentives are pulling manufacturing capacity toward domestic titanium implant production.
- Polyetheretherketone:Radiolucent polymer cages permit postoperative imaging without artifact. Elevated landed costs versus domestically manufactured titanium alternatives distort material selection in cost-constrained procurement at Tier-II city hospitals.
- Stainless Steel:316L surgical grade retains presence in legacy plating systems and budget instrumentation. BIS certification timelines for raw material approvals stretch sourcing flexibility.
- Composite Materials:Carbon fiber-reinforced PEEK and bioabsorbable polymers address niche radiolucency and stress-shielding requirements. Adoption remains limited to academic centers with research budgets.
Titanium commands the largest share; PEEK is climbing the fastest as imaging protocol standardization elevates radiolucency requirements.
End User:
Volume concentration sits with hospital chains, while site-of-care shifts are routing cases toward outpatient surgical centers where reimbursement and capital equipment alignment permits.
- Hospitals:Tertiary public institutions and private hospital chains in Maharashtra, Karnataka, and Tamil Nadu generate the deepest procedural volumes. Dedicated spine surgery centers within these networks are standardizing around single-platform instrumentation to reduce per-case costs.
- Outpatient Surgical Centers:Ambulatory settings with dedicated C-arm and anesthesia capabilities are capturing select lumbar fusion cases. State-level health insurance expansions are extending surgical coverage to Tier-II city populations, routing volume toward these facilities.
- Specialty Clinics:Orthopedic and neurosurgical group practices concentrate preoperative planning and postoperative rehabilitation. These settings drive demand for patient-specific 3D-printed implants requiring in-house modeling capabilities.
- Rehabilitation Centers:Post-fusion physiotherapy and pain management extend the care continuum. Device selection here influences hardware durability requirements for active patient populations.
Hospitals retain the largest share; outpatient surgical centers are gaining share fastest as minimally invasive techniques compress length-of-stay metrics.
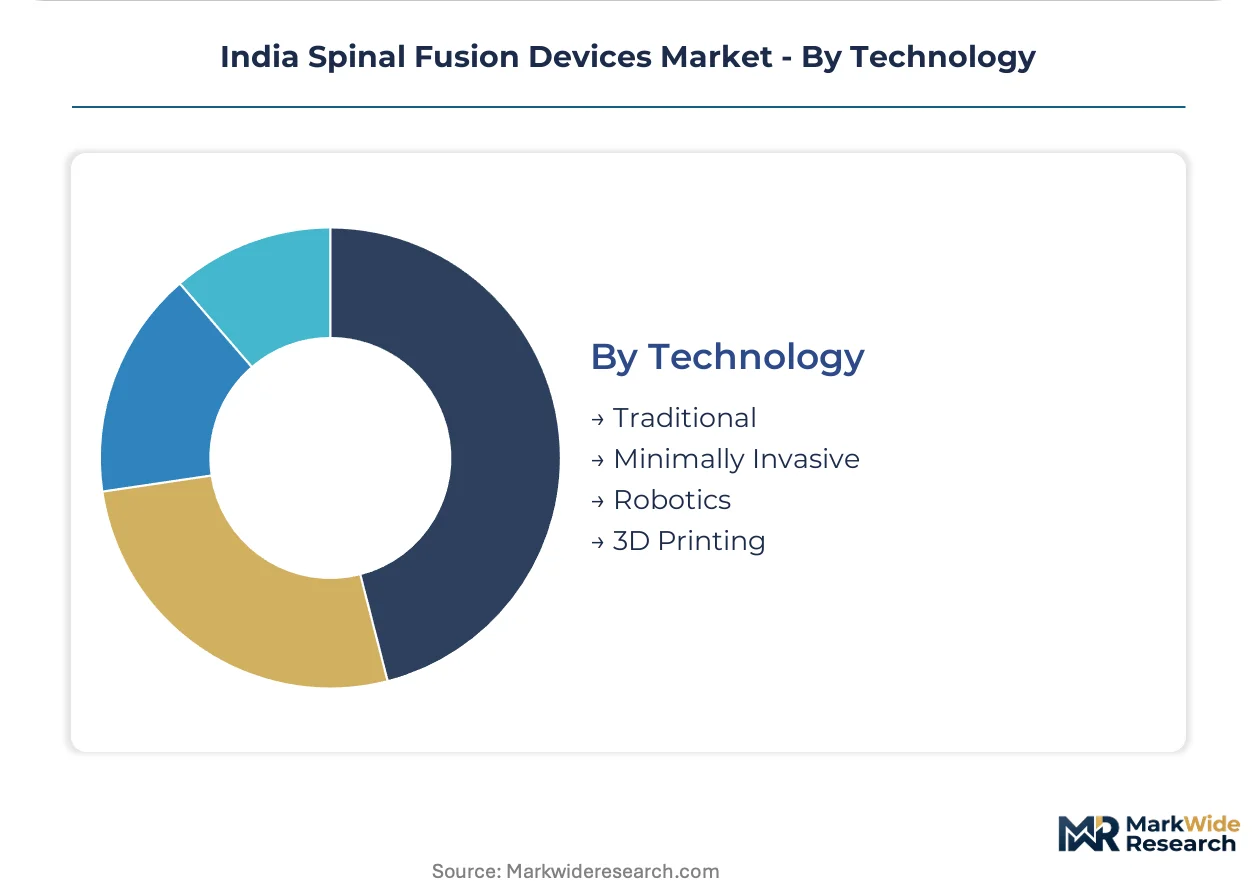
Technology:
Maturity gradients separate established traditional approaches from capital-intensive robotics, with minimally invasive techniques occupying the steepest adoption trajectory.
- Traditional:Open posterior approaches with direct visualization remain the training baseline at regional medical colleges. These procedures sustain demand for reusable pedicle screw instrumentation trays.
- Minimally Invasive:Percutaneous pedicle screw placement and lateral interbody fusion reduce soft tissue disruption. Surgical training curricula at regional medical colleges are reorienting toward MIS techniques, expanding addressable patient pools beyond academic hospital catchments.
- Robotics:Navigation-assisted placement systems concentrate in metro academic centers where equipment budgets and surgeon learning curves align. Capital equipment concentration caps penetration outside Mumbai, Bengaluru, and Chennai.
- 3D Printing:Additive manufacturing of patient-specific titanium cages collapses surgical planning cycles. Tier-II city spine surgery centers are adopting these implants for complex deformity cases where standard geometries fail.
Traditional approaches hold the largest share; minimally invasive techniques are expanding most quickly as training curricula shift and equipment costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dedicated Freight Corridor and Golden Quadrilateral highway network underwrite India's spinal device distribution topology, routing implant shipments from manufacturing clusters in Gujarat and Maharashtra toward surgical centers across the peninsula.
Maharashtra
Mumbai-Pune corridor hospitals generate the deepest procedural volumes for degenerative spine cases. CDSCO's Medical Device Rules enforcement concentrates compliance audits in this state, accelerating vendor consolidation among registered manufacturers. Nagpur and Nashik are emerging as Tier-II surgical hubs where private hospital chains are scaling dedicated spine centers.
Karnataka
Bengaluru's medical device manufacturing zone anchors domestic titanium implant production under PLI scheme incentives. The state's health insurance expansion under Arogya Karnataka routes fusion volume toward private surgical centers in Mysuru and Mangaluru. Manipal and Narayana Health networks are standardizing instrumentation platforms across their secondary city affiliates.
Tamil Nadu
Chennai's orthopedic device cluster supplies pedicle screw systems to hospital chains throughout South India. State-level surgical coverage expansion under the Chief Minister's Comprehensive Health Insurance Scheme is capturing lumbar fusion cases previously untreated. Coimbatore and Madurai are developing dedicated spine surgery centers with visiting surgeon models.
Telangana
Hyderabad's life sciences corridor is attracting contract manufacturers for 3D-printed titanium cage production. The Telangana State Medical Services Corporation's centralized procurement is consolidating vendor lists around CDSCO-registered suppliers. Warangal and Karimnagar represent procedural access gaps where mobile C-arm leasing models are penetrating.
Gujarat
Special economic zones in Ahmedabad and Vadodara host titanium alloy processing facilities serving implant manufacturers nationwide. DGFT's export promotion schemes for medical devices are positioning Gujarat as a production base for re-export to South Asian markets. Surat and Rajkot hospitals are expanding orthopedic departments with state health mission funding.
India Spinal Fusion Devices Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance and distributor depth. The market structure tiers into multinational corporations with established QMS infrastructure, mid-scale domestic manufacturers leveraging PLI incentives, and regional fabricators serving cost-constrained procurement. Three archetypes dominate: CDSCO-registered multinationals with training partnerships, PLI-beneficiary domestic titanium producers, and unnotified foreign suppliers facing registration barriers. Competitive moves concentrate on distributor network expansion into Tier-II cities and modular instrumentation platform standardization.
Within the multinational tier, Medtronic PLC and Johnson & Johnson occupy positions defined by extensive secondary city distribution networks and surgical society training partnerships. Zimmer Biomet Holdings Inc represents the modular instrumentation archetype, while domestic specialists Matrix Meditec Pvt Ltd exemplify PLI-leveraged local manufacturing. These anchors illustrate how regulatory compliance and production geography are reshaping vendor selection criteria for hospital procurement committees.
| Leading Market Players |
|---|
| Medtronic PLC |
| Johnson & Johnson (DePuy Synthes) |
| Globus Medical Inc |
| Stryker Corporation |
| Zimmer Biomet Holdings Inc |
| Matrix Meditec Pvt Ltd |
| Auxein Medical Pvt Ltd |
| S H Pitkar Orthotools Pvt Ltd |
| Bonetech Medisys Pvt Ltd |
| Others |
Supply & Pricing Matrix
Multi-year instrumentation partnership contracts lock in both supply access and price visibility for private hospital chains navigating CDSCO registration requirements and PLI scheme incentives. These arrangements bundle reusable pedicle screw systems with training and inventory management, compressing transactional purchasing into consolidated vendor relationships that stabilize procurement costs across Maharashtra and Karnataka.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CDSCO-registered multinational systems from PLI-beneficiary domestic titanium cages and unnotified import alternatives. Price differentiation hinges on quality management system certification grade and after-sales service bundling, with cost compression in the economy tier intensifying as state health insurance expansions tighten reimbursement ceilings. Tier-II city hospitals exhibit the highest price sensitivity, while dedicated spine surgery centers in metro academic hubs prioritize interoperability over unit cost.
Supply Chain Analysis
India and China anchor raw titanium alloy processing and PEEK polymer feedstock production for spinal implant manufacturers. Domestic supply chains draw from Gujarat special economic zones for Ti-6Al-4V alloy fabrication and Maharashtra precision machining clusters, while PEEK resin imports rest on Chinese petrochemical output. Single-source vulnerability concentrates in BIS-certified stainless steel approvals, where 12-18 month certification timelines freeze sourcing flexibility. Distribution runs through distributor networks penetrating Tier-II cities, with hospital chain consolidation shifting volume toward direct manufacturer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India spinal fusion devices market sits in a cyclical recovery phase as state-level health insurance expansions route surgical volume toward private centers and CDSCO enforcement clears competitive space for compliant domestic manufacturers.
For Market Incumbents: Consolidate vendor relationships around interoperable pedicle screw platforms that reduce CSSD overhead and inventory carrying costs for hospital chains standardizing instrumentation. Deepen backward integration into titanium alloy processing within Gujarat special economic zones to capture PLI scheme incentives and insulate margin structures from import duty volatility on PEEK polymers. Defend against emerging domestic manufacturers by accelerating CDSCO renewal timelines and expanding training partnerships with regional surgical societies in Tier-II cities.
For New Entrants and Emerging Players: Anchor in Tier-III city hospital networks across Uttar Pradesh, Rajasthan, and Madhya Pradesh where procedural access gaps persist and mobile C-arm leasing models can substitute capital equipment deficits. Target patient-specific 3D-printed titanium cage production for complex deformity cases, leveraging Hyderabad's life sciences corridor contract manufacturing infrastructure to collapse lead times against off-the-shelf inventory models. Penetrate through distributor partnerships offering bundled instrumentation and surgeon training rather than transactional implant sales.
For Investors and Strategic Acquirers: Capital is best deployed toward PLI-beneficiary domestic titanium implant manufacturers with established CDSCO quality management system infrastructure and proven hospital chain procurement relationships. Long-term viability over the next decade hinges on consolidation readiness as vendor list standardization accelerates and registration barriers eliminate unnotified foreign competition. Monitor state health insurance reimbursement rate announcements as the critical inflection signal for volume shifts between public tertiary hospitals and private surgical centers.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Pathway | Quality management system compliance clears competitive space ahead of enforcement deadlines. |
| Hospital System Partnership | Multi-year vendor relationships with Manipal and Narayana Health networks consolidate procurement volume. |
| Backward Integration into Titanium Processing | Gujarat SEZ-based alloy fabrication captures PLI incentives and reduces import dependency. |
| Patient-Specific 3D Printing Capability | Additive manufacturing for complex deformity cases collapses surgical planning cycles. |
| Reimbursement Strategy | Alignment with Arogya Karnataka and Chief Minister's Comprehensive Health Insurance Scheme routing decisions. |
Research Methodology
Operator-level perspectives from spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through CDSCO registration databases, state health insurance scheme procurement records, PLI scheme beneficiary disclosures, and hospital tender documentation. Bottom-up demand modeling across product type, material, end user, technology, and state-level geography triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested forecast robustness across alternative scenarios for CDSCO enforcement timing, PLI scheme extension decisions, and state health insurance reimbursement rate adjustments. The analytical framework segmented volume and value projections across pedicle screw systems, interbody cages, plates, and bone graft substitutes by titanium, PEEK, and stainless steel material tiers, with end-user splits between hospitals and outpatient surgical centers. CAGRs were derived from surgical volume growth trajectories, implant intensity per procedure, and pricing elasticity assumptions calibrated to insurance expansion patterns.
Underlying assumptions cover CDSCO registration compliance timelines, PLI scheme incentive continuity, and state health insurance coverage expansion rates, with deviation risk concentrated in BIS certification delays for raw material approvals and surgeon training pipeline bottlenecks in Tier-II cities. Recalibration cycles align with material shifts in regulatory enforcement intensity, reimbursement policy announcements, and additive manufacturing technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Rectal Catheters Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Battery-Operated Lactate Meter Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Cholecystectomy Devices Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Smart Mask Market
Medical Devices
Global Canes and Crutches Market