
 Global Bipolar Electrosurgical Devices Market | 2026-2036
Global Bipolar Electrosurgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bipolar Electrosurgical Devices Market Foresight
A shortage of certified biomedical engineers with electrosurgical system expertise is bifurcating the competitive landscape into premium service-integrated suppliers and commoditized hardware vendors. Medtronic leverages its vertically integrated training infrastructure to lock in hospital system contracts across North America. Johnson & Johnson sustains brand loyalty through specialized clinical education programs that reduce operative complications. Erbe Elektromedizin anchors its position in European university hospitals with precision-manufactured generator platforms.
Bipolar electrosurgical devices deliver controlled radiofrequency current between two electrodes at the instrument tip, enabling tissue coagulation and dissection with minimal thermal spread to adjacent structures. These instruments serve primarily in open and laparoscopic procedures where precise hemostasis protects critical anatomical structures. Forceps and scissors product categories command the deepest installed base, though bipolar combination devices capture expanding margin pools as surgeons seek instrument versatility. Radiofrequency technology leads procedure volume, while ultrasonic platforms compete in specialized dissection applications where reduced smoke plume matters.
FDA 510(k) pathways govern device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for reusable bipolar instruments. ISO 13485 quality management certification functions as a baseline market-access filter across all major jurisdictions. Procurement teams must weigh total cost-of-ownership against reprocessing validation burdens as single-use bipolar accessories gain traction in ambulatory settings.
Market Dynamics
Hospital procurement consolidation and the EU MDR's clinical evidence requirements are compressing vendor margins while accelerating single-use instrument adoption in ambulatory surgical centers.
Growth Catalysts
- Laparoscopic procedure volume expansion:Rising volumes of minimally invasive surgeries in tertiary care facilities create sustained pull for precision hemostasis instruments with controlled thermal spread profiles.
- MDR compliance deadlines:European Union Medical Device Regulation transition periods are forcing hospital systems to refresh instrument inventories, opening replacement cycles for certified suppliers.
- Radiofrequency generator platform upgrades:Electrosurgical system manufacturers are bundling intelligent energy modulation algorithms that reduce tissue adherence and operative time.
Market Restraints
- Copper and precious metal input volatility:Electrode manufacturing depends on conductive alloys whose price swings compress hardware margins unpredictably.
- Reprocessing validation burden:Reusable bipolar forceps require ISO 17664-compliant cleaning protocols that extend turnaround times and elevate labor costs in central sterile departments.
- Ultrasonic dissection substitution:Harmonic scalpel platforms compete in vessel sealing applications where smoke evacuation constraints favor non-electrical energy sources.
Strategic Opportunities
- Brazilian private hospital expansion:São Paulo's surgical center construction boom creates demand for mid-tier electrosurgical systems with localized voltage standards.
- Intelligent instrument connectivity:RFID-enabled bipolar devices that log usage cycles and performance metrics align with emerging digital surgery platforms.
- Japan's aging surgeon workforce:Ergonomic pistol-grip designs with reduced activation force target proceduralists facing repetitive strain limitations.
Industry Challenges
- Biomedical engineer certification scarcity:Electrosurgical system troubleshooting requires specialized competencies that training programs produce insufficiently across North American hospital networks.
- FDA 510(k) predicate device drift:Substantial equivalence pathways narrow as legacy predicate instruments exit the market, extending clearance timelines for novel tip geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bipolar Electrosurgical Devices Market |
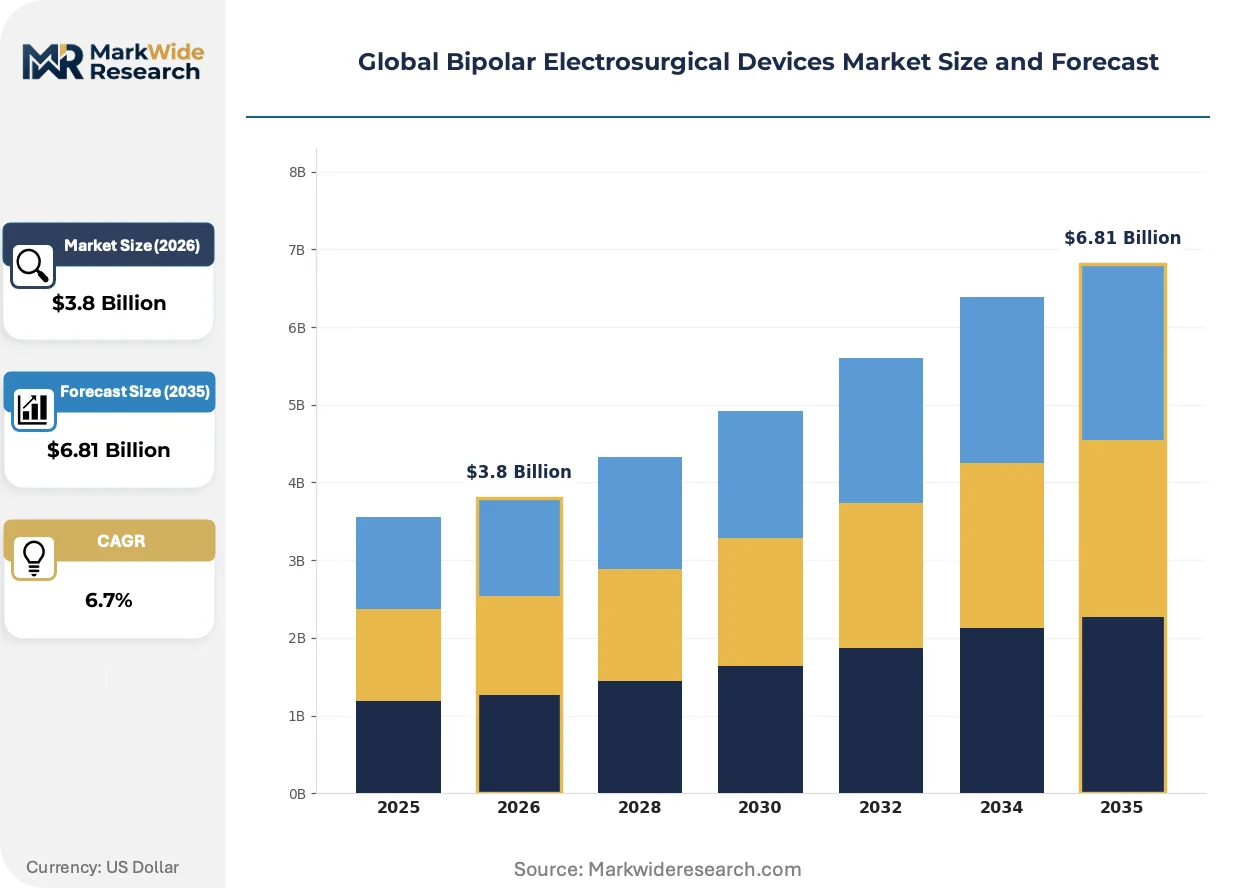
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forceps, Scissors, Bipolar Combination Devices, Bipolar Accessories Technology: Radiofrequency, Ultrasonic, Laser, Microwave, Plasma Application: Gynecology, Neurosurgery, Urology, General Surgery, ENT, Plastic Surgery End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Centers, Specialty Clinics |
| Companies Covered | Medtronic, Johnson & Johnson, B. Braun, Olympus, ConMed, Stryker, Boston Scientific, Applied Medical, Erbe Elektromedizin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bipolar Electrosurgical Devices Market Shifts & Advancements
Energy delivery platforms are converging with digital surgery ecosystems, creating instrument intelligence layers that reshape how hospitals evaluate total cost of ownership beyond hardware acquisition.
Advanced ceramic insulation coatings on bipolar instrument shafts are miniaturizing thermal profiles while maintaining dielectric strength. Academic medical centers in Germany and the United States are piloting these platforms for pediatric and neural applications where millimeter precision governs safety margins. The technology is miniaturizing access port requirements, enabling single-incision laparoscopy that compresses recovery timelines and facility length-of-stay metrics.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data for reusable Class IIa instruments. Manufacturers must now maintain vigilance systems that capture adverse event patterns across distributed hospital fleets. High-volume reusable forceps categories face disproportionate documentation burdens, accelerating portfolio shifts toward validated single-use alternatives with embedded traceability features.
Hospital supply chain directors are unbundling service contracts from capital equipment purchases, forcing generator manufacturers to compete on discrete maintenance event pricing. Integrated delivery networks in the United States now tender electrosurgical platforms through group purchasing organizations that weight reprocessing labor costs heavily in total cost models. This recalibration favors vendors with transparent parts pricing and remote diagnostic capabilities that reduce field service dispatch frequency.
Global Bipolar Electrosurgical Devices Market Segmentation
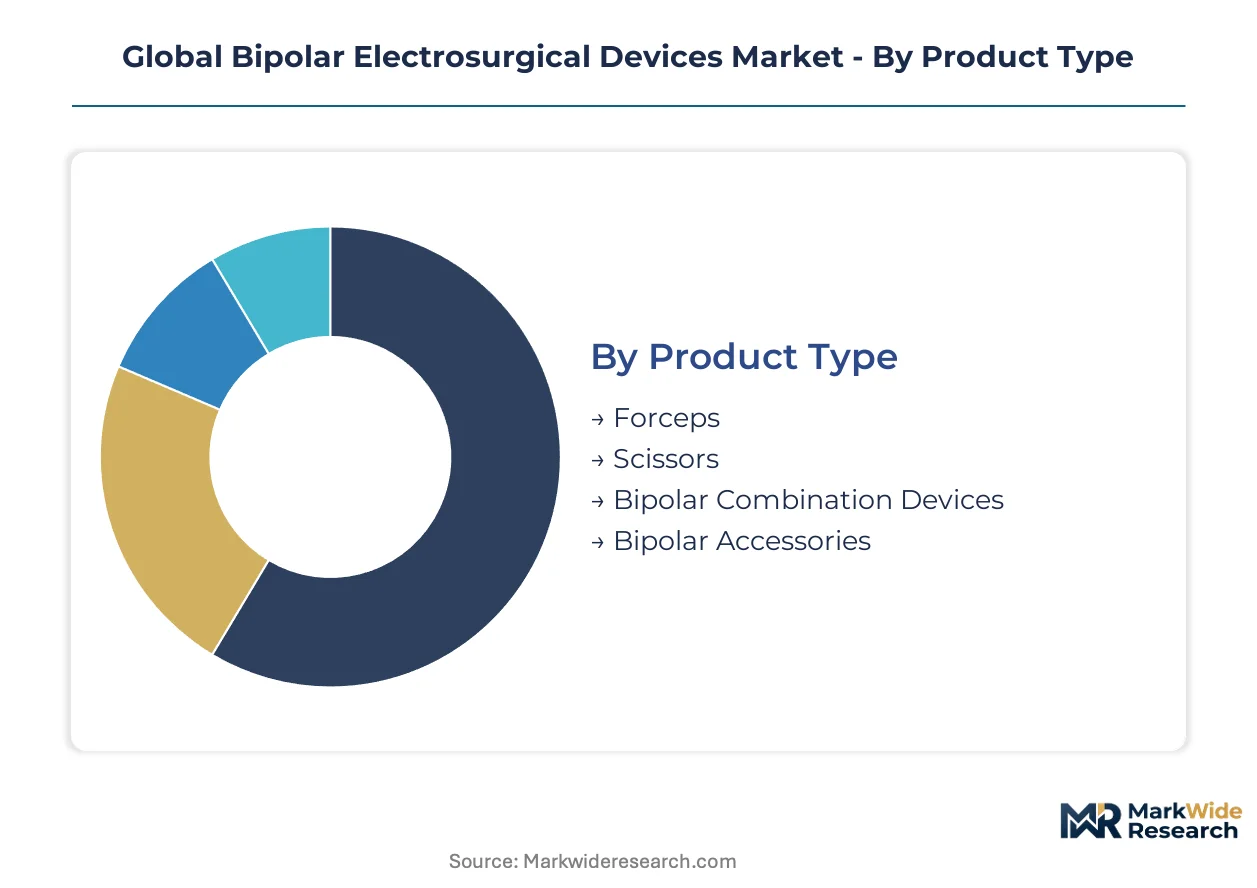
Electrosurgical device procurement varies sharply by clinical setting and procedure type, with hospital capital budgets, ambulatory reprocessing constraints, and specialty-specific energy requirements creating distinct demand pockets. Manufacturers configure product portfolios around these fracture lines to capture recurring accessory revenue and lock in generator platform placements.
Product Type:
Forceps and scissors categories dominate domestic hospital procurement in Germany and the United States, while bipolar combination devices find stronger export traction into Latin American and Southeast Asian markets seeking instrument versatility.
- Forceps:Twin-electrode jaw designs deliver controlled coagulation across vessel diameters up to 7mm. Demand concentrates in United States tertiary care centers where reusable instrument reprocessing infrastructure justifies premium stainless-steel construction.
- Scissors:Integrated cutting and coagulation blades reduce instrument exchanges during laparoscopic dissection. German university hospitals drive specification standards for ceramic-insulated shafts that minimize thermal spread in neural applications.
- Bipolar Combination Devices:Multi-functional platforms serving grasping, cutting, and coagulation in single instruments. Strong uptake in Brazilian and Mexican private surgical centers with limited sterilization capacity.
- Bipolar Accessories:Footswitches, cables, and patient return electrodes. Disposable configurations gain share in United Kingdom ambulatory settings where MDR documentation burdens weigh against reusable validation.
Forceps holds the largest share; momentum sits with Bipolar Combination Devices.
Technology:
Radiofrequency platforms command the deepest installed base and lowest per-procedure energy cost, while ultrasonic and advanced modalities capture premium positioning in smoke-sensitive environments.
- Radiofrequency:Oscillating current between 300kHz and 1MHz enables tissue resistance-dependent heating. United States hospital systems standardize on intelligent generator platforms with tissue response algorithms.
- Ultrasonic:Mechanical vibration at 55kHz produces frictional heat with minimal smoke plume. Japan's aging surgeon workforce drives demand for reduced-activation-force handpieces in extended procedures.
- Laser:Coherent light energy for precision microsurgical applications. Limited deployment to specialized ENT and ophthalmic centers in Switzerland and France.
- Microwave:Electromagnetic field heating for rapid bulk tissue ablation. Experimental adoption in Chinese liver resection programs.
- Plasma:Ionized gas-mediated energy transfer at low temperatures. Niche positioning in South Korean cosmetic surgery clinics for superficial tissue modification.
Radiofrequency maintains volume leadership; ultrasonic platforms are climbing the fastest on smoke evacuation advantages.
Application:
Procedure reimbursement rates and complication liability exposure shape technology selection across surgical specialties, with gynecology and general surgery driving highest instrument utilization intensity.
- Gynecology:Hysterectomy and myomectomy procedures demand reliable vessel sealing through vascular pedicles. United States bundled payment programs incentivize reduced operative time through advanced bipolar platforms.
- General Surgery:Cholecystectomy and colectomy volumes sustain broad forceps demand. German outpatient surgery expansion shifts volume toward single-use instrument configurations.
- Neurosurgery:Millimeter-precision requirements favor ceramic-insulated instruments with thermal spread under 2mm. Swiss and United States academic centers set specification benchmarks.
- Urology:Prostatectomy and nephrectomy procedures. Robotic surgical system integration drives specialized instrument compatibility requirements.
- ENT:Tonsillectomy and sinus surgery applications. Smoke evacuation constraints favor ultrasonic alternatives in pediatric settings.
- Plastic Surgery:Facial flap dissection and body contouring. Brazilian private clinics drive mid-tier electrosurgical system placements.
General Surgery anchors installed base volume; Neurosurgery shows steepest expansion trajectory on precision technology adoption.
End User:
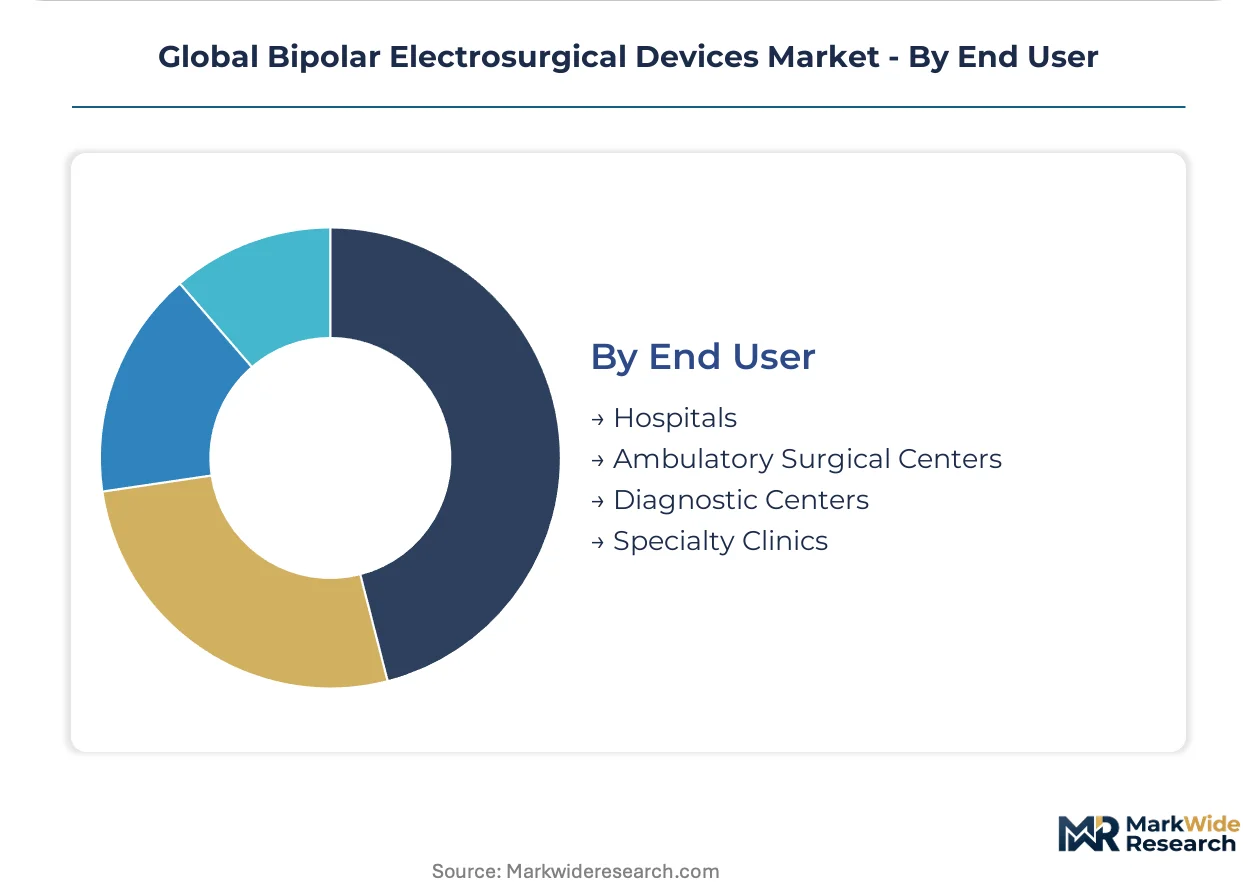
Capital equipment purchasing power and reprocessing labor economics bifurcate demand between integrated hospital networks and fragmented ambulatory settings.
- Hospitals:Centralized procurement of generator platforms with long-term service contracts. United States IDNs leverage GPO negotiating power for total cost-of-ownership pricing.
- Ambulatory Surgical Centers:Single-use instrument preference to eliminate reprocessing validation. United Kingdom independent sector providers drive fastest disposable accessory growth.
- Diagnostic Centers:Limited electrosurgical application to biopsy procedures. Minimal dedicated equipment investment.
- Specialty Clinics:Dermatology and cosmetic surgery settings in Japan and South Korea. Compact tabletop generators with procedure-specific presets.
Hospitals retain the dominant share; Ambulatory Surgical Centers are gaining share fastest on single-use conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature hospital systems prioritizing service-integrated platforms and emerging markets favoring versatile single-use instruments. The United States and Germany drive premium generator placements with long-term contracting models, while Brazil and India accelerate mid-tier adoption in private surgical centers.
United States
Integrated delivery networks consolidate procurement through group purchasing organizations that weight total cost-of-ownership metrics. FDA 510(k) clearance pathways govern device market access, with predicate device availability narrowing for novel tip geometries. The Midwest hospital corridor sustains deepest installed base density for reusable forceps with validated reprocessing protocols.
Germany
University hospitals in Bavaria and Baden-Württemberg set European specification standards for precision-manufactured generator platforms. EU MDR compliance deadlines force systematic inventory refreshes across hospital systems. The Tübingen-Stuttgart medical technology cluster anchors advanced ceramic insulation coating development for neural and pediatric applications.
Brazil
Private hospital construction in São Paulo and Rio de Janeiro creates demand for mid-tier electrosurgical systems adapted to localized voltage standards. ANVISA registration requirements shape product localization timelines for multinational suppliers. The São Paulo surgical center boom favors bipolar combination devices that reduce sterilization burden in limited-capacity settings.
Japan
An aging surgeon workforce drives ergonomic pistol-grip designs with reduced activation force for extended procedures. PMDA consultation pathways influence clinical trial design for novel energy delivery algorithms. The Osaka-Kobe medical device manufacturing belt concentrates production of compact tabletop generators for specialty clinic deployment.
United Kingdom
Ambulatory surgical centers in the independent sector drive fastest disposable accessory growth to eliminate reprocessing validation costs. MHRA post-market surveillance alignment with EU MDR imposes documentation burdens on reusable instrument categories. The London-Southeast hospital network pilots RFID-enabled device traceability systems for digital surgery platform integration.
Global Bipolar Electrosurgical Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding generator platform placements and the lower tier competing on discrete instrument pricing. The competitive landscape bifurcates between premium service-integrated suppliers and commoditized hardware vendors. Three archetypes dominate: vertically integrated conglomerates with captive training infrastructure, precision-manufacturing specialists with university hospital anchoring, and regional mid-tier assemblers serving price-sensitive private clinics. Consolidation pressure manifests through procurement bundling and M&A-driven geographic expansion.
Among integrated medical technology conglomerates, Medtronic and Johnson & Johnson occupy positions exemplifying the service-integrated archetype, leveraging training infrastructure and clinical education programs to lock in hospital system contracts. Erbe Elektromedizin represents the precision-manufacturing specialist tier, anchoring European university hospital relationships through generator platform standard-setting. These three companies illustrate how competitive positioning stratifies across training depth, manufacturing precision, and geographic anchoring rather than hardware specification alone.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| B. Braun |
| Olympus |
| ConMed |
| Stryker |
| Boston Scientific |
| Applied Medical |
| Erbe Elektromedizin |
| Others |
Supply & Pricing Matrix
ISO 13485 quality management certification gates both supplier qualification and price differentiation simultaneously, bifurcating the vendor base between premium service-integrated platforms and commoditized hardware. Hospital procurement teams weigh total cost-of-ownership against reprocessing validation burdens as single-use accessories gain traction in ambulatory settings.
Pricing Analysis
Long-term service contracts bundled with generator platform placements dominate hospital procurement, though spot-market purchasing of disposable accessories accelerates in ambulatory surgical centers. Price differentiation rests on certification tier and after-sales service depth, with FDA-cleared and MDR-compliant instruments commanding substantial premiums over baseline CE-marked alternatives. Cost compression in mid-tier hardware is intensifying because copper and precious metal input volatility compresses margins unpredictably. Ambulatory surgical centers exhibit highest price sensitivity, while United States integrated delivery networks prioritize total cost-of-ownership over per-unit acquisition cost.
Supply Chain Analysis
Strait of Malacca transit underwrites critical electrode alloy shipments from Southeast Asian refineries to German and Japanese precision manufacturers. Production concentrates in Germany, Japan, and the United States for high-end generator platforms, while China and Mexico supply mid-tier instrument assemblies. Raw material dependencies center on copper alloys, platinum-group coatings, and advanced ceramic substrates. Single-source vulnerability in precious metal refining creates supply chain risk during commodity price spikes. Distribution runs through hospital group purchasing organizations in North America and specialized medical device distributors in Europe and Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Bipolar Electrosurgical Devices Market represents high-growth disruption as EU MDR compliance deadlines force systematic inventory refreshes across European hospital systems. Intelligent energy modulation algorithms and RFID-enabled instrument connectivity reshape competitive positioning beyond hardware specifications.
For Market Incumbents: Secure generator platform placements through captive training infrastructure that locks in hospital system contracts. Deepen backward integration into electrode alloy sourcing to buffer copper price volatility. Invest in remote diagnostic capabilities that reduce field service dispatch frequency and defend margin position against unbundled service contract trends. For New Entrants and Emerging Players: Biomedical engineer certification scarcity creates service-layer white space where incumbents under-serve hospital maintenance demands. Target Brazilian private surgical centers with mid-tier bipolar combination devices adapted to localized voltage standards. Pursue ANVISA registration pathways ahead of São Paulo construction boom completion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across single-use instrument manufacturing as automated assembly lines displace manual reprocessing validation. Five-to-ten year viability favors precision-manufacturing specialists with university hospital anchoring over commoditized hardware assemblers. Watch FDA 510(k) predicate device availability as clearance timeline inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Certification | EU Medical Device Regulation clearance opens replacement cycle access across German and United Kingdom hospital systems. |
| Intelligent Generator Platform Development | Tissue response algorithms reduce operative time and differentiate against ultrasonic dissection substitutes in United States IDNs. |
| Single-Use Instrument Portfolio Expansion | Disposable configurations eliminate reprocessing validation costs for United Kingdom ambulatory surgical center procurement. |
| RFID-Enabled Traceability Integration | Usage cycle logging aligns with digital surgery platforms piloted in London-Southeast hospital networks. |
| Ergonomic Handpiece Design Investment | Reduced activation force targets Japan's aging surgeon workforce facing repetitive strain limitations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures. Interviews with biomedical engineers, hospital purchasing committee members, electrosurgical system clinicians, and GPO contracts managers inform demand-side dynamics. Secondary validation draws from customs trade data, ISO certification registries, and academic medical center pilot study publications. Bottom-up instrument shipment analysis triangulates against top-down generator platform placement estimates.
Segmentation dimensions modeled include product type, energy delivery technology, surgical application specialty, end-user setting, and regional regulatory cluster across the analysis window. CAGRs derive from procedure volume elasticity to surgical workforce expansion, reimbursement rate trajectories, and technology substitution coefficients. Forecast inputs incorporate laparoscopic surgery adoption curves and MDR transition timeline compliance patterns.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR enforcement regimes; material policy shifts would require re-modeling. Specific risks include predicate device availability constriction, precious metal supply disruption, and ultrasonic platform technology substitution. Practitioners should keep alternative scenarios live as hospital procurement consolidation and single-use conversion rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Gauze Swabs Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Cryosurgery Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Disposable Surgical Devices Market