

Helium Free MRI Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Helium Free MRI Scanners Market Insights
CE marking under the EU Medical Device Regulation (MDR) is bifurcating the competitive landscape into firms with full Notified Body certification and those limited to non-European markets. Siemens Healthineers leverages its cryogen-free platform portfolio to sustain leadership in high-field installations across European university hospitals. GE HealthCare anchors its position through backward integration into magnet manufacturing, controlling critical component supply. United Imaging Healthcare competes aggressively on price while navigating complex regulatory pathways in multiple jurisdictions.
Helium free MRI scanners employ permanent magnet, resistive magnet, or cryogen-free superconducting architectures that eliminate liquid helium dependency through advanced cooling systems or alternative magnetic field generation methods, typically operating at field strengths from 0.2 Tesla to 3.0 Tesla for diagnostic imaging. These systems serve primary clinical purposes in neurology, cardiology, and musculoskeletal imaging where continuous magnet availability proves essential for patient throughput. Mid-field and high-field product categories currently dominate installed value, though portable configurations represent the fastest-expanding segment as mobile medical units deploy to underserved regions. Permanent magnet and cryogen-free technologies capture disproportionate margin pools due to lower lifetime operating costs and reduced maintenance complexity compared to conventional superconducting alternatives.
The FDA maintains stringent premarket notification requirements for MRI devices under 21 CFR 892.1000, while the EU MDR mandates enhanced clinical evidence for cryogen-free systems seeking CE marking. Japan's PMDA imposes additional electromagnetic compatibility standards that filter which manufacturers can access its hospital procurement channels. Stakeholders must monitor evolving helium export controls and national strategic reserve policies that could abruptly reshape total cost of ownership calculations for healthcare systems worldwide.
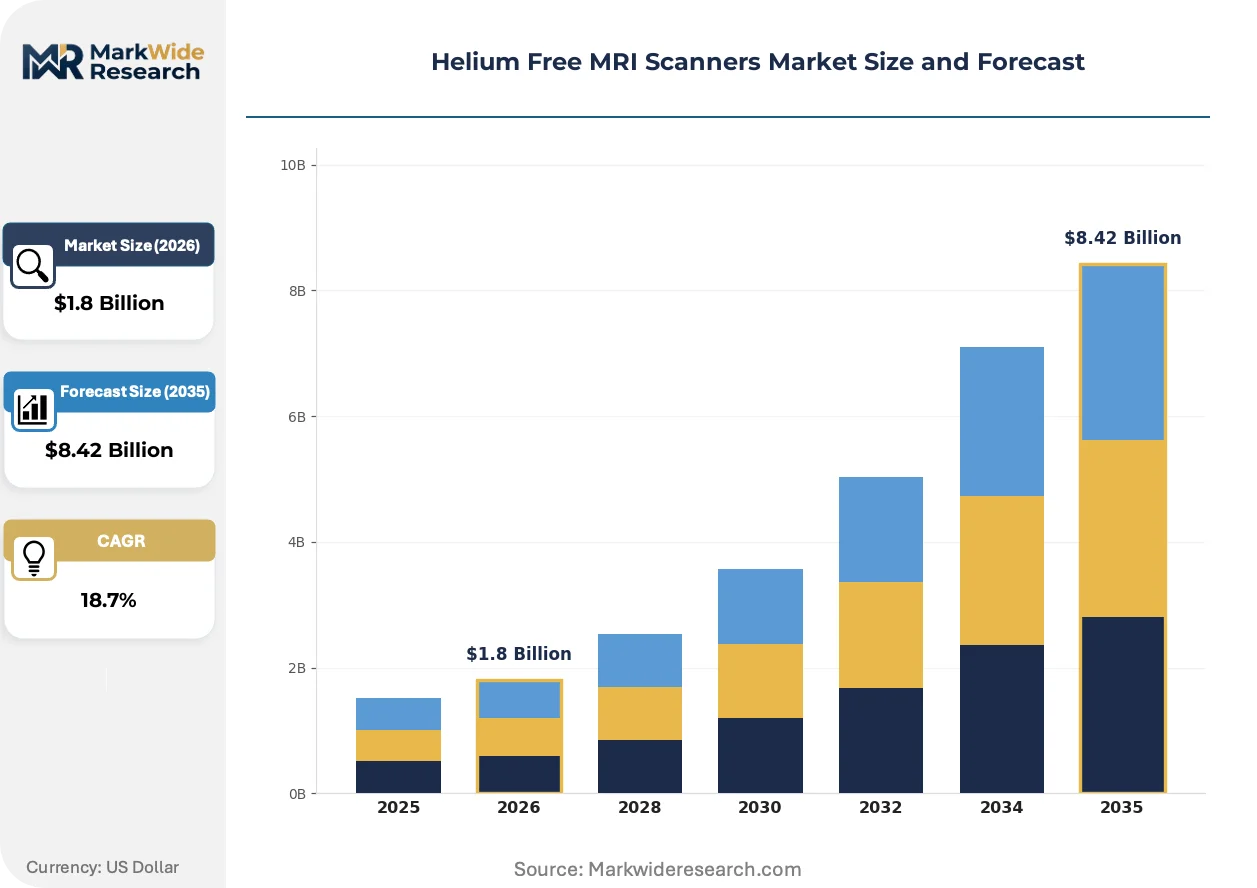
Market Dynamics
Helium supply chain fragility is restructuring procurement priorities across hospital systems, forcing accelerated capital allocation toward cryogen-free magnet architectures before conventional superconducting inventory becomes operationally stranded.
Growth Catalysts
- EU Medical Device Regulation (MDR) CE marking pathways:Streamlined conformity assessment procedures for cryogen-free systems are accelerating European hospital fleet transitions away from helium-dependent infrastructure.
- Rural hospital networks:Geographic isolation from helium logistics hubs is driving procurement of permanent magnet and cryogen-free platforms that eliminate supply chain vulnerability.
- Closed-cycle cryocooler engineering:Advances in pulse tube and Gifford-McMahon cooling systems are extending magnet uptime without liquid helium replenishment cycles.
Market Restraints
- Neodymium price volatility:Rare earth magnet material costs constrain permanent magnet MRI affordability, particularly for mid-field installations in cost-sensitive health systems.
- Notified Body capacity bottlenecks:EU MDR technical documentation review queues extend certification timelines for cryogen-free platform approvals.
- Superconducting wire supply concentration:Niobium-titanium and niobium-tin conductor manufacturing concentrates among specialized metallurgical suppliers, creating input dependency.
Strategic Opportunities
- Mobile diagnostic units:Portable helium-free configurations enable deployment to underserved regions lacking fixed imaging infrastructure.
- US Inflation Reduction Act hospital infrastructure incentives:Federal capital expenditure credits support rural facility magnet modernization programs.
- AI-assisted scan acceleration:Deep learning reconstruction algorithms converge with mid-field permanent magnet systems to restore diagnostic throughput without high-field helium dependency.
Industry Challenges
- Field service engineer scarcity:Cryogen-free superconducting platforms require specialized training in cryocooler maintenance and magnet quench recovery protocols.
- Legacy PACS integration complexity:Hospital information systems built around conventional MRI workflows demand costly reconfiguration for helium-free platform data formats.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helium Free MRI Scanners Market Trends and Innovations
Active magnet cooling architectures are supplanting passive liquid helium baths across installed base planning, with engineering focus shifting toward thermal management efficiency and service interval extension.
Conduction-cooled superconducting magnet designs are displacing conventional bath-cooled architectures in high-field installations. Academic medical centers in the United States are piloting these platforms for neuroimaging suites. The shift is compressing total cost of ownership calculations by eliminating helium inventory management and reducing quench recovery downtime.
Japan's PMDA electromagnetic compatibility standards are tightening test protocols for cryogen-free MRI platforms seeking market access. Manufacturers must demonstrate expanded shielding effectiveness and gradient coil isolation. Cardiac imaging product categories face the steepest compliance burden, with several firms redesigning radiofrequency enclosures to meet revised emission limits.
Hospital procurement departments are unbundling magnet acquisition from multi-year service contracts, negotiating discrete pricing for hardware, installation, and maintenance. Original equipment manufacturers resist this fragmentation, but group purchasing organizations in the United States are extracting modular terms. The practice is most visible among nonprofit hospital networks consolidating vendor negotiations across multi-state systems.
Helium Free MRI Scanners Market Segmentation
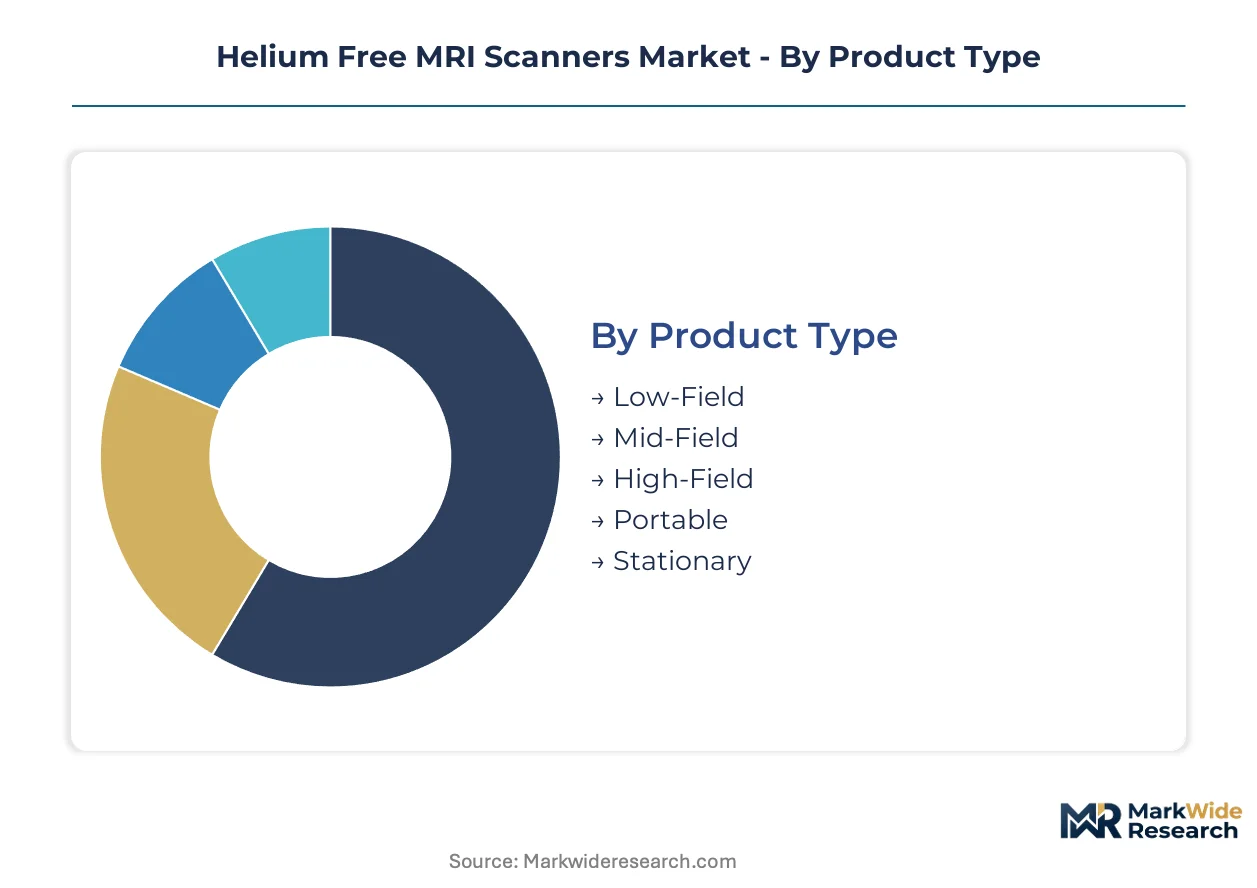
Helium-free MRI segmentation reveals how regulatory pathways and reimbursement structures concentrate procurement decisions across distinct technical tiers. Hospital capital committees weigh field strength requirements against lifetime helium cost exposure when allocating budget across product categories.
Product Type:
FDA's 21 CFR 892.1000 classification thresholds differentiate low-field systems as Class II devices with streamlined 510(k) pathways, while high-field installations trigger more stringent premarket review.
- Mid-Field:Operating between 0.5 Tesla and 1.0 Tesla, these systems balance diagnostic capability with permanent magnet architecture feasibility. Academic medical centers in the United States favor mid-field platforms for high-throughput orthopedic protocols where helium supply interruption risks outweigh marginal image quality gains from higher field strengths.
- Portable:Compact cryogen-free designs integrate closed-cycle cooling for deployment via mobile medical units. Rural hospital networks across the American Midwest accelerate procurement of trailer-mounted configurations to eliminate geographic dependency on helium logistics infrastructure.
- Low-Field:Sub-0.5 Tesla permanent magnet systems serve cost-sensitive diagnostic imaging centers with minimal maintenance requirements.
- High-Field:Conduction-cooled superconducting architectures at 1.5 Tesla and above target neuroimaging suites requiring fine structural resolution.
- Stationary:Fixed-installation cryogen-free platforms dominate hospital new construction planning with integrated RF shielding and patient handling systems.
Established volume favors Mid-Field; emerging adoption favors Portable.
Technology:
Cost tier stratification separates premium cryogen-free superconducting platforms from economy permanent magnet alternatives, with resistive systems occupying a narrowing middle band.
- Cryogen-Free:Pulse tube and Gifford-McMahon cooling systems sustain superconducting coil temperatures without liquid helium replenishment. European university hospitals under EU MDR procurement guidelines prioritize these platforms for reduced total cost of ownership and simplified regulatory compliance documentation.
- Permanent Magnet:Ferrite or neodymium-iron-boron magnetic circuits eliminate cryogenic infrastructure entirely. Community hospitals in helium supply-constrained regions select permanent magnet systems despite field strength limitations, accepting longer scan times to avoid operational vulnerability.
- Superconducting Magnet:Traditional bath-cooled architectures face accelerated replacement cycles as helium price volatility compresses economic viability.
- Resistive Magnet:Copper or aluminum conductor systems serve niche veterinary and industrial research applications with lower field requirements.
- Advanced Cooling:Emerging thermoacoustic and magnetic refrigeration prototypes target next-generation high-field installations.
Procurement volume concentrates in Cryogen-Free; permanent magnet platforms gain share fastest in cost-sensitive segments.
Application:
Clinical workflow requirements dictate field strength minimums, with cardiac and neuroimaging protocols demanding higher performance tiers than extremity or emergency screening applications.
- Neurology:High-resolution structural and functional brain imaging demands field strengths of 1.5 Tesla or above for adequate gray-white matter contrast. Academic medical centers in the United States retrofit aging neuroimaging suites with conduction-cooled systems to maintain research protocol compatibility while eliminating helium dependency.
- Musculoskeletal:Extremity and spine imaging tolerates lower field strengths, enabling permanent magnet platform adoption. Orthopedic specialty clinics in suburban markets select mid-field helium-free systems for high patient throughput with minimal infrastructure requirements.
- Cardiology:Cardiac MRI requires gradient performance and RF coil density that historically favored high-field helium-cooled systems.
- Oncology:Whole-body staging protocols balance coverage and resolution across varying field strengths.
- Pediatrics:Sedation requirements and smaller patient dimensions enable compact low-field platform utilization.
- Emergency Care:Rapid triage protocols prioritize magnet availability over image quality, favoring portable configurations.
Neurology commands premium pricing; musculoskeletal applications expand most quickly across installed base.
End User:
Customer type determines service contract structures, with diagnostic imaging centers negotiating unbundled pricing while research institutes accept comprehensive maintenance agreements.
- Diagnostic Imaging Centers:Independent outpatient facilities prioritize uptime guarantees and per-scan operating cost predictability. Group purchasing organizations in the United States extract modular pricing terms separating hardware acquisition from multi-year service commitments.
- Mobile Medical Units:Trailer-based and modular deployment configurations serve underserved regions lacking fixed infrastructure. Rural hospital networks across the American Southeast deploy portable helium-free systems via rotating schedules between multiple community access points.
- Research Institutes:Academic medical centers require field service engineer density and rapid magnet quench recovery protocols.
- Specialty Clinics:Focused orthopedic, sports medicine, and veterinary practices select compact permanent magnet systems for dedicated extremity protocols.
Diagnostic imaging centers anchor current revenue; mobile medical units present the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure incentives and helium supply vulnerability are redrawing procurement maps. Hospital systems prioritize cryogen-free platforms where logistics constraints intersect with capital subsidy availability.
United States
Rural hospital networks in the American Midwest accelerate permanent magnet acquisitions to eliminate helium logistics dependency. The Inflation Reduction Act delivers capital expenditure credits for facility modernization programs. Academic medical centers in Greater Boston pilot conduction-cooled superconducting retrofits for aging neuroimaging infrastructure.
Germany
University hospitals under EU MDR procurement guidelines prioritize cryogen-free platforms for simplified compliance documentation. CE marking pathways for superconducting medical equipment have streamlined since the 2021 regulation transition. The Munich-Stuttgart corridor concentrates magnet engineering expertise and Notified Body technical review capacity.
Japan
PMDA electromagnetic compatibility standards filter market access for cryogen-free platforms seeking hospital procurement channels. Revised emission limits force radiofrequency enclosure redesigns for cardiac imaging configurations. The Kansai region hosts concentrated medical device testing infrastructure serving domestic manufacturers.
China
Domestic manufacturers compete on price while navigating NMPA registration pathways for cryogen-free superconducting systems. National strategic reserve policies for helium reshape total cost calculations for hospital procurement committees. The Yangtze River Delta anchors production clusters for permanent magnet components and closed-cycle cryocooler assemblies.
United Kingdom
NHS capital allocation frameworks now weight lifetime helium cost exposure in magnet acquisition decisions. MHRA post-Brexit regulatory alignment with EU MDR technical standards preserves CE marking recognition for existing certifications. London-Oxford-Cambridge research corridors drive demand for high-field cryogen-free platforms in academic imaging suites.
Helium Free MRI Scanners Market Competitive Landscape
Player mix skews toward diversified medical imaging conglomerates with captive magnet manufacturing capabilities. Siemens Healthineers and GE HealthCare anchor the premium tier through backward integration into superconducting wire and cryocooler engineering. Three archetypes dominate: integrated system architects controlling critical component supply, regional price competitors leveraging manufacturing scale, and specialized permanent magnet fabricators serving cost-sensitive segments. Competitive moves concentrate on cryogen-free platform portfolio expansion and service contract unbundling resistance against group purchasing organization pressure.
Within the integrated system architect tier, Siemens Healthineers and GE HealthCare exemplify positions built on decades of magnet engineering heritage and regulatory pathway mastery. United Imaging Healthcare occupies a scale-driven position among China-based competitors, representing the price-aggressive archetype challenging established premium positioning. These three anchors illustrate how competitive advantage stratifies across technology control, manufacturing geography, and regulatory navigation capability rather than product specification alone.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE HealthCare |
| Koninklijke Philips |
| Canon Medical Systems |
| FUJIFILM Holdings |
| United Imaging Healthcare |
| Neusoft Medical Systems |
| Hitachi |
| Samsung Medison |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cryocooler component lead times concentrate pricing power among magnet engineering specialists with captive supply of pulse tube assemblies and Gifford-McMahon compressors, while hospital procurement committees exploit group purchasing organization scale to compress service contract margins.
Pricing Analysis
Certification level (FDA 510(k) versus PMA versus EU MDR CE marking) creates the primary spread between premium cryogen-free superconducting platforms and economy permanent magnet alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects field strength performance, with 1.5 Tesla and above commanding substantial premiums for neuroimaging protocols. Cost compression in mid-field permanent magnet systems is intensifying because Chinese manufacturers are scaling ferrite magnet production and undercutting European incumbents on hardware acquisition. Diagnostic imaging centers exhibit highest price sensitivity, prioritizing per-scan operating cost predictability over image quality margins, while academic medical centers prove least sensitive due to research protocol requirements and federal funding access.
Supply Chain Analysis
China and Japan anchor permanent magnet component fabrication and closed-cycle cryocooler assembly respectively, with Germany retaining concentrated superconducting wire metallurgy expertise. Niobium-titanium conductor, rare earth ferrite powders, and pulse tube regenerator materials constitute critical input dependencies. Single-source vulnerability concentrates in specialized cryocooler compressor manufacturing, where two Japanese suppliers dominate hospital-grade reliability tiers. Distribution runs through original equipment manufacturer direct sales forces for premium installations, while regional distributors and group purchasing organizations intermediate mid-field and portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through group purchasing organization consolidation across American nonprofit hospital networks, compressing vendor margin structures and forcing unbundling of hardware from service contracts.
For Market Incumbents: Consolidate backward integration into superconducting wire and cryocooler compressor manufacturing to defend against Chinese price competitors and secure supply continuity. Expand field service engineer training programs in helium logistics-constrained regions to differentiate on uptime guarantees. Prioritize EU MDR technical documentation completion to maintain CE marking access against Notified Body capacity bottlenecks.
For New Entrants and Emerging Players: Lead with portable cryogen-free configurations targeting American rural hospital networks and mobile medical unit operators, the most penetrable segment given geographic isolation from helium infrastructure. Develop AI-assisted scan acceleration software partnerships to compensate for mid-field permanent magnet image quality limitations. Pursue direct procurement relationships with independent diagnostic imaging centers outside group purchasing organization coverage.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across permanent magnet platform manufacturing as Chinese scale economies compress equipment costs and shift value toward software and service layers. Acquisition targets should display cryogen-free superconducting IP portfolios or established Notified Body relationships. Monitor helium export control policy announcements from national strategic reserve administrators as inflection indicators for accelerated cryogen-free adoption timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR streamlined conformity assessment accelerates European hospital fleet transitions from helium-dependent infrastructure. |
| Hospital System Partnership | Multi-year service agreements with American academic medical centers secure neuroimaging suite retrofit volumes. |
| Backward Integration | In-house cryocooler compressor production insulates against Japanese supplier concentration and single-source vulnerability. |
| Software Companion Development | AI reconstruction algorithms restore diagnostic throughput for mid-field permanent magnet systems without helium dependency. |
| Reimbursement Strategy | Medicare facility fee optimization for mobile diagnostic units expands rural deployment economics across American Midwest networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and PMA filings, EU MDR technical documentation databases, and hospital procurement contract registries. Primary interviews engaged biomedical engineers at academic medical centers, group purchasing organization contracts managers, cryogen-free platform product directors at major manufacturers, and Notified Body technical reviewers. Bottom-up installed base modeling triangulates against top-down healthcare capital expenditure forecasts across the analysis window.
Segmentation dimensions modeled include field strength tier, magnet technology architecture, clinical application protocol, and end-user facility type. CAGRs derive from logistic diffusion curves fitted to procurement pipeline data and helium price sensitivity elasticity estimates. Forecast inputs incorporate cryocooler reliability improvement trajectories and EU MDR certification queue projections.
Forecasts assume regulatory continuity in FDA premarket notification pathways and EU MDR conformity assessment procedures; material policy shifts in helium strategic reserve management or electromagnetic compatibility standards would require re-modeling. Recalibration cycles align with material shifts in rare earth magnet pricing, Notified Body capacity expansion, and closed-cycle cooling engineering breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.