
 Surgical Integration Systems Market | 2026-2036
Surgical Integration Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Integration Systems Market Analytics
Modular platform bundling is realigning procurement decisions across hospital systems and ambulatory surgical centers. Stryker leverages its endoscopy and navigation portfolio to anchor integrated OR suite contracts. Steris competes through sterilization-to-visualization workflow control, while Karl Storz SE & Co. KG specializes in rigid endoscope-to-display vertical integration.
Surgical integration systems orchestrate real-time routing, processing, and display of multi-source video, audio, and device data within operating theaters, typically operating at 4K resolution with latency below 50 milliseconds to preserve surgical precision. Their primary commercial purpose centers on reducing cognitive load, streamlining communication, and capturing procedure documentation for quality and training. Video management systems occupy the largest revenue pool given their position as the connectivity backbone, while 4K technology segments capture disproportionate margin expansion as display refresh cycles accelerate. Wireless technology remains nascent but fastest-growing as OR infrastructure modernizes to eliminate cable management hazards.
FDA 510(k) premarket notification, EU MDR technical documentation requirements, and IEC 60601-1 third-edition electrical safety standards collectively elevate compliance costs and extend validation timelines for new entrants. Japan's PMDA and METI further shape Asia-Pacific product specifications through localized electromagnetic compatibility testing. Stakeholders must monitor whether emerging AI-enabled surgical guidance triggers additional software-as-medical-device classifications that reshape regulatory burden and competitive moats.
Market Dynamics
Modular platform bundling is compressing procurement cycles as hospital systems consolidate vendor relationships around integrated OR suite contracts rather than point solutions. This structural shift favors suppliers with end-to-end visualization, navigation, and sterilization portfolios.
Growth Catalysts
- Outpatient procedure migration:Ambulatory surgical centers are expanding integrated system deployments as same-day surgery volumes rise across United States metropolitan markets.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for visualization hardware is accelerating product refresh cycles and reducing time-to-revenue for connectivity platform upgrades.
- 4K display refresh mandates:Hospital capital planning committees are prioritizing resolution upgrades during OR retrofit projects to support minimally invasive technique adoption.
Market Restraints
- EU MDR technical documentation burden:Conformity assessment requirements for software-enabled surgical platforms are extending validation timelines and elevating compliance expenditures for new entrants.
- Semiconductor supply concentration:Video processing chip fabrication concentrates in Taiwan and South Korea, creating input vulnerability for latency-critical routing hardware.
- Wireless electromagnetic interference limits:IEC 60601-1-2 immunity standards constrain signal transmission power in dense OR environments, capping wireless adoption speed.
Strategic Opportunities
- Japan PMDA AI software pathway:Emerging regulatory frameworks for machine learning-enabled surgical guidance create first-mover positioning for computer vision integration.
- Cloud-native video archiving:Subscription-based procedure documentation and training content management represents unbundled revenue streams from capital hardware sales.
- Germany hospital construction wave:Greenfield facility development in Bavaria and North Rhine-Westphalia is creating integrated OR suite installation demand independent of retrofit replacement cycles.
Industry Challenges
- Cybersecurity validation for networked devices:IEC 62304 software lifecycle processes and FDA guidance on interconnected systems are extending premarket testing phases for connectivity platforms.
- Legacy OR infrastructure interoperability:Proprietary video formats from installed endoscope fleets create integration friction during system upgrades, requiring costly protocol adaptation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Integration Systems Market |
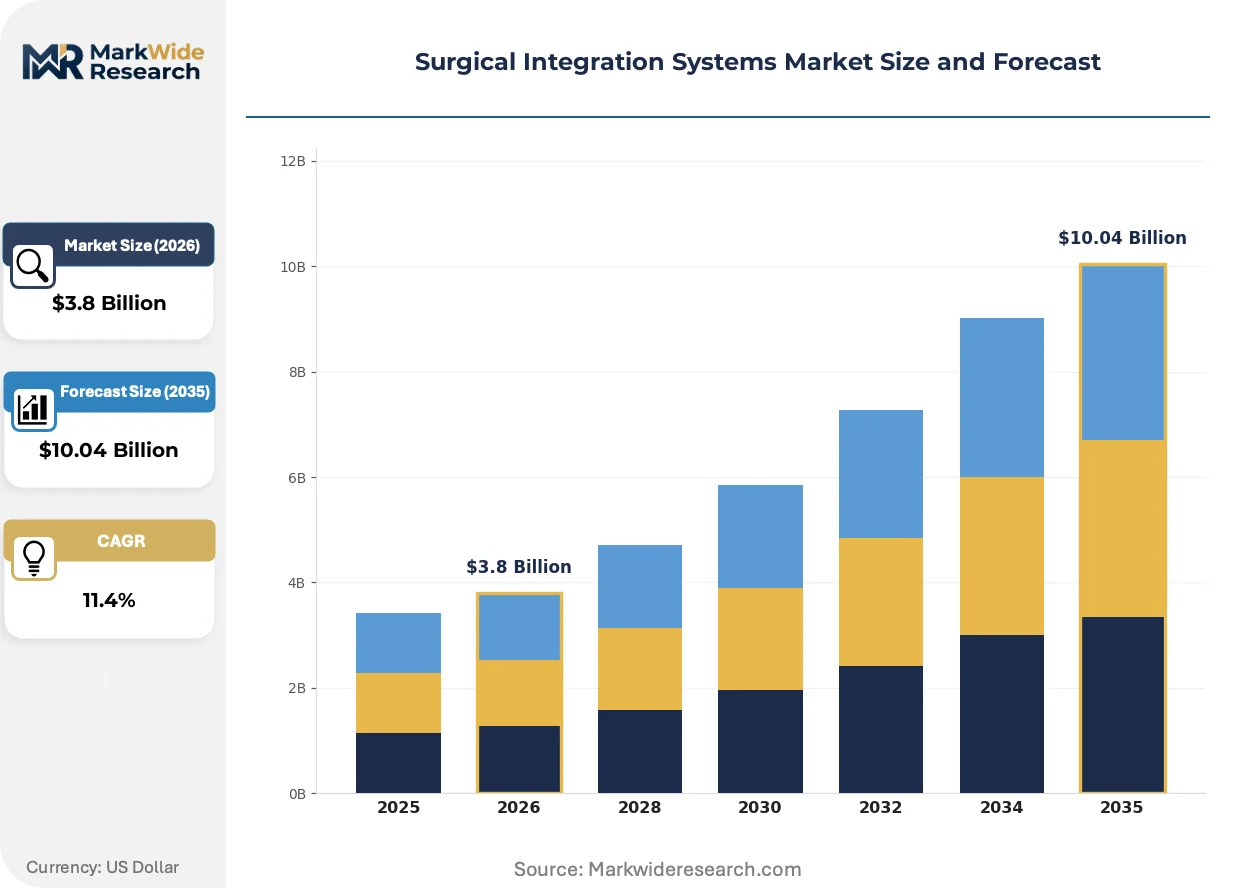
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Management Systems, Visualization Systems, Surgical Displays, Connectivity Solutions Technology: HD Technology, 4K Technology, Wireless Technology, IP-based Systems End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Orthopedic Surgery, Neurosurgery, General Surgery, Cardiothoracic Surgery |
| Companies Covered | Stryker, Steris, Olympus, Getinge AB, Karl Storz SE & Co. KG, Brainlab AG, Barco NV, Dragerwerk AG & Co. KGaA, Skytron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Integration Systems Market Evolving Landscape
Real-time data orchestration capabilities are advancing beyond passive video routing toward active surgical decision support, with artificial intelligence and edge computing architectures redefining platform value propositions.
AI-enabled surgical analytics is converging with traditional video management infrastructure to enable intraoperative instrument tracking and procedural phase recognition. Academic medical centers in Germany and Japan are piloting computer vision overlays for laparoscopic guidance. This convergence is compressing the boundary between diagnostic imaging workstations and live surgical displays, forcing vendors to recalibrate R&D allocation across hardware and software engineering teams.
EU MDR Article 10 technical documentation requirements are mandating clinical evidence thresholds for software-as-medical-device classifications that previously escaped scrutiny. Manufacturers must now generate post-market surveillance data for connectivity platforms with algorithmic processing capabilities. Visualization suppliers with legacy hardware-only portfolios face the steepest adaptation burden, while those with pre-existing software quality management systems capture regulatory timing advantages.
Hospital procurement committees are consolidating vendor evaluation criteria around total cost of ownership metrics rather than upfront capital expenditure. Integrated service contracts covering preventive maintenance, software updates, and training are displacing traditional equipment purchase models in United States health systems. This behavioral shift concentrates contract value with suppliers capable of delivering multi-year operational partnerships, penalizing pure hardware vendors lacking field service infrastructure.
Surgical Integration Systems Market Segmentation
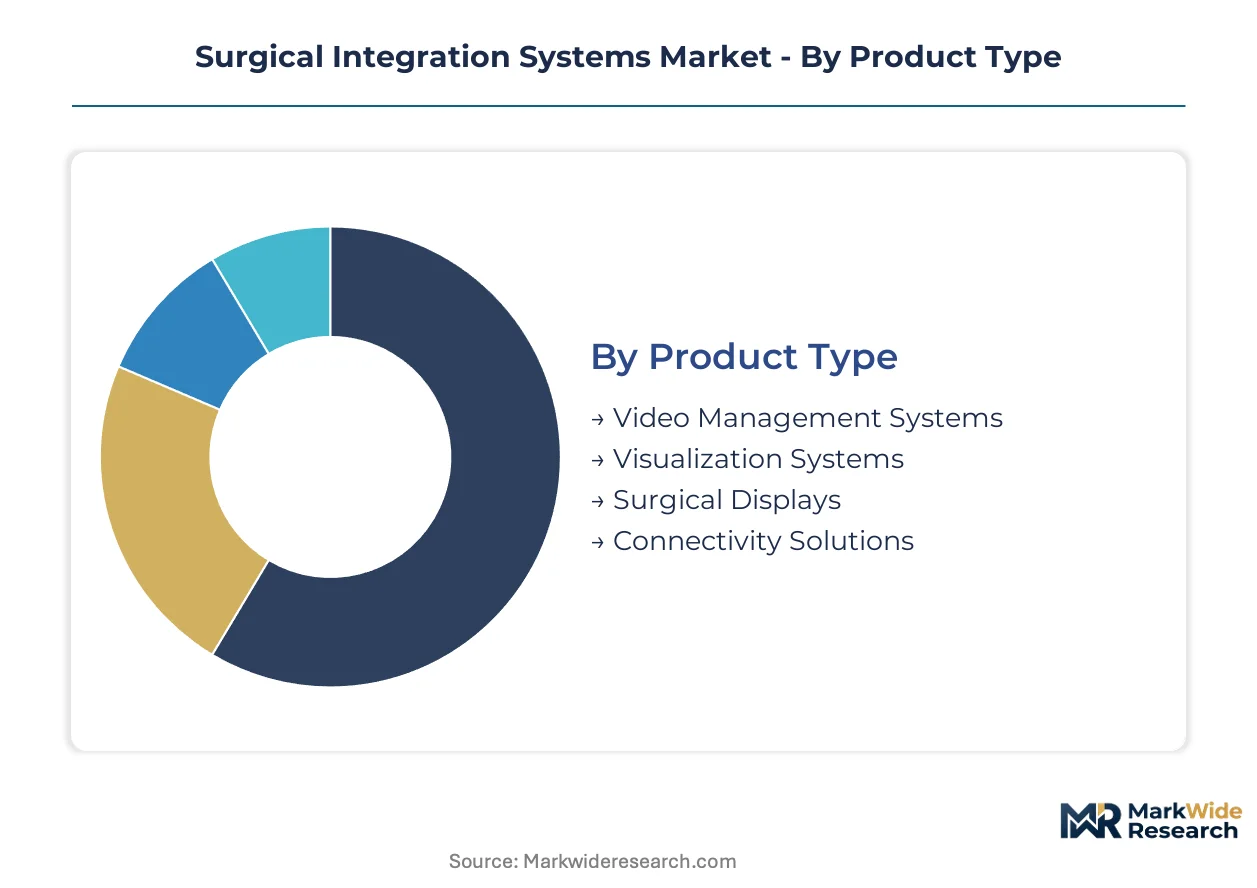
Surgical integration systems fragment across four critical dimensions that determine deployment architecture and procurement economics. Product type defines core hardware versus software revenue splits, while technology tiers separate legacy infrastructure from next-generation platforms. End-user concentration shapes contract scale and service intensity, and application specialization drives feature customization requirements.
Product Type:
Standalone visualization hardware dominates retrofit installations where hospitals preserve existing routing infrastructure, while embedded connectivity platforms anchor new construction projects requiring unified vendor accountability.
- Video Management Systems:These platforms function as the central nervous system of integrated ORs, processing multi-source video streams with sub-50 millisecond latency requirements. Demand concentrates in United States metropolitan hospital systems undergoing phased OR modernization, constrained by legacy endoscope fleet interoperability challenges that necessitate costly protocol adaptation layers.
- Visualization Systems:Comprising camera control units, image processors, and signal converters, these components determine surgical precision through color accuracy and motion handling. German academic medical centers drive specification intensity here, prioritizing 4K resolution pathways for minimally invasive technique adoption during capital planning cycles.
- Surgical Displays:Medical-grade panels with anti-glare coatings and sterilizable surfaces serve as the final output layer. Japanese hospital construction standards mandate specific electromagnetic compatibility thresholds for these devices.
- Connectivity Solutions:Network switches, fiber infrastructure, and integration middleware enable device interoperability. Ambulatory surgical centers in United States outpatient markets favor modular connectivity upgrades over full-suite replacements.
Video Management Systems lead volumes today; Connectivity Solutions are gaining share fastest.
Technology:
Resolution tiers create distinct margin pools, with premium display technologies commanding pricing multiples over baseline infrastructure while wireless architectures promise cable elimination at compliance cost.
- HD Technology:Legacy 1080p infrastructure retains installed base dominance in budget-constrained facilities and developing markets. Replacement cycles extend as hospitals defer capital commitments.
- 4K Technology:Ultra-high-definition platforms deliver four times the pixel density of HD, enabling instrument tip visualization at extended working distances. United States hospital capital committees now mandate 4K compatibility for new OR approvals, accelerating refresh cycles independent of functional obsolescence.
- Wireless Technology:Eliminating cable clutter reduces trip hazards and sterilization burden, though IEC 60601-1-2 immunity standards constrain transmission power in dense electromagnetic environments. Pilot deployments concentrate in Germany and Japan where infrastructure modernization budgets accommodate emerging architecture risk.
- IP-based Systems:Ethernet-native video routing enables software-defined configuration and remote diagnostics. These platforms face cybersecurity validation requirements under FDA guidance for interconnected medical devices.
4K Technology captures the steepest expansion trajectory; HD Technology maintains installed base dominance.
End User:
Facility scale determines contract structure, with integrated delivery networks negotiating enterprise pricing while standalone centers prioritize capital efficiency and rapid deployment timelines.
- Hospitals:Multi-OR health systems represent the foundational revenue base, deploying comprehensive integration across cardiac, neurosurgical, and orthopedic suites. United States hospital construction and retrofit cycles drive procurement timing.
- Ambulatory Surgical Centers:Same-day surgery facilities require compact, procedure-specific configurations with streamlined training requirements. These centers are expanding most quickly across United States metropolitan markets as outpatient migration accelerates.
- Specialty Clinics:Ophthalmology and endoscopy-focused practices demand single-modality integration at reduced price points. German outpatient clinic networks show particular concentration here.
- Research Institutions:Academic medical centers pilot experimental configurations including AI-enabled overlays and augmented reality guidance. Japan's university hospital networks lead experimental deployment.
Hospitals anchor revenue concentration today; Ambulatory Surgical Centers are expanding most quickly.
Application:
Surgical discipline dictates video routing complexity, with multi-instrument procedures requiring highest channel counts and lowest latency tolerances.
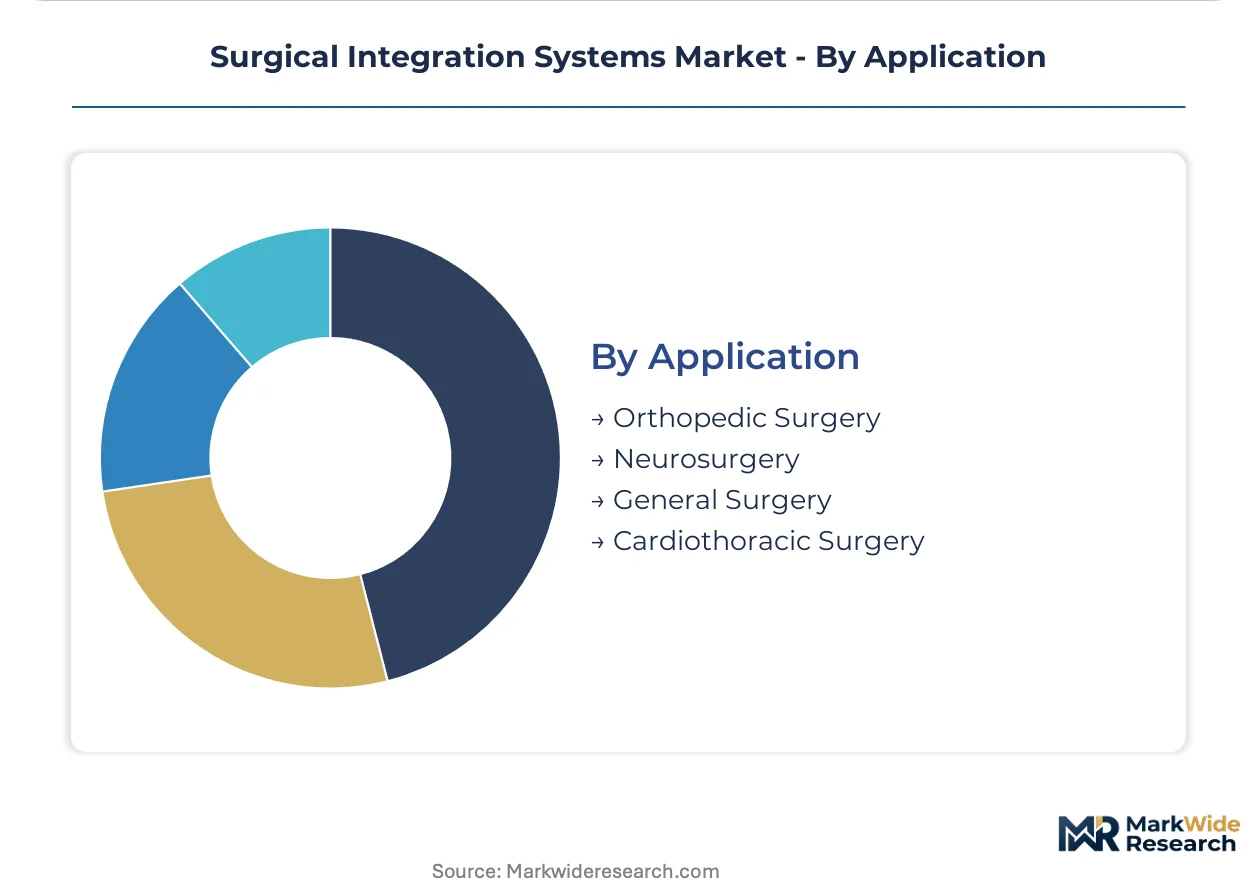
- Orthopedic Surgery:Arthroscopic and joint replacement procedures demand high-definition visualization of anatomical structures through small incisions. United States sports medicine centers drive specification intensity.
- Neurosurgery:Cranial and spinal procedures require millimeter-precision navigation integration with real-time imaging. German neurosurgical centers prioritize latency-critical performance above cost optimization.
- General Surgery:Laparoscopic cholecystectomy and hernia repair represent highest procedure volumes, creating commoditized integration requirements. These applications show strongest price sensitivity across customer segments.
- Cardiothoracic Surgery:Hybrid OR configurations for transcatheter valve replacement demand seamless fluoroscopy-to-endoscopy switching. Japanese cardiovascular centers lead hybrid suite installation rates.
General Surgery leads procedure volumes today; Cardiothoracic Surgery shows steepest integration complexity growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The surgical integration systems industry traces its commercial origins to German endoscope manufacturing clusters and United States hospital construction booms of the 1990s, with subsequent technology waves radiating from Japanese precision electronics and Swiss medical device engineering centers.
United States
Metropolitan health systems in Texas and Florida are accelerating OR retrofit cycles as ambulatory surgical center construction surges. FDA 510(k) premarket notification pathways compress visualization hardware approval timelines. The Dallas-Fort Worth corridor hosts concentrated deployment of integrated suite contracts for orthopedic and cardiovascular specialties.
Germany
Bavarian and North Rhine-Westphalian hospital construction programs drive greenfield integrated OR demand independent of replacement cycles. EU MDR technical documentation requirements elevate compliance thresholds for software-enabled platforms. The Tübingen-Stuttgart medical technology cluster anchors rigid endoscope-to-display vertical integration capabilities.
Japan
University hospital networks in Kanto and Kansai regions pilot AI-enabled surgical guidance overlays. METI and PMDA frameworks shape localized electromagnetic compatibility testing protocols for medical-grade displays. Tokyo academic medical centers lead experimental computer vision integration for laparoscopic procedures.
Switzerland
Swissmedic conformity assessment procedures align with EU MDR while preserving distinct quality management requirements for connectivity platforms. The Lake Geneva corridor concentrates precision engineering expertise for latency-critical video routing hardware. Basel-area research institutions collaborate on edge computing architectures for intraoperative decision support.
Surgical Integration Systems Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with end-to-end visualization portfolios. Three to five integrated platform suppliers command disproportionate contract value through bundled OR suite offerings. Strategic archetypes span endoscopy-to-navigation verticalists, sterilization workflow controllers, and display technology specialists. Dominant competitive moves include modular platform bundling to compress procurement cycles and cloud-native service layering to displace capital-only sales models.
Among diversified conglomerates, Stryker and Olympus occupy positions exemplifying endoscopy-anchored integration strategies, while Karl Storz SE & Co. KG represents specialized rigid endoscope-to-display vertical integration. Steris sits within the sterilization-to-visualization workflow control archetype, competing through procedural environment management rather than pure visualization hardware. These players collectively shape procurement committee evaluation criteria around total cost of ownership metrics and multi-year operational partnership capabilities.
| Leading Market Players |
|---|
| Stryker |
| Steris |
| Olympus |
| Getinge AB |
| Karl Storz SE & Co. KG |
| Brainlab AG |
| Barco NV |
| Dragerwerk AG & Co. KGaA |
| Skytron |
| Others |
Value Network & Pricing Analysis
Hospital capital planning committees and ambulatory surgical center procurement officers now dominate contract negotiations, compressing vendor margins through multi-year total cost of ownership frameworks rather than upfront capital expenditure models. This buyer concentration forces suppliers to bundle preventive maintenance, software updates, and training into subscription-like service contracts that displace pure hardware sales.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared 4K visualization platforms from CE-marked HD infrastructure and uncertified legacy routing hardware. Price differentiation rests on certification grade and after-sales service bundling, with premium tiers commanding multiples for sub-50 millisecond latency guarantees. Cost compression in the standard tier is intensifying because semiconductor input volatility and EU MDR compliance expenditures squeeze mid-market suppliers. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while German academic medical centers show least sensitivity given resolution-mandate procurement criteria.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for video processing chip fabrication, creating input fragility for latency-critical routing hardware. The supply chain draws from Japanese precision electronics for medical-grade display panels and German optical engineering for rigid endoscope components. Tariff exposure runs through semiconductor import dependencies concentrated in East Asian fabrication hubs. Distribution runs through direct sales forces for hospital system contracts and specialized medical device distributors for ambulatory surgical center penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU MDR Article 10 technical documentation requirements and FDA software-as-medical-device guidance are accelerating compliance expenditures and consolidating competitive positioning around quality management maturity.
For Market Incumbents: Acquire cloud-native video archiving capabilities to anchor subscription revenue streams and defend against pure-software entrants threatening hardware-only business models. Secure backward integration into fiber infrastructure manufacturing to control connectivity solution margins and reduce exposure to Taiwan semiconductor supply volatility. Prioritize IEC 62304 cybersecurity validation investments to preempt FDA premarket testing phase extensions for networked device platforms. For New Entrants and Emerging Players: AI-enabled surgical analytics integration represents the most penetrable wedge for challenging established video management system suppliers. Target United States ambulatory surgical center networks with modular connectivity upgrades that bypass full-suite replacement capital barriers. Deploy procedure-specific training content partnerships as the go-to-market angle to differentiate against incumbent field service infrastructure advantages. For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking visualization portfolio gaps to anchor integrated OR suite contracts. Long-term viability hinges on software quality management system maturity rather than hardware manufacturing scale. Monitor Japan PMDA AI software pathway regulatory clarity as the signal to watch for machine learning-enabled surgical guidance valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Streamlined premarket notification accelerates visualization hardware time-to-revenue for connectivity platform upgrades. |
| EU MDR Technical Documentation Investment | Conformity assessment capabilities create regulatory timing advantages against legacy hardware-only competitors. |
| Hospital System Partnership Development | Multi-year operational contracts displace capital-only sales models through total cost of ownership bundling. |
| Software Companion Development | Cloud-native video archiving enables unbundled subscription revenue streams from traditional equipment sales. |
| Reimbursement Strategy Alignment | Procedure documentation quality metrics support payer value-based contracting for integrated OR suite investments. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, biomedical engineering director consultations, GPO contracts manager surveys, and regulatory affairs specialist discussions — were reconciled against secondary validation from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital construction project tracking systems, and integrated OR suite installation records. Bottom-up segmentation modeling and top-down market sizing triangulation were applied across product type, technology tier, end-user facility scale, and surgical application dimensions.
Cross-referencing historical installation data against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include video management versus visualization hardware splits, 4K versus HD versus wireless technology tiers, hospital versus ambulatory surgical center end-user concentration, and orthopedic versus neurosurgical versus general surgery application specialization. CAGRs were derived through weighted average growth rate synthesis across these segments, incorporating OR retrofit cycle timing, outpatient procedure migration velocity, and regulatory approval pathway efficiency as industry-specific forecast inputs.
The model holds under stable FDA 510(k) pathway efficiency and continued EU MDR implementation consistency; deviation in semiconductor supply chain disruption severity or AI software-as-medical-device reclassification timing would shift trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
India Anesthesia Devices Market
Medical Devices
Smart Vision Aids Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
India Contraceptive Devices Market