
 Corneal Implants Market | 2026-2036
Corneal Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Corneal Implants Market Analysis
A shift from single-source tissue procurement toward multi-source supply networks is realigning how corneal implant manufacturers secure donor material. Alcon Inc. leverages its global distribution infrastructure to maintain consistent product availability across regulated markets. CorneaGen Inc. anchors North American supply through specialized eye banking partnerships and quality-controlled tissue processing. LinkoCare Life Sciences AB competes in European markets with focused manufacturing of synthetic keratoprosthesis alternatives.
Corneal implants are medical devices or biological tissues surgically placed to replace damaged corneal structures, typically manufactured from donor human tissue, synthetic polymers such as poly(methyl methacrylate), or bioengineered collagen matrices ranging from 0.3 to 0.6 mm in central thickness, functioning primarily to restore optical clarity and mechanical integrity to the anterior eye segment. Keratoprosthesis and artificial cornas dominate current procedural volumes due to established surgical protocols and immediate visual rehabilitation outcomes, while bioengineered implants represent the fastest-expanding category as tissue engineering advances reduce rejection rates and extend graft survival. End users cluster heavily in ophthalmic clinics and hospitals, with eye banks serving as critical intermediaries that control tissue quality, allocation logistics, and regulatory chain-of-custody documentation.
FDA premarket notification and PMA pathways govern US market entry, while the EU Medical Device Regulation and CE marking framework enforce biocompatibility and clinical evidence standards across European markets. Japan's PMDA oversees pharmaceutical and medical device agency reviews that mandate local clinical trials for novel corneal materials, creating staggered launch timelines across major jurisdictions. Stakeholders must monitor evolving tissue engineering standards from ISO and WHO guidance documents that increasingly influence national adoption of biofabricated alternatives to donor-derived tissues.
Market Dynamics
The shift from single-source tissue procurement toward multi-source supply networks is restructuring manufacturer relationships with eye banks and forcing investments in quality-controlled processing infrastructure.
Growth Catalysts
- EU Medical Device Regulation:Harmonized biocompatibility standards across European markets reduce regulatory fragmentation for manufacturers seeking CE marking on novel keratoprosthesis devices.
- Ophthalmic clinic expansion:Metropolitan surgical centers in the United States, Germany, and Japan are scaling corneal implant procedure capacity to match rising patient volumes.
- Bioengineered collagen matrices:Advances in tissue engineering are extending graft survival timelines and reducing rejection rates in keratoconus and corneal dystrophy treatments.
Market Restraints
- Donor tissue scarcity:Eye bank concentration in the United States and select European markets creates allocation bottlenecks that limit procedural volume growth.
- FDA premarket approval timelines:The PMA pathway for novel corneal devices extends investment recovery periods and compresses early-mover advantages.
- Synthetic polymer limitations:Poly(methyl methacrylate) keratoprosthesis carries elevated infection risk and end-stage glaucoma complications that restrict adoption.
Strategic Opportunities
- Japan's PMDA pathway:Local clinical trial mandates for novel corneal materials create first-mover advantages for manufacturers establishing Japanese regulatory dossiers.
- Synthetic keratoprosthesis alternatives:LinkoCare Life Sciences AB's focused European manufacturing demonstrates scalable models for biofabricated tissue substitutes.
- ISO tissue engineering standards:Evolving WHO guidance documents are accelerating national adoption frameworks for bioengineered alternatives to donor-derived tissues.
Industry Challenges
- Eye bank chain-of-custody documentation:Regulatory compliance for tissue quality and allocation logistics requires specialized personnel that outpace training pipeline capacity.
- Biocompatibility certification timelines:ISO standards for biofabricated corneal materials lack harmonized testing protocols, creating staggered validation requirements across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corneal Implants Market |
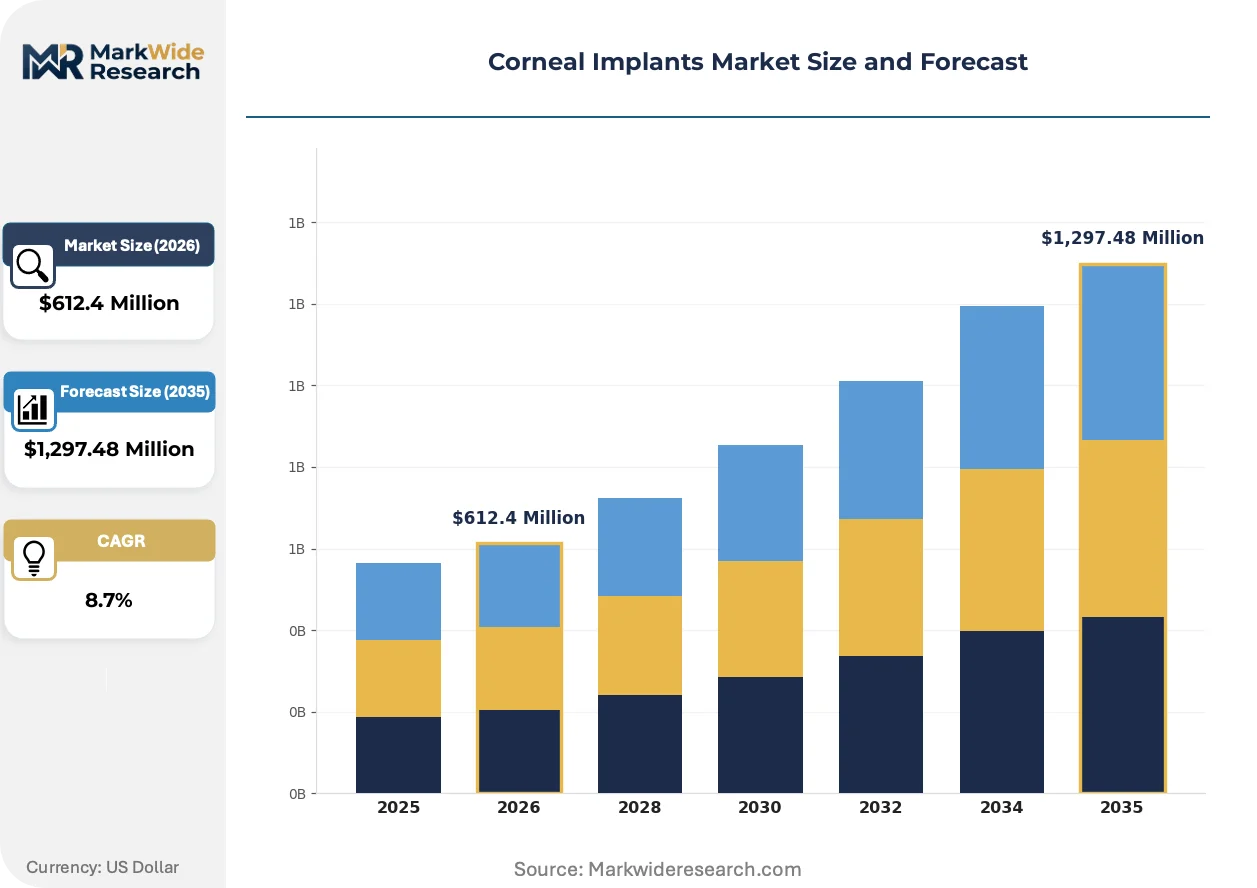
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Corneas, Keratoprosthesis, Bioengineered Implants, Corneal Tissues End User: Ophthalmic Clinics, Hospitals, Research Institutions, Eye Banks Technology: Laser-Assisted Surgery, Traditional Surgery, Biofabrication, Tissue Engineering Application: Vision Restoration, Eye Trauma, Corneal Scarring, Disease Treatment |
| Companies Covered | Alcon Inc., CorneaGen Inc., Aurolab, LinkoCare Life Sciences AB, Presbia PLC, EyeYon Medical, AJL Ophthalmic S.A., Carl Zeiss Meditec AG, DIOPTEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corneal Implants Market Emerging Trajectories
Active reshaping of the corneal implant landscape centers on three converging forces: engineered materials displacing donor dependence, regulatory frameworks accelerating biofabrication approval, and procurement models consolidating around multi-source supply networks.
Bioengineered collagen matrices are overtaking donor-derived tissues as the preferred substrate for keratoconus and dystrophy interventions. Leading ophthalmic clinics in Germany and Japan are adopting these implants at accelerating pace due to reduced rejection surveillance burden. The technology is compressing traditional eye bank dependency and forcing tissue processors to diversify into engineered material partnerships.
Japan's PMDA has tightened local clinical trial requirements for novel corneal materials, extending launch timelines but raising evidence standards for reimbursement eligibility. Manufacturers now face compressed development windows to generate Japanese-specific safety data before competitor entry. Synthetic keratoprosthesis developers targeting the Asia-Pacific corridor are restructuring regulatory strategies around PMDA dossier preparation.
Multi-source procurement is consolidating purchasing power among large ophthalmic clinic networks that previously relied on single eye bank relationships. United States hospital systems are negotiating direct tissue processing agreements that bypass traditional banking intermediaries. This concentration is most visible in metropolitan surgical centers where procedure volumes justify captive supply arrangements with quality-controlled processors.
Corneal Implants Market Segmentation
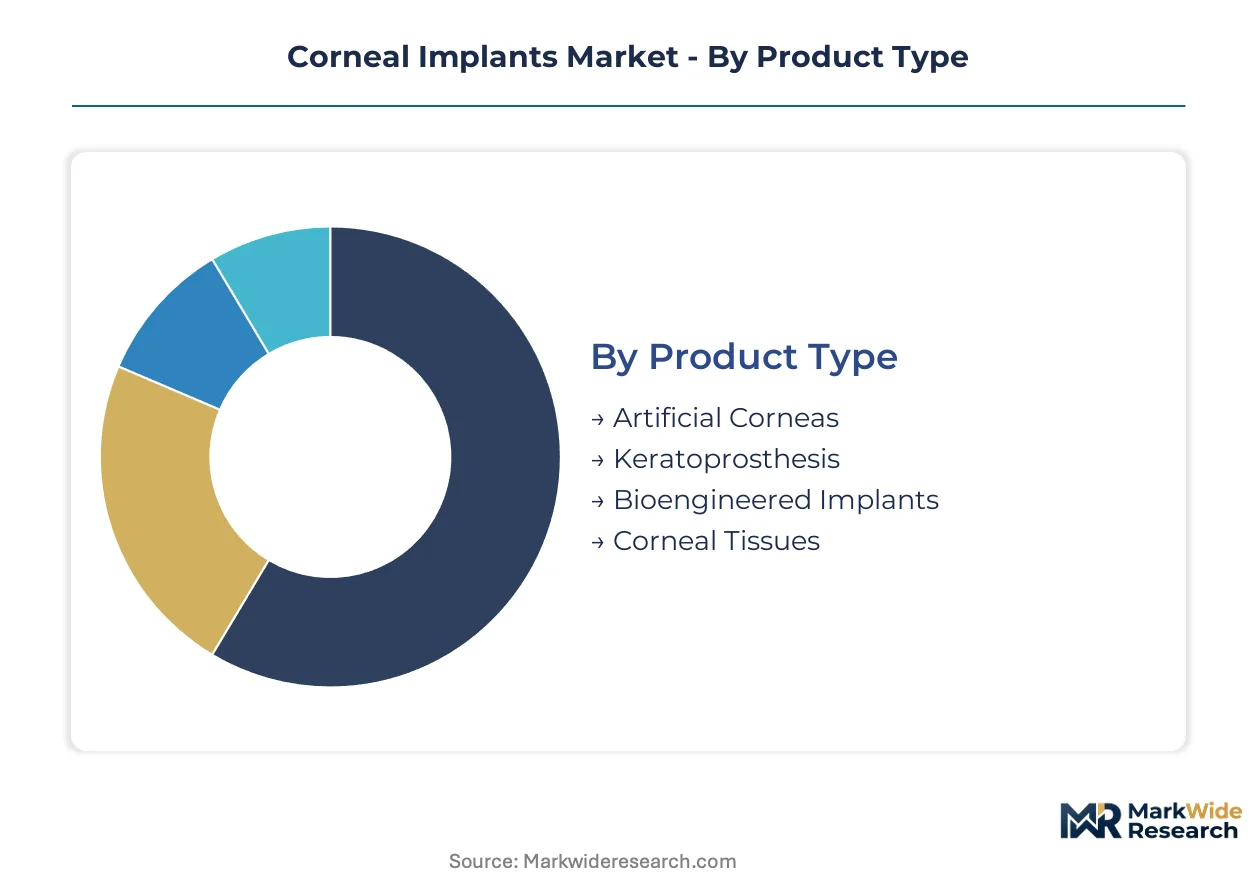
Corneal implant manufacturers configure product portfolios around distinct procurement pathways and surgical workflows. Each segmentation dimension reveals how supply chain structure, reimbursement patterns, and clinical training requirements shape commercial strategy.
Product Type:
Procurement economics separate buyers into those with captive tissue networks versus those dependent on external supply.
- Keratoprosthesis:Synthetic polymer devices manufactured from poly(methyl methacrylate) provide immediate visual rehabilitation for patients with failed donor grafts. Demand concentrates in tertiary ophthalmic centers in the United States and Germany where complex case volumes justify specialized surgical expertise and infection management protocols.
- Bioengineered Implants:Collagen matrices produced through tissue engineering techniques reduce rejection surveillance burden and extend graft survival timelines. Leading clinics in Japan and metropolitan United States surgical centers are adopting these substrates fastest as biofabrication partnerships displace traditional eye bank relationships.
- Artificial Corneas:Full-thickness synthetic replacements serve patients lacking suitable donor tissue availability.
- Corneal Tissues:Donor-derived allografts remain the standard for routine penetrating keratoplasty procedures.
Keratoprosthesis leads volumes today; bioengineered implants are climbing the fastest.
End User:
Facility scale determines whether buyers process tissue in-house or outsource to specialized intermediaries.
- Ophthalmic Clinics:Outpatient surgical centers performing high-volume corneal procedures negotiate direct agreements with tissue processors, bypassing traditional eye bank markups. United States metropolitan networks in particular are consolidating procurement through captive supply arrangements that match rising patient volumes with quality-controlled processing capacity.
- Hospitals:Integrated health systems maintain internal eye banking partnerships and regulatory chain-of-custody documentation for complex transplant networks. German university hospitals and Japanese national medical centers anchor procurement through specialized tissue allocation logistics that serve regional referral bases.
- Eye Banks:Intermediaries control donor tissue quality standards and geographic allocation priorities.
- Research Institutions:Academic centers drive preclinical validation for novel bioengineered substrates.
Ophthalmic clinics lead procedural volumes today; hospital systems are expanding implant capacity fastest.
Technology:
Capital equipment requirements and surgeon training curves segment buyers by technical sophistication and reimbursement access.
- Laser-Assisted Surgery:Femtosecond laser platforms enable precise corneal dissection and customized graft preparation. Adoption concentrates in premium ophthalmic clinics across the United States and Germany where procedure fees support capital recovery and specialized technician staffing.
- Biofabrication:Additive manufacturing and 3D bioprinting techniques produce patient-specific collagen scaffolds. Japanese regulatory frameworks for novel corneal materials are accelerating clinical validation timelines as PMDA trial mandates raise evidence standards for reimbursement eligibility.
- Traditional Surgery:Manual keratoplasty techniques remain standard in resource-constrained settings.
- Tissue Engineering:Laboratory cultivation of corneal epithelial and stromal layers supports advanced graft development.
Laser-assisted surgery dominates current procedural economics; biofabrication is expanding most quickly.
Application:
Clinical indication severity drives pricing tolerance and urgency of procurement decisions.
- Vision Restoration:Elective procedures for keratoconus and corneal dystrophy patients represent the largest addressable population. German and Japanese ophthalmic clinics report accelerating volumes as bioengineered collagen matrices reduce postoperative surveillance requirements and improve graft survival outcomes.
- Eye Trauma:Emergency penetrating keratoplasty for chemical burns and penetrating injuries demands immediate tissue availability. United States eye bank networks prioritize trauma cases through expedited allocation protocols that bypass standard waiting list queues.
- Corneal Scarring:Opacity removal procedures follow failed primary grafts or infectious keratitis sequelae.
- Disease Treatment:Therapeutic keratoplasty addresses active infectious or inflammatory conditions.
Vision restoration leads elective procedure volumes today; eye trauma applications command premium pricing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are migrating regulatory dossier preparation toward jurisdictions with accelerated approval pathways, exploiting cost-of-compliance gaps between the FDA's PMA timeline and streamlined European CE marking under MDR harmonization.
United States
Metropolitan surgical centers in New York, Los Angeles, and Chicago are scaling corneal implant capacity to match rising keratoconus procedure volumes. The FDA's premarket approval pathway for novel keratoprosthesis devices shapes manufacturer investment timelines and compresses early-mover advantages. Eye bank networks concentrated in these urban clusters prioritize trauma cases through expedited allocation protocols.
Germany
University hospitals in Munich and Heidelberg anchor procurement through specialized tissue allocation logistics serving regional referral bases. The EU Medical Device Regulation enforces harmonized biocompatibility standards that reduce regulatory fragmentation for CE marking on novel devices. Baden-Württemberg's ophthalmic clinic networks are consolidating purchasing power through direct tissue processing agreements.
Japan
PMDA-mandated local clinical trials for novel corneal materials create staggered launch timelines but raise evidence standards for reimbursement eligibility. Tokyo and Osaka metropolitan surgical centers report accelerating adoption of bioengineered collagen matrices as biofabrication partnerships displace traditional eye bank relationships. Kanto region clinics lead procedural volume expansion.
India
Aurolab's manufacturing presence in Madurai demonstrates scalable production models for synthetic keratoprosthesis alternatives serving price-sensitive markets. CDSCO oversight of medical device imports shapes competitive entry strategies for international manufacturers. Tamil Nadu's ophthalmic infrastructure supports complex transplant networks across South Asia.
Switzerland
Swissmedic's streamlined review timelines for biofabricated medical devices attract manufacturers seeking rapid European market entry. Basel and Zurich host specialized eye banking partnerships that control quality standards for engineered tissue distribution. The country's precision manufacturing base supports advanced keratoprosthesis device fabrication.
Corneal Implants Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bioengineered substrate differentiation and synthetic polymer alternatives. The vendor base stratifies across three tiers: multinational ophthalmic device conglomerates with global distribution infrastructure, regional tissue processors controlling eye bank relationships, and specialized synthetic keratoprosthesis developers. Dominant competitive moves include strategic partnerships with quality-controlled tissue processors and geographic expansion through regulatory dossier preparation in staggered launch markets.
Among North American suppliers, Alcon Inc. and CorneaGen Inc. exemplify contrasting archetypes: the former represents multinational scale with integrated global distribution, while the latter anchors regional supply through specialized eye banking partnerships. LinkoCare Life Sciences AB occupies a position within the European synthetic keratoprosthesis tier, demonstrating focused manufacturing of biofabricated tissue substitutes. These three entities collectively illustrate how procurement economics separate competitors into captive tissue networks versus external supply dependence.
| Leading Market Players |
|---|
| Alcon Inc. |
| CorneaGen Inc. |
| Aurolab |
| LinkoCare Life Sciences AB |
| Presbia PLC |
| EyeYon Medical |
| AJL Ophthalmic S.A. |
| Carl Zeiss Meditec AG |
| DIOPTEX |
| Others |
Supply Flow & Price Mechanics
Bioengineered collagen matrix production is displacing donor-tissue dependence across German and Japanese ophthalmic networks, compressing procurement costs for quality-controlled processors while concentrating supply relationships among multi-source tissue engineering partnerships. This shift simultaneously reduces eye bank markups and elevates biocompatibility certification expenses, reshaping margin distribution between synthetic keratoprosthesis manufacturers and biofabrication specialists.
Pricing Analysis
Distributor margins on donor-derived corneal tissues range from 15-25% in United States metropolitan networks, while direct-to-clinic bioengineered substrates command premium positioning based on ISO 10993 biocompatibility tier and graft survival performance. Three-tier pricing structure across premium bioengineered, standard donor tissue, and economy synthetic polymer levels separates academic medical centers from community ophthalmic clinics. Cost compression in standard donor tissue tiers is intensifying because eye bank consolidation in the United States and Germany limits allocation competition. Community ophthalmic clinics exhibit highest price sensitivity; tertiary referral centers prioritize graft outcomes over unit economics.
Supply Chain Analysis
Dual-sourcing requirements now mandate that United States hospital systems qualify both domestic eye bank networks and European biofabrication partners to secure keratoprosthesis supply continuity. Manufacturing concentrates in the United States, Germany, and Japan, with Switzerland emerging as a precision fabrication hub for synthetic polymer devices. Raw material dependencies center on pharmaceutical-grade collagen isolates, poly(methyl methacrylate) resin, and recombinant growth factor additives. Single-source vulnerability persists in donor tissue networks concentrated in select metropolitan eye banking clusters. Distribution runs through specialized tissue processors that maintain cold-chain custody documentation for regulatory compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers exploit the 18-24 month gap between FDA PMA timelines and Swissmedic's accelerated biofabricated device reviews to establish European revenue bases before United States market entry.
For Market Incumbents: Hedge against bioengineered implant commoditization by securing captive collagen matrix supply through backward integration into tissue engineering partnerships, particularly in Baden-Württemberg's precision manufacturing corridor. Eye bank relationship consolidation represents a secondary defensive lever against synthetic keratoprosthesis entrants.
For New Entrants and Emerging Players: Eye banks seeking biofabrication partnerships present the most penetrable channel opportunity, as traditional intermediaries face displacement pressure from direct clinic-processor agreements. Target Japanese PMDA regulatory dossier preparation as a first-mover wedge, leveraging local clinical trial mandates that extend incumbent launch timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap synthetic keratoprosthesis developers with CE marking but pending FDA submission. Long-term viability hinges on bioengineered substrate pipelines displacing donor tissue dependence within the next decade. Watch PMDA reimbursement eligibility decisions for novel collagen matrices as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Regulatory Dossier Preparation | Japanese clinical trial mandates create first-mover advantages for bioengineered implant developers establishing local evidence bases. |
| Eye Bank Partnership Consolidation | Direct agreements with quality-controlled processors bypass traditional banking intermediaries and secure tissue allocation priority. |
| ISO 10993 Biocompatibility Certification | Harmonized testing protocols accelerate CE marking timelines under EU MDR and reduce staggered validation requirements. |
| Biofabrication Capacity Expansion | Collagen matrix production scale-up in Germany and Switzerland displaces donor tissue dependence for keratoconus interventions. |
| Hospital System GPO Contracting | Group purchasing organization agreements with metropolitan surgical networks lock in procedural volume commitments. |
Methodological Framework
Coverage spans the United States, Germany, Japan, and Switzerland, with primary inputs from each jurisdiction's regulatory cluster. The analysis combines structured interviews with ophthalmic surgeons, eye bank operations directors, biomedical engineers, and GPO contracts managers with secondary validation from FDA PMA filings, PMDA submission databases, Swissmedic device registries, and EU MDR notified body documentation. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue allocations.
Granularity-level framing models product type, end user facility scale, surgical technology, and clinical application at the country level, with reimbursement pathway and regulatory cluster as cross-cutting dimensions. CAGRs derive from logistic growth curve fitting to historical procedural data and elasticity-adjusted adoption projections for bioengineered substrates. Forecast inputs incorporate eye bank tissue availability constraints, PMDA trial completion timelines, and ISO tissue engineering standard evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biofabrication scale-up economics and donor tissue allocation policy shifts. Projections reflect assumptions regarding regulatory harmonization progress and biocompatibility certification streamlining. Deviation in PMDA reimbursement eligibility timelines or FDA PMA backlog duration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Cheek Implants Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Venturi Mask Market
Medical Devices
Heating Pads Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Implantable Port Devices Market