
 Lyophilized Injectable Market | 2026-2036
Lyophilized Injectable Market Size, Share, and Industry Trends Forecast 2026-2036
Lyophilized Injectable Market Outlook
Multi-source API procurement is broadening across lyophilized injectable supply chains as manufacturers reduce dependency on single freeze-drying contractors. Pfizer leverages captive lyophilization suites across North American and European sites to secure biologics output. Vetter Pharma specializes in contract freeze-drying services for complex peptides and monoclonal antibodies. B. Braun Melsungen anchors European hospital supply through vertically integrated sterile fill-finish and lyophilization lines.
Lyophilized injectables are sterile biologic or small-molecule formulations dehydrated via sublimation under vacuum to achieve chemical stability, typically reconstituted with sterile water for injection before administration. The freeze-drying cycle involves controlled freezing at minus 40 to minus 50 degrees Celsius followed by primary and secondary drying to residual moisture below three percent, preserving protein tertiary structure for multi-year shelf life. Proteins and peptides dominate current revenue pools given the thermal lability of large-molecule biotherapeutics. Vaccines represent the fastest-expanding product category as mRNA and viral-vector platforms require lyophilized stabilization for tropical distribution. Oncology leads therapy-area demand due to the expansion of checkpoint inhibitors and antibody-drug conjugates requiring parenteral delivery.
FDA current Good Manufacturing Practice regulations and EMA guidelines on sterile medicinal products govern lyophilization validation, container-closure integrity, and particulate matter limits. The EU GMP Annex 1 revision mandates enhanced barrier technology and real-time monitoring for aseptic processing, directly raising capital requirements for freeze-dryer upgrades. Stakeholders must weigh in-house lyophilization investment against contract manufacturing partnerships as regulatory scrutiny intensifies and biologic pipeline complexity deepens.
Market Dynamics
Biologics pipeline complexity is forcing manufacturers to choose between captive lyophilization investment and contract partnerships as regulatory scrutiny intensifies across FDA and EMA jurisdictions. The structural pressure centers on validation requirements for aseptic freeze-drying cycles that preserve protein tertiary structure.
Growth Catalysts
- mRNA Platform Expansion:Viral-vector and nucleic acid vaccines require lyophilized stabilization for tropical distribution, creating pull-through demand for freeze-drying capacity.
- EU GMP Annex 1 Revision:Enhanced barrier technology mandates are accelerating facility upgrades among sterile injectable manufacturers seeking compliance.
- Oncology Biologics:Checkpoint inhibitors and antibody-drug conjugates require parenteral delivery formats that freeze-drying stabilizes for multi-year shelf life.
Market Restraints
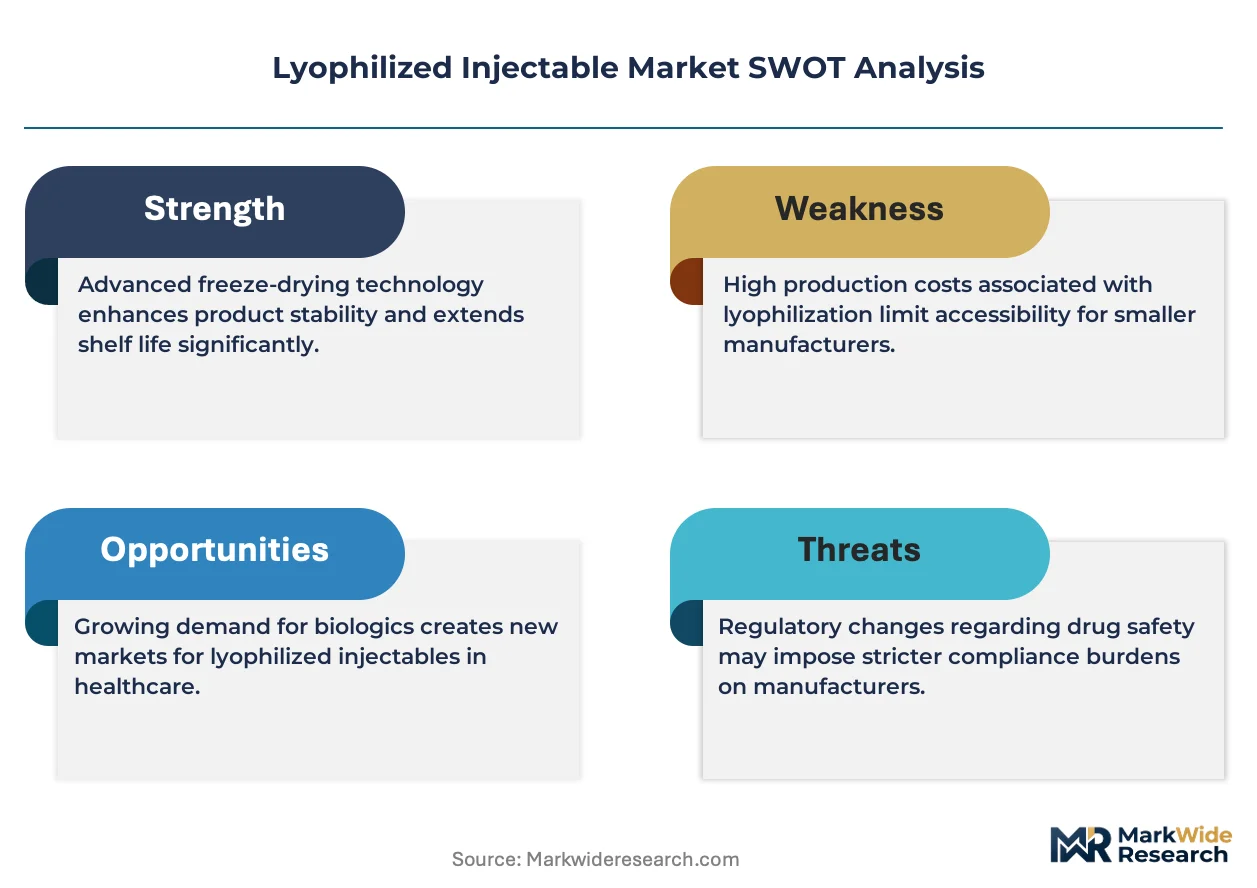
- Freeze-Dryer Capital Intensity:Commercial-scale lyophilization suites require substantial investment, concentrating supply among established equipment vendors and contract manufacturers.
- Single-Source API Risk:Dependency on limited freeze-drying contractors for complex peptides creates vulnerability in biologics supply chains.
- Residual Moisture Validation:FDA current Good Manufacturing Practice requirements for sub-three-percent moisture content extend cycle development timelines.
Strategic Opportunities
- Indian Contract Manufacturing:CDSCO regulatory alignment with ICH standards positions domestic freeze-drying capacity for export to regulated markets.
- Continuous Freeze-Drying:Integration of process analytical technology with lyophilization cycles enables real-time release testing and reduced batch variability.
- Prefilled Reconstitution Systems:Dual-chamber syringes and vial-adapter technologies streamline clinical administration of lyophilized biologics.
Industry Challenges
- Lyophilization Cycle Development:Formulation scientists with protein stabilization expertise remain scarce relative to biologics pipeline expansion.
- Container-Closure Integrity Testing:EMA guidelines on sterile medicinal products require enhanced validation protocols that extend qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lyophilized Injectable Market |
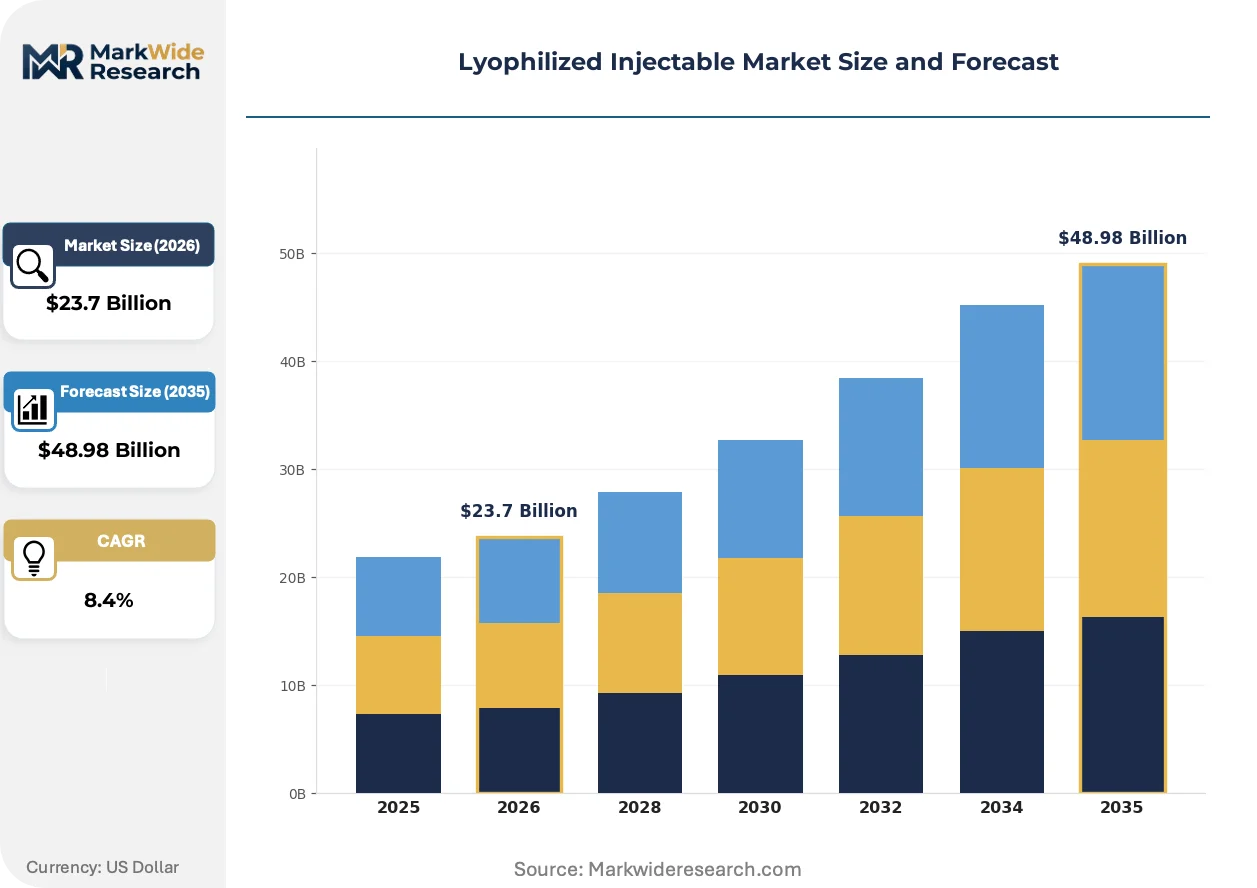
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteins, Peptides, Vaccines, Enzymes Therapy Area: Oncology, Infectious Diseases, Autoimmune Disorders, Cardiovascular End User: Hospitals, Clinics, Pharmaceutical Companies, Research Institutions Packaging Type: Vials, Ampoules, Pre-filled Syringes, Blister Packs |
| Companies Covered | Pfizer, Roche, Merck, Sanofi, Baxter International, Johnson & Johnson, Novartis, B. Braun Melsungen, Vetter Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lyophilized Injectable Market Strategic Shifts
Freeze-drying operations are converging with digital process control and advanced containment systems as manufacturers respond to tightening aseptic processing standards. The shift centers on reducing batch failure risk while compressing cycle times.
Process analytical technology is automating lyophilization cycle control through inline near-infrared spectroscopy and mass spectrometry that monitor ice sublimation endpoints in real time. Biopharmaceutical manufacturers deploying these systems at commercial scale are reducing primary drying duration by eliminating conservative safety margins. The structural consequence is compressing batch release timelines while improving vial-to-vial uniformity.
EMA's revised Annex 1 on sterile medicinal products is mandating isolator-based barrier technology and continuous environmental monitoring for aseptic processing lines. Freeze-dryer loading systems must now demonstrate validated robotic transfer or closed restricted access barriers. European manufacturers are retrofitting existing suites or specifying new isolator-integrated lyophilization lines to meet compliance deadlines.
Hospital procurement of lyophilized injectables is consolidating through group purchasing organizations that negotiate multi-year supply agreements with freeze-dried parenteral specialists. The channel shift favors manufacturers with demonstrated cold-chain reliability and redundant production sites. Germany and Japan exhibit the most concentrated buying power, with university hospital networks standardizing on preferred supplier formularies for oncology biologics.
Lyophilized Injectable Market Segmentation
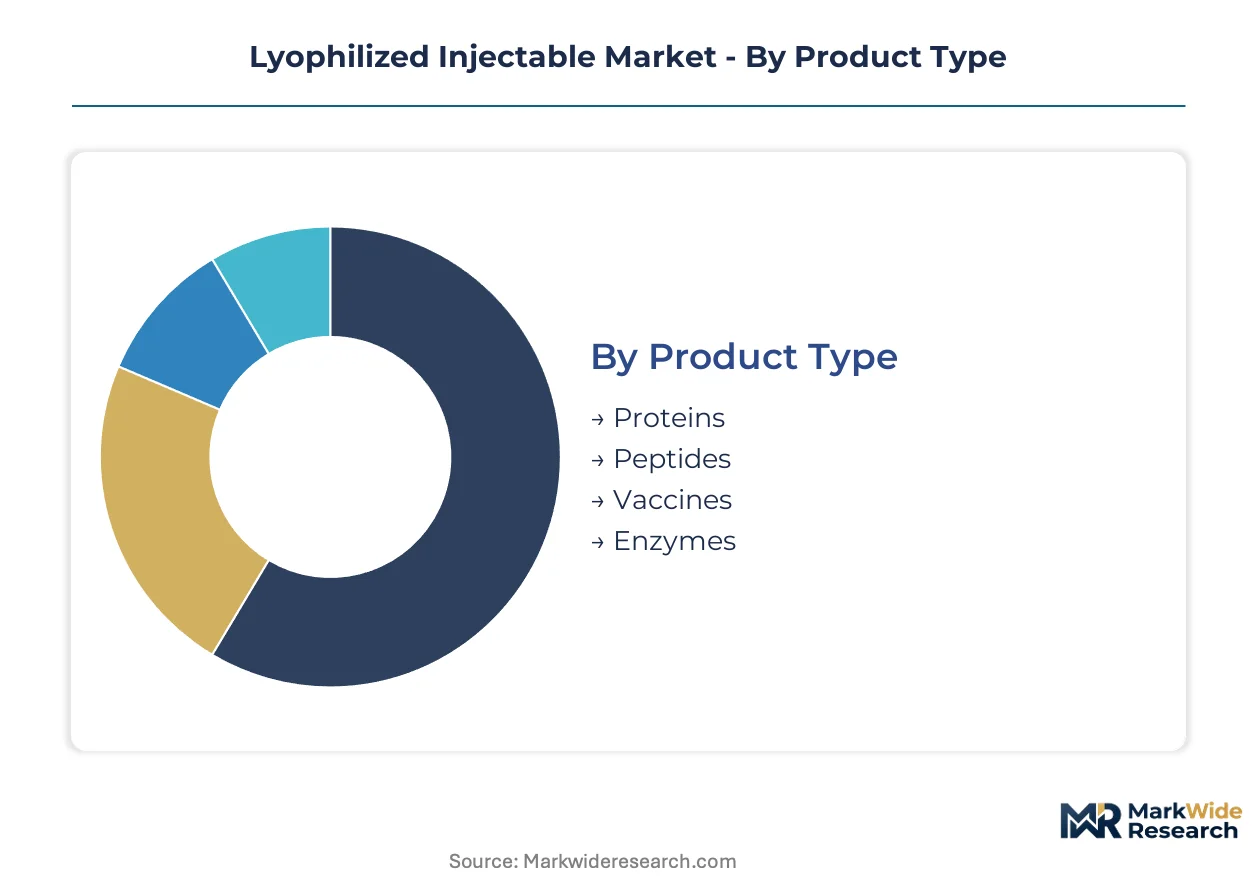
Lyophilized injectable segmentation reveals how formulation complexity, therapeutic application, and delivery format intersect to determine manufacturing requirements and commercial strategy. Each dimension carries distinct regulatory, technical, and economic implications for stakeholders across the value chain.
Product Type:
Proteins dominate current revenue pools given their thermal lability and structural complexity, while vaccines command premium capacity investments for emerging platform technologies.
- Proteins:Monoclonal antibodies and recombinant therapeutic proteins require precise tertiary structure preservation through controlled sublimation cycles. Demand concentrates in United States and Germany where oncology biologics procurement runs through consolidated hospital networks facing FDA and EMA stability validation requirements.
- Vaccines:mRNA and viral-vector platforms require lyophilized stabilization for distribution beyond cold-chain infrastructure. Tropical market access in Brazil and India is driving freeze-drying capacity expansion as manufacturers seek WHO prequalification pathways.
- Peptides:Complex synthetic peptides with limited chemical stability benefit from dehydration to extend shelf life beyond aqueous limitations.
- Enzymes:Replacement enzyme therapies for rare metabolic disorders utilize lyophilization to maintain catalytic activity through multi-year storage.
Mature deployment sits with Proteins. Newer deployment is concentrated in Vaccines.
Therapy Area:
Oncology biologics anchor current manufacturing volumes, while infectious disease applications are expanding fastest through vaccine platform proliferation.
- Oncology:Checkpoint inhibitors and antibody-drug conjugates require parenteral delivery formats that freeze-drying stabilizes for extended shelf life. United States academic medical centers and German university hospital networks represent the concentrated procurement channel, with FDA and EMA batch release testing governing supply qualification.
- Infectious Diseases:Viral and bacterial vaccines against emerging pathogens require lyophilized presentation for field deployment. Japanese and Australian public health procurement is expanding freeze-dried stockpile contracts as PMDA and TGA align stability standards with ICH guidelines.
- Autoimmune Disorders:TNF-alpha inhibitors and interleukin blockers utilize lyophilized formulations to reduce injection frequency and improve patient adherence.
- Cardiovascular:Thrombolytic enzymes and natriuretic peptides employ freeze-drying for emergency department reconstitution protocols.
Revenue concentration favors Oncology. Capacity expansion is accelerating in Infectious Diseases.
End User:
Hospital procurement runs through group purchasing organizations that negotiate multi-year supply agreements, while pharmaceutical companies retain captive capacity for pipeline assets.
- Hospitals:Consolidated buying power through group purchasing organizations in Germany and Japan favors suppliers with redundant production sites and demonstrated cold-chain reliability. University hospital networks standardize preferred supplier formularies for oncology biologics.
- Pharmaceutical Companies:Biopharmaceutical manufacturers weigh in-house lyophilization investment against contract partnerships as FDA and EMA regulatory scrutiny intensifies and pipeline complexity deepens.
- Clinics:Outpatient infusion centers require smaller batch sizes and flexible reconstitution protocols for specialist-administered biologics.
- Research Institutions:Clinical trial material supply demands rapid cycle development and adaptive packaging for investigational freeze-dried parenterals.
Volume leadership rests with Hospitals. Strategic control sits with Pharmaceutical Companies.
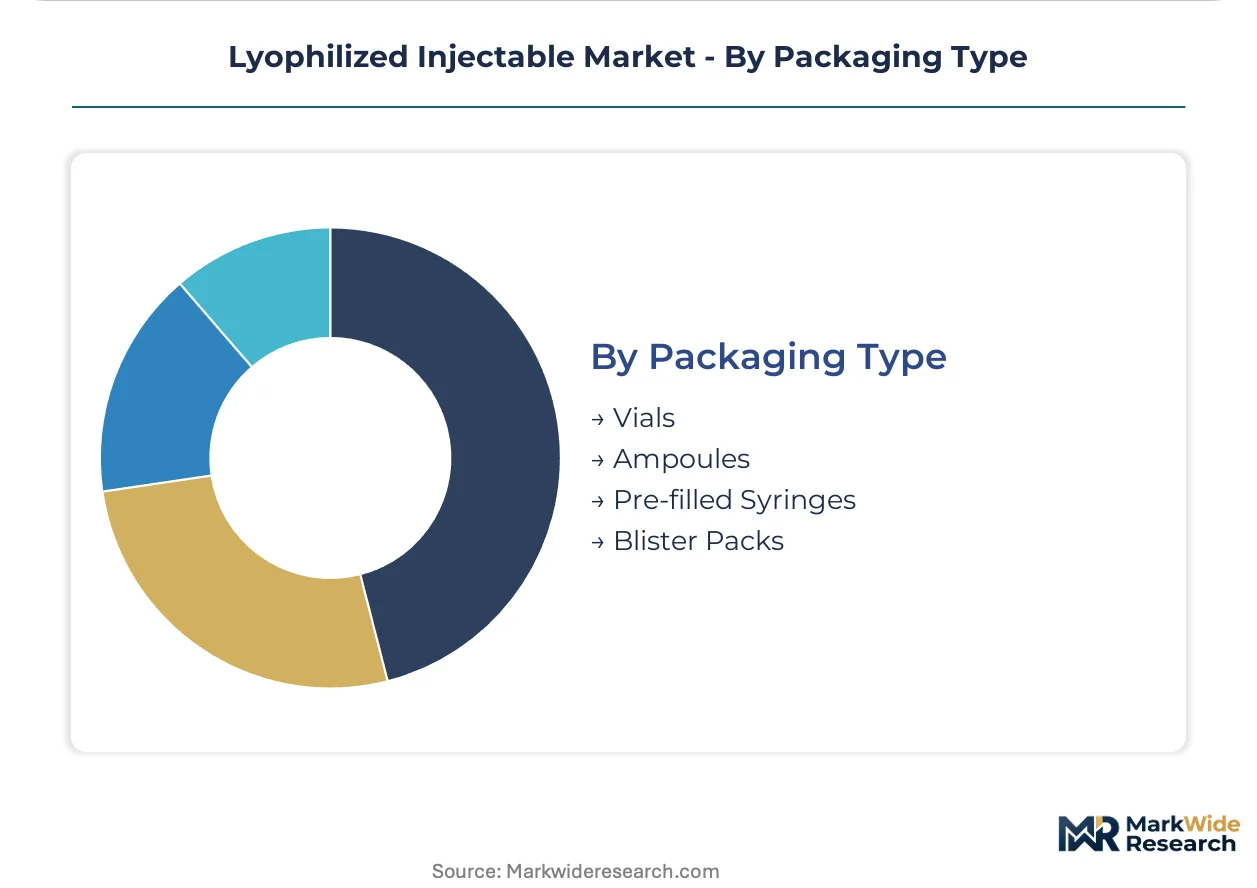
Packaging Type:
Vials retain dominant share through established fill-finish infrastructure, while pre-filled syringes command development investment for administration convenience.
- Vials:Standard borosilicate glass vials with bromobutyl stoppers remain the default container for lyophilized biologics, supported by validated robotic loading systems and isolator-integrated lyophilization lines mandated under EMA Annex 1 revisions.
- Pre-filled Syringes:Dual-chamber designs enable reconstitution at point of care without separate diluent handling. Japanese and United States regulatory pathways for combination products are driving development investment.
- Ampoules:Single-use glass containers serve cost-sensitive generic injectables with simpler stability profiles.
- Blister Packs:Unit-dose presentations for field vaccination campaigns prioritize portability over reconstitution precision.
Installed base favors Vials. Innovation investment targets Pre-filled Syringes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement networks in the United States, Germany, and Japan concentrate lyophilized injectable demand through consolidated group purchasing organizations. Cold-chain infrastructure maturity and regulatory stringency determine where freeze-dried biologics command premium pricing.
United States
FDA stability validation requirements for freeze-dried parenterals drive contract manufacturing decisions among biopharmaceutical sponsors. Academic medical centers in Boston and the Research Triangle anchor oncology biologics procurement through multi-year supply agreements. Pfizer leverages captive lyophilization suites across North American sites to secure biologics output.
Germany
EMA Annex 1 revisions on enhanced barrier technology mandate isolator-integrated lyophilization lines for aseptic processing compliance. University hospital networks in Bavaria and North Rhine-Westphalia standardize preferred supplier formularies for checkpoint inhibitors. B. Braun Melsungen anchors European hospital supply through vertically integrated sterile fill-finish operations.
Japan
PMDA alignment with ICH stability guidelines accelerates freeze-dried vaccine registration for tropical distribution partnerships. Public health procurement in Tokyo and Osaka expands stockpile contracts for viral-vector platforms. Dual-chamber prefilled syringe development targets Japanese regulatory pathways for combination products.
India
CDSCO regulatory alignment with ICH standards positions domestic freeze-drying capacity for export to regulated markets. Contract manufacturing clusters in Maharashtra and Gujarat serve biopharmaceutical sponsors seeking cost-advantaged lyophilization. WHO prequalification pathways drive capacity expansion for mRNA vaccine stabilization.
Switzerland
Swissmedic oversight of sterile medicinal products governs container-closure integrity testing for high-value biologics. Basel and Zurich host formulation development specialists serving global biopharmaceutical pipelines. Roche maintains captive lyophilization infrastructure for complex protein therapeutics.
Lyophilized Injectable Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers retrofit isolator-integrated lines to meet EMA Annex 1 deadlines. The vendor base separates into three tiers: integrated pharmaceutical conglomerates with captive freeze-drying infrastructure, specialized contract development and manufacturing organizations, and regional hospital supply specialists. Strategic archetypes include biologics originators securing supply chain control and CDMOs building regulatory-compliant capacity for export markets. Competitive intensity centers on M&A activity targeting freeze-drying expertise and geographic expansion into Indian and Swiss contract manufacturing hubs.
Within the integrated pharmaceutical tier, Pfizer and Roche exemplify backward integration strategies that reduce dependency on external freeze-drying contractors. Among specialized service providers, Vetter Pharma occupies a position representing the contract manufacturing archetype focused on complex peptides and monoclonal antibodies. These three anchors demonstrate how scale, specialization, and regulatory proximity define competitive positioning as FDA and EMA scrutiny intensifies.
| Leading Market Players |
|---|
| Pfizer |
| Roche |
| Merck |
| Sanofi |
| Baxter International |
| Johnson & Johnson |
| Novartis |
| B. Braun Melsungen |
| Vetter Pharma |
| Others |
Value Chain & Pricing Dynamics
Captive lyophilization infrastructure anchors supply positioning and pricing power for biopharmaceutical manufacturers navigating FDA and EMA validation requirements. The choice between in-house freeze-drying suites and contract partnerships directly shapes margin structures as regulatory scrutiny intensifies across United States and European jurisdictions.
Pricing Analysis
Service bundling separates contract manufacturers offering integrated formulation development from commodity freeze-drying houses. Pricing stratifies across premium, standard, and economy tiers based on regulatory compliance history and cold-chain reliability guarantees. Cost compression in the economy tier is intensifying because Indian CDSCO-aligned facilities are expanding capacity for export markets. Hospital group purchasing organizations in Germany exhibit the highest price sensitivity, while United States academic medical centers prioritize supplier redundancy over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for pharmaceuticals are reshaping sourcing patterns for freeze-drying equipment and sterile packaging materials. Manufacturing concentrates in United States, Germany, and Switzerland where isolator-integrated lyophilization lines meet EMA Annex 1 requirements. Active pharmaceutical ingredients and specialized stoppers draw from limited qualified suppliers, creating single-source vulnerability for complex biologics. Distribution runs through hospital group purchasing organizations and pharmaceutical company captive networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where control over freeze-drying capacity determines supply security. Biopharmaceutical sponsors are pursuing backward integration into formulation development to reduce dependency on contract manufacturing partnerships.
For Market Incumbents: Deepen isolator-integrated lyophilization investments across redundant production sites to defend against emerging Indian contract manufacturers capturing regulated-market share. Prioritize EMA Annex 1 compliance deadlines as a certification lever to extend qualification timelines for competitors lacking barrier technology infrastructure.
For New Entrants and Emerging Players: Enter via Indian CDSCO-aligned freeze-drying capacity serving biopharmaceutical sponsors seeking cost-advantaged alternatives to European and North American contract manufacturers. Target mRNA vaccine stabilization as the most penetrable segment, leveraging WHO prequalification pathways for tropical distribution partnerships.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by pharmaceutical conglomerates seeking captive lyophilization expertise. Long-term viability hinges on regulatory proximity to FDA and EMA jurisdictions. Watch for CDSCO regulatory alignment announcements as the inflection signal for Indian contract manufacturing competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Integrated Lyophilization Line Deployment | EMA Annex 1 compliance mandates barrier technology upgrades across European sterile processing facilities. |
| CDSCO Regulatory Alignment Investment | Indian contract manufacturers gain export access to FDA and EMA jurisdictions through ICH standard adoption. |
| Dual-Chamber Prefilled Syringe Development | Japanese PMDA combination product pathways drive point-of-care reconstitution convenience for oncology biologics. |
| Continuous Freeze-Drying Technology Integration | Process analytical technology enables real-time release testing and compresses batch variability for protein stabilization. |
| Multi-Site Cold-Chain Redundancy Buildout | German hospital group purchasing organizations require demonstrated supply reliability for preferred supplier formulary inclusion. |
Study Parameters
Multi-period observation of freeze-dryer capacity expansions, regulatory submission timelines, and hospital procurement contract awards anchored the trend analysis, supplemented by interviews with formulation development executives, regulatory affairs leads, hospital procurement managers, and contract manufacturing officers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and WHO prequalification databases. Bottom-up and top-down triangulation reconciled equipment vendor shipment data with biopharmaceutical sponsor pipeline disclosures.
Input-output matrices mapped lyophilization cycle development timelines against therapy area demand across the projection horizon. Segmentation dimensions modeled included product type, therapy area, end user, and packaging format alongside regional regulatory cluster differentiation. CAGRs were derived through regression analysis of historical capacity utilization and forward pipeline density. Forecast inputs incorporated EMA Annex 1 implementation schedules and CDSCO regulatory alignment milestones.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated mRNA platform proliferation or delayed barrier technology retrofits. Forecasts reflect assumptions documented in the analytical framework. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
South Korea ECG Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Facial Implant Market