
 US Lubricants Market | 2026-2036
US Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
US Lubricants Market Intelligence
Gulf Coast refining corridors are reconfiguring blending capacity to serve both domestic automotive service shops and export terminals. ExxonMobil Corporation leverages its integrated base oil production in Baytown to supply downstream formulators. Valvoline Inc. competes through quick-lube channel control, with over 1,700 company-owned and franchised locations. Chevron Corporation anchors industrial demand via its ISOSYN technology platform and direct sales to mining and power generation accounts.
Lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with viscosity grades typically ranging from ISO VG 32 to ISO VG 680 for industrial applications and SAE 0W-16 to SAE 60 for automotive engines. Synthetic formulations command premium positioning due to extended drain intervals and thermal stability under severe operating conditions, while mineral oil products retain volume leadership in price-sensitive fleet maintenance segments. Industrial machinery applications generate the most stable margin pools through long-term supply contracts with manufacturing and energy end users.
The EPA regulates lubricant environmental impact through used oil management standards under RCRA, while the Department of Transportation imposes fuel economy mandates that indirectly shape viscosity grade demand through OEM specifications. California Air Resources Board enforces the strictest state-level requirements, pushing low-viscosity and re-refined product categories. OSHA workplace exposure limits for metalworking fluids further constrain formulation choices in manufacturing settings. Stakeholders must track state-level low-carbon fuel standard expansions and OEM warranty specification shifts to anticipate grade-mix transitions.
Market Dynamics
Fleet operators in commercial trucking are accelerating synthetic lubricant adoption to extend drain intervals and reduce vehicle downtime, while EPA emissions standards for heavy-duty engines force reformulation toward lower-viscosity grades that improve fuel economy.
Growth Catalysts
- EPA Tier 3 Emissions Standards:Mandates for heavy-duty diesel engines compel OEMs to specify lower-viscosity lubricants that reduce friction losses and improve fuel efficiency across commercial vehicle fleets.
- Synthetic Formulation Technology:Polyalphaolefin and ester-based base oils deliver thermal stability and extended drain intervals that cut maintenance costs for long-haul trucking operators.
- Texas Petrochemical Infrastructure:Concentrated blending capacity along the Gulf Coast supports rapid product formulation and cost-efficient export logistics to Latin American markets.
Market Restraints
- Base Oil Supply Concentration:Domestic production of Group II and Group III base oils clusters in Texas and Louisiana, creating geographic vulnerability to hurricane-related supply disruptions.
- Group I Refinery Closures:Conversion of older refineries to higher-value products eliminates economical mineral oil supply for price-sensitive fleet maintenance segments.
- Used Oil Re-refining Capacity Limits:RCRA compliance costs and permitting delays constrain expansion of re-refined base oil production despite California Air Resources Board preferences for circular supply.
Strategic Opportunities
- California Low-Carbon Fuel Standard:State-level carbon intensity scoring creates premium positioning for lubricants with verified lifecycle emissions reductions and re-refined content.
- Wind Turbine Gearbox Maintenance:Expanding installed base of utility-scale wind generation in Texas and the Great Plains drives demand for synthetic industrial gear oils with 10-year service life.
- Quick-Lube Channel Digitization:Mobile scheduling platforms and predictive maintenance integration enable direct consumer relationships outside traditional automotive service shop networks.
Industry Challenges
- Formulation Chemist Shortage:Retirement of experienced additive blending specialists outpaces university pipeline output, compressing R&D timelines for OEM specification approvals.
- Multi-State Regulatory Fragmentation:Divergent state-level requirements for metalworking fluid disposal and re-refined oil labeling force redundant compliance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Lubricants Market |
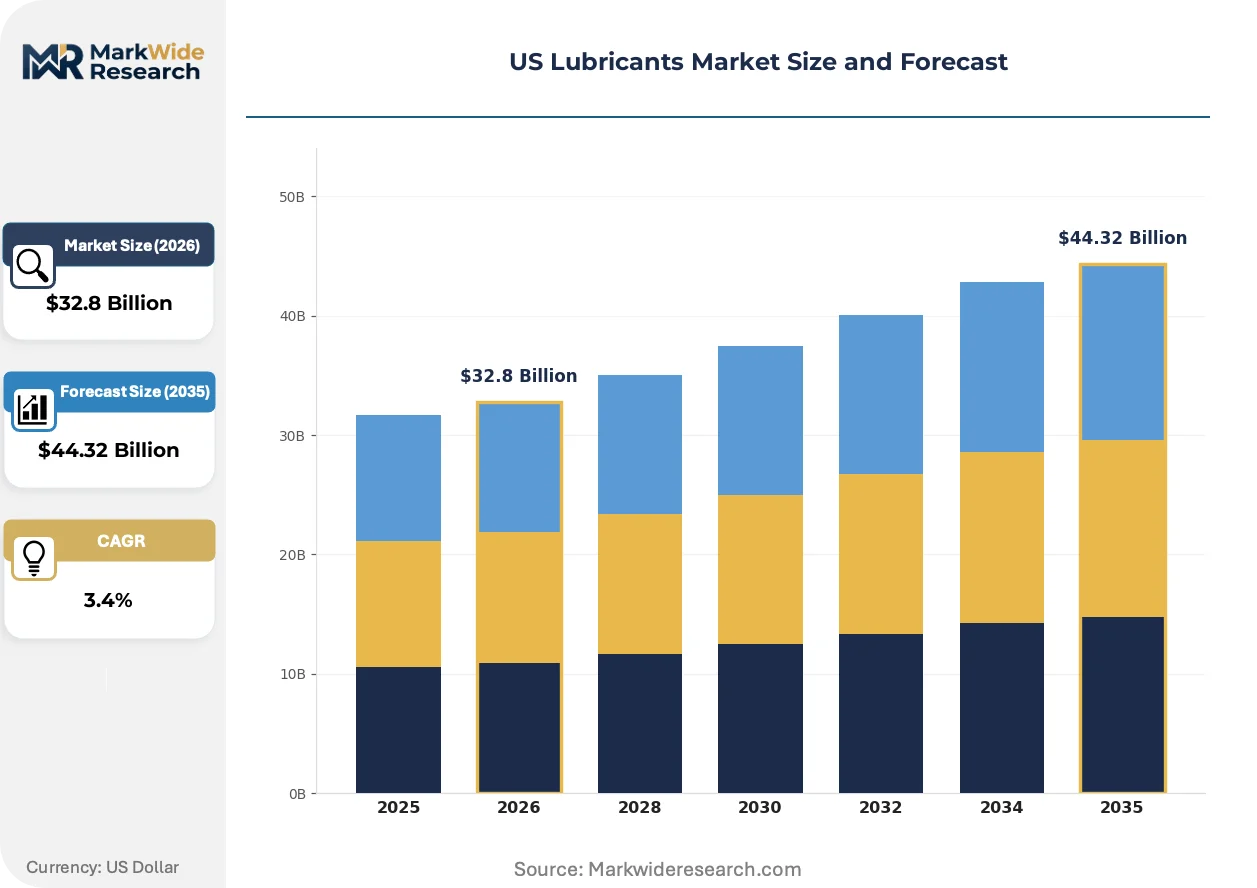
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $44.32 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Mineral, Biodegradable, Semi-Synthetic Application: Automotive, Industrial Machinery, Marine, Aerospace End User: Manufacturing, Transportation, Construction, Energy Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Shell USA, Inc., BP America Inc., TotalEnergies Marketing USA, Inc., Phillips 66 Company, Valvoline Inc., Fuchs Lubricants Co., AMSOIL Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Lubricants Market Strategic Shifts & Innovations
Digital fluid monitoring systems and predictive analytics are transforming how fleet managers schedule maintenance, compressing the traditional fixed-interval drain model toward condition-based service that optimizes lubricant consumption and asset uptime.
Cloud-connected oil analysis platforms is virtualizing the conventional laboratory testing workflow for used lubricant diagnostics. Commercial trucking fleets with 500-plus vehicle counts are deploying these systems fastest, replacing quarterly send-out samples with real-time viscosity and contamination alerts. The technology is virtualizing aftermarket service relationships by enabling direct manufacturer-to-fleet technical support that bypasses distributor networks.
The Department of Transportation's Phase 2 greenhouse gas standards for medium- and heavy-duty vehicles mandate incremental fuel economy improvements that OEMs achieve partly through lower-viscosity engine oil specifications. Engine manufacturers are locking SAE 10W-30 and 5W-30 grades into warranty requirements, displacing legacy 15W-40 volumes in new vehicle segments. California Air Resources Board enforcement of the strictest state-level standards accelerates this grade-mix transition in the West Coast market.
Consolidation among national quick-lube chains is reshaping how branded lubricants reach consumer vehicle owners. Independent service shops in the Midwest and Southeast are losing share to standardized franchise formats that negotiate exclusive supply agreements and centralize inventory management. Fleet maintenance divisions at regional trucking companies are mirroring this concentration by awarding multi-year sole-source contracts to integrated suppliers with captive base oil production.
US Lubricants Market Segmentation
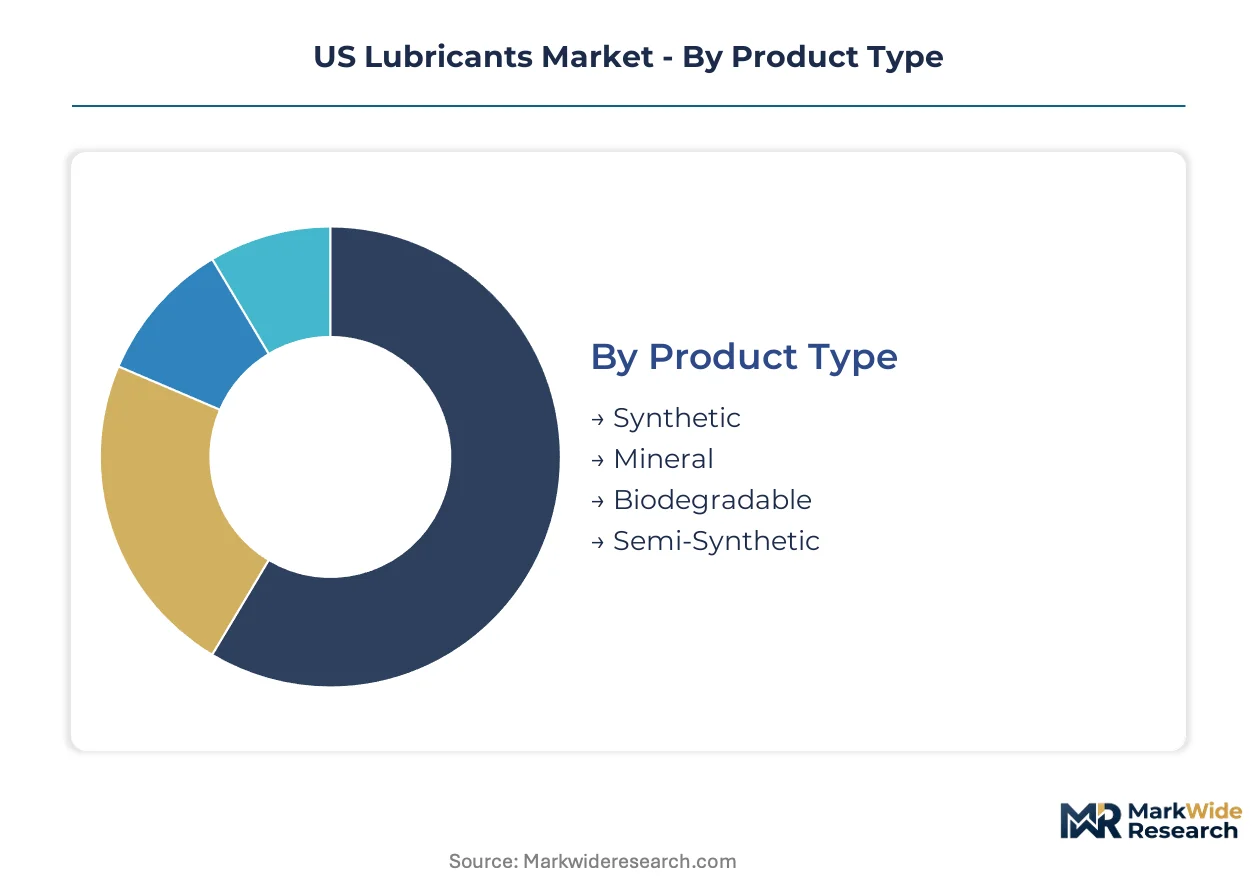
Segmentation reveals how lubricant procurement patterns diverge across technical specifications and operational contexts. Each dimension exposes distinct margin structures, specification requirements, and channel economics that shape supplier positioning.
Product Type:
After-sales-service intensity varies sharply across formulation chemistry, with synthetic products demanding technical support for drain interval optimization while mineral oils rely on volume logistics.
- Synthetic:Polyalphaolefin and ester-based formulations deliver thermal stability under severe operating conditions. Fleet operators in long-haul trucking specify these grades to extend drain intervals and compress maintenance downtime. OEM warranty requirements for heavy-duty diesel engines are locking SAE 10W-30 and 5W-30 synthetic specifications into new vehicle segments.
- Mineral:Conventional Group I and Group II base oil formulations retain cost advantages for price-sensitive maintenance segments. Independent service shops in the Midwest and Southeast continue specifying these grades for older vehicle populations where OEM warranty constraints do not apply.
- Biodegradable:Vegetable oil and synthetic ester formulations engineered for environmental compliance in sensitive operating environments.
- Semi-Synthetic:Blended formulations balancing performance enhancement against mineral oil cost structures for mid-tier fleet segments.
Synthetic holds the largest share; momentum sits with biodegradable formulations as California Air Resources Board standards tighten.
Application:
Application context determines specification complexity, with industrial machinery requiring long-term technical partnerships while automotive service operates through transactional volume channels.
- Automotive:Engine oils, transmission fluids, and gear lubricants formulated to OEM viscosity and performance specifications. Quick-lube chains are consolidating exclusive supply agreements that displace independent service shop procurement. The Department of Transportation's Phase 2 greenhouse gas standards mandate lower-viscosity grades that improve fuel economy across passenger and commercial vehicle fleets.
- Industrial Machinery:Hydraulic fluids, compressor oils, and turbine lubricants engineered for extended service intervals under continuous operation. Manufacturing and energy end users generate the most stable margin pools through multi-year supply contracts with technical service attachments.
- Marine:Cylinder oils and system lubricants formulated for slow-speed two-stroke engines and auxiliary equipment.
- Aerospace:Synthetic turbine oils and hydraulic fluids meeting stringent military and commercial aviation specifications.
Automotive generates the highest volume; industrial machinery delivers the most durable margin structure.
End User:
End-user concentration shapes contract structure, with transportation fleets negotiating sole-source agreements while construction procurement fragments across project-based purchasing.
- Transportation:Commercial trucking fleets, railroad operators, and logistics companies with centralized lubricant procurement functions. Regional trucking companies are awarding multi-year contracts to integrated suppliers with captive base oil production and predictive maintenance integration.
- Manufacturing:Metalworking, plastics processing, and assembly operations with continuous equipment lubrication requirements. OSHA workplace exposure limits for metalworking fluids constrain formulation choices and drive specification toward low-mist synthetics.
- Construction:Heavy equipment operators and contractors with seasonal demand patterns and decentralized job site logistics.
- Energy:Power generation, oil and gas production, and renewable energy installations with specialized thermal and oxidation stability requirements.
Transportation commands the largest volume commitment; energy end users are expanding most quickly behind utility-scale wind turbine installations.
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with direct sales capturing complex industrial accounts while retail serves fragmented consumer demand.
- Wholesale:Distributor networks supplying jobbers, independent service shops, and regional fleet maintenance operations. Gulf Coast blending capacity supports rapid product formulation and cost-efficient bulk logistics to these intermediaries.
- Direct Sales:Manufacturer-to-end-user relationships for large industrial accounts with technical service requirements. Digital fluid monitoring systems are virtualizing aftermarket service relationships and enabling direct technical support that bypasses distributor networks.
- Retail:Auto parts stores and mass merchants serving DIY consumers and small independent garages.
- Online:E-commerce platforms and mobile scheduling applications emerging in quick-lube channel digitization.
Wholesale retains the deepest penetration; online channels are gaining share fastest through predictive maintenance platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards anchor demand concentration in Texas, where Gulf Coast petrochemical infrastructure supports the dominant blending and export corridor for domestic lubricant supply.
Texas
Commercial trucking fleets command the largest synthetic lubricant procurement volumes to extend drain intervals under severe operating conditions. The Texas Commission on Environmental Quality enforces used oil recycling standards that align with RCRA compliance frameworks. Houston and Baytown host concentrated base oil production and downstream formulation capacity serving both domestic automotive service networks and Latin American export terminals.
California
Low-carbon fuel standard implementation drives premium positioning for re-refined and biodegradable lubricant categories in automotive and industrial applications. The California Air Resources Board mandates the strictest state-level emissions requirements, accelerating SAE 10W-30 and 5W-30 grade adoption in heavy-duty fleets. Los Angeles and Long Beach logistics corridors concentrate quick-lube chain consolidation and predictive maintenance platform deployment.
Michigan
Automotive OEM headquarters and tier-one supplier networks generate specification-intensive demand for warranty-compliant engine oils and transmission fluids. The Michigan Department of Environment, Great Lakes, and Energy administers used oil management rules that complement federal RCRA standards. Detroit and Grand Rapids manufacturing clusters anchor metalworking fluid procurement for powertrain and component machining operations.
Illinois
Midwest distribution hub positioning captures wholesale lubricant flows to independent service shops and regional fleet maintenance operations across agricultural and construction equipment segments. The Illinois Environmental Protection Agency enforces used oil generator status thresholds that shape collector network economics. Chicago metropolitan logistics infrastructure supports bulk blending and interstate trucking distribution to Upper Midwest markets.
Pennsylvania
Marcellus Shale natural gas production and legacy industrial machinery bases sustain demand for compressor oils and hydraulic fluids in continuous-operation energy applications. The Pennsylvania Department of Environmental Protection regulates waste oil storage and transfer facility permitting. Pittsburgh and Philadelphia manufacturing corridors maintain metalworking fluid demand from specialty steel and precision machining operations.
US Lubricants Market Key Industry Players
Capability concentration sits with integrated base oil producers; scale advantage sits with quick-lube channel operators. The market structures around three tiers: multinational energy majors with captive upstream supply, national formulators with service network control, and specialty blenders targeting specification-intensive industrial niches. Dominant competitive moves include exclusive supply agreement negotiation with consolidated fleet operators and predictive maintenance platform integration to bypass traditional distributor relationships.
Within the integrated major tier, ExxonMobil Corporation anchors Gulf Coast production gravity through Baytown base oil assets, while Chevron Corporation occupies a position emphasizing industrial direct sales and mining sector technical partnerships. Valvoline Inc. exemplifies the service-channel archetype through quick-lube network control spanning company-owned and franchised locations. These three entities represent distinct strategic postures: upstream integration, industrial specification depth, and consumer-facing distribution density.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell USA, Inc. |
| BP America Inc. |
| TotalEnergies Marketing USA, Inc. |
| Phillips 66 Company |
| Valvoline Inc. |
| Fuchs Lubricants Co. |
| AMSOIL Inc. |
| Others |
Cost & Logistics Intelligence
Houston-Baytown petrochemical corridor capacity utilization directly determines downstream pricing leverage for formulators serving quick-lube chains and industrial accounts. Synthetic base oil premiums widen when Gulf Coast blending capacity tightens, while mineral oil spreads compress as Group I refinery conversions eliminate economical supply alternatives.
Pricing Analysis
Texas-to-California price spreads for SAE 5W-30 synthetic grades reflect transport cost differentials and CARB compliance premiums. Three-tier pricing structure across premium synthetics, standard mineral formulations, and economy fleet oils differentiates by drain interval certification and OEM warranty backing. Cost compression in economy mineral tiers is intensifying because Group I supply scarcity forces blenders toward higher-cost Group II feedstocks. Independent service shops in the Midwest exhibit highest price sensitivity; wind turbine operators with decade-long service contracts show least.
Supply Chain Analysis
Hurricane exposure along the Texas-Louisiana Gulf Coast dominates supply chain risk assessment for domestic base oil procurement. Geographic supply concentration clusters in the United States, with secondary sourcing from South Korea and Qatar for Group III+ ultra-high-viscosity grades. Raw material dependencies rest on ethylene-derived polyalphaolefin feedstocks, additive packages from specialty chemical manufacturers, and steel drum packaging. Single-source vulnerability exists for certain friction modifier chemistries. Distribution runs through wholesale distributor networks to independent jobbers, with direct sales capturing large industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EPA and CARB specification requirements create switching costs that lock fleet operators into approved supplier relationships across multi-year contract horizons.
For Market Incumbents: Entrench through exclusive multi-year supply agreements with consolidated regional trucking fleets and predictive maintenance platform integration that virtualizes distributor relationships. Capacity addition in Baytown-Beaumont corridor secures captive base oil supply against hurricane disruption risk. Investment in re-refining capability addresses CARB circular supply preferences before permitting delays constrain competitor expansion. For New Entrants and Emerging Players: Re-refined base oil production for California Low-Carbon Fuel Standard compliance represents the most penetrable entry point given incumbent blind spots in circular supply chain development. Wind turbine gearbox service contracts in Great Plains states offer specification-intensive niche with limited quick-lube channel competition. Go-to-market through direct technical sales to energy asset operators bypasses entrenched wholesale distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a contracted-cash-flow play because industrial machinery lubrication generates durable margin pools through decade-long service agreements with limited substitution risk. Acquisition target archetype: specialty blenders with wind turbine and mining sector technical specifications and existing OEM approval portfolios. Signal to watch is CARB low-carbon fuel standard expansion into neighboring states as volume inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive supply of Group II/III feedstocks insulates margin pressure from hurricane-related disruption events. |
| Predictive Maintenance Platform Deployment | Digital fluid monitoring virtualizes distributor relationships and enables direct manufacturer-to-fleet technical support. |
| Re-refining Capacity Expansion | California Air Resources Board carbon intensity scoring creates premium positioning for circular supply chain participants. |
| Quick-Lube Channel Consolidation | Exclusive supply agreements with standardized franchise formats displace independent service shop procurement volumes. |
| Wind Turbine Service Contract Acquisition | Ten-year synthetic gear oil specifications in utility-scale installations generate stable, non-cyclical revenue streams. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with lubricant formulators, fleet maintenance directors, quick-lube franchise operators, and base oil procurement specialists; and secondary validation through EPA regulatory filings, Department of Transportation fuel economy rulemakings, American Petroleum Institute statistical reports, and SEC 10-K disclosures from integrated energy majors. Bottom-up volume modeling across product type, application, end user, and distribution channel segments was triangulated against top-down macroeconomic drivers.
Forecast inputs considered OEM warranty specification shifts, EPA Tier 3 and Phase 2 greenhouse gas compliance timelines, and California Low-Carbon Fuel Standard carbon intensity scoring mechanics across the analysis window. Segmentation dimensions modeled include formulation chemistry tier, automotive versus industrial application context, transportation fleet versus manufacturing end-user concentration, and wholesale versus direct sales channel structure. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints.
Stress conditions across hurricane frequency, base oil refinery conversion rates, and CARB regulatory expansion timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding specification transition speeds and fleet turnover rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Bio-Based Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
South Korea Automotive Lubricants Market
Lubricants
Israel Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Brazil Lubricants Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Africa Lubricants Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Canada Lubricants Market