
 United Kingdom Lubricants Market | 2026-2036
United Kingdom Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Lubricants Market Analytics
Aftermarket service revenue is reconfiguring margin pools away from base-oil sales toward fluid analysis and condition monitoring contracts. Shell plc leverages its upstream integration to secure advantaged feedstock access across North Sea operations. Fuchs Petrolub SE specializes in high-performance industrial greases for precision machinery, anchoring its position in the manufacturing segment. BP p.l.c. competes through its Castrol brand strength in motorsport-derived automotive formulations.
Lubricants are formulated mixtures of base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with synthetic variants achieving viscosity indices exceeding 140 for extreme-temperature stability. Their primary commercial purpose spans engine protection, industrial process efficiency, and equipment longevity across capital-intensive industries. The automotive application segment dominates volume throughput, while biodegradable product types capture expanding margin pools from environmental compliance premiums. Synthetic formulations lead technology positioning, though mineral oil maintains cost-sensitive segments through established supply infrastructure.
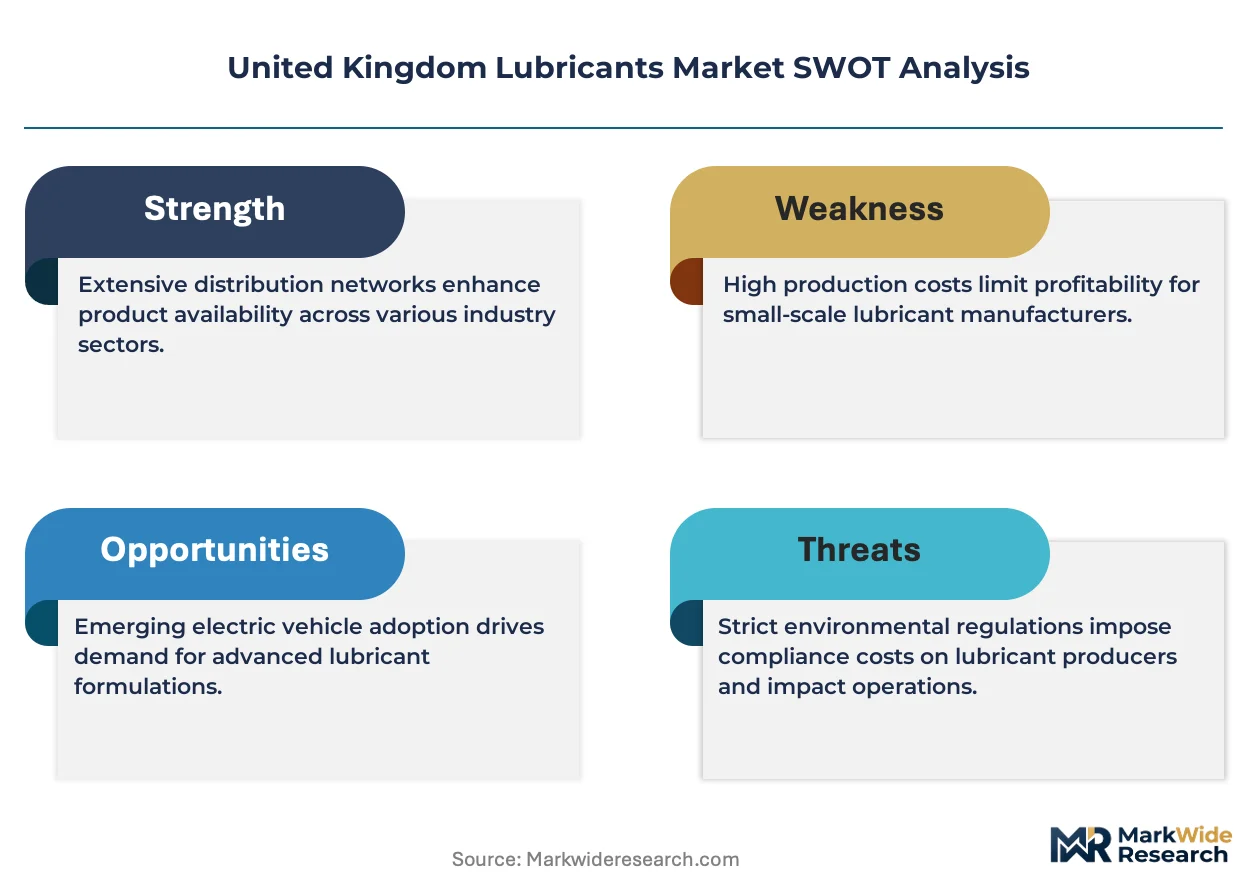
The UK's Environment Agency enforces waste-oil recovery mandates under environmental permitting regulations, while REACH compliance administered by the Health and Safety Executive governs chemical substance registration and restriction. The EU F-Gas Regulation's residual influence and domestic carbon-reduction commitments pressure reformulation toward lower-viscosity, energy-efficient grades. Stakeholders must monitor evolving UKCA marking requirements and potential divergence from EU chemical standards to anticipate certification costs and product registration timelines.
Market Dynamics
The United Kingdom lubricants market is undergoing structural reconfiguration as REACH compliance and domestic carbon-reduction commitments force wholesale reformulation of additive packages and base-oil selections, compressing product development cycles and elevating technical service intensity.
Growth Catalysts
- Extended vehicle lifecycles:Fleet operators in England's manufacturing belt are retaining commercial vehicles beyond traditional replacement horizons, expanding demand for high-mileage lubricant formulations and predictive maintenance services.
- REACH substance registration:The Health and Safety Executive's chemical registration framework is accelerating substitution of legacy additive chemistries, creating pull-through demand for compliant synthetic base stocks.
- West Midlands industrial clustering:Precision machinery manufacturers around Birmingham concentrate consumption of high-performance industrial greases, anchoring regional formulation expertise and technical support infrastructure.
Market Restraints
- Base-oil supply concentration:North Sea upstream operations dominate feedstock access for UK blenders, exposing margins to geopolitical disruption and North Sea production volatility.
- EU F-Gas Regulation residual influence:Persistent alignment pressure on fluorinated compound restrictions limits certain extreme-pressure additive options for specialized industrial applications.
- Bio-based formulation cost premiums:Vegetable oil-derived base stocks command 25-40% price elevation over mineral equivalents, constraining adoption in cost-sensitive fleet maintenance segments.
Strategic Opportunities
- Fluid analysis subscription models:Fleet operators in England are unbundling lubricant supply from condition monitoring, opening recurring revenue streams for diagnostic service providers.
- UKCA marking divergence:Potential regulatory separation from EU chemical standards creates first-mover advantage for domestic blenders with accelerated certification capabilities.
- Energy-efficient low-viscosity grades:Carbon-reduction commitments from the Environment Agency are elevating demand for friction-reducing 0W-20 and 5W-30 automotive formulations.
Industry Challenges
- Additive chemistry expertise scarcity:Formulation chemists with REACH-compliant additive package design experience command premium compensation, constraining mid-tier blender technical capacity.
- Waste-oil recovery infrastructure:The Environment Agency's environmental permitting mandates require capital-intensive re-refining investments that smaller distributors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Lubricants Market |
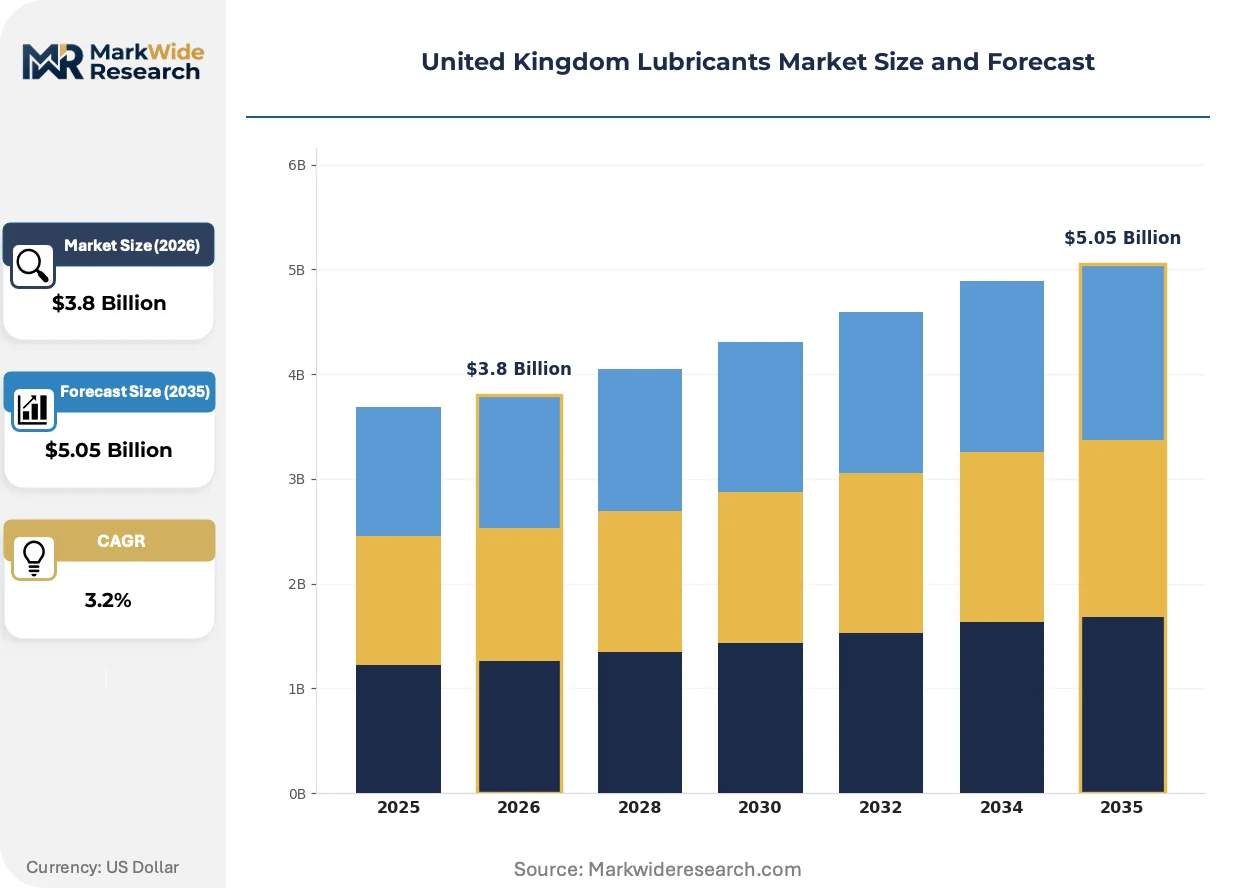
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.05 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive, Industrial Machinery, Marine, Aerospace Product Type: Mineral Oil, Synthetic, Biodegradable, Automotive Oils End User: Manufacturing, Transportation, Energy Sector, Agriculture Sales Channel: Direct Sales, Distributors, Retail, E-commerce |
| Companies Covered | Shell plc, ExxonMobil Corporation, BP p.l.c., TotalEnergies SE, Chevron Corporation, Fuchs Petrolub SE, Valvoline LLC, Petronas Lubricants International Sdn Bhd, PJSC Lukoil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Lubricants Market Evolving Landscape
Formulation science and service delivery models are converging to redefine value capture in the United Kingdom lubricants market, with technology substitution, regulatory chemistry constraints, and procurement transformation operating as interconnected forces.
Polyalkylene glycol (PAG) synthetic base stocks are achieving commercial scale in high-temperature industrial gear applications where thermal oxidative stability determines equipment life. Food processing manufacturers in Yorkshire are specifying PAG-based food-grade lubricants for bakery oven chains and packaging machinery. Mineral oil formulations with inferior thermal performance are rendering obsolete in these temperature-critical installations.
The Environment Agency's waste-oil recovery mandates under environmental permitting regulations are compelling blenders to establish closed-loop collection and re-refining capabilities. This regulatory pressure is restructuring distributor economics toward integrated service provision rather than transactional product sales. Automotive aftermarket channels in Greater Manchester are responding by consolidating around full-service fluid management contracts.
Fleet maintenance managers are compressing lubricant procurement decisions into total cost of ownership frameworks that weight fluid life, fuel economy impact, and downtime reduction above unit price. This analytical purchasing behavior is displacing traditional distributor relationships with direct technical partnerships between end-users and formulation specialists. The shift is most visible among logistics operators along the M6 corridor, where vehicle utilization rates maximize the value of extended-drain synthetic formulations.
United Kingdom Lubricants Market Segmentation
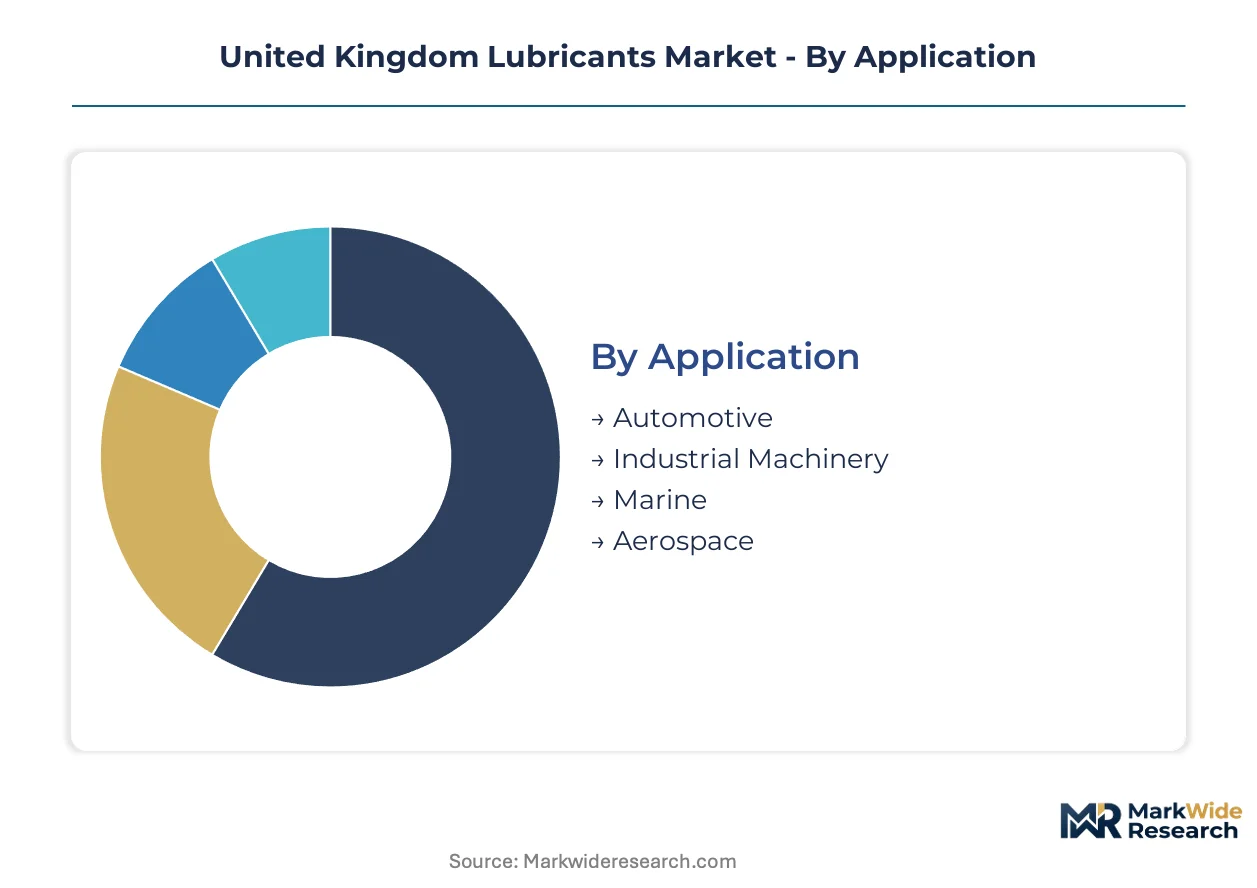
Segmentation in the United Kingdom lubricants market reveals how formulation requirements, procurement channels, and end-use intensity create distinct commercial battlegrounds. Each dimension carries unique margin structures and regulatory exposure that reshape competitive positioning.
Application:
Use-case spectrum spans friction management across mobility, manufacturing, and specialized equipment with radically different duty cycles and specification thresholds.
- Automotive:Engine oils, transmission fluids, and greases formulated for passenger vehicles and commercial fleets. Demand concentrates around Birmingham's logistics corridor where extended-drain synthetics reduce downtime for high-utilization operators.
- Industrial Machinery:Hydraulic fluids, metalworking coolants, and compressor oils for manufacturing equipment. The West Midlands precision engineering cluster drives specification toward high-performance greases with extreme-pressure additive packages.
- Marine:Stern tube oils, cylinder lubricants, and deck machinery fluids for commercial shipping. Port operations around Southampton and Liverpool anchor consumption of environmentally acceptable lubricants meeting Environment Agency discharge standards.
- Aerospace:Low-temperature hydraulic fluids and turbine oils for commercial aviation and defense applications. Heathrow's maintenance, repair, and overhaul facilities specify synthetic formulations with exceptional thermal stability.
The dominant share belongs to Automotive, while Industrial Machinery is closing the gap fastest as manufacturing reshoring elevates equipment utilization rates.
Product Type:
Cost tier stratification separates commodity mineral formulations from premium synthetics and compliance-driven bio-based alternatives.
- Mineral Oil:Refined petroleum-derived base stocks blended with conventional additive packages. Cost-sensitive fleet maintenance segments in Northern England retain this tier despite inferior thermal oxidative stability.
- Synthetic:Chemically engineered base stocks including polyalphaolefins and polyalkylene glycols achieving viscosity indices above 140. Yorkshire food processors specify PAG-based synthetics for high-temperature bakery applications.
- Biodegradable:Vegetable oil-derived base stocks with enhanced environmental degradation profiles. The Environment Agency's water discharge regulations elevate pull from marine and agricultural equipment operators.
- Automotive Oils:Passenger car motor oils and heavy-duty diesel formulations with OEM certification requirements. Low-viscosity 0W-20 and 5W-30 grades gain traction from carbon-reduction commitments.
Synthetic formulations command the dominant revenue position, with Biodegradable expanding most quickly as REACH compliance accelerates substitution of persistent chemistries.
End User:
Customer type determines volume scale, technical service intensity, and contract structure across capital-intensive industries.
- Manufacturing:Precision machinery, metal fabrication, and process equipment operators. The West Midlands industrial cluster demands predictive maintenance partnerships with integrated fluid analysis.
- Transportation:Road freight, passenger transit, and logistics fleet operators. M6 corridor hauliers compress procurement into total cost of ownership frameworks weighting fuel economy impact.
- Energy Sector:Offshore platforms, wind turbine installations, and power generation facilities. North Sea operations expose supply security to upstream production volatility.
- Agriculture:Tractor hydraulics, combine harvester engines, and irrigation pump lubrication. Seasonal demand patterns and biodegradable discharge requirements shape specification.
Manufacturing retains the dominant consumption position, though Transportation is gaining share fastest as fleet operators extend vehicle lifecycles and unbundle lubricant supply from condition monitoring.
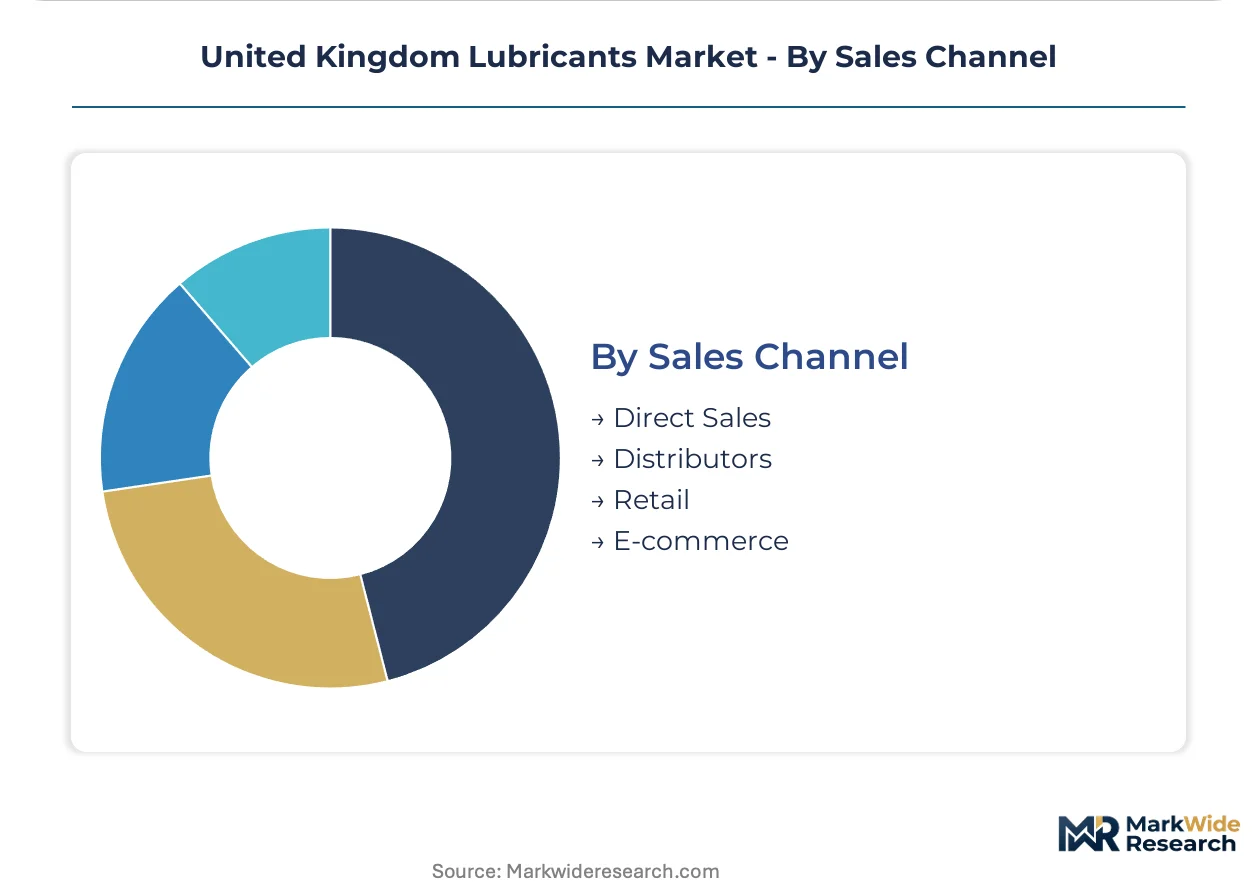
Sales Channel:
Supply concentration varies from direct technical partnerships to fragmented retail distribution with diverging margin capture.
- Direct Sales:Technical account management for large industrial accounts and national fleet operators. Direct relationships displace traditional distributors as procurement shifts toward outcome-based fluid management contracts.
- Distributors:Regional stockholding intermediaries with blending and technical service capabilities. Smaller distributors face capital constraints from Environment Agency waste-oil recovery mandates.
- Retail:Automotive aftermarket channels including motor factors and service stations. Greater Manchester consolidation responds to integrated service provision economics.
- E-commerce:Digital procurement platforms for standardized product grades and small-volume orders. This channel climbs fastest among independent workshops and agricultural operators.
Distributors hold the dominant channel position, while Direct Sales is expanding most quickly as fleet managers prioritize technical partnerships over transactional relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United Kingdom diverge sharply between England's industrial manufacturing belt and the peripheral nations, with formulation requirements and procurement sophistication varying by regional economic structure.
England
The West Midlands precision engineering cluster around Birmingham concentrates demand for high-performance industrial greases with extreme-pressure additive packages. The Health and Safety Executive's REACH compliance framework accelerates substitution of legacy chemistries in this manufacturing heartland. Yorkshire food processors specify PAG-based synthetics for high-temperature bakery applications, rendering mineral oil formulations obsolete in temperature-critical installations.
Scotland
North Sea offshore platforms and Aberdeen's energy services sector anchor consumption of specialized hydraulic fluids and compressor lubricants. The Environment Agency's environmental permitting regulations extend to Scottish waters, compelling operators toward biodegradable marine lubricants. Glasgow's manufacturing base maintains secondary demand for standard industrial grades, though at lower specification intensity than English counterparts.
Wales
Port operations around Cardiff and Swansea drive specification of environmentally acceptable lubricants meeting discharge standards for commercial shipping. The country's automotive components suppliers in the Ebbw Vale corridor source mid-tier mineral formulations for metalworking applications. Welsh industrial demand remains cost-sensitive relative to English benchmarks, constraining synthetic penetration rates.
Northern Ireland
Belfast's aerospace maintenance facilities and Londonderry's food processing plants create bifurcated demand between aviation-grade synthetics and food-grade lubricants. The region's smaller industrial scale limits dedicated technical service infrastructure, concentrating procurement through distributor intermediaries. Agricultural equipment operators in the border counties exhibit seasonal demand patterns with biodegradable discharge requirements.
London and the Southeast
Heathrow's maintenance, repair, and overhaul facilities specify synthetic formulations with exceptional thermal stability for commercial aviation. Fleet operators along the M25 logistics corridor compress procurement into total cost of ownership frameworks weighting fuel economy impact. The capital's premium service infrastructure supports the highest synthetic penetration rates and fluid analysis subscription adoption nationally.
United Kingdom Lubricants Market Competitive Landscape
Capability concentration sits with specialized industrial formulators; scale advantage sits with integrated energy majors with captive base-oil access. The United Kingdom lubricants market structures around three tiers: upstream-integrated majors securing feedstock security, mid-tier blenders with regional technical service depth, and niche specialists commanding premium positioning in food-grade and aerospace applications. Consolidation pressure concentrates among distributors facing capital constraints from waste-oil recovery mandates. Competitive moves center on backward integration into re-refining capacity and direct technical partnerships displacing traditional channel relationships.
Within the integrated-major tier, Shell plc and BP p.l.c. exemplify upstream-advantaged positioning through North Sea feedstock access. Fuchs Petrolub SE occupies a specialist position representing the precision-industrial archetype with formulation expertise in high-performance greases. These three anchors illustrate the competitive spectrum: scale-driven resource integration versus technical-specialist margin capture versus hybrid models attempting both.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil Corporation |
| BP p.l.c. |
| TotalEnergies SE |
| Chevron Corporation |
| Fuchs Petrolub SE |
| Valvoline LLC |
| Petronas Lubricants International Sdn Bhd |
| PJSC Lukoil |
| Others |
Value Network & Pricing Analysis
The North Sea upstream operations around Aberdeen concentrate base-oil feedstock capacity for UK blenders, translating upstream production volatility into downstream margin compression and pricing power asymmetry between integrated majors and independent formulators.
Pricing Analysis
Long-term offtake agreements dominate procurement between fleet operators and major blenders, insulating volume commitments from spot market swings while subscription-based fluid analysis contracts capture recurring revenue streams. Price differentiation hinges on certification tier—REACH-compliant synthetic formulations command premiums over mineral equivalents—and volume scale, with national logistics fleets extracting favorable terms through consolidated purchasing. Pricing pressure stems from bio-based formulation cost premiums of 25-40% over mineral stocks, squeezing mid-tier blender margins. Cost-sensitive fleet maintenance segments in Northern England exhibit highest price sensitivity, while aerospace and food-grade applications show least elasticity due to specification rigidity.
Supply Chain Analysis
Export-control regimes on fluorinated compound technologies limit certain extreme-pressure additive flows into UK formulation facilities, constraining specialized industrial grease production. Geographic supply concentration draws from Norway, the Netherlands, and Belgium for Group II/III base stocks, with North Sea crude anchoring domestic Group I capacity. Raw material dependencies center on polyalphaolefin feedstocks, polyalkylene glycol precursors, and REACH-compliant additive packages. Single-source vulnerability pervades the North Sea feedstock corridor, where production disruptions cascade rapidly to blending operations. Distribution runs through integrated service contracts for large fleet accounts, with regional distributors retaining fragmented automotive aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation along England's M6 logistics corridor is compressing supplier counts and shifting procurement power toward direct technical partnerships, fragmenting traditional distributor relationships and elevating buyer negotiation leverage.
For Market Incumbents: Pre-empt margin erosion by securing backward integration into waste-oil re-refining capacity before Environment Agency mandates intensify capital requirements. Anchor technical service teams within the West Midlands precision engineering cluster to defend against emerging fluid analysis specialists. Prioritize certification investment for low-viscosity 0W-20 and 5W-30 formulations aligned with carbon-reduction commitments.
For New Entrants and Emerging Players: Build out biodegradable formulation capabilities targeting marine and agricultural equipment operators facing Environment Agency discharge regulations. Yorkshire food processors represent the most penetrable white-space segment, with temperature-critical PAG-based synthetics displacing obsolete mineral formulations. Pursue direct sales partnerships with precision machinery manufacturers rather than distributor intermediaries.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized industrial formulators with REACH-compliant additive chemistry expertise over commodity mineral blenders. Five-to-ten year viability hinges on regulatory chemistry substitution capabilities and closed-loop collection infrastructure. Watch for inflection signals in UKCA marking divergence timelines, which would accelerate certification advantages for domestic players with pre-positioned compliance capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Re-refining | Captures waste-oil recovery economics under Environment Agency permitting mandates. |
| Direct Technical Partnership Models | Displaces distributor relationships as M6 corridor fleets consolidate procurement. |
| Low-viscosity Grade Certification | Aligns product portfolios with Environment Agency carbon-reduction commitments. |
| Fluid Analysis Subscription Launch | Converts transactional lubricant sales into recurring diagnostic revenue streams. |
| Biodegradable Formulation Scale-up | Addresses Environment Agency discharge standards for marine and agricultural applications. |
Research Methodology
Desk research of customs trade data, Health and Safety Executive REACH registration filings, and Environment Agency permitting records preceded structured interviews with lubricant formulation chemists, fleet procurement managers, and industrial maintenance directors. Primary fieldwork captured procurement decision frameworks and specification evolution across the West Midlands manufacturing belt and M6 logistics corridor. Secondary validation drew from base-oil trade flow databases, SEC filings of integrated energy majors, and chemical industry association reports. Bottom-up volume modeling triangulated against top-down market sizing from feedstock consumption patterns.
Assumptions held fixed include REACH compliance trajectory, North Sea production stability, and carbon-reduction commitment intensity, while variables tested encompassed UKCA-EU regulatory divergence speed and bio-based feedstock cost curves. Segmentation modeling spanned application type, product grade tier, end-use industry intensity, and sales channel structure across the analysis window. CAGRs derived from regression analysis of historical volume trends against fleet lifecycle extension rates and manufacturing equipment utilization projections. Forecast inputs incorporated additive chemistry substitution timelines and re-refining capacity buildout schedules.
Practitioners should monitor UKCA marking implementation pace and North Sea upstream investment signals for early revision indicators. Forecasts reflect documented assumptions regarding regulatory continuity and feedstock supply security. Material shifts in REACH-UKCA divergence timelines or North Sea production profiles would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
North America Automotive Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Gun Lubricant Market
Lubricants
Construction Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Friction Reducers Market
Lubricants
Philippines Lubricants Market
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
Polyurea-Based Greases Market
Lubricants
France Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Contact Lubricants Market