
 South America Commercial Vehicles Lubricants Market | 2026-2036
South America Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South America Commercial Vehicles Lubricants Market Analytics
API CK-4 and FA-4 specification upgrades is collapsing the legacy mineral-grade installed base across South American heavy-duty fleets. Chevron Corporation leverages its additive technology leadership to capture premium positioning in Brazilian engine oil channels. Petrobras anchors national supply security through its integrated refining and lubricant blending network. ExxonMobil Corporation differentiates via synthetic-grade penetration in Andean mining truck applications.
South America commercial vehicles lubricants comprise formulated petroleum-derived or synthetic base oils blended with performance additives to reduce friction, dissipate heat, and protect powertrain components under severe-duty cycles; these formulations typically operate within viscosity grades from SAE 10W-30 to SAE 15W-40 and incorporate detergent-dispersant packages to manage soot loading in diesel engines. Engine oil commands the dominant value pool given high consumption rates and specification intensity in long-haul trucking, while fully synthetic grades capture expanding share as fleet managers prioritize extended drain intervals and fuel economy gains. Bio-based lubricants occupy a nascent but structurally important position where ANP-mandated biodiesel compatibility and Amazon basin environmental sensitivity create specialized demand pockets.
Brazil's ANP regulates fuel quality and lubricant labeling standards, while PROCONVE emission tiers align lubricant formulation with after-treatment system protection requirements; Argentina's IRAM standards and Chile's SEC certification create complementary compliance layers that shape product registration and market access protocols. Fleet procurement teams must monitor regulatory convergence between MERCOSUR technical standards and EU REACH-aligned additive restrictions. Stakeholders should track bio-based feedstock certification developments and synthetic base oil import tariff dynamics as structural margin determinants.
Market Dynamics
PROCONVE emission tier progression is collapsing the legacy mineral-grade installed base across Brazilian heavy-duty fleets, forcing formulators to accelerate lower-SAPS additive packages and bio-compatible base stock qualification timelines.
Growth Catalysts
- ANP Biodiesel Mandates:Brazil's national petroleum agency mandates escalating biodiesel blend rates, creating specialized demand for bio-compatible lubricant formulations that protect fuel system components and after-treatment hardware.
- Long-Haul Fleet Consolidation:São Paulo state freight corridors concentrate high-mileage tractor-trailer operations where extended drain interval specifications generate premium synthetic-grade pull-through.
- Group III Base Oil Availability:Regional refining investments expand synthetic-grade feedstock supply, enabling formulators to meet CK-4/FA-4 specification requirements without full import dependency.
Market Restraints
- API Certification Cost Burden:Engine oil marketers face escalating testing and licensing fees for CK-4/FA-4 claims, compressing margin structures for mid-tier blenders without captive additive technology.
- Andean Import Tariff Volatility:Synthetic base oil shipments into Chile and Peru encounter unpredictable customs duty adjustments, disrupting inventory planning for mining truck lubricant programs.
- Mineral Grade Price Anchoring:Legacy 15W-40 mineral formulations retain stubborn fleet procurement preference in Argentina's cost-sensitive agricultural transport segment, delaying premium-grade conversion.
Strategic Opportunities
- Amazon Basin Environmental Sensitivity:Ecuador and Colombia's extractive industries face intensifying spill-liability exposure, creating white space for biodegradable hydraulic fluids and eco-labeled engine oils.
- Telematics-Integrated Fluid Monitoring:Fleet management platforms enable real-time oil condition sensing, opening subscription-based lubricant service models alongside traditional product sales.
- PROCONVE P-8 Alignment:Brazil's upcoming emission tier tightens particulate matter limits, positioning low-ash formulations for first-mover advantage in after-treatment-compatible product positioning.
Industry Challenges
- Additive Chemist Talent Scarcity:Formulation laboratories in São Paulo and Rio de Janeiro compete for limited specialists capable of balancing biofuel compatibility with wear protection performance.
- MERCOSUR Harmonization Delays:Divergent technical standards between Brazilian ANP protocols and Argentine IRAM certification requirements force dual-registration investments for regional product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Commercial Vehicles Lubricants Market |
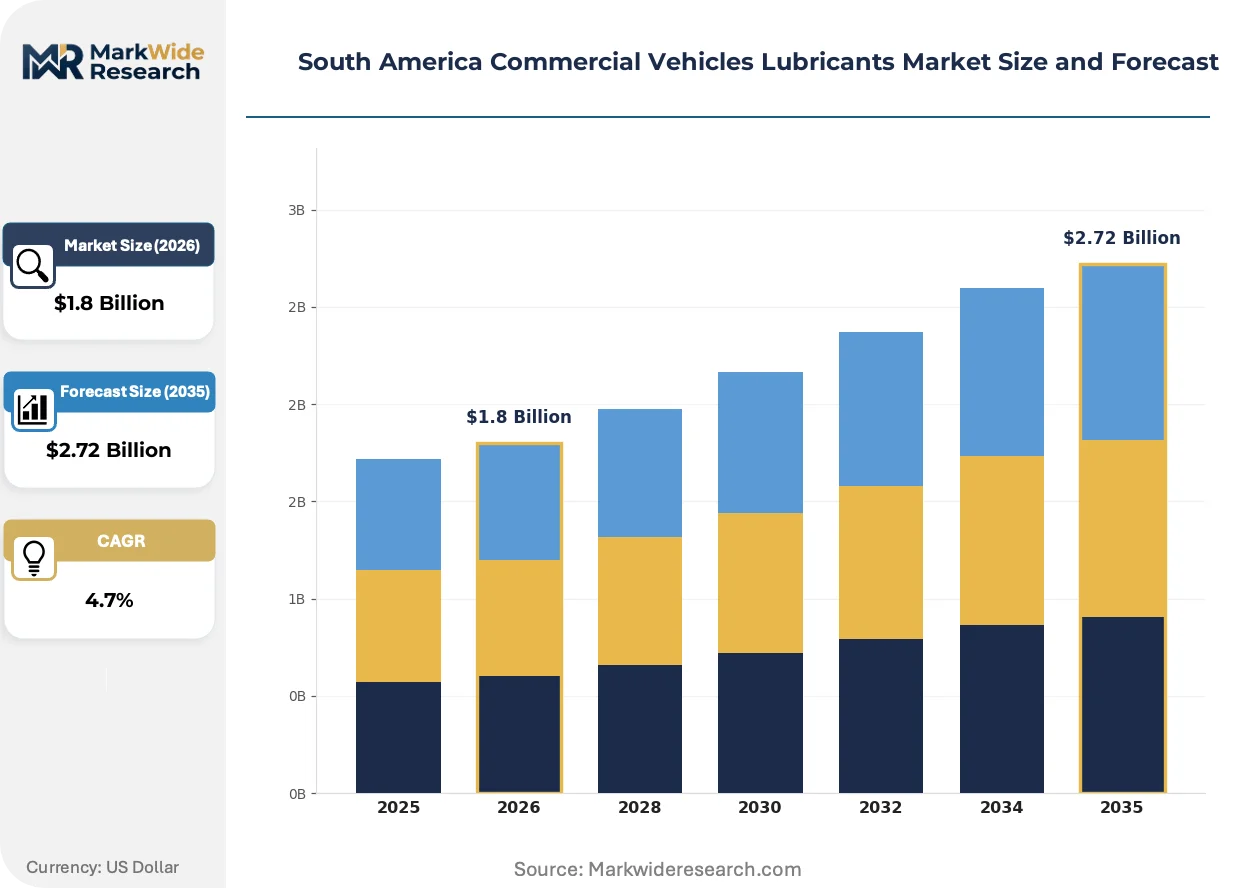
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Greases, Hydraulic Oil End Use: Trucks, Buses, Vans, Heavy-Duty Vehicles Grade: Semi-Synthetic, Fully Synthetic, Mineral, Bio-Based Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Iconic Lubrificantes, Petronas Lubricants International, Chevron Corporation, Terpel, Royal Dutch Shell Plc, ExxonMobil Corporation, Petrobras, TotalEnergies, Gulf Oil International, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Commercial Vehicles Lubricants Market Evolving Landscape
Specification intensity is accelerating across South American commercial vehicle lubricants as emission hardware protection demands collide with biofuel compatibility requirements and fleet uptime economics.
Lower-SAPS additive technology is fragmenting the traditional diesel engine oil market into distinct specification tiers. CK-4 chemistry protects exhaust after-treatment systems in newer Brazilian tractors, while FA-4 viscosity grades target fuel economy gains in Class 8 line-haul operations. Fleet maintenance managers in Minas Gerais freight corridors now specify these technologies to compress total cost-per-mile calculations.
ANP biofuel blending mandates are reshaping lubricant formulation priorities through mandatory biodiesel percentage escalations. These regulations force detergent-dispersant package redesigns to manage elevated fuel dilution and oxidation byproducts. Argentine and Chilean formulators track Brazilian regulatory precedent to anticipate parallel compliance requirements in their domestic markets.
Fluid analysis subscriptions are displacing traditional scheduled-drain maintenance models among large fleet operators. São Paulo-based logistics companies now outsource oil condition monitoring to lubricant suppliers, unbundling product supply from technical service relationships. This pattern concentrates most rapidly in mining truck applications across Chile's Atacama copper belt where unplanned downtime carries extreme cost penalties.
South America Commercial Vehicles Lubricants Market Segmentation
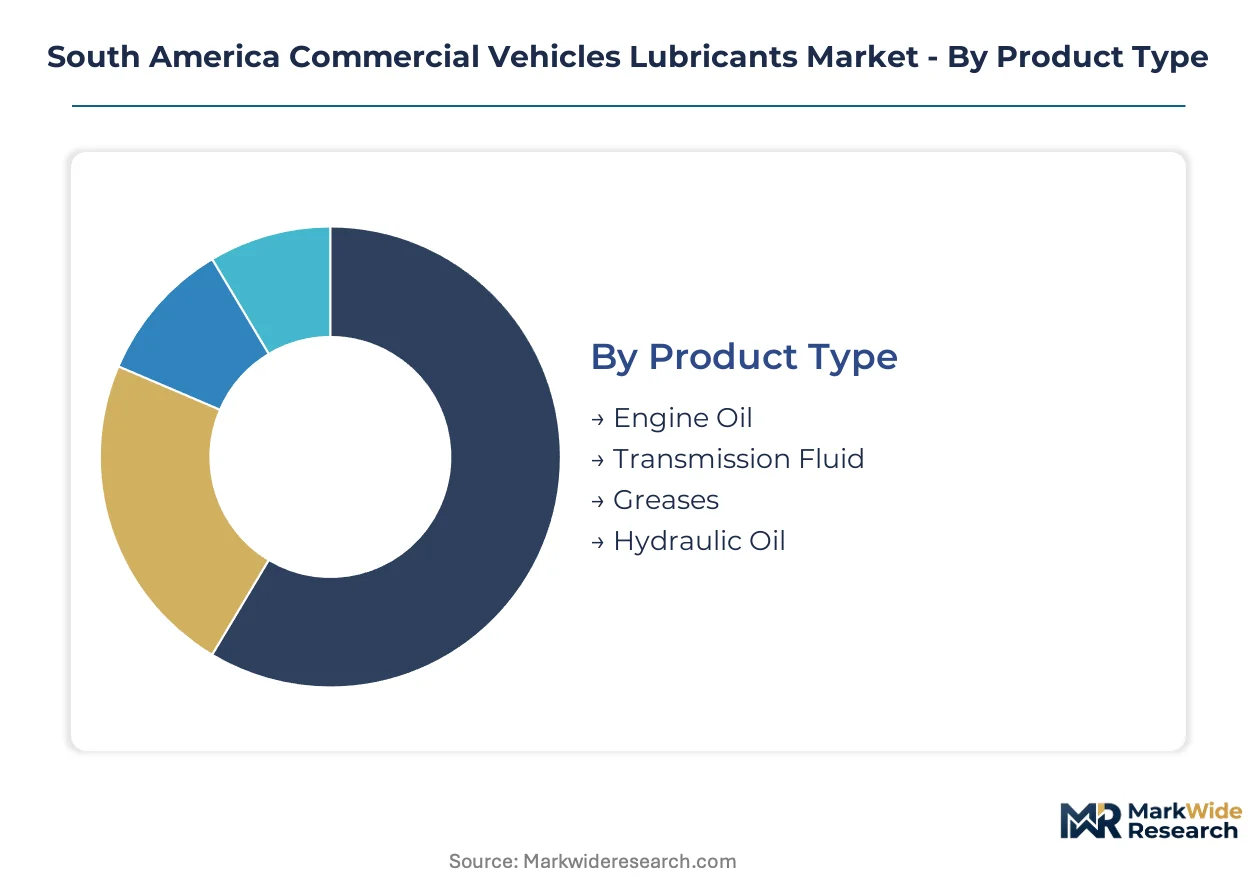
Segmentation in South American commercial vehicle lubricants reveals how specification intensity, fleet procurement patterns, and regulatory compliance reshape channel economics. Understanding these divisions exposes where premium-grade conversion accelerates and where mineral-grade legacy demand persists.
Product Type:
Product-type segmentation channels through distinct commercial pathways: engine oil dominates direct fleet contracts, while hydraulic fluids and greases concentrate in mining-sector wholesale arrangements. Transmission fluids split between OEM fill programs and aftermarket retail.
- Engine Oil:Formulated petroleum-derived or synthetic base oils blended with detergent-dispersant packages manage soot loading in diesel engines. São Paulo state long-haul fleets drive demand for CK-4/FA-4 specifications that extend drain intervals and protect after-treatment hardware. PROCONVE tier progression forces rapid specification upgrades across Brazilian heavy-duty corridors.
- Transmission Fluid:Specialized formulations for automated manual and dual-clutch transmissions in Class 8 tractors. Minas Gerais freight operators specify synthetic-grade ATFs to reduce component wear under high-torque hauling cycles. Extended fluid life claims support premium pricing against mineral alternatives.
- Greases:Lithium-complex and calcium-sulfonate thickened lubricants for chassis, wheel bearings, and fifth-wheel applications.
- Hydraulic Oil:Anti-wear formulations for dump trucks, concrete mixers, and mining equipment hydraulic systems.
By volume, engine oil leads. By growth pace, transmission fluid is expanding most quickly.
End Use:
End-use segmentation maps directly to duty-cycle severity and procurement sophistication. Heavy-duty mining trucks command technical service relationships, while van fleets transact through retail channels with minimal specification negotiation.
- Heavy-Duty Vehicles:Mining trucks, construction equipment, and agricultural machinery operating in severe-duty cycles. Chile's Atacama copper belt and Brazil's iron ore corridors concentrate demand for extended-drain synthetic formulations. Unplanned downtime costs in extractive applications justify premium fluid investments.
- Trucks:Class 6-8 tractor-trailers dominating Brazil's southeastern freight corridors. Fleet consolidation in São Paulo state accelerates specification standardization across thousand-vehicle operator portfolios. Telematics integration enables condition-based maintenance contracts.
- Buses:Urban transit and intercity coach applications with high stop-start frequency.
- Vans:Light commercial delivery vehicles in urban last-mile logistics.
Heavy-duty vehicles generate the highest revenue per liter. Trucks show the steepest expansion trajectory in absolute volume terms.
Grade:
Grade segmentation reflects a cost-tier structure where mineral formulations anchor entry-level pricing, synthetics capture fleet premium budgets, and bio-based grades occupy regulatory-mandated niches.
- Fully Synthetic:Group III and PAO-based formulations meeting CK-4/FA-4 specifications with extended drain intervals. Brazilian fleet operators in high-mileage applications specify these grades to compress total cost-per-mile calculations. Regional Group III base oil investments reduce import dependency for formulators.
- Semi-Synthetic:Blended base oil formulations bridging mineral and synthetic performance tiers. Argentina's cost-sensitive agricultural transport segment favors this grade for moderate-duty cycles where full synthetic economics fail to justify.
- Mineral:Solvent-refined base oils in legacy 15W-40 formulations retaining procurement preference in price-anchored segments.
- Bio-Based:Renewable feedstock lubricants with biodegradability certifications for Amazon basin environmental compliance.
Fully synthetic commands the highest margin pool. Bio-based is gaining share fastest amid ANP biodiesel compatibility mandates and spill-liability exposure in sensitive ecosystems.
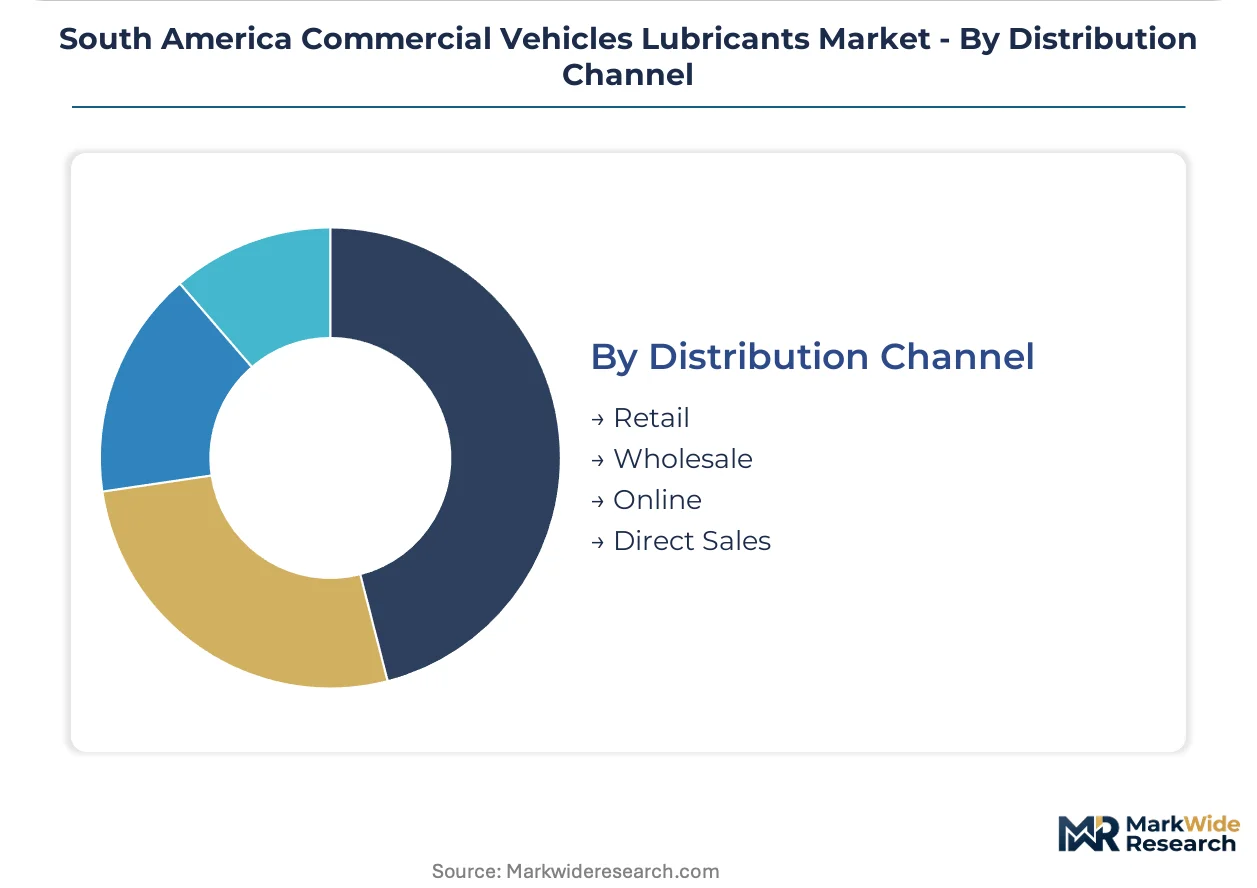
Distribution Channel:
Channel segmentation reveals a bifurcation between relationship-driven direct sales to consolidated fleets and transactional retail serving fragmented owner-operators.
- Direct Sales:Lubricant suppliers contract directly with large fleet operators and mining companies for integrated fluid management programs. São Paulo-based logistics companies outsource oil condition monitoring alongside product supply, unbundling technical service from commodity transactions. Subscription-based fluid analysis models concentrate in this channel.
- Wholesale:Distributor networks serving independent repair shops and smaller fleet maintenance facilities. Mining-sector hydraulic fluid programs in Chile and Peru flow through specialized industrial distributors with inventory positioning near extraction sites.
- Retail:Automotive parts stores and service stations targeting owner-operators and small commercial vehicle users.
- Online:Emerging digital procurement platforms for standardized grade replenishment.
Direct sales captures the highest value per transaction. Online is climbing the fastest as fleet procurement digitization accelerates specification transparency and price discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South American lubricant trade flows reveal a structural deficit in synthetic base stocks, with regional refiners importing Group III feedstocks to meet CK-4/FA-4 specification demand while exporting surplus mineral-grade formulations to Central American markets.
Brazil
ANP biodiesel mandates and PROCONVE emission tiers drive formulators toward lower-SAPS additive packages. São Paulo state's southeastern industrial belt concentrates long-haul fleet procurement, where thousand-vehicle operators specify extended-drain synthetic grades to compress cost-per-mile calculations. Minas Gerais freight corridors anchor demand for telematics-integrated fluid monitoring services.
Argentina
IRAM certification requirements create parallel compliance layers alongside Brazilian ANP protocols, forcing dual-registration investments for regional product lines. Buenos Aires province agricultural transport operators retain stubborn mineral-grade preference in cost-sensitive segments. Córdoba's grain logistics corridors delay premium-grade conversion despite neighboring market specification upgrades.
Chile
SEC certification governs product registration while unpredictable synthetic base oil import tariffs disrupt inventory planning for mining truck lubricant programs. The Atacama copper belt concentrates demand for condition-based maintenance contracts where unplanned downtime carries extreme cost penalties. Antofagasta region extractive operations justify premium fluid investments through severe-duty cycle economics.
Colombia
Extractive industries face intensifying spill-liability exposure in Amazon basin operations, creating specialized demand pockets for biodegradable hydraulic fluids. Bogotá-based formulators track Brazilian regulatory precedent to anticipate domestic biofuel compatibility requirements. Orinoco heavy crude corridors concentrate heavy-duty fleet operations with extended drain interval specifications.
Peru
Andean import tariff volatility compounds supply chain complexity for mining-sector lubricant programs. Lima-based distributors position inventory near Cerro Verde and Antamina extraction sites to serve hydraulic fluid demand. Cusco region transport operators bridge agricultural and mining logistics, fragmenting procurement sophistication across duty-cycle extremes.
South America Commercial Vehicles Lubricants Market Competitive Landscape
Listed leaders compete with private specialists across specification intensity and channel access dimensions. The market structures around three tiers: integrated national oil companies with captive refining, multinational additive technology leaders, and regional blenders serving cost-anchored segments. Strategic moves concentrate on synthetic-grade portfolio expansion and direct fleet contracting relationships that unbundle technical service from commodity transactions.
Within the integrated national champion tier, Petrobras anchors Brazilian supply security through captive refining and lubricant blending networks. Chevron Corporation and ExxonMobil Corporation exemplify multinational additive technology leaders leveraging specification complexity to capture premium positioning. These three occupy positions across the spectrum from national supply security to synthetic-grade mining applications and Brazilian engine oil channels.
| Leading Market Players |
|---|
| Iconic Lubrificantes |
| Petronas Lubricants International |
| Chevron Corporation |
| Terpel |
| Royal Dutch Shell Plc |
| ExxonMobil Corporation |
| Petrobras |
| TotalEnergies |
| Gulf Oil International |
| Others |
Value Network & Pricing Analysis
ANP biofuel blending mandates and PROCONVE emission tier progression simultaneously gate supply qualification and stratify price differentiation across Brazilian lubricant channels. Fleet procurement teams in São Paulo state's long-haul corridors face tiered cost structures where lower-SAPS additive packages command premium positioning against legacy mineral formulations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium synthetic, semi-synthetic, and mineral economy levels. Price differentiation hinges on API CK-4/FA-4 certification grade and volume-scale contracting terms. Cost compression in the mineral tier is intensifying because Argentine agricultural transport operators retain stubborn price anchoring preferences. Small owner-operators in fragmented retail channels exhibit highest price sensitivity, while thousand-vehicle fleet managers prioritize total cost-per-mile economics over unit pricing.
Supply Chain Analysis
Strategic stockpile preferences dominate mining-sector procurement in Chile's Atacama copper belt, where unplanned downtime penalties justify inventory buffers against Andean import tariff volatility. Geographic supply concentration draws from Brazil's integrated refining network, US Gulf Coast additive technology hubs, and Asian Group III base oil production. Raw material dependencies rest on polyalphaolefin feedstocks, detergent-dispersant packages, and viscosity index improvers. Single-source vulnerability around specialty additive chemists in São Paulo and Rio de Janeiro laboratories elevates supply risk. Distribution runs through direct fleet contracting relationships alongside wholesale distributor networks serving independent repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American commercial vehicle lubricants sit in early-cycle expansion as PROCONVE P-8 alignment accelerates specification upgrades and bio-compatible formulation adoption across Brazilian heavy-duty corridors.
For Market Incumbents: Compound technical service relationships into subscription-based fluid monitoring platforms that unbundle product supply from condition-based maintenance contracts. Deepen backward integration into regional Group III base oil production to reduce import dependency. Defend against mid-tier blenders by accelerating captive additive technology investments that compress CK-4/FA-4 certification timelines. For New Entrants and Emerging Players: Differentiate on biodegradable hydraulic fluid formulations targeting Amazon basin spill-liability exposure in Ecuador and Colombia extractive operations. Penetrate the telematics-integrated fluid monitoring white space where São Paulo logistics companies outsource oil condition sensing. Pursue direct sales channel access through fleet procurement digitization platforms that accelerate specification transparency. For Investors and Strategic Acquirers: PROCONVE P-8 particulate matter tightening reshapes the acquisition landscape toward low-ash formulation capabilities and biofuel-compatible additive packages. Long-term viability centers on formulators with demonstrated after-treatment system protection expertise and regional laboratory infrastructure. Target acquisition archetypes include mid-cap blenders with ANP-registered product portfolios and established mining-sector distributor relationships. Watch for bio-based feedstock certification developments as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Production | Reduces import dependency for CK-4/FA-4 specification compliance in Brazilian blending operations. |
| Telematics-Integrated Fluid Monitoring Platform Launch | Enables subscription revenue models alongside traditional product sales to São Paulo fleet operators. |
| Biodegradable Hydraulic Fluid Certification Program | Captures spill-liability-sensitive demand from Amazon basin extractive industries in Colombia and Ecuador. |
| Direct Fleet Contracting Relationship Expansion | Concentrates procurement standardization across thousand-vehicle operator portfolios in Minas Gerais corridors. |
| Low-Ash Additive Package R&D Investment | Positions first-mover advantage for PROCONVE P-8 after-treatment compatibility requirements. |
Research Methodology
A standing panel of fleet maintenance directors, lubricant formulation chemists, ANP regulatory affairs specialists, and mining-sector procurement managers provided ongoing calibration throughout the study. Primary interview insights combined with secondary validation from customs trade databases, ANP regulatory filings, PROCONVE technical bulletins, and SEC disclosures from listed additive technology leaders. Bottom-up volume modeling across product type, end-use, grade, and channel segments triangulated against top-down macroeconomic drivers.
Consistency checks validated volume and value outputs against external benchmarks including regional base oil import statistics and fleet operator maintenance expenditure surveys. The analytical framework modeled segmentation across product type, end-use duty cycle, formulation grade tier, and distribution channel structure across the analysis window. CAGRs derived from segment-level growth trajectories incorporating PROCONVE tier progression timelines and ANP biodiesel mandate escalations. Industry-specific forecast inputs captured telematics penetration rates and synthetic-grade conversion elasticities in high-mileage applications.
The analysis sits within stated boundaries; outcomes outside sustained PROCONVE enforcement, stable biofuel blending trajectories, or intact MERCOSUR trade flows would require recalibration. Forecasts reflect documented assumptions around specification adoption curves and fleet consolidation patterns. Revision becomes warranted when Andean import tariff volatility or additive chemist talent scarcity crosses thresholds that disrupt inventory planning or formulation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Automotive Engine Oils Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Bulgaria Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Germany Automotive Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Global Group IV and V Lubricants Market
Lubricants
Qatar Automotive Lubricants Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Gun Lubricant Market
Lubricants
Global Friction Modifiers Market
Lubricants
Drilling Lubricants Market