
 Canada Commercial Vehicles Lubricants Market | 2026-2036
Canada Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Commercial Vehicles Lubricants Market Outlook
Environment and Climate Change Canada's Clean Fuel Regulations is realigning procurement priorities across Canadian fleet yards, compelling lubricant suppliers to certify carbon intensity reductions across their product portfolios. Petro-Canada Lubricants leverages its domestic refining footprint to secure feedstock proximity advantages in Western Canada. ExxonMobil Corporation anchors its position through synthetic base oil technology leadership, while FUCHS competes via specialized mining and construction equipment formulations tailored to Alberta's oil sands terrain.
Canada commercial vehicles lubricants comprise formulated fluids engineered from Group I through Group IV base stocks with viscosity grades spanning SAE 15W-40 to SAE 5W-30, designed to reduce friction, dissipate heat, and suspend combustion byproducts in diesel and gasoline engines operating under severe duty cycles. Engine Oil occupies the dominant value share given high-consumption intervals in heavy-duty trucks traversing the Trans-Canada Highway corridor, while Transmission Fluid generates premium margin pools as automated manual transmissions proliferate in Class 8 vehicles. Hydraulic Oil sustains steady replacement demand from construction equipment deployed in British Columbia's infrastructure and energy projects.
Health Canada and PMRA oversee chemical hazard classifications affecting lubricant additive packages, while the Canadian Environmental Protection Act governs waste oil recovery and re-refining mandates that shape reverse logistics economics. Transport Canada's vehicle emission standards indirectly tighten lubricant performance specifications as engine hardware advances to meet pollutant thresholds. Stakeholders must monitor pending amendments to the Canadian Environmental Protection Act that could recalibrate allowable heavy metal content in anti-wear additives.
Market Dynamics
Extended oil drain intervals enabled by low-viscosity synthetic formulations are compressing per-vehicle lubricant consumption volumes across Canadian heavy-duty fleets, forcing suppliers to defend revenue through premium product mix and service bundling rather than unit growth.
Growth Catalysts
- Clean Fuel Regulations:Environment and Climate Change Canada's carbon intensity mandates push blenders toward certified lower-carbon base oils, creating procurement preference for domestically re-refined feedstocks in Ontario and Quebec.
- Automated manual transmission proliferation:Class 8 vehicle operators are upgrading to synthetic transmission fluids at shorter replacement cycles, generating premium margin pools in long-haul corridors.
- Alberta oil sands equipment density:Mining and construction fleets operating in Fort McMurray and Cold Lake sustain elevated hydraulic oil throughput from severe-duty cycle requirements.
Market Restraints
- Group II/III base oil import dependence:Eastern Canadian blenders rely on US Gulf Coast refiners for high-quality feedstock, exposing margins to pipeline capacity constraints and currency volatility.
- Waste oil re-refining infrastructure gaps:Collection network density in the Prairie provinces lags Ontario and Quebec, raising reverse logistics costs for closed-loop sourcing commitments.
- API FA-4 specification hesitation:Fleet maintenance managers in older vehicle segments resist backward-incompatible engine oils, slowing full synthetic penetration in mixed-age truck populations.
Strategic Opportunities
- British Columbia hydrogen corridor development:Provincial zero-emission vehicle mandates and hydrogen hub investments will require new lubricant formulations for fuel cell auxiliary systems and electric axle motors.
- Re-refined base oil certification premium:Extended producer responsibility frameworks under the Canadian Environmental Protection Act position certified recycled content as a bidding advantage in municipal and Crown corporation tenders.
- Telematics-integrated fluid monitoring:Real-time oil condition sensors in Volvo and Daimler trucks enable predictive drain scheduling, opening subscription-based fluid management services for multi-site fleet operators.
Industry Challenges
- Additive chemist talent scarcity:Specialized formulation expertise for cold-climate pour point depressants concentrates among retiring professionals at legacy Canadian refiners, constraining new product development pipelines.
- Cross-provincial waste oil transport permitting:Interjurisdictional hazardous material classifications complicate centralized re-refining economics, fragmenting collection radius efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Commercial Vehicles Lubricants Market |
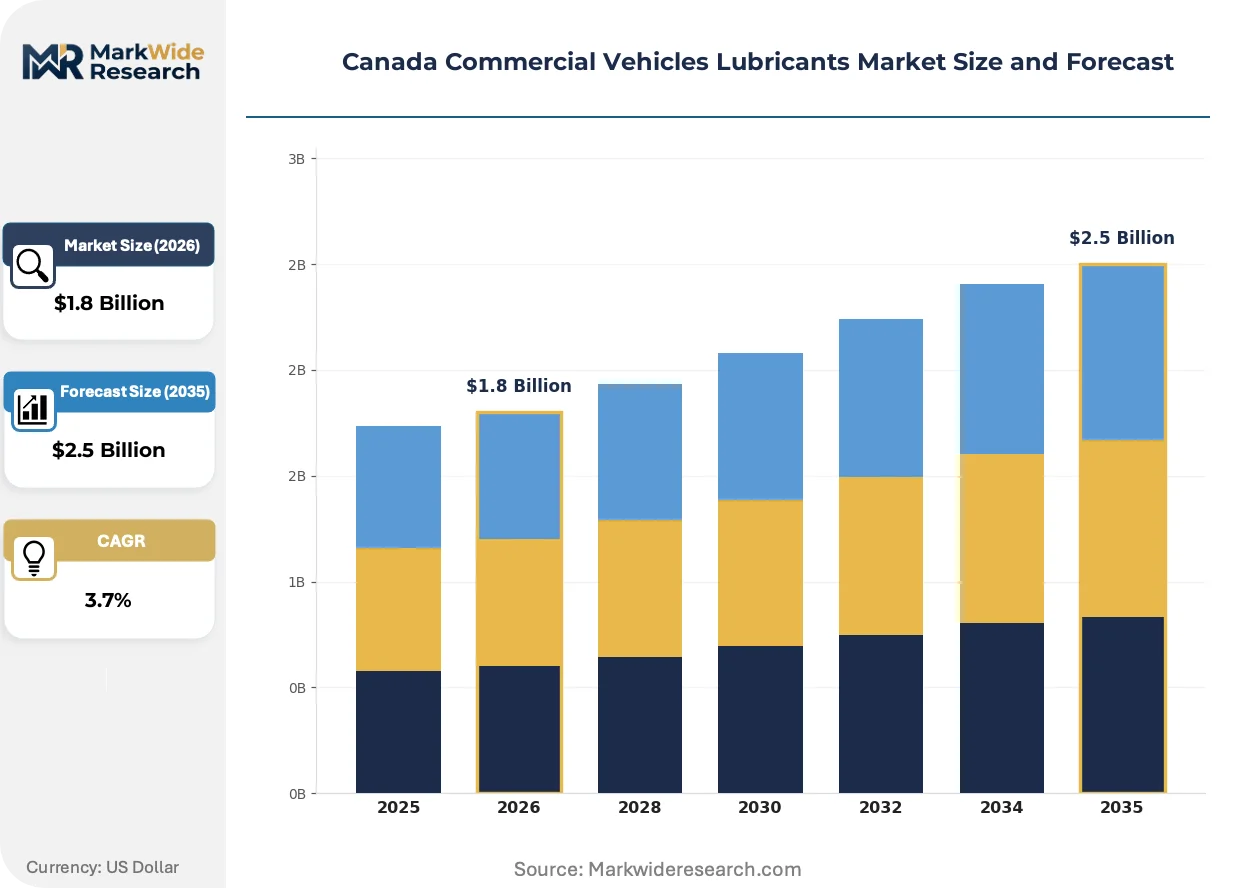
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Hydraulic Oil Application: Heavy-Duty Trucks, Buses, Construction Equipment, Agricultural Equipment Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Direct Sales End User: Fleet Operators, Service Centers, Vehicle Manufacturers, Maintenance Providers |
| Companies Covered | Boss Lubricants, BP PLC (Castrol), Chevron Corporation, ExxonMobil Corporation, FUCHS, Petro-Canada Lubricants, Phillips 66 Lubricants, Royal Dutch Shell Plc, TotalEnergies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Commercial Vehicles Lubricants Market Strategic Shifts
Formulation chemistry and fleet data infrastructure are converging to redefine how lubricant value is captured, shifting supplier relationships from transactional drum sales toward performance-guaranteed supply agreements.
Polyalkylene glycol (PAG) synthetic base stocks are modularizing conventional engine oil architectures by enabling separate optimization of thermal stability and seal compatibility layers. Long-haul operators in Saskatchewan and Manitoba are piloting PAG-based extended-life formulations at 100,000-kilometre drain intervals. This modularization is compressing the addressable market for standard mineral oils while expanding service attach rates for oil analysis and condition monitoring.
Health Canada and PMRA are tightening chemical hazard classifications for zinc dialkyldithiophosphate anti-wear additives, compelling reformulation toward ashless phosphorus chemistry. Blenders must resubmit product registrations with revised toxicological profiles, extending new product launch timelines by 12-18 months. Mining equipment operators in Alberta face immediate inventory transitions as legacy additive packages lose regulatory approval for import and sale.
Fleet procurement departments are consolidating lubricant purchasing through integrated maintenance contracts rather than standalone fluid tenders. National carriers with cross-border operations are selecting single-source suppliers capable of matching specifications across Canadian and US terminal networks. This concentration is most visible among Ontario-based third-party logistics providers serving the Golden Horseshoe warehousing cluster, where multi-site fuel and fluid bundling now determines vendor selection.
Canada Commercial Vehicles Lubricants Market Segmentation
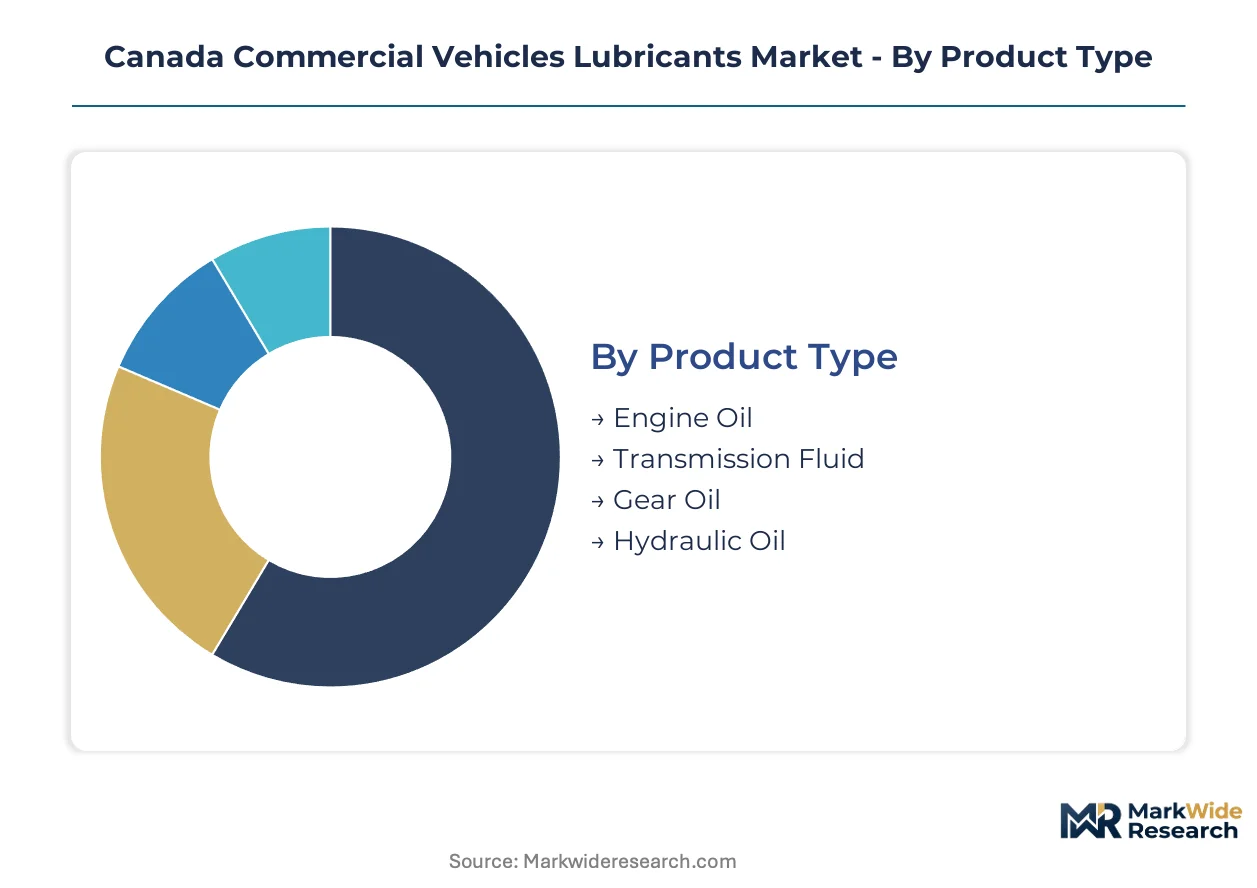
Segmentation in the Canada commercial vehicles lubricants market reveals distinct procurement patterns across fleet types and duty cycles. Understanding these divisions enables suppliers to align formulation portfolios with specific performance thresholds and replacement intervals demanded by Canadian operating conditions.
Product Type:
Fleet maintenance managers select lubricant categories based on drain interval economics and equipment warranty requirements rather than upfront price alone.
- Engine Oil:Formulated from Group II through Group IV base stocks with SAE viscosity grades from 15W-40 to 5W-30, designed to suspend soot and neutralize acidic combustion byproducts in diesel powertrains. Demand concentrates in Ontario's Golden Horseshoe corridor, where dense cross-border freight flows sustain high-throughput oil changes at 25,000-kilometre intervals for mineral formulations and 75,000 kilometres for synthetics.
- Transmission Fluid:Synthetic blends engineered for automated manual transmissions in Class 8 vehicles, delivering thermal stability across -40°C Prairie winters and summer mountain grades. Long-haul operators traversing the Trans-Canada Highway are shortening replacement cycles to 500,000 kilometres, generating premium margin pools as hardware complexity outpaces standard ATF specifications.
- Gear Oil:Extreme-pressure formulations for differential and axle assemblies in heavy-duty trucks.
- Hydraulic Oil:Anti-wear fluids sustaining construction and mining equipment deployed across Alberta's oil sands and British Columbia infrastructure projects.
Engine Oil leads on scale; Transmission Fluid leads on momentum.
Application:
Equipment utilization intensity varies dramatically across Canadian provinces, shaping lubricant consumption velocity and formulation requirements.
- Heavy-Duty Trucks:Class 7-8 vehicles operating at 160,000+ annual kilometres dominate volume consumption, with synthetic penetration accelerating among national carriers seeking extended drain intervals to minimize downtime at Ontario-Quebec distribution hubs.
- Construction Equipment:Excavators, loaders, and graders deployed in Fort McMurray oil sands and Vancouver infrastructure corridors sustain elevated hydraulic and engine oil throughput from severe dust contamination and continuous-duty cycles.
- Buses:Urban transit and motor coach fleets operating in Montreal, Toronto, and Calgary with stop-and-go duty profiles.
- Agricultural Equipment:Seasonal-use tractors and combines in Saskatchewan and Manitoba with concentrated spring and fall lubricant demand spikes.
Heavy-Duty Trucks anchor volume throughput; Construction Equipment drives premium formulation adoption.
Distribution Channel:
Procurement consolidation among multi-site fleet operators is compressing channel diversity and favoring integrated supply relationships.
- Direct Sales:National carriers and Crown corporations negotiate multi-year supply agreements with blenders, bundling lubricants with fuel cards and maintenance services to secure volume pricing and specification consistency across Alberta, Ontario, and Quebec terminals.
- Wholesalers:Regional distributors serving independent repair shops and smaller fleet operators in Prairie provinces, bridging supply gaps where direct blender relationships prove uneconomical.
- Retail Stores:Parts retailers catering to owner-operators and agricultural customers with immediate pickup needs.
- Online Platforms:E-procurement portals gaining traction among municipal fleet managers seeking transparent pricing and consolidated invoicing.
Direct Sales commands the largest contract value; Online Platforms are gaining share fastest among public sector buyers.
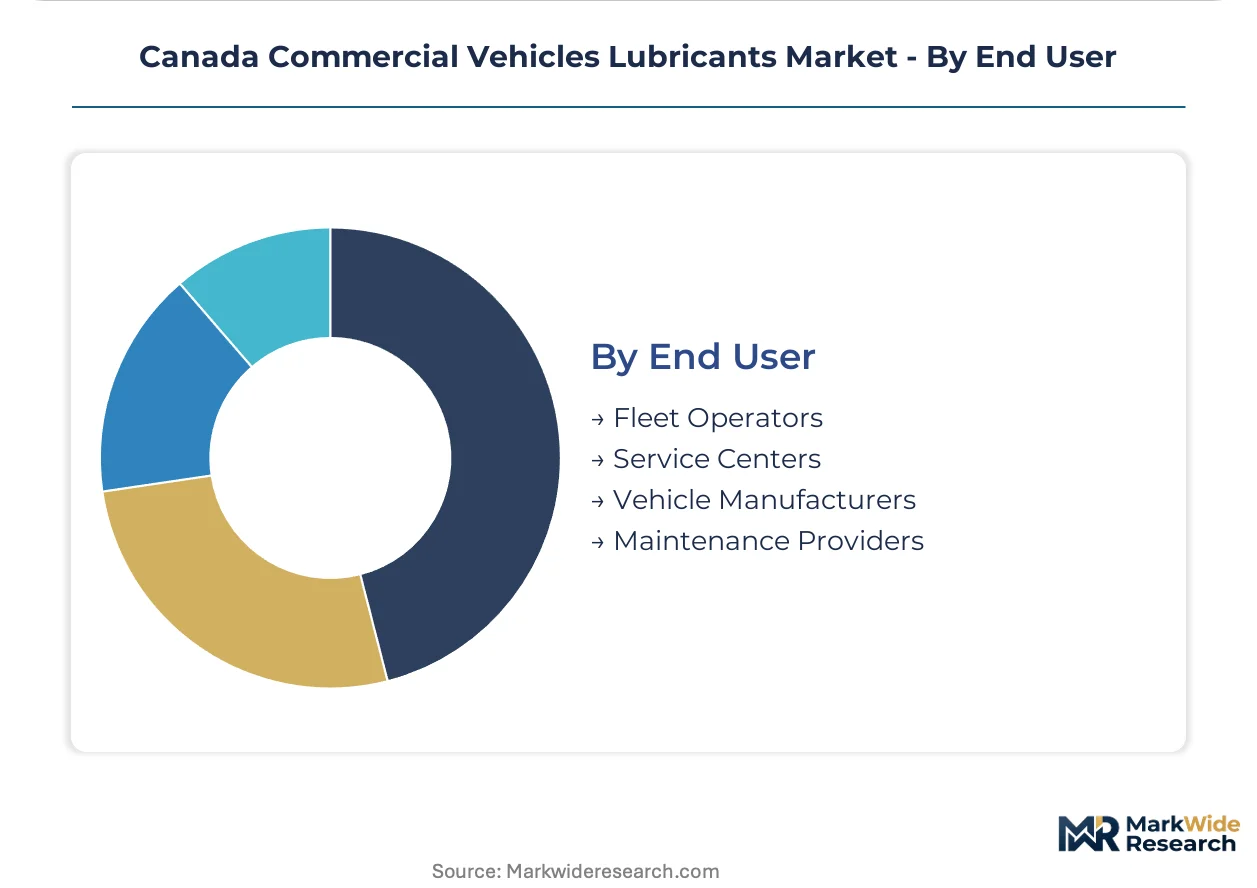
End User:
Technical sophistication and purchasing authority diverge sharply across user categories, requiring distinct sales engagement models.
- Fleet Operators:National and regional trucking companies with in-house maintenance facilities, specifying lubricants through centralized procurement functions that prioritize total cost of ownership calculations over per-litre pricing.
- Service Centers:Independent quick-lube and heavy-duty repair chains across Ontario and Quebec, selecting products based on bulk delivery reliability and co-marketing support from suppliers.
- Vehicle Manufacturers:OEM first-fill and warranty-service specifications influencing aftermarket lubricant choices through factory-approved branding programs.
- Maintenance Providers:Third-party logistics and equipment leasing companies managing fluid programs for outsourced fleet operations.
Fleet Operators represent the deepest volume concentration; Service Centers offer the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Canadian commercial vehicles lubricants industry traces its modern scale to post-war industrialization along the Great Lakes corridor, where automotive manufacturing and cross-border freight infrastructure created concentrated demand for heavy-duty engine oils and hydraulic fluids.
Ontario
Ontario's Golden Horseshoe manufacturing belt generates the highest lubricant throughput in Canada, with dense warehousing operations and Trans-Canada Highway freight flows sustaining 24-hour service bay activity. Environment and Climate Change Canada enforces Clean Fuel Regulations that push Toronto-area blenders toward lower-carbon base oil sourcing. Windsor and Hamilton anchor this demand cluster, where cross-border trucking to Detroit maintains elevated consumption of synthetic 5W-30 formulations.
Quebec
Quebec's logistics sector concentrates around Montreal's intermodal rail terminals and Port of Montreal container traffic, driving steady demand for extended-drain synthetic engine oils in regional distribution fleets. The province's extended producer responsibility frameworks under the Canadian Environmental Protection Act incentivize certified re-refined content in municipal procurement. Laval and Longueuil host the densest concentration of heavy-duty repair facilities serving Quebec's north-south highway corridors.
Alberta
Alberta's oil sands operations and Calgary-Edmonton freight corridor sustain premium-margin hydraulic oil demand from mining equipment operating in severe dust conditions. Health Canada and PMRA oversight of chemical hazard classifications affects additive package approvals for Fort McMurray equipment operators. The Calgary logistics hub serves as the primary distribution point for Western Canadian fleet lubricant supply.
British Columbia
British Columbia's mountainous terrain and Vancouver port activity generate specialized demand for transmission fluids rated for steep-grade thermal stress in Class 8 vehicles. Provincial zero-emission vehicle mandates and hydrogen corridor investments are reshaping lubricant formulation requirements for emerging fuel cell auxiliary systems. The Lower Mainland and Prince George anchor construction equipment deployment for ongoing infrastructure and energy export projects.
Canada Commercial Vehicles Lubricants Market Competitive Environment
Capital-heavy integrated refiners compete with asset-light blenders and specialized formulators across Canada's lubricant value chain. The market structure reflects moderate consolidation, with domestic refining footprints conferring feedstock proximity advantages in Western Canada while Eastern Canadian blenders rely on cross-border supply relationships. Three strategic archetypes dominate: integrated petroleum majors with captive base oil production, independent blenders with regional distribution density, and specialty chemical formulators serving severe-duty mining applications. Competitive intensity centers on portfolio diversification into synthetic and re-refined product lines, alongside geographic expansion through multi-site fleet service contracts.
Among integrated petroleum majors, ExxonMobil Corporation and Chevron Corporation anchor the premium synthetic tier through technology leadership in Group III and Group IV base stocks. Petro-Canada Lubricants occupies a distinctive position as a domestic refiner with captive feedstock access in Alberta and Ontario. FUCHS represents the specialized formulator archetype, with severe-duty expertise aligned to Alberta oil sands equipment requirements. These three companies exemplify how competitive positioning stratifies across scale, vertical integration, and application-specific technical depth.
| Leading Market Players |
|---|
| Boss Lubricants |
| BP PLC (Castrol) |
| Chevron Corporation |
| ExxonMobil Corporation |
| FUCHS |
| Petro-Canada Lubricants |
| Phillips 66 Lubricants |
| Royal Dutch Shell Plc |
| TotalEnergies |
| Others |
Value Chain & Pricing Dynamics
Low-viscosity synthetic formulation adoption across Alberta and Saskatchewan fleets is compressing per-unit revenue while concentrating procurement power among national carriers with multi-site maintenance contracts. This technological transition simultaneously elevates formulation complexity costs and rewards blenders with captive base oil production, reshaping margin distribution across the value chain.
Pricing Analysis
Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral economy levels dominates Canadian commercial vehicle lubricant transactions. Price differentiation centers on API certification tier and volume commitment scale, with FA-4 licensed synthetics commanding substantial premiums over CK-4 mineral formulations. Cost compression in the mineral tier is intensifying because extended drain intervals erode unit consumption, while fleet operators with centralized procurement show lowest price sensitivity due to total cost of ownership calculations.
Supply Chain Analysis
Regional distribution centers in Calgary, Toronto, and Montreal operate hub-and-spoke patterns feeding service bays across the Prairie provinces and Atlantic Canada. Geographic supply concentration draws from United States Gulf Coast refiners for Group II/III base oils, with domestic re-refining capacity anchored in Ontario and Quebec. Raw material dependencies include polyalphaolefin synthetic feedstocks, zinc dialkyldithiophosphate anti-wear additives, and viscosity index improvers. Single-source vulnerability runs through US-Canada pipeline capacity for high-quality base oil, while distribution feeds from blender-owned terminals and third-party wholesalers serving independent repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in Canadian commercial vehicle lubricants rests on synthetic product mix elevation and re-refined base oil certification premiums, with cost-down drivers emerging from telematics-integrated fluid monitoring reducing waste and service attach rates.
For Market Incumbents: Anchor defensive positioning through backward integration into re-refining capacity in Ontario and Quebec, securing feedstock proximity advantages as Environment and Climate Change Canada's carbon intensity mandates tighten. Deepen synthetic formulation R&D investment for cold-climate pour point performance to offset additive chemist talent scarcity constraining new product pipelines. Consolidate channel control by bundling predictive maintenance subscriptions with bulk fluid supply agreements for national carriers. For New Entrants and Emerging Players: Owner-operators and mid-sized agricultural contractors in Manitoba and Saskatchewan represent underserved buyer archetypes with concentrated seasonal demand spikes and limited direct blender access. Penetrate this segment through mobile bulk delivery services bypassing traditional wholesaler markups, leveraging telematics partnerships for predictive scheduling. Target construction equipment operators in British Columbia's infrastructure corridor with severe-duty hydraulic oil formulations differentiated for dust contamination resistance. For Investors and Strategic Acquirers: Valuations sit cheapest among independent blenders with regional distribution density but lacking synthetic technology licenses or re-refining certifications. Long-term viability over the coming decade hinges on regulatory alignment with extended producer responsibility frameworks and Clean Fuel Regulations carbon intensity thresholds. Watch for pending Canadian Environmental Protection Act amendments on heavy metal additive content as the critical inflection signal for formulation asset obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Re-refining Capacity Expansion | Captures carbon intensity certification premiums under Clean Fuel Regulations in Ontario and Quebec procurement. |
| Synthetic Base Oil Backward Integration | Secures Group III/IV feedstock proximity advantages reducing currency and pipeline capacity exposure. |
| Telematics-Integrated Fluid Management | Enables subscription revenue streams through predictive drain scheduling with Volvo and Daimler platform partnerships. |
| Specialized Mining Formulation Development | Addresses severe-duty hydraulic oil demand from Alberta oil sands equipment density in Fort McMurray. |
| Hydrogen Corridor Formulation R&D | Positions for British Columbia fuel cell auxiliary system lubricant requirements under zero-emission mandates. |
Study Parameters
Direct dialogue with fleet maintenance directors, lubricant procurement managers at national carriers, blender operations executives, and aftermarket service chain owners grounded qualitative assessment of formulation adoption patterns and contract structuring. Secondary validation drew from Environment and Climate Change Canada regulatory filings, Canadian Environmental Protection Act amendment tracking, API licensing databases, and provincial extended producer responsibility framework documentation. Bottom-up volume estimates from provincial fleet registration data and top-down value reconciliation against blender revenue disclosures enabled triangulation across analysis approaches.
Top-down macroeconomic framing anchored demand projections to freight ton-kilometer trends and construction equipment deployment statistics, while bottom-up segmentation modeled product type, application intensity, and channel mix shifts across the projection horizon. CAGRs derived from regression analysis of historical synthetic penetration rates against regulatory milestone timing, with industry-specific inputs including API specification adoption curves, re-refining capacity buildout schedules, and telematics sensor installation rates in Class 8 vehicle populations.
Underlying measurement precision varies by segment; Engine Oil and Transmission Fluid categories carry tighter precision than emerging hydrogen corridor applications due to established consumption tracking. Forecasts reflect documented assumptions regarding regulatory implementation timelines and fleet replacement cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Open Gear Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
Drilling Lubricants Market
Lubricants
Friction Reducers Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Solid/Dry Lubricants Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Iran Passenger Vehicles Lubricants Market
Lubricants
Iraq Lubricants Market
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market